

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
PW Consulting: Cephalosporin Intermediates GCLE Market Set to Grow at a 5.4% CAGR, New 2025–2032 Insight Reveals
By pmarketresearch, 2026-07-15
Cephalosporin Intermediates (GCLE) Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s new market research brief on Cephalosporin Intermediates GCLE delivers a focused, practice-oriented view designed to inform executive choices in 2026. The analysis synthesizes historical performance (2020–2025), a base-year diagnostic (2025), and a forward-looking forecast window (2026–2032). This preview highlights the strategic implications — from supply-chain fragility to competitive positioning — that will determine winners and losers as the GCLE landscape evolves. For full datasets, regional splits, and proprietary scorecards, refer to the complete report on our website.
Cephalosporin Intermediates GCLE Market
Executive snapshot — market direction and scale
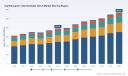
The GCLE intermediate market has demonstrated resilience through the past half-decade. From a 2020 baseline the industry expanded steadily to reach approximately USD 392.36 Million in 2025. PW Consulting’s scenario-driven forecast models a compound annual growth rate (CAGR) of 5.4% across 2026–2032, producing an estimated market outcome near USD 567.0 Million by 2032 under our central case. These headline figures encapsulate demand tied to cephalosporin active pharmaceutical ingredient (API) production, shifts in grade mix (high-purity vs. standard), and structural supply-side dynamics that are relevant for procurement, capacity investment, and M&A planning in 2026.
Cephalosporin Intermediates GCLE Market
Why this report matters for 2026 corporate strategy
- Actionable signal amid structural concentration: Market concentration metrics indicate meaningful clustering among leading suppliers. That concentration amplifies the strategic value of supplier negotiation, alliance formation, and acquisition tactics in 2026.
- Raw-material dependency risk: Key inputs underpinning GCLE manufacture are sourced from a narrow geographic set of suppliers, creating asymmetric exposure to logistics, trade policy, and quality volatility — a top priority for procurement teams.
- Regulatory arbitrage and export policy: Recent policy windows allow specific import concessions for export-oriented antibiotic production in some jurisdictions. Capturing these regulatory advantages requires precise operational timing and compliance readiness.
- Margin recovery and premiumization: Growth is not uniform across the product-grade spectrum. High-purity grades are a critical driver of margin expansion and contract differentiation.
What’s inside the full PW Consulting report (practical components)
Our report is designed as a toolset for decision-makers, not just a descriptive summary. The deliverables include:
Cephalosporin Intermediates GCLE Market
- Scenario-based demand models (2026–2032) with sensitivity levers for price, capacity outages, and shipment-cost shocks.
- Supplier and asset scorecards combining capacity, quality certifications, geographic exposure, and counterparty risk.
- Regulatory impact map showing how authorization schemes and trade measures alter landed cost across export corridors.
- An operational playbook for raw-material risk mitigation: inventory policy designs, hedging tactics, and recommended contractual clauses.
- Capital deployment guidance: cost-to-build benchmarks for incremental GCLE capacity and payback simulations under conservative and aggressive uptake scenarios.
- Deal flow shortlist and diligence checklist tailored for acquisitive strategies targeting upstream intermediates and logistics nodes.
- Plant-level contamination and quality failure risk matrices with remediation timelines — practical for QA/QC and manufacturing heads.
Each component is supported by our proprietary database and verified market-sourcing interviews; however, detailed subsegment numbers and regional shares are intentionally gated to ensure this preview preserves the full report’s strategic value.
Competitive landscape — who moves markets and why
The GCLE supplier ecosystem reflects a mix of established multinational chemistry houses, specialized intermediate manufacturers, and regional listed players. From a strategic standpoint, three seller archetypes matter:
- IP-backed, scale incumbents: Firms that originated or own key β‑lactam intermediate processes and have integrated manufacturing footprints. They bring predictable quality, backward integration potential, and leverage in premium segments.
- Cost-advantaged regional manufacturers: Producers focused on scale, low-cost feedstocks, and a volume play for standard grades. Their strengths show up in price-sensitive contracts but expose purchasers to quality and concentration risks during supply shocks.
- Emerging contract-focused suppliers: Smaller producers and toll manufacturers that provide flexibility for API houses requiring rapid capacity adjustments or bespoke purity specifications.
Notable market participants profiled in the report include major Japanese specialty-chem players with dedicated β‑lactam lines; a cohort of listed Chinese manufacturers with significant GCLE activity; and focused Indian producers who are active partners in the cefixime and broader cephalosporin export value chain. Our competitive assessment evaluates each on capacity elasticity, geographic diversification, relationship capital with API customers, and exposure to raw-material sourcing constraints.
Supply-chain dynamics and critical risk vectors
Three structural dynamics dominate the GCLE supply picture and should shape 2026 priority decisions:
- Single-sourced raw material exposure: Penicillin‑G is the foundational feedstock for GCLE synthesis and, in practice, remains concentrated in a limited number of suppliers. That sourcing geometry limits rapid re-routing options during capacity disruptions and elevates inventory strategy to a strategic discipline rather than an operational afterthought.
- Export-oriented regulatory windows: Some jurisdictions have implemented advanced authorization measures that temporarily relax minimum import price restrictions for specific export uses. These measures can materially alter landed-cost economics — but exploiting them demands tight coordination between customs, production scheduling, and sales planning.
- Logistics inflation and bottlenecks: High international freight costs and container shortages periodically amplify landed cost and shrink the merit of distant-sourcing strategies. Firms that control or co-invest in logistics solutions secure a durable commercial edge.
Compounding these are technical challenges in several historic synthesis routes — uneven yields, impurity profiles that complicate downstream API synthesis, and quality variance across suppliers. These technical factors directly influence grade mix economics, regulatory approval timelines for APIs, and ultimately patient access chains.
Strategic imperatives for executives in 2026
Based on our assessment, PW Consulting recommends a prioritized set of moves for mid- to large-sized organizations operating in the GCLE value chain:
- Lock in multi-year, conditional supply contracts: Prioritize contracts that combine volume certainty with quality KPIs and clause-based price adjustments tied to documented input-cost indices.
- Invest selectively in high-purity capability: Build or acquire capacity that can deliver above-99% grades. Premiumization in this tier delivers asymmetric margin uplift and customer stickiness.
- De-risk penicillin-G dependence: Explore joint ventures upstream, targeted equity stakes in feedstock producers, or long-term offtake agreements with financial conditioning to secure throughput.
- Operationalize regulatory arbitrage: Align commercial calendars with advanced authorization windows and ensure compliance processes are audit-ready to access import concessions.
- Embed logistics resilience: Negotiate priority container capacity, invest in bonded warehousing closer to primary export ports, and model landed-cost shocks monthly.
- Prioritize bolt-on M&A where concentration creates rent opportunities: Small-to-medium acquisitions can yield integrated margins faster than greenfield builds in constrained supply scenarios.
- Make QA/QC investments non-negotiable: Failure to pass key impurity specification gates imposes multi-month revenue losses; remediation is costly and reputationally harmful.
How PW Consulting’s report supports execution
Our full deliverable translates the high-level imperatives above into executable workstreams: negotiation playbooks with contract text templates, an asset capex decision tree, an M&A due-diligence pack, and an interactive demand-supply model where clients can stress-test scenarios (logistics shocks, feedstock failure, price moves). Importantly, we provide a supplier risk heat map and a prioritized action list that a procurement or corporate development team can operationalize within 90–180 days.
To respect the “trailer” principle, this preview intentionally omits granular regional and application splits, as well as detailed supplier scorecard metrics. The complete report contains those specifics, including validated plant maps, contract examples, and a ranked list of acquisition targets with indicative valuation bands.
Next steps for leaders
If your 2026 strategy hinges on cephalosporin value capture — whether through securing cost-of-goods, enhancing product quality, or executing bolt-on capacity plays — this PW Consulting report provides the scenario-tested playbook you need. Access the full research package for detailed segmentation, supplier-level analytics, and the interactive models that translate market signals into boardroom-ready decisions.
For detailed analysis of this topic, please visit the official page: Cephalosporin Intermediates GCLE Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Used Cooking Oil for Sustainable Aviation Fuel Market to Skyrocket from USD 2,865.4 Million in 2025 to USD 10,448.7 Million by 2032 at a 20.31% CAGR
By pmarketresearch, 2026-07-15
Used Cooking Oil for Sustainable Aviation Fuel: PW Consulting Strategic Briefing for 2026 Decision-Makers
Executive snapshot
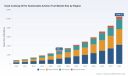
The global market for used cooking oil (UCO) as a feedstock for sustainable aviation fuel (SAF) is shifting from opportunistic aggregation to strategic industrialisation. PW Consulting’s latest market study shows the UCO-for-SAF market growing from roughly USD 2.87 billion in 2025 to an expected USD 3.49 billion in 2026, and continuing on to an estimated USD 10.45 billion by 2032 — an implied compound annual growth rate of 20.31% for the forecast horizon. For executives making 2026 capital, procurement and partnership decisions, the window to secure resilient feedstock chains and value-capture routes is narrow but actionable. This briefing outlines the report’s strategic value, the drivers reshaping the market, competitive dynamics to watch, and the practical tools included in our full deliverable that boardrooms will need as SAF policy and commercial realities converge.
Used Cooking Oil for Sustainable Aviation Fuel Market
Why 2026 is a strategic inflection point
-
Policy front-loading: Aviation-specific mandates and national SAF programmes that became effective in 2025 are now binding commercial decisions in 2026. Early compliance pathways such as HEFA using UCO are the dominant near‑term route for many markets; evolving quota timetables materially change demand profiles for certified waste feedstocks.
Used Cooking Oil for Sustainable Aviation Fuel Market -
Incentives and localisation: Regional incentive structures — notably production tax credits in North America with feedstock eligibility conditions — create asymmetries in feedstock economics and sourcing priorities. These rules are decisive when choosing between local aggregation, imports and co-processing strategies.
Used Cooking Oil for Sustainable Aviation Fuel Market -
Supply squeeze and price volatility: Increasing demand for both SAF and biodiesel has elevated UCO market tightness. Market participants are already experiencing significant price swings and episodic supply tightness, forcing procurement teams to decide between short-term spot purchases and longer-term offtake or vertical integration.
Market dynamics that will shape corporate plays in 2026
Our analysis highlights four interacting dynamics that should guide every 2026 strategic plan:
-
Demand certainty from regulatory mandates: Regional SAF blending mandates have moved the sector from speculative demand to structural offtake. Early-compliant feedstocks (notably UCO for HEFA pathways) are the default supply pool in many jurisdictions while alternative pathways scale.
-
Policy-driven regional arbitrage: Incentives that tie credits or subsidies to domestically sourced feedstock create trade flows that can rapidly realign procurement maps. Corporates must model both tariff and subsidy regimes simultaneously when sizing assets or negotiating supply.
-
Aggregation economics: Collecting UCO at scale requires dense logistics networks, contamination management and traceability systems. Scale and trusted collection partners materially lower delivered feedstock cost and quality risk.
-
Price and feedstock transparency: Volatility in bulk UCO prices has become a tactical variable for operations and contracting teams. Hedging tools, indexed contracts and blended feedstock strategies reduce short-term margin erosion but require robust data inputs.
Competitive landscape: positioning and strategic moves
The UCO-to-SAF ecosystem is already populated by a mixture of global refiners, specialised collectors, vertically integrated biofuel producers and national oil companies. Market concentration indicators in our study show a moderately consolidated structure: the top three firms account for around 38.4% of market supply by volume, while the top five approach approximately 52.2% — leaving meaningful room for strategic partnerships and consolidation targeted at the mid‑market.
Key strategic archetypes and representative players include:
-
Global integrated renewables leaders (scale + conversion capability): Companies with refinery footprints, proprietary HEFA capacity and aggregation networks are pursuing a full-value-chain play. Their advantage is end-to-end control of quality, certification and logistics, which shortens time-to-market for SAF sales and secures higher margin capture.
-
Collectors and logistics specialists: Firms focused on UCO aggregation, preprocessing and certification are increasingly critical partners for refiners and airlines. Their strategic options include exclusive long-term supply contracts, regional consolidation and investments in preprocessing to improve feedstock yields.
-
National oil companies and integrated refiners: State-backed and major refiners are deploying co-processing and dedicated HEFA units to secure domestic SAF supply. Their balance-sheet strength and fuel distribution networks accelerate market placement but require feedstock assurances that collectors must provide.
-
Emerging tech and regional converters: Smaller players and technology licensors are moving to prove scaleable, cost-competitive routes for converting UCO and other wastes. Their strategic value lies in niche capabilities and potential licence or JV upside with larger offtakers.
Recent market actions we highlight as case studies: long-term supply arrangements that lock volumes; first commercial shipments by refiners transitioning to SAF delivery; and plant ramp-ups returning capacity to market. These moves exemplify the strategic choices facing buyers and investors: secure contracted volumes at premium, invest in aggregation capability, or pursue co-processing to diversify feedstock options.
Strategic implications and recommended 2026 actions
-
Prioritise feedstock security over lowest-price procurement: Given mandate-driven demand and episodic price spikes, procurement strategies that prioritise multi-year, indexed offtakes and exclusive collection partnerships reduce supply risk and support financing of conversion assets.
-
Design contracts for policy and market volatility: Include clauses for subsidy reallocation, tariff shifts and feedstock eligibility changes. Where relevant, reserve capacity for domestic feedstock to retain incentive eligibility.
-
Invest in traceability and pre-processing: Quality variability is a persistent source of conversion inefficiency. Investment in preprocessing hubs, sampling protocols and digital traceability improves yield predictability and simplifies certification compliance.
-
Evaluate consolidation and partnership targets actively: The mid-market remains fragmented; acquisitive players can rapidly scale aggregation capabilities by targeting regional collectors and logistics specialists with strong local relationships.
-
Scenario-test conversion routes: Compare HEFA versus co-processing economics under differing feedstock availability, credit regimes and carbon prices. Align capital deployment with the route that best matches offtake structure and policy risk tolerance.
What PW Consulting’s report delivers to support 2026 decisions
Our full PW Consulting report is built as a practical decision-support suite for executives and investment committees. Deliverables include:
-
Proprietary market sizing and forecast model with downloadable worksheets — enabling custom scenario runs for prices, mandates and feedstock mixes across the 2026–2032 horizon.
-
Supply-chain maps and collection-density analytics — visualised catchment areas for aggregation hubs, estimated collection costs under differing contamination profiles, and logistics optimisation levers.
-
Contracting and procurement playbook — clause libraries for offtake, quality warranties, force majeure and indexation mechanisms adapted for UCO markets and incentive regimes.
-
Investment and M&A playbook — valuation templates, due-diligence checklists for feedstock assets, and integration roadmaps for collectors and converters.
-
Policy and incentive modelling toolkit — sensitivity analyses showing how mandate trajectories and tax-credit rules alter project IRRs and required offtake terms.
-
Competitive intelligence dossiers — strategic profiles of major collectors, refiners and converters, recent deal activity and a CR3/CR5 concentration dashboard to support strategic positioning.
-
Primary-data appendices: a curated dataset of supply agreements, recent commercial shipments and a vetted list of collection specialists and technology providers — maintained behind the report gateway.
To preserve the strategic value of the dataset and to respect commercial confidentiality in competitive segments, detailed regional and application-level splits and certain contract-level metrics are provided exclusively in the full report and interactive workbooks.
Closing guidance for boardrooms and investors
For corporate strategists, the next 12–18 months are a race for credible, contractually-secured feedstock and for conversion capacity alignment with offtake channels. For investors, the uneven regional incentive landscape and still-fragmented aggregation market create differentiated opportunities for roll-up strategies, strategic partnerships with refiners, and early-stage technology bets. PW Consulting’s analysis shows that participants who align procurement, policy hedging and vertically integrated economics early will be best placed to capture disproportionate value as SAF volumes transition from niche compliance to a structural fuel market.
How to access the full intelligence
This briefing is a strategic preview. Our comprehensive report contains the full datasets, model templates and supplier-level dossiers referenced above. For subscription access, bespoke briefings tailored to a company’s asset or procurement footprint, or to schedule a workshop on how to operationalise these insights in 2026, please visit PW Consulting’s report page or contact our advisory team.
For detailed analysis of this topic, please visit the official page: Used Cooking Oil for Sustainable Aviation Fuel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Single Mode Fiber Bundle Market to Expand at a 7.8% CAGR, Powering Growth in Data Centers and Medical Imaging
By pmarketresearch, 2026-07-15
Single Mode Fiber Bundle Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
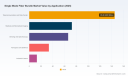
As global networks accelerate capacity upgrades and optical architectures diversify, single mode fiber (SMF) bundles have moved from niche technical components to strategic enablers of carrier, hyperscale, industrial and specialty photonics deployments. PW Consulting’s latest market study, anchored on a 2025 base year and a 2026–2032 forecast window, quantifies a resilient expansion in the SMF bundle market — driven by renewed capital intensity in data centers, broadband rollouts, and an expanding set of non-telecom applications. Our top-line projection: the global market reached USD 330.1 Million in 2025 and is set to grow at a 7.8% compound annual growth rate (CAGR) over the forecast horizon, approaching the mid-hundreds of millions by 2032.
Single Mode Fiber Bundle Market
Why this report matters for 2026 strategy
-
Time-sensitive capital allocation. For network operators and optical component suppliers, 2026 is a pivotal year to rebase capex assumptions. The market’s steady CAGR and near-term uptick imply that procurement strategies and capacity investments made this year will materially affect unit economics and service timelines through 2032.
Single Mode Fiber Bundle Market -
Supplier selection and negotiating leverage. With a moderately concentrated supplier base (the top three firms account for ~42.5% of market revenue and the top five roughly ~58.8%), purchasers can optimize sourcing through portfolio rationalization, long-form agreements, and contingency sourcing — especially where tariffs and raw-material volatility have increased cost exposure.
Single Mode Fiber Bundle Market -
Cross-sector growth windows. Beyond telecom and data centers, applications in sensing, medical optics, high-power laser delivery and aerospace create differentiated premium opportunities for firms that can adapt bundle form-factors and qualification processes rapidly.
Market trajectory: the headline numbers
Our historical series documents consistent expansion from 2020 through 2025, with the market rising from the low hundreds of millions to USD 330.1 Million in 2025. Based on demand drivers and supply-side dynamics modeled in the report, the market is projected to exceed USD 360 Million in 2026 and continue expanding across the 2026–2032 forecast period at a 7.8% CAGR, reaching an elevated scale by 2032. These aggregated figures reflect both traditional telecom demand and the acceleration of specialty applications that are beginning to represent a growing share of vendor roadmaps.
Dynamics shaping 2026 decisions
-
Regulatory and policy shifts. Recent policy moves in major markets are re-shaping transition risk and deployment windows. For example, regulatory changes affecting technology transition rules and broadband classification have implications for legacy copper-to-fiber migration timelines and service continuity obligations. Decision-makers need to model multiple regulatory scenarios when planning network upgrades to avoid stranded assets and to ensure emergency-service continuity during transitions.
-
Trade and tariff risk. Import restrictions and tariffs enacted in the prior 18 months have materially altered landed costs for certain cross-border fiber products. Buyers and manufacturers must revisit trade strategies — localized manufacturing, nearshoring and tariff engineering — to protect margins and maintain predictable lead times.
-
Raw-material and supply-chain pressure. Commodity and component price movements have raised production costs for optical fiber and related assemblies. In early 2026, industry pricing pressures re-emerged, underscoring the importance of active procurement hedging, dual-sourcing strategies and inventory optimization for manufacturers and system integrators.
-
Technology convergence and product innovation. Advances such as multi-core fiber demonstrations and hybrid bundle architectures are beginning to surface in trade shows and product roadmaps. These innovations create both a threat (product obsolescence for incumbents slow to adapt) and an opportunity (premium ASPs for differentiated, performance-assured bundles).
Competitive landscape: what winners are doing
The market exhibits a clear mix of global incumbents and specialized niche players. Established fiber and cable houses continue to dominate systems-oriented and high-volume telecom/business deployments, while highly specialized vendors service medical, aerospace, laser and instrumentation segments where qualification cycles are longer but margins can be premium.
-
Large-volume incumbents — firms with deep optical manufacturing footprints and broad product portfolios are optimizing scale through bend-insensitive designs, high-density bundle constructions and integrated cable systems suitable for backbone and FTTH infrastructures.
-
Regional and specialty players — niche suppliers are capitalizing on application-specific requirements (e.g., high-power laser transmission, fused silica bundles for medical use, polarization-maintaining configurations for instrumentation) by offering configurable assemblies and rapid prototyping capabilities.
Representative firms featured in our competitive analysis include long-standing global leaders in glass and cable manufacturing, prominent system suppliers with enterprise and telco-focused offerings, and agile specialists addressing instrumentation and industrial laser markets. The report profiles each firm’s strategic positioning, product portfolio highlights, commercial strengths, and likely moves over the next 18–36 months — including potential areas of M&A interest and capacity reallocation. Additionally, we map partner ecosystems, critical supplier relationships and the commercial levers companies are using to protect margin under commodity pressure.
What the PW Consulting report provides — practical, decision-ready content
This study is designed as an operational manual for executives, strategy teams and procurement leaders. It blends rigorous quantitative modeling with practical tools you can apply in 2026 planning cycles:
-
Market sizing and demand scenarios — top-down and bottom-up models with alternative adoption curves to stress-test investment decisions.
-
Supply-chain and cost-to-serve mapping — supplier archetypes, raw-material exposure matrices, and end-to-end lead-time sensitivity analysis to guide contingency decisions and inventory policy.
-
Commercial playbooks — tender frameworks, negotiation levers, and contract structures tailored for high-volume telecom buys versus low-volume specialty assemblies.
-
Go-to-market frameworks — segmentation strategies for entering adjacent specialty markets (medical, sensing, aerospace) where certification and qualification are the primary barriers.
-
M&A and partnership scorecards — criteria for target selection, valuation sensitivities, and integration checkpoints relevant to capability-driven consolidation.
-
Regulatory risk matrix — scenario-based assessments of policy changes (including technology transition rules and trade measures) and recommended mitigations for service providers and vendors.
-
Implementation-ready dashboards — KPI sets and monitoring templates designed to track market share, margin pressure, and capacity utilization quarterly.
Actionable recommendations for 2026
-
Rebalance procurement timelines. Lock in strategic suppliers for base volumes while keeping a portion of demand flexibly sourced to exploit spot-market pricing or to pivot to localized production if tariffs persist.
-
Prioritize capability investments. For manufacturers, invest selectively in modular assembly and qualification capabilities that reduce time-to-market for specialty bundles, enabling premium pricing in non-commodity segments.
-
Build regulatory playbooks. Operators should maintain scenario-based plans for legacy service grandfathering and 911/critical-service continuity to reduce transition risk when moving services from copper to fiber.
-
Evaluate M&A or JV paths. Given moderate market concentration, strategic acquisitions that add unique form-factors, connectorization expertise, or regional manufacturing footprint can accelerate market entry and margin accretion.
Signal watch: near-term events to monitor
-
Product demonstrations and multi-core fiber (MCF) integrations showcased at major industry events signal the pace at which alternate architectures could move from lab to deployment. We observed notable MCF and hybrid solutions previewed in early 2026, which merit attention from both buyers and incumbents.
-
Policy and trade updates — sudden changes in tariff postures or domestic content incentives can create immediate shifts in procurement routing and capital allocation.
-
Raw-material cost movements — continued upward pressure will compress margins absent corresponding price pass-through mechanisms; monitoring suppliers’ cost disclosures and inventory positions is now essential.
How to use this analysis
This briefing provides a strategic perspective and operational starting points. For teams preparing 2026 budgets, negotiating supplier agreements, evaluating M&A targets, or designing go-to-market plays in adjacent specialty segments, the full PW Consulting Single Mode Fiber Bundle Market report delivers the necessary quantitative detail, primary-source interview excerpts, and model sensitivities to convert insight into action.
Next steps — where to find the full intelligence
We have intentionally highlighted the analytical framework, headline market dynamics, and the decision-useful tools contained in the study while reserving granular segmentation tables, regional and application breakdowns, and proprietary company-by-company revenue estimates for the full report. Access to the complete dataset and downloadable models is available through our report distribution channels. For enterprise licensing, bespoke briefings, or to request an extract tailored to your procurement, product or M&A agenda, contact your PW Consulting representative or visit our report landing page.
For detailed analysis of this topic, please visit the official page: Single Mode Fiber Bundle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Negative Thermal Expansion Filler Market to Reach USD 473.43 Million by 2032, Driven by an 8.79% CAGR
By pmarketresearch, 2026-07-13
Negative Thermal Expansion (NTE) Filler Market: Strategic Priorities for 2026 — A PW Consulting Advisory
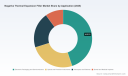
As companies plan capital allocation and product roadmaps for 2026, Negative Thermal Expansion (NTE) fillers have moved from niche materials into a strategic lever for managing reliability, miniaturization and athermalization across high-value industries. Our latest market study — anchored on a 2025 base year and a detailed 2026–2032 forecast horizon — projects continued, above-market growth for the NTE filler sector, with the global market expanding at a compound annual growth rate of 8.79%. The market has grown materially over the last half-decade, and our scenarios indicate a robust climb from the 2025 baseline toward substantially higher volumes and revenues by the end of the forecast period.
Negative Thermal Expansion Filler Market
Why 2026 Is a Pivotal Year for Decision-Makers
Several converging forces make 2026 a turning point for firms that manufacture, source or specify NTE fillers:
Negative Thermal Expansion Filler Market
- Engineering constraints in advanced electronics and optics are tightening as device geometries shrink and multi-material assemblies proliferate; thermal mismatch is now a first-order design constraint rather than an afterthought.
- Supply-side volatility in critical feedstocks (notably tungsten and zirconium derivatives) has increased input-cost and continuity risk, elevating procurement and inventory strategy to board-level priorities.
- Regulatory and certification pathways — particularly in aerospace and defense — are creating premium product segments where validated NTE solutions command disproportionate value.
- Manufacturing innovations such as nano-structured powders and additive-compatible formulations are opening new applications while changing unit economics and integration complexity.
For executives, the practical implication is clear: 2026 is the year to transition from opportunistic engagement with NTE technologies to integrated strategic programs that span R&D, supply chain and commercial go-to-market.
Negative Thermal Expansion Filler Market
Data-driven market posture
Our analysis shows the industry’s macro trajectory is healthy: between 2020 and 2025 the market expanded markedly, and the forecast through 2032 reflects sustained mid-to-high single-digit CAGR growth. This macro momentum masks important heterogeneity — certain material families and end-use pairings are emerging as premium pockets while others remain price- and commodity-driven. PW Consulting’s report quantifies these dynamics at the product and application level and models scenarios that translate macro growth into actionable demand forecasts for product teams and procurement functions.
Competitive Landscape: Who Matters and Why
Understanding incumbent capabilities and technology roadmaps is essential when crafting partnerships, licensing deals or M&A approaches. The NTE filler ecosystem today combines specialty chemical producers, advanced materials manufacturers and precision component firms. Notable players we profile include:
- TOAGOSEI CO., LTD. — With ULTEA (zirconium phosphate based) offerings that exhibit NTE behavior to high temperatures and notable chemical resilience, TOAGOSEI is positioned for sealed-glass and high-temperature applications. Their strength is applied material reliability and formulation know-how for adhesion and sealing systems.
- Nippon Electric Glass (NEG) — NEG’s spherical glass-based negative-CTE fillers prioritize packability and dispersibility in resin systems, directly addressing manufacturability and processing efficiency for electronics and precision assemblies.
- Mitsui Kinzoku — By commercializing powders that deliver substantial NTE, Mitsui brings metallurgical and powder-processing scale advantages that suit glass and resin suppression applications where throughput and cost efficiency are important.
- JX Advanced Metals — Focused development of zirconium tungstate (ZrW2O8) with attention to particle fineness and phase behavior positions JX for semiconductor packaging and sealing markets that require tight CTE control and process compatibility.
- Japan Material Technologies Corporation (JMTC) — Offering perovskite oxide-based NTE materials with tunable center temperatures, JMTC represents an innovation vector for thermally responsive composites and advanced epoxies with bespoke thermal profiles.
- ALLVAR Alloys — A different commercialization model: metal-alloy components and custom mechanical parts that exhibit strong NTE and are used directly in optical assemblies and precision structural items where form factor and machinability matter.
Each of these players brings a differentiated value proposition: from powder chemistry and thermal stability to particle morphology and finished-component supply. For strategic buyers and OEMs, the right engagement model will depend on desired control over specification, sensitivity to raw-material cycles and certification requirements in target end-markets.
Supply Chain and Input Risk: The New Operating Reality
Raw material dynamics are an unavoidable part of any 2026 sourcing strategy for NTE fillers. Recent market signals are instructive:
- Tungsten markets have tightened materially, and price spikes observed in early 2026 have direct implications for tungsten-containing NTE chemistries (e.g., zirconium tungstate). Such moves change the relative economics between competing NTE material families and elevate the value of material-agnostic design options.
- Export controls and trade policy shifts — notably actions that affect key concentrate flows — have compressed available global supply and increased the probability of supply interruptions for tungsten-dependent manufacturers.
- Zirconium oxide and related zirconia derivatives also showed price pressure in late 2025, reflecting both energy/input cost pass-through and capacity constraints. For firms using zirconium phosphate, zirconia or related compounds, contingency plans are essential.
For procurement organizations, the takeaway is straightforward: active commodity risk-management (strategic stock positions, diversified sourcing, long-term offtakes), combined with near-term product substitution assessments, will materially reduce margin and schedule exposure.
Strategic Playbook for 2026
PW Consulting’s advisory recommends a four-track strategy for players who want to convert the macro growth tailwind into durable competitive advantage:
- Product and IP posture: Prioritize R&D investments that address dispersibility and particle control (reducing agglomeration and improving resin compatibility), along with efforts to lower phase-transition sensitivity across operating temperatures. Proprietary surface treatments and composite engineering provide defensible differentiation.
- Supply resiliency: Execute dual-sourcing strategies for tungsten and zirconium feedstocks, explore hedging and long-term contracts with upstream miners and consider strategic inventory buffers targeted at high-risk SKUs.
- Commercial focus: Target high-value, high-barrier applications — aerospace, high-end optics, and advanced semiconductor packaging — where certification and reliability premium justify higher margins. Build joint-development agreements with OEMs to lock in application-specific qualifications.
- M&A and partnerships: For firms seeking to scale quickly, bolt-on acquisitions that bring particle-engineering expertise, certifications for regulated markets, or downstream assembly capabilities can accelerate entry and reduce go-to-market friction.
What Our Report Delivers — Practical, Executable Insight
This release is not an academic paper; it is a practitioner’s toolkit. Highlights from the full PW Consulting NTE Filler Market Report include:
- Top-down and bottom-up market forecasts (2026–2032) cross-validated against supply-side capacity and demand signals, with scenario stress-testing for raw-material shocks.
- Commercial due-diligence templates: supplier scorecards, margin sensitivities, and procurement negotiation playbooks tailored to NTE materials.
- Product-development briefs that translate thermal expansion targets into formulation priorities (particle size, morphology, surface chemistry, and binder compatibility), plus a prioritized technology roadmap for R&D teams.
- Regulatory and certification pathway maps for aerospace, medical and semiconductor applications, including time-to-qualification estimates and key test protocols.
- Competitive landscape dossiers with capability matrices, potential white-space opportunities, and strategic options (partner, acquire, co-develop) for market entrants.
We deliberately omit line-by-line disclosure of granular regional splits and application-specific revenue buckets in this public summary — the full dataset and interactive dashboards are available through our report portal for clients who require the complete, attributional intelligence necessary to execute transaction and product decisions.
Near-term Signals to Watch in 2026
- Raw-material price trajectories and policy announcements affecting tungsten and zirconium supply will be immediate leading indicators of margin pressure and product re-pricing.
- Certification wins and aerospace approvals will re-rate suppliers into premium segments; watch for additional announcements following the recent aerospace certifications observed in the sector.
- New product introductions and manufacturing methods (e.g., nano-structured powders or additive-compatible formulations) will indicate where early adopters are focusing and where downstream demand is likely to concentrate.
- Consolidation activity: given the market’s concentration dynamics, expect selective M&A among specialty providers aimed at augmenting particle-engineering or downstream application capabilities.
Concluding Recommendations for 2026 Planning
For leadership teams our advice is pragmatic: treat NTE fillers as a strategic material category, not a commodity. Embed thermal-management considerations into product and procurement planning cycles, invest in joint-development projects with leading suppliers to secure differentiated formulations, and build supply-side contingencies for critical feedstocks. The market’s projected growth — underpinned by a near-double-digit CAGR relative to many mature materials segments — creates attractive upside for companies that act now to secure technology, qualify materials in target assemblies and mitigate supply risk.
PW Consulting’s full Negative Thermal Expansion Filler Market Report provides the granular forecasts, supplier assessments, and execution-ready playbooks required to convert this strategic insight into measurable commercial outcomes. For clients who need the datasets, scenario models, and bespoke advisory to support 2026 capital and product decisions, please visit our report page to access the complete intelligence suite and to arrange a dedicated briefing.
For detailed analysis of this topic, please visit the official page: Negative Thermal Expansion Filler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: UV Gravure Ink Market to Expand at 7.15% CAGR (2026–2032), Growing from USD 720.01M in 2025 to USD 1,167.57M by 2032
By pmarketresearch, 2026-07-13
UV Gravure Ink Market 2026: Strategic Imperatives from PW Consulting’s Market Study
As the global gravure ink landscape shifts under regulatory pressure, material innovation, and evolving packaging economics, decision-makers must translate market intelligence into decisive action for 2026. PW Consulting’s UV Gravure Ink Market study (base year 2025, forecast period 2026–2032) synthesizes five years of historical performance with a granular forward view, delivering the actionable frameworks executives need to orient R&D, commercial, and capital-allocation choices. At the macro level the market stood at approximately USD 720 million in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 7.15% over the projection window—trajectory that implies both scale and opportunity for differentiated players.
UV Gravure Ink Market
Why this study matters for 2026 strategic choices
-
Timing matters: 2026 is a junction year in which regulatory harmonization, LED-curing adoption, and supply-chain reconfiguration converge. The report maps these inflection points into prioritized investment themes and near-term actions that materially affect margin and market access.
UV Gravure Ink Market -
Risk-to-reward clarity: with a market that is expanding steadily, the study isolates risk vectors—raw material volatility, photoinitiator reformulation needs, and oxygen-inhibition process costs—and quantifies their impact on operating models and product roadmaps.
UV Gravure Ink Market -
Competitive posture: the study decodes how leading ink manufacturers are responding across product, capacity, and regulatory dimensions, enabling firms to benchmark strategic moves without waiting months for public filings or trade show noise to clarify intent.
What the report contains — practical, executable intelligence
-
Market sizing and trajectory: a reconciled top-down and bottom-up model from 2020–2025, with a forward projection through 2032. The study synthesizes demand drivers and cost inputs to produce scenario outputs that are ready to be stress‑tested in boardrooms and investor decks.
-
Regulatory impact matrices: line-item assessments of emerging rules in major jurisdictions—particularly restrictions on certain photoinitiator chemistries—and their implications for formulation, certification timelines, and go-to-market sequencing.
-
Technology adoption roadmaps: comparative analysis of mercury-arc, LED, and advanced photoinitiator systems, including practical decision trees for converters and ink producers (capex thresholds, retrofit vs. greenfield economics, and productivity impacts such as curing line speed and energy consumption).
-
Supply-chain and raw-material stress tests: sensitivity models for monomer, oligomer, and photoinitiator price shocks; recommended hedging approaches; and supplier concentration assessments that inform procurement strategies and strategic partnerships.
-
Production and process playbook: operational guidance on nitrogen inertization to counteract oxygen inhibition, process controls to improve curing yields, and protocols to reduce scrap—presented as a checklist for factory directors and continuous-improvement teams.
-
Commercial playbook: segmentation-agnostic go-to-market strategies that include value-based pricing templates, contract structures for long-term supply, and channel prioritization criteria for converters, brand owners, and co-packers.
-
M&A and partnership shortlist: a curated, due-diligence-ready list of target profiles—technology specialists, regional converters, and raw-material integrators—matched to strategic objectives such as geographic expansion, capability acquisition, or margin enhancement.
-
Sustainability and circularity modules: technical guidance on deinkability and mono-material compatibility to align prints with evolving packaging regulations and to secure shelf-space with sustainability-minded brand owners.
Key market dynamics that will shape winners and losers
-
Regulatory tightening on photoinitiators: authorities in several major markets are restricting specific photoinitiator chemistries over migration concerns. This is not a theoretical risk—manufacturers will face concrete reformulation costs and extended validation cycles for food-contact applications. Firms with established low-migration platforms or rapid reformulation capabilities will obtain first-mover advantage for major packaging accounts.
-
Energy-curable technology migration: LED-curable systems are moving from niche to mainstream. The energy and line-speed benefits are clear, but converters must weigh retrofit capital versus process disruption. Our scenario analysis shows that LED adoption materially reduces operating cost per linear meter only once run-lengths exceed certain thresholds; the study provides the break-even calculus for 2026 budgeting.
-
Operational complexity: UV systems are sensitive to oxygen inhibition, often necessitating nitrogen inertization. This adds both capex and operational overhead. The study quantifies the typical N2 consumption profile and outlines options—from modular inertization units to centralized nitrogen supply—that materially affect conversion economics.
-
EU circularity and deinkability pressure: packaging rules incentivize mono-material solutions, increasing demand for inks that enable recycling or deinking. This trend favors formulations engineered for barrier performance and recyclability—and will be a key procurement filter for major brand owners by 2026.
-
Market concentration and competitive dynamics: the market exhibits a moderate level of concentration among leading players. The top three competitors account for a meaningful share of industry revenue, and the top five aggregate over half of market sales—conditions that favor scale players for large contracts but leave niches open for agile, technology-focused entrants.
Competitive landscape: what leading players are signaling
-
Product innovation as defense: established ink manufacturers are launching low-migration, faster-curing systems and promoting compliance credentials to retain packaging business where regulatory scrutiny is highest. Recent product introductions emphasize advanced photoinitiator systems and formulations tuned for food-contact compliance.
-
Capacity and footprint shifts: investments and expansions in Asia and other growth corridors indicate a dual focus on proximity to converters and cost-efficient production. These moves reduce lead times and improve service levels for large converters operating regional supply chains.
-
Trade-show and industry engagement: active participation in label and packaging exhibitions remains a critical channel for showcasing technical capabilities—particularly around sustainability claims and energy-curable solutions—and for building OEM and brand relationships.
Strategic recommendations for 2026 planning
-
Prioritize regulatory-compliant platforms now: allocate R&D to low-migration formulations and secure early-stage certification for strategic accounts. Delaying reformulation initiatives risks supply interruptions and contract losses when rules are enforced.
-
Build LED adoption playbooks: run pilot lines with clear KPIs (energy, speed, yield, maintenance) and develop a staged investment plan that ties capital deployment to measured operational improvements.
-
Secure photoinitiator supply and diversify: where regulation restricts chemistries, having alternative supplier relationships—and validated substitute chemistries—reduces disruption. Consider strategic long-term contracts or equity partnerships with upstream suppliers.
-
Operationalize nitrogen strategies: evaluate modular inertization or centralized supply, but prioritize rapid deployment options to avoid production bottlenecks tied to oxygen-related spoilage.
-
Invest in deinkability and circularity claims: target product development to meet mono-material and deinkability requirements; these attributes increasingly influence procurement decisions by global brands and retail chains.
-
Refine M&A and partnership criteria: pursue targets that close capability gaps (e.g., LED expertise, regulatory science, regional manufacturing footprint) rather than only revenue lift—this accelerates time-to-value and mitigates integration risk.
Signals from recent market activity
-
Product launches emphasizing enhanced adhesion and reduced energy consumption underscore a competitive pivot toward higher-performance UV systems that also address environmental scrutiny.
-
Capacity expansions in growth regions indicate that supply-side players anticipate sustained demand from packaging converters seeking local sourcing and faster lead times.
-
Continued trade-show engagement reflects the role of direct technical demonstration in converting cautionary buyers—especially brand owners requiring documented compliance and performance data.
How PW Consulting’s study supports boardroom decisions
-
Decision-grade scenario outputs: alternate market trajectories that tie regulatory timelines, technology adoption rates, and raw-material shocks to P&L outcomes—enabling CFOs and strategy teams to model contingencies for 2026 capital allocation.
-
Ready-to-use operational templates: procurement checklists, retrofit capex calculators, and validation roadmaps that reduce the time from decision to deployment.
-
M&A diligence accelerators: standardized assessment frameworks, integration checklists, and synergies playbooks to compress transaction timelines and improve valuation accuracy.
As the UV gravure ink market progresses toward the latter half of the decade, the next 12–18 months will disproportionately determine competitive positions. PW Consulting’s market study equips leaders with the quantitative outlook and practical toolset to convert regulatory challenges and technology shifts into sustainable revenue and margin expansion. For executives preparing budgets and strategic plans for 2026, the study functions as both a navigation chart and an operational playbook—highlighting where to move fast, where to hedge, and where to partner.
To access the full set of models, scenario outputs, and executable playbooks referenced above, PW Consulting invites industry practitioners to review the complete report and supplementary toolkits available through our market research portal.
For detailed analysis of this topic, please visit the official page: UV Gravure Ink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PLA Biodegradable Stretch Film Market to Grow at 12.99% CAGR, Reaching USD 1,799.75 Million by 2032
By pmarketresearch, 2026-07-13
PLA Biodegradable Stretch Film Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
PW Consulting’s latest market study on the PLA biodegradable stretch film market delivers a focused, decision-ready view for leadership teams preparing plans in 2026. Built on a 2025 base year (with historical coverage from 2020–2025 and forecast through 2026–2032), the report quantifies a market that has roughly doubled in scale since 2020 and is poised to continue rapid expansion. Our modeling shows total market revenue rising from USD 765.0 Million in 2025 to USD 1,799.75 Million by 2032, representing a compounded expansion trajectory consistent with a 12.99% CAGR across the forecast window.
PLA Biodegradable Stretch Film Market
Why this matters now
-
Timing: 2026 is the inflection year for many procurement and innovation programs. Regulatory momentum, buyer preference shifts, and improving PLA supply economics are converging to make commercial launches and scale-ups materially more attractive this year.
PLA Biodegradable Stretch Film Market -
Margin and sourcing pressure: Raw-material dynamics and regional cost divergence are already affecting supplier selection and margin expectations. Our price and feedstock analysis highlights a narrow but meaningful band of PLA cost structures across primary markets, and a lactic-acid and PLA industry that expanded in value between 2025 and 2026 — a factor buyers and CFOs must model into 2026 budgets.
PLA Biodegradable Stretch Film Market -
Commercial differentiation: Brand owners and logistics operators face accelerating demands for credible compostable alternatives to conventional stretch film. Firms that lock in validated suppliers, performance-tested formulations, and compliant certification frameworks in 2026 will hold a decisive advantage in RFPs and sustainability reporting cycles in 2027–2028.
What PW Consulting’s report delivers — practical, executable intelligence
The report is structured to give immediate, operational lift to strategy, procurement, product, and M&A teams. Key deliverables include:
-
Market sizing and validated forecasts (2020–2032) with scenario layers that stress-test demand under conservative, base, and accelerated adoption paths.
-
Driver and restraint maps tying policy, circular-economy infrastructure, and feedstock economics to short- and medium-term adoption curves.
-
Supply-chain and cost models: landed-cost templates, supplier scorecards, sourcing playbooks, and a raw-material sensitivity matrix that quantifies EBITDA exposure to PLA price moves.
-
Regulatory and compliance roadmaps that translate EU directives, national single-use plastics restrictions, and export-compliance expectations into actionable checklists for product development and labeling.
-
Procurement negotiation kits and pilot-to-scale implementation guides, including sample technical acceptance criteria, testing protocols, and consumer-claims guardrails for compostability certifications.
-
Competitive landscape analysis and M&A playbooks that prioritize targets by technological fit, manufacturing footprint, and capability to deliver PLA/PBAT blends at scale.
-
Risk register and mitigation playbooks covering feedstock fluctuation, certification misalignment, composting infrastructure gaps, and substitution threats from other bio-based resins.
Competitive landscape: who’s shaping the market and how
The market exhibits a moderate concentration profile: the top three suppliers command a significant niche presence while the top five broaden that influence. This structure creates a dual-speed market — established players able to supply global programs, and nimble regional specialists that drive innovation in formulations and localized service models.
-
YITOPACK (Huizhou Yito Packaging Co., Ltd.) — A leading Chinese OEM focusing on PLA and PLA/PBAT blends for pallet wrapping. Strengths include scale manufacturing for industrial logistics applications and the capacity to provide customizable thicknesses and specifications tailored to customer handling systems.
-
RTG Films — US-based converter specializing in compostable PLA films with clear grades suitable for sustainable stretch and packaging. Their market positioning is built on conversion expertise and integration with North American supply chains.
-
BUHE Technology Ltd — Chinese producer emphasizing PLA + PBAT blends positioned as compostable alternatives without microplastic risk. Their go-to-market focus is industrial pallet wrapping where compostability claims must be defensible.
-
Hongren Packing — A China-based supplier with a certification-led proposition (OK Compost, EN13432, BPI). They serve customers requiring documented end-of-life performance and export-ready certification packs.
-
Torise Biomaterials — Specializes in tailored PLA/PBAT films with engineering emphasis on clarity, strength, and consistency — attractive to brand owners seeking parity with conventional film performance.
-
Taghleef Industries — A global player offering biodegradable BoPLA films (Nativia® line). Their international production footprint and product breadth make them a logical partner for multi-region rollouts.
-
Shanghai Yifu Packaging, Chintec, Hubei HYF, Easy Flux — Regional manufacturers driving localized innovation, speed-to-market, and competitive pricing. Collectively they serve fast-moving segments including food, retail, and domestic logistics.
Raw materials and regulatory context
PLA production remains anchored in renewable feedstocks, principally corn-derived starch, which continues to represent the majority route-to-market for PLA monomers. The upstream lactic-acid and PLA value chain expanded meaningfully between 2025 and 2026, reflecting both capacity additions and higher commercial uptake. PLA feedstock costs vary by market; in early 2026 we observed a meaningful band of regional price differentials that suppliers and buyers must account for when comparing landed costs and negotiating multi-territory contracts.
On the regulatory front, Europe’s sustained restrictions on single-use plastics and a mosaic of more than 70 national-level bans are accelerating adoption of PLA-based alternatives for packaging. Complementary policy drivers in China (industrial-park biodegradable packaging programs and export-aligned compliance) are encouraging PLA-PBAT hybrids as practical industrial solutions. These policy forces make 2026 a critical year for firms to align technical specifications with credible end-of-life claims and to secure supply certainty ahead of tightened compliance windows.
Scenarios and risks that should shape your 2026 roadmap
-
Price volatility: PLA feedstock swings will influence commercial thresholds for replacing conventional PE-based stretch films. Hedged purchasing and multi-supplier strategies are prudent.
-
Certification vs. infrastructure mismatch: Compostability claims are only as valuable as the composting infrastructure to process them. Market winners will couple claims with downstream processing partnerships or take-back pilots.
-
Performance trade-offs: PLA/PBAT blends bridge the mechanical gaps versus conventional film, but technical benchmarking against customer handling systems remains essential to avoid claim-based recalls or uplift costs.
-
Supply concentration: With a moderate top-tier concentration in the vendor pool, single-source exposures can create lead-time and pricing risk for large-scale rollouts.
Priority moves for 2026 — a tactical checklist
-
Procurement: Implement a two-tier sourcing strategy (global preferred suppliers + regional fast-fail converters) and model landed cost scenarios against PLA price-band sensitivities.
-
Product development: Prioritize PLA/PBAT formulations for pallet-wrap applications that meet minimum durability thresholds; embed certification and on-package guidance from the outset.
-
Commercial pilots: Launch targeted logistics pilots with tier-1 carriers and distribution centers where composting or industrial processing can be documented.
-
M&A and partnerships: Screen acquisition targets that provide either capacity to scale or specialized formulation IP that shortens time-to-market for clear, high-strength grades.
-
Regulatory readiness: Map your product claims to regional waste-processing realities and prepare labeling, chain-of-custody, and certification dossiers to support global tenders.
How PW Consulting’s report helps you execute in 2026
This publication is deliberately tactical. It equips commercial, procurement, and technical teams with the precise inputs they need to set 2026 budgets, prioritize pilots, and negotiate supplier contracts with confidence. The full report includes downloadable cost-model workbooks, supplier scorecards, test protocol templates, and an interactive scenario dashboard designed to stress-test programs against PLA price and policy shifts.
Next step
We have deliberately provided this preview to surface the strategic implications and practical actions companies must consider in 2026. The full report contains the detailed segmentation, supplier datasets, and localized market intelligence that procurement and product teams require to operationalize the recommendations shown here. Access the complete study to obtain the granular supplier profiles, regional matrices, and downloadable decision tools that will convert 2026 opportunity into measurable commercial outcomes.
For detailed analysis of this topic, please visit the official page: PLA Biodegradable Stretch Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: MPPO Resin for CCL Market Set to Grow at a 12.48% CAGR During 2026–2032
By pmarketresearch, 2026-07-13
MPPO Resin for CCL Market — Strategic Intelligence Briefing for 2026 Decision-Making
Executive preview
PW Consulting’s new market research brief on MPPO (modified polyphenylene oxide) resins for copper-clad laminates (CCL) synthesizes the commercial, technical, and regulatory forces that will shape supplier and buyer strategies through 2032. The market exhibits strong momentum: from an estimated industry size in 2025 of approximately USD 545 million, we model a structural expansion at a compound annual growth rate (CAGR) of 12.48% across the 2026–2032 forecast window, reaching just over USD 1.24 billion by 2032. That trajectory reflects not only demand from high-speed and high-frequency substrates in 5G and AI data center applications but also a premiumization trend driven by regulatory constraints and raw-material-driven pricing dynamics.
Mppo Resin For Ccl Market
Why this matters to corporate leaders in 2026
As companies plan capacity, product roadmaps, and supply-chain strategies for 2026 and beyond, the MPPO-for-CCL market presents a classic high-growth, high-complexity opportunity. Our analysis is designed to convert that complexity into prioritized actions. Specifically, the report helps stakeholders assess where to invest, when to lock in feedstock agreements, how to structure partnerships with CCL fabricators, and which product attributes will command margins and customer preference over the next investment cycle.
Mppo Resin For Ccl Market
What the report delivers — practical, transaction-ready intelligence
PW Consulting’s deliverable is intentionally operational. Readers can expect a suite of tools and actionable analyses, including:
Mppo Resin For Ccl Market
- Market-sizing and a transparent forecasting model (2020–2032) with scenario toggles for demand elasticity, raw-material shocks, and regulatory tightening.
- Price-sensitivity and margin-impact simulations that translate fluctuations in the primary feedstock (notably 2,6-xylenol) into unit-cost and realized-margin outcomes for resin makers and CCL laminators.
- Capex and capacity-planning playbooks that align ramp schedules with lead indicators from electronics OEM demand (5G infrastructure, AI servers, and automotive high-speed signaling).
- Supplier and technology scorecards, including readiness for halogen-free and low-VOC formulations, certification timelines for compliance regimes such as REACH and RoHS, and manufacturing scalability assessments.
- Go-to-market blueprints for resin formulators and compounders targeting turn-key solutions for high-frequency and low-loss CCL applications, with channel strategies for APAC, North America, and EMEA customers.
- M&A and partnership heatmaps that prioritize targets by technological differentiation, geographic footprint, and near-term capacity availability — framed to support diligence rather than replace it.
- Regulatory and sustainability roadmaps that map product redesign requirements, testing windows, and cost-to-compliance estimates for flame-retardant and halogen-free material transitions.
Market dynamics — drivers, constraints, and the near-term outlook
The ongoing upgrade cycle in telecom infrastructure and the accelerating adoption of AI compute create persistent, secular demand for high-performance substrates. MPPO-derived chemistries are attractive because they balance low dielectric loss, thermal stability and dimensional fidelity — attributes central to high-speed and high-frequency PCB laminates. Our historical reconstruction (2020–2025) shows a steady adoption curve, and the forecast through 2032 embeds both conservative and aggressive scenarios to reflect uncertainty in end-market capex.
Key structural dynamics captured in the report include:
- Upstream feedstock volatility: 2,6-xylenol is the dominant upstream material for PPE/MPPO chemistry. Its price swings and availability materially influence final resin pricing and have driven recent shifts toward upstream vertical integration and long-term offtake contracts.
- Regulatory premiumization: Stricter limits on flame retardants and VOCs are accelerating demand for halogen-free and low-emission resin grades. Compliance costs and testing lead times are non-trivial and must be budgeted into product-program economics.
- Consolidation and concentration effects: The market displays meaningful concentration among a limited set of global suppliers — a structural feature that affects bargaining power, lead times, and the competitive response to demand surges.
- Technology differentiation as a margin driver: Small but meaningful dielectric and mechanical advantages deliver outsized value in applications like AI server PCBs and 5G base stations, where signal integrity and thermal reliability have direct system-level cost implications.
Competitive landscape — what established players and regional champions are doing
Our competitive intelligence section profiles the global leaders and regional specialists shaping material availability and capability sets. Highlights include strategic moves and product positioning from both multinational producers and regional champions:
- SABIC: Positioned with specialty PPE oligomers (e.g., NORYL SA9000) aimed at low-loss CCL applications in 5G and AI server markets. Recent announcements include incremental capacity expansion of PPE oligomers slated for completion in 2H 2026 to support growing demand — a material development for OEMs and laminators to monitor when planning supplier capacity commitments.
- Asahi Kasei and Mitsubishi Gas Chemical: Both Japanese players are investing in modified PPE and PPO chemistries optimized for high-frequency and high-speed CCLs, emphasizing dielectric performance, dimensional stability, and formulation flexibility for multilayer systems.
- Regional Chinese capability: Domestic producers, including major state-backed and private groups, are expanding capacity and technical competencies for PPE-based resins. Notably, recent project launches target large-scale production of low-dielectric thermosetting PPO resin for communication and server substrates.
- Specialists and niche suppliers: Several suppliers across South Korea and China are differentiating through application-specific grades (automotive high-speed signaling, halogen-free laminates) and advanced oligomer chemistries to compete on performance rather than price alone.
These dynamics create windows for strategic partnerships, selective capacity expansion, and targeted R&D investments that can capture premium segments of the value chain.
Risks, sensitivities and scenario planning
Our scenario analysis isolates the dominant risk vectors that enterprises should stress-test in 2026 planning cycles:
- Raw-material shock: A sustained spike in 2,6-xylenol prices compresses margins and shifts cost competitiveness toward integrated suppliers or those with hedging programs.
- Regulatory acceleration: Faster-than-expected bans or tighter exposure limits for legacy flame retardants shorten commercialization horizons for existing formulations.
- Supply concentration events: Capacity outages at a small number of global producers can create temporary supply tightness and price volatility in the resin market, impacting lead times for laminate manufacturers.
- End-market demand variance: Slower-than-expected upgrades in telecom infrastructure or a delay in AI server expansion materially reduces demand for premium low-loss laminates.
For each scenario, the report offers quantified P&L and cash-flow sensitivities, inventory and contract-duration recommendations, and decision thresholds that convert uncertainty into actionable triggers.
Strategic recommendations for 2026 — prioritized, time-bound actions
Based on our analysis, we recommend that corporate decision-makers prioritize the following actions in the 2026 planning horizon:
- Implement dual-sourcing or long-term offtake agreements for critical feedstocks; where possible, pursue partial vertical integration or strategic investments in upstream capacity to mitigate feedstock-driven margin compression.
- Prioritize halogen-free and low-VOC product lines in the next fiscal-year R&D portfolio, and map certification timelines against key customer qualification windows (telecom OEMs, data-center integrators, and automotive Tier 1s).
- Align capacity-expansion or brownfield conversion projects with supplier roadmaps — target funding decisions in H1–H2 2026 to capture demand ramps and avoid mid-cycle shortages.
- Negotiate flexible pricing clauses tied to benchmark feedstock indices or mutual hedging arrangements to share raw-material risk across the value chain.
- Use the report’s supplier scorecards and M&A heatmaps to identify prioritized partners for joint development agreements, licensing, or bolt-on acquisitions that fill technical gaps in low-loss or high-frequency performance.
Why PW Consulting — methodological rigor and commercial relevance
PW Consulting combines materials chemistry know-how with transaction-grade market analytics. Our proprietary forecast model integrates historical shipment data, end-market capex indicators, and raw-material input-cost mapping. The report’s confidence intervals and sensitivity matrices are designed for CFOs, R&D heads, supply-chain leaders, and corporate development teams seeking to make capital allocation decisions that are defensible to boards and investors.
Next steps — how to convert insight into advantage
This briefing is a compact preview of a full report that contains the detailed segmentation, supplier matrices, and downloadable modeling templates required to execute the actions outlined above. To preserve the strategic value of that granular intelligence — including detailed regional and application splits, supplier-specific capacity maps, and model outputs — the full dataset and interactive forecast are available on our report page.
For immediate strategic support, PW Consulting offers tailored briefings, scenario workshops, and diligence packages to operationalize these findings for supply-chain negotiation, product-development prioritization, and M&A screening in 2026.
Contact and access
To access the full MPPO Resin for CCL Market report, interactive forecast, and bespoke advisory engagements, please visit our report page or contact PW Consulting’s industry practice. The full package is structured to be execution-ready for 2026 planning cycles, with modular deliverables to fit strategic, commercial, and technical decision workflows.
For detailed analysis of this topic, please visit the official page: Mppo Resin For Ccl Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Semiconductor-Grade Tungsten Powder Market Set to Grow at 9.15% CAGR from 2026 to 2032
By pmarketresearch, 2026-07-13
Semiconductor Grade Tungsten Powder Market: Strategic Imperatives for 2026 — PW Consulting Report Briefing
Executive Summary
PW Consulting’s new market intelligence brief on the Semiconductor Grade Tungsten Powder Market synthesizes an integrated view of supply, demand, pricing dynamics, regulatory shocks, and supplier strategy to inform corporate decisions in 2026. Anchored by a rigorous dataset spanning 2020–2025 and a detailed forecast through 2032, the report documents a clear multi-year acceleration: the market expanded from roughly USD 385 million in 2020 to about USD 565 million in 2025 and is modeled to exceed USD 1.04 billion by 2032, tracking a compound annual growth rate of 9.15% over the forecast horizon. This release outlines the strategic value of the analysis for C-suite executives, procurement leads, and M&A teams while intentionally withholding granular segment tables to encourage full report engagement.
Semiconductor Grade Tungsten Powder Market
Why This Matters for 2026 Decision-Makers
- Procurement resilience: Recent upstream disruptions have exposed single-point vulnerabilities in tungsten feedstocks. Procurement strategies calibrated to 2026 realities must balance spot exposure with structured long-term offtakes and diversified supplier panels.
- Capital allocation: Strong market growth and rising material intensity across advanced packaging and deposition processes create selective opportunities for capacity expansion, downstream integration, and targeted vertical investments.
- Regulatory and supply-chain risk management: Export controls and feedstock concentration have immediate pricing and availability consequences; companies that preemptively model regulatory scenarios will preserve product roadmaps and time-to-market for critical nodes.
Market Trajectory: Data-Driven Context (High Level)
Our historical sizing shows steady, demand-led expansion through 2020–2025, accelerating as semiconductor content per device climbs and advanced deposition and metallization techniques proliferate. The 2026–2032 forecast, derived from bottom-up modelling across technology adoption curves and wafer fab investment plans, produces a 9.15% CAGR for the period. This trajectory reflects both secular semiconductor demand and episodic supply-side shocks that have structurally tightened availability of semiconductor-grade tungsten powder.
Semiconductor Grade Tungsten Powder Market
Dynamics: Supply Shocks, Pricing, and Feedstock Stress
- Export controls and upstream feedstock volatility: In early 2025, restrictive export measures on key tungsten intermediates were introduced, resulting in material licensing requirements that materially reduced export volumes. The consequences cascaded through the supply chain and were a principal driver of a multi-fold rise in market prices for semiconductor-grade powders during 2025–2026.
- Feedstock scarcity and pricing spikes: The principal upstream intermediate, ammonium paratungstate (APT), saw unprecedented price swings in the period following tightened exports. Certain reporting windows registered several-hundred-percent jumps, forcing downstream buyers to reprice product roadmaps and re-evaluate procurement contracts.
- Near-term market tightness vs. structural growth: While short-term tightness is primarily supply-driven, structural demand from advanced node manufacturing, 3D integration, and specialty deposition techniques (CVD/ALD and sputtering use-cases) underpins the medium-term growth path.
Competitive Landscape: Who Moves Markets
The semiconductor-grade tungsten powder market is concentrated and technical barriers to entry are meaningful. The competitive field combines legacy refractory metals specialists, integrated producers, and regionally anchored manufacturers. Our concentration analysis indicates a compact top tier, with the leading three and five suppliers controlling a substantial portion of market throughput—an important consideration when evaluating counterparty risk and bargaining power.
Semiconductor Grade Tungsten Powder Market
- Buffalo Tungsten Inc. (Depew, NY) — A specialized high-purity tungsten metal powder producer with strengths in niche, high-reliability applications. Its focus on quality and traceability positions it well for semiconductor supply chains that emphasize material provenance.
- Global Tungsten & Powders Corp. (Towanda, PA) — A western producer with multi-site production capability. Recent product introductions tailored for semiconductor applications signal an emphasis on differentiated chemistries and tighter tolerances for electronic-grade usage.
- Elmet Technologies LLC (Lewiston, ME) — Vertically integrated production from oxide to powder, offering control over impurity profiles and the flexibility to meet bespoke customer specifications.
- H.C. Starck Tungsten Powders (Goslar, Germany / Mitsubishi Materials) — A supplier emphasizing recycling and closed-loop material strategies; recently reported a notable recycling rate that serves both sustainability goals and feedstock security.
- Kennametal Inc., Edgetech Industries, AEM Metal, Stanford Advanced Materials, Atlantic Equipment Engineers, Japan New Metals, and major Chinese producers — Each brings distinct capabilities across particle engineering, spherical powder forms, and scale production. Collectively, these firms form a supply map with different technical specializations and geopolitical footprints.
Recent corporate activity reinforces market shifts: a product launch focused explicitly on semiconductor-grade powders by a major western supplier and operational disclosures on recycling rates by a leading manufacturer are symptomatic of a broader pivot—suppliers are investing in both technical differentiation and resilience-focused strategies.
Report Contents: Practical, Actionable Deliverables
PW Consulting’s full report is built for executables: it moves beyond narrative to deliver playbooks and decision tools you can use in 2026. Key inclusions are:
- Methodology and transparent assumptions behind the 2026–2032 forecast and scenario variants.
- Supply chain heat maps and supplier scorecards that quantify technical capabilities, geopolitical exposure, and capacity elasticity.
- Procurement playbooks with negotiation levers: contract structures, hedging approaches, and buyer-supplier partnership models tailored to tungsten powder markets.
- Pricing model that decomposes input cost drivers (including APT trajectories), conversion yields, and margin pass-through mechanics under alternative regulatory scenarios.
- Technology tracker that maps particle-level innovations, purity regimes, and deposition compatibility to end-market adoption timelines.
- M&A and investment thesis annex: target profiles, valuation sensitivities, and integration risk checklists.
- Risk matrix and regulatory scenario planning: probability-weighted impacts of export policy shifts, feedstock embargoes, and substitution risks.
Strategic Recommendations for 2026
Our analysis translates into eight priority actions for executives planning around the 2026 inflection point:
- Formalize multi-tiered sourcing strategies: Combine secure long-term allocations with tactical spot exposure; prioritize suppliers with demonstrable supply-chain traceability and redundant processing locations.
- Invest in feedstock flexibility: Where feasible, retrofit or design process lines to accept alternate tungsten chemistries or particle morphologies to reduce single-source dependency.
- Capitalize on supplier consolidation: Use the market’s concentrated supplier base to negotiate performance-based agreements, but recognize the counterparty pricing power when appetite for capacity is tight.
- Prioritize technical partnerships: Co-develop powder grades or particle treatments that improve yield or compatibility with advanced deposition methods—this can create defensible differentiation and thinner cost pass-throughs.
- Embed regulatory scenario planning into product roadmaps: Shorten decision cycles for qualification runs and maintain modular approval paths to mitigate sudden material substitutions.
- Explore recycled-content strategies: Recycled tungsten is emerging as both a supply buffer and an ESG lever; partnership opportunities exist with operators reporting high recycling rates.
- Gate M&A decisions with supply-chain analytics: Targets should be evaluated not only on EBITDA accretion but also on feedstock control, facility footprint, and qualification backlog for semiconductor customers.
- Monitor pricing corridors: Apply dynamic cost-pass-through models in customer contracts where possible to preserve margins during elevated volatility windows.
How We Built the View
The forecast uses a hybrid approach combining bottom-up adoption curves for semiconductor deposition and metallization processes, detailed supplier capacity modelling, and scenario-driven stress tests of supply chain interruption events. We triangulated industry data, proprietary supplier interviews, and third-party commodity pricing intelligence to create a defensible, decision-focused output.
Conclusion: Navigating a Strategic Inflection
The semiconductor-grade tungsten powder market sits at a strategic inflection: structural demand growth is meeting episodic supply-side constraints and tighter regulatory oversight. For companies dependent on these materials, 2026 is a year to translate scenario planning into executed strategies—whether through procurement playbooks, targeted investments, supplier partnerships, or selective M&A. PW Consulting’s comprehensive report provides the data, frameworks, and executable recommendations to make those choices with confidence.
Next Steps
This briefing is intended as an executive prelude. The full PW Consulting report contains the granular segmentation, supplier scorecards, and actionable playbooks referenced above. For access to the complete intelligence package, scenario workbooks, and bespoke advisory engagements tailored to your organization’s role in the tungsten powder value chain, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Semiconductor Grade Tungsten Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CPVC Power Pipe Market to Reach USD 2.59 Billion by 2032 at 6.67% CAGR—Asia‑Pacific Leads with USD 908.1M in 2025
By pmarketresearch, 2026-07-13
CPVC Power Pipe Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive preview from PW Consulting’s 2026 market intelligence suite
As power networks, telecom backbones and industrial plants accelerate upgrades, the market for CPVC power pipe is entering a phase of sustained expansion and strategic complexity. Our new PW Consulting report — covering historical performance (2020–2025) and forward forecasts through 2032 — synthesizes demand drivers, supply-chain pressures and competitive positioning into a decision-ready narrative for corporate leaders planning 2026 investments.
Cpvc Power Pipe Market
Market trajectory at a glance
After a five-year expansion through 2025, the CPVC power pipe market reached an estimated USD 1,648.6 million (base year 2025). Our model projects a continuation of growth into the forecast window (2026–2032) at a compound annual growth rate (CAGR) of 6.67%, lifting total market value toward approximately USD 2,590.7 million by 2032. The transition from retrofit-centric demand in earlier years to a blended mix of urban grid modernization, telecom cable protection upgrades and industrial infrastructure investment underpins this trajectory.
Cpvc Power Pipe Market
These headline figures are the starting point. What matters for 2026 decisions are the underlying vectors — where demand concentrates, how input-cost volatility will affect margins, and which capability investments will yield the best risk-adjusted returns. The report translates headline growth into actionable scenarios for manufacturers, EPC contractors, utilities, and strategic investors.
Cpvc Power Pipe Market
Why 2026 is a strategic inflection
- Capital cycles align with policy windows: Many utilities and governments entering multi-year modernization programs will finalize procurement roadmaps in 2026 — creating near-term volume opportunities and contractual lock-ins.
- Raw material and trade dynamics are fluid: Feedstock price movements and policy actions in 2025 have already reshaped supply economics, and 2026 will be the first year when these impacts fully propagate through procurement and customer pricing.
- Competitive posture matters more than ever: Market concentration remains moderate (CR3 ≈ 21.45%, CR5 ≈ 32.18%), meaning scale, integrated-resin relationships and certification breadth will decide which suppliers capture high-value contracts.
Supply-side dynamics and cost levers
Three forces will dominate supplier economics in 2026:
- Feedstock pricing and availability: CPVC production is closely tied to PVC resin and chlorine feedstock cycles. Notably, spot PVC-related prices were softer in Q2 2025 (with a quarter-over-quarter decline of approximately 5.96% in North America), while US CPVC pricing reached near USD 2,370/MT in June 2025. These moves create both margin pressure and purchasing windows for buyers with flexible sourcing strategies.
- Regulatory intermittency: Environmental audits and tighter emissions controls in 2025 constrained output in several production hubs, particularly in China and parts of Europe, generating transitory supply tightness for import-dependent regions. Compliance-driven capacity curtailments are likely to recur as regulators enforce upgraded standards.
- Trade and tariff volatility: Sharp tariff actions in the 2025 period increased pricing premiums for regions reliant on imports. For 2026 procurement planning, tariff risk needs to be treated as a first-order variable in supplier selection and localization decisions.
For operators and procurement teams, these dynamics translate into concrete trade-offs between spot buys, long-term contracts and near-sourcing investments. The report provides modeled cost curves and procurement scenarios to stress-test these choices under alternative feedstock and tariff pathways.
Segmentation and demand patterns (high level)
Demand for CPVC power pipe is anchored by three application clusters: urban power grid upgrades, telecommunications and cable protection, and industrial/power-plant infrastructure. Each cluster exhibits distinct project rhythms, qualification needs and price sensitivity. Our analysis maps the implications of these differences for product specification, lead times and warranty design — without disclosing proprietary segment allocations in this summary.
Key takeaways for 2026 strategy:
- Urban grid programs favor suppliers with project and logistics scale, tight quality control and long-track records on system integration.
- Telecom and cable-protection projects prioritize conduit integrity, low-install-cost solutions and agile delivery, often favoring specialized channel partners.
- Industrial and power-plant clients demand high-temperature performance, traceability and stringent compliance pedigree, creating premium pockets within the market.
Competitive landscape — capabilities that matter
The CPVC power pipe arena blends global resin leaders, established North American and European manufacturers, and highly capable regional producers across Asia. In our review, key competitors demonstrate discrete strengths:
- Resin and compound leadership: Firms with integrated resin capability maintain a dual advantage: control over raw-material availability and influence over compound specifications. This vertical edge shortens lead times and supports higher-margin engineered lines.
- System suppliers and certification breadth: Manufacturers offering end-to-end systems (pipes, fittings, valves) with robust third-party certifications (e.g., NSF/ANSI) are preferred in regulated projects and public tenders.
- Regional manufacturing & distribution footprints: Local production capacity in high-growth markets reduces tariff exposure and improves responsiveness to utility-defined schedules.
Representative company archetypes we analyze in the full report include long-established North American producers with domestic manufacturing and compliance pedigrees; European thermoplastic specialists providing full-system solutions; and large regional manufacturers across South Asia and China focused on cost competitiveness and local project penetration. Each archetype faces different strategic imperatives in 2026, from downstream integration to export-risk mitigation.
What the PW Consulting report delivers (operational takeaways)
The full report is built for executives who must convert market projections into executable plans in 2026. It contains:
- Scenario-driven revenue models for 2026–2032 reflecting alternative macro, price and regulatory assumptions.
- Supplier risk heatmaps and procurement playbooks that integrate price, lead-time and compliance vectors.
- CapEx prioritization templates for manufacturing scale-up, near-shoring and certification roadmaps.
- Commercial negotiation templates and TCO calculators calibrated for CPVC-specific inputs (resin linked costs, tariffs, logistics premium).
- M&A readiness and target-screening criteria for buyers pursuing inorganic growth in core and adjacent segments.
- Regulatory impact assessment, including country-level constraint scenarios and mitigation approaches for import-dependent markets.
These tools are grounded in our proprietary databases and scenario engines, which synthesize historical performance (2020–2025) with forward-looking demand drivers to produce stress-tested strategies — not just static forecasts.
Strategic actions recommended for 2026
Based on the analysis, PW Consulting recommends that stakeholders prioritize three strategic actions this year:
- Lock strategic feedstock agreements with flexible clauses: Given ongoing feedstock price volatility and tariff risk, suppliers and large buyers should negotiate contracts with indexed pricing collars and capacity guarantees to preserve margins while retaining optionality.
- Invest selectively in near-shoring and certification: Target investments that reduce tariff exposure and shorten lead times for high-value projects. Certifications and traceability investments unlock premium tenders and reduce compliance friction in regulated markets.
- Differentiate on solutions not just product: Move from component sales to system solutions (value-added fittings, life-cycle services, warranty programs) to capture higher-margin pockets and deepen customer stickiness.
How to use the intelligence in 90 days
- Week 1–2: Validate exposure — map your 2026 tender pipeline against supplier concentration and tariff-exposed regions.
- Week 3–6: Run the PW procurement scenario models with your actual cost inputs to identify optimal contracting strategies (spot vs. hedged volume).
- Week 7–12: Execute targeted supplier negotiations or short-term near-shoring pilots to insulate mission-critical projects from feedstock shocks.
Access and next steps
This brief is a strategic preview designed to surface core market dynamics and executive priorities. The full PW Consulting CPVC Power Pipe Market report contains the detailed segment models, supplier profiles, contract templates and downloadable financial models that operational teams will need to execute on the 2026 agenda. For procurement directors, plant managers and corporate strategists, the report converts macro trends into procurement-ready actions and investment choices.
To obtain the full report, detailed scenario tables and the proprietary decision tools described above, please visit our official report page. PW Consulting clients can contact their account lead for expedited delivery and a tailored briefing session.
PW Consulting — converting market insight into executable advantage for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Cpvc Power Pipe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Welded Stainless Steel Tubing Market Poised for 4.2% CAGR Through 2032
By pmarketresearch, 2026-07-13
Welded Stainless Steel Tubing Market 2026: Strategic Imperatives from PW Consulting
The global welded stainless steel tubing market reached USD 18,242.3 Million in 2025 and is set to resume steady expansion over the forecast window. PW Consulting’s new market study projects a compound annual growth rate (CAGR) of 4.2% for 2026–2032, driving the market toward roughly USD 24.33 Billion by 2032. For executives planning capital allocation, supply-chain redesign, or M&A activity in 2026, this report translates macro momentum into disciplined, actionable choices while preserving the proprietary subsegment intelligence that underpins high‑confidence decisions.
Welded Stainless Steel Tubing Market
What the PW Consulting Report Actually Delivers (Practical, Usable Intelligence)
- Rigorous market sizing and trend validation: historical time-series (2020–2025), base‑year reconciliation (2025), and scenario-driven forecasts to 2032 with downside, base, and upside cases.
- Supply‑chain cost and margin maps: raw‑material exposure (nickel/chrome), mill yield curves, conversion cost drivers, and inflation pass‑through assumptions to model price sensitivity.
- Technology benchmarking and adoption curves: laser‑weld, laser‑hybrid, and conventional welding performance, unit cost comparisons, productivity deltas and investment break‑even analyses.
- Regulatory and standards impact assessment: implications of ASTM standards and their adoption timelines for product certification, liability, and contract compliance.
- Competitive positioning and deal pipeline: company scorecards, capability matrices, and a prioritized list of potential acquisition and partnership targets aligned to four corporate archetypes (scale players, high‑value alloy specialists, precision/laser specialists, and regional nimble suppliers).
- Playbooks for 2026 execution: procurement hedging strategies, capacity‑planning templates, product roadmap prioritization, and go‑to‑market tactics tailored for OEM, energy, and industrial end users.
- Interactive decision tools: downloadable models for scenario testing, unit economics, and cash‑flow sensitivity tuned to user inputs.
Note: This press summary intentionally highlights strategic insights and frameworks rather than publishing the full subsegment tables and granular company revenue splits. The complete datasets, dashboards, and segment-level forecasts are available through the report portal.
Welded Stainless Steel Tubing Market
Key Market Dynamics That Will Drive Decisions in 2026
- Steady, broad‑based growth. After a multi‑year recovery phase, the market’s mid‑single digit CAGR reflects structural demand across energy, process industries, transportation electrification, and commercial infrastructure. The growth profile favors players with flexible supply chains and product families that span commodity to high‑performance alloys.
- Raw‑material volatility as an operational risk. Nickel and chromium feedstock pricing swung materially in the run‑up to 2024, creating pronounced input cost risk for manufacturers and buyers. Buyers and producers must embed price‑flexibility clauses and consider financial hedging or forward procurement strategies to protect margins in 2026.
- Technology led differentiation. Laser and laser‑hybrid welding technologies materially improve fatigue resistance and dimensional control versus conventional welding, unlocking new use cases in thermal management, emission control, and structural profiles. Capital allocation to selective automation and welding upgrades is becoming a competitive prerequisite rather than optional.
- Standards and certification as market access gates. Recent and emerging ASTM specifications for mechanical and laser‑welded structural tubing raise the bar for material qualification and traceability. Compliance timelines will influence procurement windows and offer early-mover advantages to certified suppliers.
- Production concentration vs. fragmentation. The industry exhibits low top‑tier concentration—CR3 at c.14.8% and CR5 at c.22.2%—indicating fragmentation and substantial white space for roll‑up, capacity rationalization, and value‑chain consolidation strategies.
Competitive Landscape: Strategic Implications for 2026
The market map includes global steel majors, precision alloy specialists, and highly focused regional fabricators. Each archetype is playing a distinct game:
Welded Stainless Steel Tubing Market
- Precision and performance specialists (e.g., Plymouth Tube Company, Sandvik/Alleima) compete on tight tolerances, specialty grades, and aftermarket value for aerospace, medical, and heat‑exchanger OEMs. Their strategic advantage is IP, quality control, and premium yields.
- High‑alloy and energy-focused producers (e.g., Tubacex) serve demanding oil & gas and petrochemical specifications where metallurgical depth and alloy availability are paramount. These players weather commodity cycles by locking long‑term offtake and leveraging alloy inventories.
- Integrated industrial steel players (e.g., ArcelorMittal, Nippon Steel) bring scale, vertical integration, and broad distribution. Their strengths lie in cost competitiveness on commodity grades and in exploiting global project pipelines through existing client relationships.
- Regional and niche fabricators (e.g., Marcegaglia Steel, Bristol Metals/Brismet, Stainless Structurals, Indiana Tube, KVA Stainless) focus on service, custom profiles, quick turnarounds and compliance to local standards. Laser‑weld enabled firms and those certified to new ASTM profiles will increasingly capture architectural, structural and data‑center opportunities.
- Smaller precision makers (e.g., Fischer Group, YC Inox) and custom suppliers play important roles as specialist partners or tuck‑in targets for strategic acquirers.
Strategic takeaway: the combination of a fragmented supplier base and differentiated technology pathways creates both consolidation opportunities and niches where focused investment can yield outsized margins. Full company scorecards and capability heatmaps are included in the paid report.
Recent Events and What They Signal for 2026
- Standards compliance and trade show visibility from laser‑weld specialists highlights how certification plus targeted marketing accelerates adoption—an advantage for early‑certified players.
- Industry commentary noting dynamic growth in heat‑exchange replacement cycles confirms a durable demand pool for precision welded tubes.
- Raw‑material swings and regional manufacturing footprints underscore the strategic value of diversified sourcing and localized buffering strategies ahead of 2026 project cycles.
Actionable Strategic Recommendations for 2026
- Adopt a three‑track procurement posture: (1) short‑term hedging and indexed contracts for 2026, (2) mid‑term supplier diversification to de‑risk alloy exposure, and (3) strategic supplier partnerships with volume commitments to secure prioritized capacity.
- Prioritize selective capital investment in laser‑weld and automated inspection systems where the technology premium can be monetized (thermal management, EV battery systems, emission controls). Run a two‑year pilot to validate performance gains and commercialization cadence.
- Pursue targeted M&A and JV plays focused on: (a) laser‑weld technology providers and profile fabricators, and (b) regional service leaders that provide fast customer access and JIT logistics for critical end users.
- Institutionalize standards readiness: ensure product development pipelines incorporate ASTM requirements and that quality systems can produce traceable documentation for structural and pressure applications.
- Develop aftermarket and service revenue streams (assembly, coating, inventory management) to reduce exposure to commodity cycle swings and to deepen customer relationships.
- Embed scenario planning in capex decisions: use stress tests for feedstock price spikes, major new project rollouts, and accelerated EV demand shifts to size buffer capacity prudently.
Who Should Read This Report — And Why It Matters for 2026
- C‑suite leaders (CEOs, CFOs, COOs) evaluating strategic investment and portfolio reshaping.
- Procurement and supply chain heads seeking practical hedging frameworks and supplier scorecards.
- M&A teams and private equity assessing roll‑up opportunities in a fragmented market.
- Product and engineering leaders determining when and where to field laser‑welded and high‑alloy offerings.
- Project developers and EPCs who need certified supply sources for project delivery and warranty certainty.
PW Consulting’s study converts broad market signals into executable programs tailored to these stakeholders, with downloadable decision models that permit rapid scenario testing for 2026 actions.
Next Steps (How to Access the Full Intelligence)
This release provides a high‑confidence strategic view while preserving the granular subsegment forecasts, company revenue splits, and the interactive models that constitute the report’s commercial value. To access the full datasets, company scorecards, and the downloadable decision tools that will support 2026 planning, visit the PW Consulting report page. Our team also offers bespoke briefings and scenario workshops for executive teams preparing capital plans and M&A pipelines for 2026.
PW Consulting — translating market dynamics into clear, executable strategy for industrial leaders navigating the welded stainless steel tubing landscape.
For detailed analysis of this topic, please visit the official page: Welded Stainless Steel Tubing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com