

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Single Mode Fiber Bundle Market to Expand at a 7.8% CAGR, Powering Growth in Data Centers and Medical Imaging

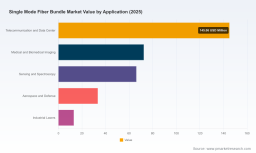
Single Mode Fiber Bundle Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As global networks accelerate capacity upgrades and optical architectures diversify, single mode fiber (SMF) bundles have moved from niche technical components to strategic enablers of carrier, hyperscale, industrial and specialty photonics deployments. PW Consulting’s latest market study, anchored on a 2025 base year and a 2026–2032 forecast window, quantifies a resilient expansion in the SMF bundle market — driven by renewed capital intensity in data centers, broadband rollouts, and an expanding set of non-telecom applications. Our top-line projection: the global market reached USD 330.1 Million in 2025 and is set to grow at a 7.8% compound annual growth rate (CAGR) over the forecast horizon, approaching the mid-hundreds of millions by 2032.
Single Mode Fiber Bundle Market
Why this report matters for 2026 strategy
-
Time-sensitive capital allocation. For network operators and optical component suppliers, 2026 is a pivotal year to rebase capex assumptions. The market’s steady CAGR and near-term uptick imply that procurement strategies and capacity investments made this year will materially affect unit economics and service timelines through 2032.
Single Mode Fiber Bundle Market -
Supplier selection and negotiating leverage. With a moderately concentrated supplier base (the top three firms account for ~42.5% of market revenue and the top five roughly ~58.8%), purchasers can optimize sourcing through portfolio rationalization, long-form agreements, and contingency sourcing — especially where tariffs and raw-material volatility have increased cost exposure.
Single Mode Fiber Bundle Market -
Cross-sector growth windows. Beyond telecom and data centers, applications in sensing, medical optics, high-power laser delivery and aerospace create differentiated premium opportunities for firms that can adapt bundle form-factors and qualification processes rapidly.
Market trajectory: the headline numbers
Our historical series documents consistent expansion from 2020 through 2025, with the market rising from the low hundreds of millions to USD 330.1 Million in 2025. Based on demand drivers and supply-side dynamics modeled in the report, the market is projected to exceed USD 360 Million in 2026 and continue expanding across the 2026–2032 forecast period at a 7.8% CAGR, reaching an elevated scale by 2032. These aggregated figures reflect both traditional telecom demand and the acceleration of specialty applications that are beginning to represent a growing share of vendor roadmaps.
Dynamics shaping 2026 decisions
-
Regulatory and policy shifts. Recent policy moves in major markets are re-shaping transition risk and deployment windows. For example, regulatory changes affecting technology transition rules and broadband classification have implications for legacy copper-to-fiber migration timelines and service continuity obligations. Decision-makers need to model multiple regulatory scenarios when planning network upgrades to avoid stranded assets and to ensure emergency-service continuity during transitions.
-
Trade and tariff risk. Import restrictions and tariffs enacted in the prior 18 months have materially altered landed costs for certain cross-border fiber products. Buyers and manufacturers must revisit trade strategies — localized manufacturing, nearshoring and tariff engineering — to protect margins and maintain predictable lead times.
-
Raw-material and supply-chain pressure. Commodity and component price movements have raised production costs for optical fiber and related assemblies. In early 2026, industry pricing pressures re-emerged, underscoring the importance of active procurement hedging, dual-sourcing strategies and inventory optimization for manufacturers and system integrators.
-
Technology convergence and product innovation. Advances such as multi-core fiber demonstrations and hybrid bundle architectures are beginning to surface in trade shows and product roadmaps. These innovations create both a threat (product obsolescence for incumbents slow to adapt) and an opportunity (premium ASPs for differentiated, performance-assured bundles).
Competitive landscape: what winners are doing
The market exhibits a clear mix of global incumbents and specialized niche players. Established fiber and cable houses continue to dominate systems-oriented and high-volume telecom/business deployments, while highly specialized vendors service medical, aerospace, laser and instrumentation segments where qualification cycles are longer but margins can be premium.
-
Large-volume incumbents — firms with deep optical manufacturing footprints and broad product portfolios are optimizing scale through bend-insensitive designs, high-density bundle constructions and integrated cable systems suitable for backbone and FTTH infrastructures.
-
Regional and specialty players — niche suppliers are capitalizing on application-specific requirements (e.g., high-power laser transmission, fused silica bundles for medical use, polarization-maintaining configurations for instrumentation) by offering configurable assemblies and rapid prototyping capabilities.
Representative firms featured in our competitive analysis include long-standing global leaders in glass and cable manufacturing, prominent system suppliers with enterprise and telco-focused offerings, and agile specialists addressing instrumentation and industrial laser markets. The report profiles each firm’s strategic positioning, product portfolio highlights, commercial strengths, and likely moves over the next 18–36 months — including potential areas of M&A interest and capacity reallocation. Additionally, we map partner ecosystems, critical supplier relationships and the commercial levers companies are using to protect margin under commodity pressure.
What the PW Consulting report provides — practical, decision-ready content
This study is designed as an operational manual for executives, strategy teams and procurement leaders. It blends rigorous quantitative modeling with practical tools you can apply in 2026 planning cycles:
-
Market sizing and demand scenarios — top-down and bottom-up models with alternative adoption curves to stress-test investment decisions.
-
Supply-chain and cost-to-serve mapping — supplier archetypes, raw-material exposure matrices, and end-to-end lead-time sensitivity analysis to guide contingency decisions and inventory policy.
-
Commercial playbooks — tender frameworks, negotiation levers, and contract structures tailored for high-volume telecom buys versus low-volume specialty assemblies.
-
Go-to-market frameworks — segmentation strategies for entering adjacent specialty markets (medical, sensing, aerospace) where certification and qualification are the primary barriers.
-
M&A and partnership scorecards — criteria for target selection, valuation sensitivities, and integration checkpoints relevant to capability-driven consolidation.
-
Regulatory risk matrix — scenario-based assessments of policy changes (including technology transition rules and trade measures) and recommended mitigations for service providers and vendors.
-
Implementation-ready dashboards — KPI sets and monitoring templates designed to track market share, margin pressure, and capacity utilization quarterly.
Actionable recommendations for 2026
-
Rebalance procurement timelines. Lock in strategic suppliers for base volumes while keeping a portion of demand flexibly sourced to exploit spot-market pricing or to pivot to localized production if tariffs persist.
-
Prioritize capability investments. For manufacturers, invest selectively in modular assembly and qualification capabilities that reduce time-to-market for specialty bundles, enabling premium pricing in non-commodity segments.
-
Build regulatory playbooks. Operators should maintain scenario-based plans for legacy service grandfathering and 911/critical-service continuity to reduce transition risk when moving services from copper to fiber.
-
Evaluate M&A or JV paths. Given moderate market concentration, strategic acquisitions that add unique form-factors, connectorization expertise, or regional manufacturing footprint can accelerate market entry and margin accretion.
Signal watch: near-term events to monitor
-
Product demonstrations and multi-core fiber (MCF) integrations showcased at major industry events signal the pace at which alternate architectures could move from lab to deployment. We observed notable MCF and hybrid solutions previewed in early 2026, which merit attention from both buyers and incumbents.
-
Policy and trade updates — sudden changes in tariff postures or domestic content incentives can create immediate shifts in procurement routing and capital allocation.
-
Raw-material cost movements — continued upward pressure will compress margins absent corresponding price pass-through mechanisms; monitoring suppliers’ cost disclosures and inventory positions is now essential.
How to use this analysis
This briefing provides a strategic perspective and operational starting points. For teams preparing 2026 budgets, negotiating supplier agreements, evaluating M&A targets, or designing go-to-market plays in adjacent specialty segments, the full PW Consulting Single Mode Fiber Bundle Market report delivers the necessary quantitative detail, primary-source interview excerpts, and model sensitivities to convert insight into action.
Next steps — where to find the full intelligence
We have intentionally highlighted the analytical framework, headline market dynamics, and the decision-useful tools contained in the study while reserving granular segmentation tables, regional and application breakdowns, and proprietary company-by-company revenue estimates for the full report. Access to the complete dataset and downloadable models is available through our report distribution channels. For enterprise licensing, bespoke briefings, or to request an extract tailored to your procurement, product or M&A agenda, contact your PW Consulting representative or visit our report landing page.
For detailed analysis of this topic, please visit the official page: Single Mode Fiber Bundle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com