

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Welded Stainless Steel Tubing Market Poised for 4.2% CAGR Through 2032

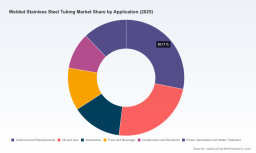
Welded Stainless Steel Tubing Market 2026: Strategic Imperatives from PW Consulting
The global welded stainless steel tubing market reached USD 18,242.3 Million in 2025 and is set to resume steady expansion over the forecast window. PW Consulting’s new market study projects a compound annual growth rate (CAGR) of 4.2% for 2026–2032, driving the market toward roughly USD 24.33 Billion by 2032. For executives planning capital allocation, supply-chain redesign, or M&A activity in 2026, this report translates macro momentum into disciplined, actionable choices while preserving the proprietary subsegment intelligence that underpins high‑confidence decisions.
Welded Stainless Steel Tubing Market
What the PW Consulting Report Actually Delivers (Practical, Usable Intelligence)
- Rigorous market sizing and trend validation: historical time-series (2020–2025), base‑year reconciliation (2025), and scenario-driven forecasts to 2032 with downside, base, and upside cases.
- Supply‑chain cost and margin maps: raw‑material exposure (nickel/chrome), mill yield curves, conversion cost drivers, and inflation pass‑through assumptions to model price sensitivity.
- Technology benchmarking and adoption curves: laser‑weld, laser‑hybrid, and conventional welding performance, unit cost comparisons, productivity deltas and investment break‑even analyses.
- Regulatory and standards impact assessment: implications of ASTM standards and their adoption timelines for product certification, liability, and contract compliance.
- Competitive positioning and deal pipeline: company scorecards, capability matrices, and a prioritized list of potential acquisition and partnership targets aligned to four corporate archetypes (scale players, high‑value alloy specialists, precision/laser specialists, and regional nimble suppliers).
- Playbooks for 2026 execution: procurement hedging strategies, capacity‑planning templates, product roadmap prioritization, and go‑to‑market tactics tailored for OEM, energy, and industrial end users.
- Interactive decision tools: downloadable models for scenario testing, unit economics, and cash‑flow sensitivity tuned to user inputs.
Note: This press summary intentionally highlights strategic insights and frameworks rather than publishing the full subsegment tables and granular company revenue splits. The complete datasets, dashboards, and segment-level forecasts are available through the report portal.
Welded Stainless Steel Tubing Market
Key Market Dynamics That Will Drive Decisions in 2026
- Steady, broad‑based growth. After a multi‑year recovery phase, the market’s mid‑single digit CAGR reflects structural demand across energy, process industries, transportation electrification, and commercial infrastructure. The growth profile favors players with flexible supply chains and product families that span commodity to high‑performance alloys.
- Raw‑material volatility as an operational risk. Nickel and chromium feedstock pricing swung materially in the run‑up to 2024, creating pronounced input cost risk for manufacturers and buyers. Buyers and producers must embed price‑flexibility clauses and consider financial hedging or forward procurement strategies to protect margins in 2026.
- Technology led differentiation. Laser and laser‑hybrid welding technologies materially improve fatigue resistance and dimensional control versus conventional welding, unlocking new use cases in thermal management, emission control, and structural profiles. Capital allocation to selective automation and welding upgrades is becoming a competitive prerequisite rather than optional.
- Standards and certification as market access gates. Recent and emerging ASTM specifications for mechanical and laser‑welded structural tubing raise the bar for material qualification and traceability. Compliance timelines will influence procurement windows and offer early-mover advantages to certified suppliers.
- Production concentration vs. fragmentation. The industry exhibits low top‑tier concentration—CR3 at c.14.8% and CR5 at c.22.2%—indicating fragmentation and substantial white space for roll‑up, capacity rationalization, and value‑chain consolidation strategies.
Competitive Landscape: Strategic Implications for 2026
The market map includes global steel majors, precision alloy specialists, and highly focused regional fabricators. Each archetype is playing a distinct game:
Welded Stainless Steel Tubing Market
- Precision and performance specialists (e.g., Plymouth Tube Company, Sandvik/Alleima) compete on tight tolerances, specialty grades, and aftermarket value for aerospace, medical, and heat‑exchanger OEMs. Their strategic advantage is IP, quality control, and premium yields.
- High‑alloy and energy-focused producers (e.g., Tubacex) serve demanding oil & gas and petrochemical specifications where metallurgical depth and alloy availability are paramount. These players weather commodity cycles by locking long‑term offtake and leveraging alloy inventories.
- Integrated industrial steel players (e.g., ArcelorMittal, Nippon Steel) bring scale, vertical integration, and broad distribution. Their strengths lie in cost competitiveness on commodity grades and in exploiting global project pipelines through existing client relationships.
- Regional and niche fabricators (e.g., Marcegaglia Steel, Bristol Metals/Brismet, Stainless Structurals, Indiana Tube, KVA Stainless) focus on service, custom profiles, quick turnarounds and compliance to local standards. Laser‑weld enabled firms and those certified to new ASTM profiles will increasingly capture architectural, structural and data‑center opportunities.
- Smaller precision makers (e.g., Fischer Group, YC Inox) and custom suppliers play important roles as specialist partners or tuck‑in targets for strategic acquirers.
Strategic takeaway: the combination of a fragmented supplier base and differentiated technology pathways creates both consolidation opportunities and niches where focused investment can yield outsized margins. Full company scorecards and capability heatmaps are included in the paid report.
Recent Events and What They Signal for 2026
- Standards compliance and trade show visibility from laser‑weld specialists highlights how certification plus targeted marketing accelerates adoption—an advantage for early‑certified players.
- Industry commentary noting dynamic growth in heat‑exchange replacement cycles confirms a durable demand pool for precision welded tubes.
- Raw‑material swings and regional manufacturing footprints underscore the strategic value of diversified sourcing and localized buffering strategies ahead of 2026 project cycles.
Actionable Strategic Recommendations for 2026
- Adopt a three‑track procurement posture: (1) short‑term hedging and indexed contracts for 2026, (2) mid‑term supplier diversification to de‑risk alloy exposure, and (3) strategic supplier partnerships with volume commitments to secure prioritized capacity.
- Prioritize selective capital investment in laser‑weld and automated inspection systems where the technology premium can be monetized (thermal management, EV battery systems, emission controls). Run a two‑year pilot to validate performance gains and commercialization cadence.
- Pursue targeted M&A and JV plays focused on: (a) laser‑weld technology providers and profile fabricators, and (b) regional service leaders that provide fast customer access and JIT logistics for critical end users.
- Institutionalize standards readiness: ensure product development pipelines incorporate ASTM requirements and that quality systems can produce traceable documentation for structural and pressure applications.
- Develop aftermarket and service revenue streams (assembly, coating, inventory management) to reduce exposure to commodity cycle swings and to deepen customer relationships.
- Embed scenario planning in capex decisions: use stress tests for feedstock price spikes, major new project rollouts, and accelerated EV demand shifts to size buffer capacity prudently.
Who Should Read This Report — And Why It Matters for 2026
- C‑suite leaders (CEOs, CFOs, COOs) evaluating strategic investment and portfolio reshaping.
- Procurement and supply chain heads seeking practical hedging frameworks and supplier scorecards.
- M&A teams and private equity assessing roll‑up opportunities in a fragmented market.
- Product and engineering leaders determining when and where to field laser‑welded and high‑alloy offerings.
- Project developers and EPCs who need certified supply sources for project delivery and warranty certainty.
PW Consulting’s study converts broad market signals into executable programs tailored to these stakeholders, with downloadable decision models that permit rapid scenario testing for 2026 actions.
Next Steps (How to Access the Full Intelligence)
This release provides a high‑confidence strategic view while preserving the granular subsegment forecasts, company revenue splits, and the interactive models that constitute the report’s commercial value. To access the full datasets, company scorecards, and the downloadable decision tools that will support 2026 planning, visit the PW Consulting report page. Our team also offers bespoke briefings and scenario workshops for executive teams preparing capital plans and M&A pipelines for 2026.
PW Consulting — translating market dynamics into clear, executable strategy for industrial leaders navigating the welded stainless steel tubing landscape.
For detailed analysis of this topic, please visit the official page: Welded Stainless Steel Tubing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com