

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cephalosporin Intermediates GCLE Market Set to Grow at a 5.4% CAGR, New 2025–2032 Insight Reveals

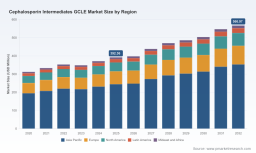
Cephalosporin Intermediates (GCLE) Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s new market research brief on Cephalosporin Intermediates GCLE delivers a focused, practice-oriented view designed to inform executive choices in 2026. The analysis synthesizes historical performance (2020–2025), a base-year diagnostic (2025), and a forward-looking forecast window (2026–2032). This preview highlights the strategic implications — from supply-chain fragility to competitive positioning — that will determine winners and losers as the GCLE landscape evolves. For full datasets, regional splits, and proprietary scorecards, refer to the complete report on our website.
Cephalosporin Intermediates GCLE Market
Executive snapshot — market direction and scale
The GCLE intermediate market has demonstrated resilience through the past half-decade. From a 2020 baseline the industry expanded steadily to reach approximately USD 392.36 Million in 2025. PW Consulting’s scenario-driven forecast models a compound annual growth rate (CAGR) of 5.4% across 2026–2032, producing an estimated market outcome near USD 567.0 Million by 2032 under our central case. These headline figures encapsulate demand tied to cephalosporin active pharmaceutical ingredient (API) production, shifts in grade mix (high-purity vs. standard), and structural supply-side dynamics that are relevant for procurement, capacity investment, and M&A planning in 2026.
Cephalosporin Intermediates GCLE Market
Why this report matters for 2026 corporate strategy
- Actionable signal amid structural concentration: Market concentration metrics indicate meaningful clustering among leading suppliers. That concentration amplifies the strategic value of supplier negotiation, alliance formation, and acquisition tactics in 2026.
- Raw-material dependency risk: Key inputs underpinning GCLE manufacture are sourced from a narrow geographic set of suppliers, creating asymmetric exposure to logistics, trade policy, and quality volatility — a top priority for procurement teams.
- Regulatory arbitrage and export policy: Recent policy windows allow specific import concessions for export-oriented antibiotic production in some jurisdictions. Capturing these regulatory advantages requires precise operational timing and compliance readiness.
- Margin recovery and premiumization: Growth is not uniform across the product-grade spectrum. High-purity grades are a critical driver of margin expansion and contract differentiation.
What’s inside the full PW Consulting report (practical components)
Our report is designed as a toolset for decision-makers, not just a descriptive summary. The deliverables include:
Cephalosporin Intermediates GCLE Market
- Scenario-based demand models (2026–2032) with sensitivity levers for price, capacity outages, and shipment-cost shocks.
- Supplier and asset scorecards combining capacity, quality certifications, geographic exposure, and counterparty risk.
- Regulatory impact map showing how authorization schemes and trade measures alter landed cost across export corridors.
- An operational playbook for raw-material risk mitigation: inventory policy designs, hedging tactics, and recommended contractual clauses.
- Capital deployment guidance: cost-to-build benchmarks for incremental GCLE capacity and payback simulations under conservative and aggressive uptake scenarios.
- Deal flow shortlist and diligence checklist tailored for acquisitive strategies targeting upstream intermediates and logistics nodes.
- Plant-level contamination and quality failure risk matrices with remediation timelines — practical for QA/QC and manufacturing heads.
Each component is supported by our proprietary database and verified market-sourcing interviews; however, detailed subsegment numbers and regional shares are intentionally gated to ensure this preview preserves the full report’s strategic value.
Competitive landscape — who moves markets and why
The GCLE supplier ecosystem reflects a mix of established multinational chemistry houses, specialized intermediate manufacturers, and regional listed players. From a strategic standpoint, three seller archetypes matter:
- IP-backed, scale incumbents: Firms that originated or own key β‑lactam intermediate processes and have integrated manufacturing footprints. They bring predictable quality, backward integration potential, and leverage in premium segments.
- Cost-advantaged regional manufacturers: Producers focused on scale, low-cost feedstocks, and a volume play for standard grades. Their strengths show up in price-sensitive contracts but expose purchasers to quality and concentration risks during supply shocks.
- Emerging contract-focused suppliers: Smaller producers and toll manufacturers that provide flexibility for API houses requiring rapid capacity adjustments or bespoke purity specifications.
Notable market participants profiled in the report include major Japanese specialty-chem players with dedicated β‑lactam lines; a cohort of listed Chinese manufacturers with significant GCLE activity; and focused Indian producers who are active partners in the cefixime and broader cephalosporin export value chain. Our competitive assessment evaluates each on capacity elasticity, geographic diversification, relationship capital with API customers, and exposure to raw-material sourcing constraints.
Supply-chain dynamics and critical risk vectors
Three structural dynamics dominate the GCLE supply picture and should shape 2026 priority decisions:
- Single-sourced raw material exposure: Penicillin‑G is the foundational feedstock for GCLE synthesis and, in practice, remains concentrated in a limited number of suppliers. That sourcing geometry limits rapid re-routing options during capacity disruptions and elevates inventory strategy to a strategic discipline rather than an operational afterthought.
- Export-oriented regulatory windows: Some jurisdictions have implemented advanced authorization measures that temporarily relax minimum import price restrictions for specific export uses. These measures can materially alter landed-cost economics — but exploiting them demands tight coordination between customs, production scheduling, and sales planning.
- Logistics inflation and bottlenecks: High international freight costs and container shortages periodically amplify landed cost and shrink the merit of distant-sourcing strategies. Firms that control or co-invest in logistics solutions secure a durable commercial edge.
Compounding these are technical challenges in several historic synthesis routes — uneven yields, impurity profiles that complicate downstream API synthesis, and quality variance across suppliers. These technical factors directly influence grade mix economics, regulatory approval timelines for APIs, and ultimately patient access chains.
Strategic imperatives for executives in 2026
Based on our assessment, PW Consulting recommends a prioritized set of moves for mid- to large-sized organizations operating in the GCLE value chain:
- Lock in multi-year, conditional supply contracts: Prioritize contracts that combine volume certainty with quality KPIs and clause-based price adjustments tied to documented input-cost indices.
- Invest selectively in high-purity capability: Build or acquire capacity that can deliver above-99% grades. Premiumization in this tier delivers asymmetric margin uplift and customer stickiness.
- De-risk penicillin-G dependence: Explore joint ventures upstream, targeted equity stakes in feedstock producers, or long-term offtake agreements with financial conditioning to secure throughput.
- Operationalize regulatory arbitrage: Align commercial calendars with advanced authorization windows and ensure compliance processes are audit-ready to access import concessions.
- Embed logistics resilience: Negotiate priority container capacity, invest in bonded warehousing closer to primary export ports, and model landed-cost shocks monthly.
- Prioritize bolt-on M&A where concentration creates rent opportunities: Small-to-medium acquisitions can yield integrated margins faster than greenfield builds in constrained supply scenarios.
- Make QA/QC investments non-negotiable: Failure to pass key impurity specification gates imposes multi-month revenue losses; remediation is costly and reputationally harmful.
How PW Consulting’s report supports execution
Our full deliverable translates the high-level imperatives above into executable workstreams: negotiation playbooks with contract text templates, an asset capex decision tree, an M&A due-diligence pack, and an interactive demand-supply model where clients can stress-test scenarios (logistics shocks, feedstock failure, price moves). Importantly, we provide a supplier risk heat map and a prioritized action list that a procurement or corporate development team can operationalize within 90–180 days.
To respect the “trailer” principle, this preview intentionally omits granular regional and application splits, as well as detailed supplier scorecard metrics. The complete report contains those specifics, including validated plant maps, contract examples, and a ranked list of acquisition targets with indicative valuation bands.
Next steps for leaders
If your 2026 strategy hinges on cephalosporin value capture — whether through securing cost-of-goods, enhancing product quality, or executing bolt-on capacity plays — this PW Consulting report provides the scenario-tested playbook you need. Access the full research package for detailed segmentation, supplier-level analytics, and the interactive models that translate market signals into boardroom-ready decisions.
For detailed analysis of this topic, please visit the official page: Cephalosporin Intermediates GCLE Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com