

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Semiconductor-Grade Tungsten Powder Market Set to Grow at 9.15% CAGR from 2026 to 2032

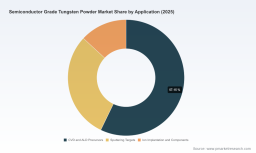
Semiconductor Grade Tungsten Powder Market: Strategic Imperatives for 2026 — PW Consulting Report Briefing
Executive Summary
PW Consulting’s new market intelligence brief on the Semiconductor Grade Tungsten Powder Market synthesizes an integrated view of supply, demand, pricing dynamics, regulatory shocks, and supplier strategy to inform corporate decisions in 2026. Anchored by a rigorous dataset spanning 2020–2025 and a detailed forecast through 2032, the report documents a clear multi-year acceleration: the market expanded from roughly USD 385 million in 2020 to about USD 565 million in 2025 and is modeled to exceed USD 1.04 billion by 2032, tracking a compound annual growth rate of 9.15% over the forecast horizon. This release outlines the strategic value of the analysis for C-suite executives, procurement leads, and M&A teams while intentionally withholding granular segment tables to encourage full report engagement.
Semiconductor Grade Tungsten Powder Market
Why This Matters for 2026 Decision-Makers
- Procurement resilience: Recent upstream disruptions have exposed single-point vulnerabilities in tungsten feedstocks. Procurement strategies calibrated to 2026 realities must balance spot exposure with structured long-term offtakes and diversified supplier panels.
- Capital allocation: Strong market growth and rising material intensity across advanced packaging and deposition processes create selective opportunities for capacity expansion, downstream integration, and targeted vertical investments.
- Regulatory and supply-chain risk management: Export controls and feedstock concentration have immediate pricing and availability consequences; companies that preemptively model regulatory scenarios will preserve product roadmaps and time-to-market for critical nodes.
Market Trajectory: Data-Driven Context (High Level)
Our historical sizing shows steady, demand-led expansion through 2020–2025, accelerating as semiconductor content per device climbs and advanced deposition and metallization techniques proliferate. The 2026–2032 forecast, derived from bottom-up modelling across technology adoption curves and wafer fab investment plans, produces a 9.15% CAGR for the period. This trajectory reflects both secular semiconductor demand and episodic supply-side shocks that have structurally tightened availability of semiconductor-grade tungsten powder.
Semiconductor Grade Tungsten Powder Market
Dynamics: Supply Shocks, Pricing, and Feedstock Stress
- Export controls and upstream feedstock volatility: In early 2025, restrictive export measures on key tungsten intermediates were introduced, resulting in material licensing requirements that materially reduced export volumes. The consequences cascaded through the supply chain and were a principal driver of a multi-fold rise in market prices for semiconductor-grade powders during 2025–2026.
- Feedstock scarcity and pricing spikes: The principal upstream intermediate, ammonium paratungstate (APT), saw unprecedented price swings in the period following tightened exports. Certain reporting windows registered several-hundred-percent jumps, forcing downstream buyers to reprice product roadmaps and re-evaluate procurement contracts.
- Near-term market tightness vs. structural growth: While short-term tightness is primarily supply-driven, structural demand from advanced node manufacturing, 3D integration, and specialty deposition techniques (CVD/ALD and sputtering use-cases) underpins the medium-term growth path.
Competitive Landscape: Who Moves Markets
The semiconductor-grade tungsten powder market is concentrated and technical barriers to entry are meaningful. The competitive field combines legacy refractory metals specialists, integrated producers, and regionally anchored manufacturers. Our concentration analysis indicates a compact top tier, with the leading three and five suppliers controlling a substantial portion of market throughput—an important consideration when evaluating counterparty risk and bargaining power.
Semiconductor Grade Tungsten Powder Market
- Buffalo Tungsten Inc. (Depew, NY) — A specialized high-purity tungsten metal powder producer with strengths in niche, high-reliability applications. Its focus on quality and traceability positions it well for semiconductor supply chains that emphasize material provenance.
- Global Tungsten & Powders Corp. (Towanda, PA) — A western producer with multi-site production capability. Recent product introductions tailored for semiconductor applications signal an emphasis on differentiated chemistries and tighter tolerances for electronic-grade usage.
- Elmet Technologies LLC (Lewiston, ME) — Vertically integrated production from oxide to powder, offering control over impurity profiles and the flexibility to meet bespoke customer specifications.
- H.C. Starck Tungsten Powders (Goslar, Germany / Mitsubishi Materials) — A supplier emphasizing recycling and closed-loop material strategies; recently reported a notable recycling rate that serves both sustainability goals and feedstock security.
- Kennametal Inc., Edgetech Industries, AEM Metal, Stanford Advanced Materials, Atlantic Equipment Engineers, Japan New Metals, and major Chinese producers — Each brings distinct capabilities across particle engineering, spherical powder forms, and scale production. Collectively, these firms form a supply map with different technical specializations and geopolitical footprints.
Recent corporate activity reinforces market shifts: a product launch focused explicitly on semiconductor-grade powders by a major western supplier and operational disclosures on recycling rates by a leading manufacturer are symptomatic of a broader pivot—suppliers are investing in both technical differentiation and resilience-focused strategies.
Report Contents: Practical, Actionable Deliverables
PW Consulting’s full report is built for executables: it moves beyond narrative to deliver playbooks and decision tools you can use in 2026. Key inclusions are:
- Methodology and transparent assumptions behind the 2026–2032 forecast and scenario variants.
- Supply chain heat maps and supplier scorecards that quantify technical capabilities, geopolitical exposure, and capacity elasticity.
- Procurement playbooks with negotiation levers: contract structures, hedging approaches, and buyer-supplier partnership models tailored to tungsten powder markets.
- Pricing model that decomposes input cost drivers (including APT trajectories), conversion yields, and margin pass-through mechanics under alternative regulatory scenarios.
- Technology tracker that maps particle-level innovations, purity regimes, and deposition compatibility to end-market adoption timelines.
- M&A and investment thesis annex: target profiles, valuation sensitivities, and integration risk checklists.
- Risk matrix and regulatory scenario planning: probability-weighted impacts of export policy shifts, feedstock embargoes, and substitution risks.
Strategic Recommendations for 2026
Our analysis translates into eight priority actions for executives planning around the 2026 inflection point:
- Formalize multi-tiered sourcing strategies: Combine secure long-term allocations with tactical spot exposure; prioritize suppliers with demonstrable supply-chain traceability and redundant processing locations.
- Invest in feedstock flexibility: Where feasible, retrofit or design process lines to accept alternate tungsten chemistries or particle morphologies to reduce single-source dependency.
- Capitalize on supplier consolidation: Use the market’s concentrated supplier base to negotiate performance-based agreements, but recognize the counterparty pricing power when appetite for capacity is tight.
- Prioritize technical partnerships: Co-develop powder grades or particle treatments that improve yield or compatibility with advanced deposition methods—this can create defensible differentiation and thinner cost pass-throughs.
- Embed regulatory scenario planning into product roadmaps: Shorten decision cycles for qualification runs and maintain modular approval paths to mitigate sudden material substitutions.
- Explore recycled-content strategies: Recycled tungsten is emerging as both a supply buffer and an ESG lever; partnership opportunities exist with operators reporting high recycling rates.
- Gate M&A decisions with supply-chain analytics: Targets should be evaluated not only on EBITDA accretion but also on feedstock control, facility footprint, and qualification backlog for semiconductor customers.
- Monitor pricing corridors: Apply dynamic cost-pass-through models in customer contracts where possible to preserve margins during elevated volatility windows.
How We Built the View
The forecast uses a hybrid approach combining bottom-up adoption curves for semiconductor deposition and metallization processes, detailed supplier capacity modelling, and scenario-driven stress tests of supply chain interruption events. We triangulated industry data, proprietary supplier interviews, and third-party commodity pricing intelligence to create a defensible, decision-focused output.
Conclusion: Navigating a Strategic Inflection
The semiconductor-grade tungsten powder market sits at a strategic inflection: structural demand growth is meeting episodic supply-side constraints and tighter regulatory oversight. For companies dependent on these materials, 2026 is a year to translate scenario planning into executed strategies—whether through procurement playbooks, targeted investments, supplier partnerships, or selective M&A. PW Consulting’s comprehensive report provides the data, frameworks, and executable recommendations to make those choices with confidence.
Next Steps
This briefing is intended as an executive prelude. The full PW Consulting report contains the granular segmentation, supplier scorecards, and actionable playbooks referenced above. For access to the complete intelligence package, scenario workbooks, and bespoke advisory engagements tailored to your organization’s role in the tungsten powder value chain, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Semiconductor Grade Tungsten Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com