

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
PW Consulting: Electrically Heated Windshield Market for EVs to Reach USD 3,043.51 Million by 2032 at a 14.12% CAGR — Asia Pacific Leads with USD 526.44M
By pmarketresearch, 2026-07-15
Electrically Heated Windshields for EVs: A Strategic Preview for 2026 Decision-Making
PW Consulting’s new market study on Electrically Heated Windshields for EVs presents a timely, actionable intelligence package aimed at executives who must convert winter-performance innovation into durable commercial advantage. The global market for electrically heated windshields has moved from niche technology to a strategic EV systems component: our model shows the market more than doubled between 2020 and 2025, reaching roughly USD 1.2 billion (Million USD) in 2025, and is forecast to grow at a compound annual growth rate (CAGR) of 14.12% across the 2026–2032 horizon to exceed USD 3.0 billion by 2032.
Electrically Heated Windshield for EV Market
Why this matters for 2026 planning
-
Energy efficiency now equals safety and comfort in EV purchasing criteria. Electrically heated windshields materially reduce HVAC load during cold-start conditions—an important lever to protect real-world driving range.
Electrically Heated Windshield for EV Market -
Electrified vehicle electrical architectures (notably the growing adoption of 48‑volt subsystems) are lowering the integration barrier for higher-power glass-based heating solutions. This is shifting heated windshields from nice-to-have luxury options into core thermal management strategy for mainstream EV platforms.
Electrically Heated Windshield for EV Market -
Market concentration is meaningful: the sector exhibits mid-to-high supplier concentration, underscoring supplier negotiation power, technology differentiation stakes, and M&A interest among glass OEMs, Tier‑1s, and new tech entrants.
Snapshot: What our numbers tell you (high-level)
Historical demand doubled in five years, driven by BEV adoption, colder-market feature expectations, and OEM-led comfort-safety differentiation. The forecast trajectory embedded in our model captures accelerating adoption as OEM platforms standardize higher-voltage architectures and as more efficient heating technologies commercialize. These macro dynamics create a multi-year runway for suppliers and OEMs, but success will hinge on integration costs, energy trade-offs, certification timeframes, and component supply resilience.
Report value: practical outputs for corporate decision-makers
-
Executive Decision Playbook: scenario-based recommendations for OEMs, Tier‑1s and suppliers to prioritize product investments, specification timing, and partnership models through 2026.
-
Market Model & Sensitivity Toolkit: a transparent forecasting engine (2026–2032) with configurable levers—adoption curves, power-architecture mix, and price erosion—that executives can use to stress-test product and pricing strategies.
-
Commercial Benchmarking: supplier scorecards that combine technical differentiation, supply capacity, certification track record, cost position, and OEM relationships—designed to support sourcing and co-development decisions.
-
Integration & Systems Guide: engineering-level checklists for electrical architecture compatibility (including 48‑volt adoption), ADAS camera/window optics considerations, and NVH/lamination trade-offs to accelerate time-to-vehicle.
-
Raw Material & Supply Risk Matrix: procurement playbooks and hedging strategies for PVB/PVA and specialty glass inputs, including scenario planning for observed price volatility and export headwinds.
-
M&A and Partnership Roadmap: valuation frameworks for acquiring or partnering with specialist technology firms (e.g., pulsed electro-thermal providers), with deal structures to protect IP and scale manufacturing rapidly.
Competitive landscape: who moves the market
Our competitive analysis blends product-level engineering differentiation with go-to-market posture. Key incumbents and challengers typify three strategic archetypes: traditional glass OEMs evolving coatings and wire embedding; specialist thermal-tech startups commercializing disruptive low-energy approaches; and OEMs internalizing glass heating to protect system-level range.
-
AGC Inc. (AGC Automotive) — plays to its glass‑OEM strengths with both conductive coating (invisible) and ultra‑fine wire approaches, positioning solutions explicitly for EV thermal management. Its dual-technology portfolio reduces client integration friction and supports multiple platform strategies.
-
Pilkington (NSG Group) — leverages established wire‑heated windshield competency and ADAS integration experience. Their proposition is speed-to-defog/defrost with compatibility for advanced driver assistance sensors—a clear value for OEMs targeting cold-climate reliability.
-
Fuyao Glass — focuses on cost-competitive manufacturing and targeted heating zones (wiper, sensor, camera) through tungsten micro-wires laminated within PVB. This zone-targeting is relevant where cost and selective functionality trump full-surface heating.
-
Saint‑Gobain Sekurit — differentiates via invisible conductive coatings (ClimaCoat) combined with heat‑reflective glass formulations, positioning for OEMs seeking integrated all‑weather performance while maintaining optical clarity for ADAS cameras.
-
Betterfrost Technologies — represents a category-defining specialist. Their pulsed electro‑thermal deicing (PETD) delivers fast clear‑times with demonstrable energy reduction versus HVAC defrost. Recent 2026 testing shows commercial traction with OEMs and Tier‑1s; this modality is attracting attention where rapid-clear times and low energy draw are prioritized.
-
Hyundai Motor Group / Genesis — as a technology adopter and developer, Genesis’ public demonstrations of a 48‑volt metal‑coated heated glass on electrified models signal a potent integrator strategy: OEMs can capture system-level energy savings by pairing glass heating with platform electrical architectures.
Collectively, these players illustrate a market in which competitive advantage will come from multi-technology roadmaps, high-quality lamination and coating expertise, fast qualification cycles for ADAS compatibility, and supply footprint close to major vehicle assembly centers.
Supply chain, raw materials, and regulatory headwinds
-
Raw material dynamics: PVB interlayers and PVA inputs remain central to lamination and wire embedding. Recent price movements and export dynamics require procurement contingency planning; small unit-cost shifts can materially change glass BOM economics at scale.
-
Certification and optical safety: electrically heated glazing must satisfy automotive glazing standards (e.g., ECE R43, FMVSS 205) while preserving ADAS camera performance. Plan for longer qualification paths where new coatings or heating topologies alter optical properties.
-
Electrical architecture fit: the rise of 48‑volt subsystems meaningfully improves the energy and integration case for higher‑power glass heaters. OEM platform strategy decisions in 2026 should explicitly include heated‑glass power budgets and harmonize with HVAC, battery thermal management, and vehicle energy management software.
Technology trajectories and trade-offs
Two technical families dominate: embedded fine‑wire heating and invisible conductive coatings; a third—pulsed electro‑thermal deicing (PETD)—is emerging as a disruptive energy-efficient alternative. Selection drivers are clear:
-
Fine wires: rapid, evenly distributed heating and proven ADAS compatibility when properly engineered; potential compromises in optical uniformity if not ultra‑fine.
-
Conductive coatings: invisible aesthetics and improved optical continuity for cameras, with power and coating durability trade-offs that require rigorous environmental testing.
-
PETD: very low steady-state energy consumption and fast clear times, but system-level integration (control electronics, pulse drivers) and long-term reliability data are still maturing.
Our report includes comparative P&L-level modeling of these approaches, showing where lifetime energy savings and customer-experience premiums offset higher unit costs.
Implications for corporate strategy in 2026
-
OEMs should codify heated‑glass strategy in platform value engineering: decide whether to insource, co-develop, or buy from established glass OEMs based on volume forecasts and ADAS requirements.
-
Glass OEMs and Tier‑1s should converge product roadmaps with electrical architecture and ADAS teams to shorten qualification cycles—time-to-spec will determine early-adopter economics.
-
Material suppliers and contract manufacturers must build price-risk mitigation into long-term supply agreements for PVB/PVA and specialty coatings.
-
Investors and M&A teams should evaluate specialists—particularly PETD providers—for bolt-on acquisitions to capture energy-efficiency differentiation, but structure earn-outs tied to OEM qualification milestones.
What’s in the full PW Consulting report (practical table of contents)
-
1) Executive summary & strategic recommendations
-
2) Market sizing & forecast model (2020–2032) with downloadable model
-
3) Segmentation analysis (region, technology, vehicle type) and adoption scenarios
-
4) Supplier benchmarking and capability heatmaps
-
5) Detailed technical annex: coating chemistries, wire metallurgy, lamination methods, and testing protocols
-
6) Procurement and raw-material risk playbooks
-
7) Integration checklists for OEM systems engineering
-
8) M&A & commercial partnership guidance with valuation templates
Note: this preview intentionally omits the granular regional, technology, and vehicle-type revenue splits that form the heart of the model. Those segment-level outputs—and supporting appendices with supplier price decks, BOM scenarios, and regional adoption curves—are available in the full report and the downloadable forecast tool.
Next steps for executives
-
Download the forecast model and run platform-specific scenarios (we provide templates keyed to battery pack size, 12/48‑volt subsystem availability, and expected cold‑climate penetration).
-
Initiate supplier dialogues using our scorecards to accelerate qualification with those that align to your integration roadmap.
-
Design pilot programs that combine one glass OEM and one PETD specialist to evaluate trade-offs across range preservation, user experience, and unit-cost outcomes within your 2026 program timelines.
PW Consulting’s Electrically Heated Windshield for EVs report is designed as a strategic instrument for 2026 planning cycles—giving you the market model, technical comparators, and commercial playbooks needed to convert winter-performance innovation into durable product and financial advantage. For access to the full dataset, supplier-level appendices, and the downloadable forecast workbook, please visit our report landing page.
For detailed analysis of this topic, please visit the official page: Electrically Heated Windshield for EV Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HDH Titanium Powder Market to Rise from USD 524.5 Million in 2025 to USD 853.3 Million by 2032 at a 7.2% CAGR
By pmarketresearch, 2026-07-15
HDH Titanium Powder Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive snapshot
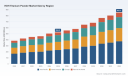
PW Consulting’s HDH Titanium Powder Market report (base year 2025) delivers a focused, actionable view of a market that has transitioned from niche feedstock supply to a strategic industrial commodity. Our modelling shows the global HDH titanium powder market reached approximately USD 524.5 Million in 2025 and — under a set of consensus demand and supply assumptions — is projected to grow at a compound annual growth rate (CAGR) of 7.2% through the 2026–2032 forecast period, reaching roughly USD 853.3 Million by 2032. The report couples a granular view of dynamics with transaction-grade tools to inform 2026 capital allocation, procurement, and M&A choices.
HDH Titanium Powder Market
Why this matters for 2026 decision-makers
- Supply security is now strategic: HDH titanium powder remains feedstock-dependent, with production ultimately tied to titanium sponge availability and the hydrogenation–dehydrogenation (HDH) processing route. Policy and geopolitical shifts in sponge-producing regions elevate the value of resilient sourcing strategies.
- Cost–performance trade-offs are reshaping choices: HDH powders offer a cost-competitive alternative to spherical gas-atomized powders for many powder metallurgy, metal injection molding, and thermal spray applications. Procurement teams must weigh powder morphology, downstream processing costs, and end-use specification risks — not only headline price per kilogram.
- Regulatory and standards risk is non-trivial for critical end-markets: Medical and aerospace buyers face strict standards (e.g., ISO 23301 and relevant ASTM specifications). Certification and traceability are decisive contract terms in 2026.
- Market structure enables targeted plays: Concentration metrics show a moderately concentrated supplier market (CR3 ≈ 42.5%, CR5 ≈ 58.3%), which creates room for both incumbent scale plays and focused niche entrants to capture differentiated margins.
What the PW Consulting HDH Titanium Powder Market report contains
- Comprehensive market sizing and forecast (2020–2032): Historical reconciliation, driver-based forecasts, scenario workstreams, and sensitivity modelling to inform 2026 budgeting and capital plans.
- Methodology and data pack: Transparent assumptions, source laddering, confidence bands, and an Excel model for custom scenario analysis and integration into client financial models.
- Value-chain mapping and cost stack analysis: From sponge procurement through hydrogenation, crushing, dehydrogenation, sieving, and post-processing, with unit-cost drivers and break-even maps for vertical integration decisions.
- Pricing deck and benchmark comparators: Market price ranges by grade and particle size, comparative economics versus gas-atomized powders, and margin waterfall for typical producers and consumers.
- Demand-by-application playbooks: End-market demand drivers (aerospace, medical implants, additive manufacturing, powder metallurgy, coatings), use-case risk matrices, and adoption curves — with executable commercial tactics for suppliers and buyers.
- Supplier intelligence and competitive mapping: Transaction-ready profiles for incumbent producers, capacity maps, capability heatmaps, and a M&A watchlist.
- Regulatory, geopolitical and raw-material risk assessment: Scenario-based impact analysis of export controls, tariffs, and domestic content rules on sourcing and pricing.
- Commercial diligence toolkit: Supplier scorecards, sampling and testing checklists (oxygen/hydrogen content, PSD, morphology), contract templates, and quality audit playbooks tailored to 2026 procurement cycles.
Note: the report intentionally aggregates sensitive subsegment tables and supplier capacity schedules behind our data room. This executive briefing highlights key insights while directing practitioners to the full dataset for transaction-level decisions.
HDH Titanium Powder Market
Competitive landscape — what to watch in 2026
The HDH market is shaped by diversified players: legacy refiners and sponge integrators in East Asia; specialized powder manufacturers in North America and Europe; and high-volume producers from China that serve global industrial chains. Strategic moves in 2025–2026 underscore several themes:
HDH Titanium Powder Market
- Vertical integration and consolidation: Recent corporates actions — including a share exchange that will bring a major Japanese HDH producer into a larger metals group effective mid-2026 — illustrate a push toward upstream control of feedstock and enhanced product portfolios. Expect further consolidation in response to supply-security imperatives.
- Long-term offtakes and aerospace tie-ups: Expanded long-term agreements between titanium material suppliers and major OEMs reinforce how aerospace demand secures higher-value, certified flows of powder and sheet. These contracts raise the hurdle for new entrants seeking aerospace approvals.
- Quality and certification as market access gates: Suppliers that secure aerospace and medical certifications, and demonstrate low-impurity control, are capturing premium segments. Independent quality credentials are becoming determinative in supplier selection.
- Chinese producers remain pivotal: Large producers based in China continue to supply significant volume to global markets, offering broad PSD options and competitive pricing. Buyers must balance short-term cost advantages versus medium-term geopolitical and regulatory risk.
- Specialized Western suppliers: Select firms in North America and Europe focus on higher-spec alloys and engineered powders tailored to medical implants and additive manufacturing, positioning themselves on quality and service rather than commodity pricing.
Supply-chain risks and mitigation playbook for 2026
- Feedstock concentration: Titanium sponge production concentration makes feedstock strategies (dual-sourcing, local inventory pools, backward integration) essential. Commodity hedging alone is insufficient given non fungible specifications and certification requirements.
- Quality drift: Control of oxygen and hydrogen content is paramount for medical and aerospace. Buyers should establish inline testing, third-party validation, and contractual acceptance criteria tied to lot-based traceability.
- Geopolitical contingencies: Prepare scenario playbooks for export restrictions, tariffs, and domestic content mandates. Scenarios should include time-to-fill windows, alternate routing, and contractor substitution playbooks.
- Commercial levers: Structured, multi-year offtake agreements with performance-based pricing, capacity reservation clauses, and ramp schedules protect OEMs while providing revenue visibility to producers making capital investments.
Commercial implications & go-to-market strategies
- For suppliers: Prioritize certified product lines (medical/aerospace), augment quality management systems, and consider small-scale atomization or surface modification services to capture higher-value AM markets. Geographic diversification of customers mitigates concentration risk.
- For buyers: Rebalance procurement from lowest-cost spot buys to strategic blends of contracted volumes plus validated spot sourcing. Invest in incoming inspection capabilities and create supplier development programs to align material specifications with in-house processing constraints.
- For investors and M&A teams: Focus on targets with defensible certifications, proven low-impurity processes, and flexible particle-size distribution capabilities. The mid-market remains ripe for bolt-on plays that extend value chains into pre-alloying, blending, or downstream finishing.
How to use this report in 2026 planning
- Integrate our forecast scenarios directly into capex and inventory modelling to quantify upside and downside from feedstock disruptions.
- Use the supplier scorecards and audit templates to re-run procurement RFIs and shorten supplier qualification lead times.
- Employ our price decks and cost stacks to stress-test supplier bids and structure multi-year contracts with indexed pricing and quality KPIs.
- Apply the M&A screening checklist to prioritize acquisition targets that deliver immediate capability upgrades (certifications, specialty alloys, PSD flexibility).
Access and next steps
PW Consulting’s HDH Titanium Powder Market report is designed as an operational decision tool for 2026. It combines a validated macro forecast with drill-down analytics, supplier intelligence, and executable playbooks. For access to the full dataset — including detailed segmentation tables, supplier capacity schedules, price decks, and the interactive Excel model — please visit our report page or contact PW Consulting’s industry team to arrange a briefing and data-room access. The executive briefing above provides the strategic framing; the licensed report supplies the transaction-ready detail you will need to act this year.
For detailed analysis of this topic, please visit the official page: HDH Titanium Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PCM Metal Sheet Market Set for Steady Expansion — 5.15% CAGR Through 2032, Led by Asia‑Pacific Demand
By pmarketresearch, 2026-07-15
PCM Metal Sheet Market 2026: Strategic Intelligence for Decision Makers
Executive snapshot
The pre‑coated metal (PCM) sheet market has entered a phase where disciplined industrial strategy, granular supplier intelligence, and nimble cost‑management will determine winners. Our updated market model shows the industry expanding from roughly USD 3.75 billion in 2020 to about USD 4.85 billion in 2025 (base year), with a mid‑single‑digit trajectory thereafter. PW Consulting’s forecast through 2032 projects a compound annual growth rate (CAGR) of 5.15%, taking the market to an estimated USD 6.89 billion by the end of the decade. For 2026 corporate planning, these headline dynamics — steady demand growth coupled with episodic input‑cost volatility — create a narrow window for strategy choices that materially affect margin and market position.
PCM Metal Sheet Market
Why this report matters for 2026 planning
- Actionable timing: We align market forecasts to procurement cycles, new product development timelines, and capex review windows commonly used by appliance OEMs, construction product manufacturers, and large fabricators.
- Decision economics: The report converts market growth assumptions into supplier capacity scenarios, price sensitivity models, and profitability break‑points so senior leaders can test “what‑if” options without building bespoke analytics teams.
- Risk‑to‑opportunity mapping: Beyond headline growth, the analysis translates raw material shocks, regulatory constraints, and service differentiators into prioritized mitigation and capture plays for commercial, sourcing, and R&D leaders.
Report contents — practical, deployable modules
- Executive framework and five strategic pathways for market leaders and challenger brands.
- Market sizing and trend lines (2020–2025 historical, 2026–2032 forecast) with scenario overlays and sensitivity to raw material price indices.
- Supply‑side diagnostics: capacity maps, line‑level capabilities (coil coating, embossing, film lamination), and supplier readiness for specialty coatings and small‑lot color matching.
- Commercial playbooks: contracting templates, indexation clauses keyed to cold‑rolled and hot‑rolled coil benchmarks, and customer segmentation for premium vs. commoditized PCM.
- Regulatory and sustainability module: compliance checklists (ISO 9001, RoHS) and EPD/LCAs required by large appliance OEMs and public infrastructure tenders.
- Supplier scorecards and deal structuring guidance — quality, lead time, price, and environmental compliance are weighted and benchmarked.
- Competitive landscape and M&A heat map with tactical recommendations for alliances, bolt‑on acquisitions, and JV structures.
- Operational excellence playbook: recommended takt times, quality checkpoints (e.g., ΔE color tolerances, salt‑spray resistance thresholds), and digitization priorities for shopfloor traceability.
- Appendices: downloadable model, data tables, and an annotated list of primary data sources and validation checks.
Market dynamics that should shape 2026 choices
- Input cost pressure: The market is sensitive to base‑metal spreads and processing differentials. Current industry indicators show a persistent premium on cold‑rolled coil versus hot‑rolled coil, reflecting the extra processing required for PCM substrates; meanwhile regional HRC price movements in early 2026 have displaced short‑term margin assumptions for many suppliers. Companies that revise contract terms to include transparent, auditable indexation mechanisms reduce margin leakage and preserve supply relationships.
- Demand complexion: End‑market pull remains anchored in household appliances and construction finishes, while transportation and specialty industrial segments provide episodic upside. Winning propositions will marry material performance (corrosion resistance, long‑life warranties) with service elements such as just‑in‑time coil replenishment and precise color matching.
- Compliance and procurement hygiene: ISO 9001 and environmental constraints such as RoHS are table stakes; leading buyers now vet third‑party test reports (SGS, BV, Intertek) and expect suppliers to publish EPDs or equivalent lifecycle disclosures when bidding for large programs.
- Concentration and competitive tension: The market exhibits moderate consolidation among top players. A compact competitive core controls a meaningful share of capacity, placing a premium on commercial sophistication for mid‑market buyers looking to diversify risk without sacrificing price.
Competitive landscape — what top players reveal about strategy
The sector combines global steel majors, regional champions, and specialist PCM producers. Each archetype signals a distinct strategic playbook for 2026:
PCM Metal Sheet Market
- Global integrated producers (examples include long‑standing steel majors): leverage vertical integration to defend margin through upstream supply security, offering bundled guarantees (coating warranties, long‑tenor supply contracts) that appeal to large OEMs seeking single‑source simplicity.
- Regional system integrators and niche specialists: firms with focused production of pre‑painted coils and value‑added services (tight ΔE color matching, extended salt‑spray resistance) win business where technical fit and service responsiveness trump lowest price.
- Commercial differentiators: several suppliers are investing in coatings development (e.g., antiviral surfaces) and cataloged product families to lock in specification leadership with appliance OEMs and building product manufacturers.
Key operational signals to watch from publicly visible players: capacity announcements and published performance records (for example, a supplier reporting zero rust claims across a large shipment cohort), catalog expansions that imply new color or film portfolios, and facility investments tied to coil center processing and embossing capabilities. These moves are strong leading indicators of where competition for premium segments will intensify.
PCM Metal Sheet Market
Strategic implications and recommended moves for 2026
- Procurement: Move from annual RFQs to multi‑year, index‑linked frameworks that incorporate transparent cost pass‑through for coil indices and processing differentials. Embed quality KPIs (color delta, salt‑spray hours) with financial penalties and reward gates tied to continuous improvement.
- Supply diversification: Adopt a tiered supplier strategy — retain strategic capacity with integrated majors while engaging regional specialists for innovation and service uplift. Scenario‑based sourcing playbooks in the report map how to rebalance exposure across supplier archetypes without disrupting production.
- Product strategy: For OEMs, specify performance bands (e.g., corrosion warranty, aesthetic durability) rather than commodity grades; this allows suppliers to propose differentiated coating systems and supports premium pricing models.
- Operational resilience: Invest in inbound visibility (real‑time shipment tracking, quality imaging) and co‑design small‑lot production capabilities to reduce inventory drag and accelerate new SKUs from pilot to scale.
- Sustainability and compliance: Prioritize suppliers with published EPDs and demonstrable third‑party certification. Early alignment with green procurement criteria will be a competitive advantage in public tenders and OEM supplier scorecards.
- M&A and partnerships: The report identifies niches where bolt‑on acquisitions (local coil centers, film‑lamination specialists) deliver step‑change capabilities quickly; alternatively, use JVs to access regional logistics benefits while sharing capex.
Data integrity & what we deliberately withhold here
To preserve the value of the full research package and to comply with our “trailer” principle for public communications, this release presents sector‑level growth and concentration metrics while omitting detailed segment splits, regional percentages, and supplier revenue lines. The full report contains the granular datasets that senior decision‑makers use in sourcing negotiations — downloadable supplier scorecards, regional demand curves, substrate‑by‑application matrices, and a live Excel model calibrated to multiple pricing scenarios. Clients and interested parties are invited to access the complete package to operationalize these insights.
Recent market signals to monitor in 1H–2H 2026
- Supplier performance disclosures (e.g., reported rust‑free shipment cohorts, expanded catalogs) that validate quality claims and reduce due diligence friction.
- Facility communications and community engagement from regional producers, which often presage capacity availability or local hiring that will impact lead times.
- Raw material index movements and substrate spreads; a sustained premium for cold‑rolled coil versus hot‑rolled coil will change the relative economics of PCM substrates and co‑determine pricing strategies.
- Regulatory tender language shifts favoring environmental declarations and lifecycle metrics.
Next steps for leaders
- Download the full PCM Metal Sheet Market report and Excel model to run procurement scenarios against your 2026 budgets and capex plans.
- Initiate a rapid supplier risk audit using our scorecard template (included with the report) to identify high‑risk single‑source dependencies and validate alternative qualified suppliers within 60 days.
- Convene a cross‑functional war‑room (procurement, engineering, quality, regulatory) to adopt the tactical playbook and contract templates we provide — this reduces negotiation cycles and locks in performance parameters before cost swings intensify.
PW Consulting’s PCM Metal Sheet Market report is crafted for leaders who need both the macro line of sight (market size and 2026 trajectory) and the micro operational tools to convert insight into commercial advantage. For access to the full datasets, supplier scorecards, and downloadable models, visit our report page and contact our strategy team for a briefing tailored to your business priorities.
For detailed analysis of this topic, please visit the official page: PCM Metal Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Isopropyl Biphenyl Heat Transfer Fluid Market to Grow from USD 238.5 Million in 2025 to USD 346.61 Million by 2032 at a 5.48% CAGR
By pmarketresearch, 2026-07-15
Isopropyl Biphenyl Heat Transfer Fluid Market: Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s latest market study on Isopropyl Biphenyl (IPB) heat transfer fluids offers a concise, actionable map for commercial leaders, procurement heads, and technology strategists preparing plans for 2026. The study synthesizes historical performance, forward-looking scenario work, supplier intelligence, and regulatory context into a playbook designed to reduce execution risk while preserving optionality — a necessary balance as the market moves from niche industrial use toward broader adoption in decarbonization and advanced thermal management applications.
Isopropyl Biphenyl Heat Transfer Fluid Market
Market trajectory: what the numbers say (and what they don’t)
Over the historical window we examined (2020–2025), the IPB heat transfer fluid market demonstrated consistent expansion, growing from a clearly smaller base to an estimated USD 238.5 Million in 2025. Our baseline forecast shows the market entering 2026 with continued momentum, and a compound annual growth rate (CAGR) of approximately 5.48% over the 2026–2032 forecast horizon. By the end of the forecast period the market is projected to be materially larger, reflecting steady industrial demand, incremental displacement of legacy chemistries, and new end‑use opportunities that emerge from energy transition programs.
Isopropyl Biphenyl Heat Transfer Fluid Market
These headline figures are purposefully presented at a market level to show directionality and scale. PW Consulting’s proprietary models further decompose growth drivers into technical, regulatory, and commercial vectors — but in keeping with the “trailer” principle of this release, core segment-level datapoints and detailed regional/application shares are reserved for the full report.
Isopropyl Biphenyl Heat Transfer Fluid Market
Why 2026 is a hinge year for strategic choices
- Procurement posture matters: The combination of steady demand growth and concentrated supply dynamics means buyers will face meaningful supplier‑selection tradeoffs in 2026. Our market concentration analysis highlights a marketplace where a handful of suppliers control most of the commercially available volumes, elevating the importance of contractual terms, contingency capacity, and qualification pipelines.
- Raw material and production footprints are decisive: Producers with dedicated IPB production capacity gain a durable advantage in lead time and price resilience. For example, one major manufacturer maintains an annual dedicated production capacity in the low thousands of tonnes for isopropyl biphenyl, a practical fact that shapes sourcing strategies and potential partnership models.
- Regulatory momentum favors IPB over legacy PCBs: The historical phase-out of polychlorinated biphenyls (PCBs) has created an industry legacy that continues to influence buyer confidence, compliance requirements, and insurance economics. IPB-based fluids are widely adopted as alternatives in many applications, which simplifies entry for conservative buyers but places a premium on demonstrable purity and long-term stability data.
- New end-use vectors will drive incremental demand: Beyond traditional chemical and polyester processing, thermal energy recovery, advanced electronics cooling, and large-scale concentrated solar power projects are emerging as meaningful growth pockets. Each of these use cases imposes distinct technical and supply constraints that the full report models in scenario form.
Report contents: practical deliverables for the 2026 agenda
PW Consulting designed this study as a business tool, not just an academic exercise. Key practical outputs included in the full report are:
- Verified market sizing (historical and forecast), including sensitivity runs tied to energy policy and capital deployment assumptions.
- Commercial decision frameworks: supplier selection scorecards, total cost of ownership templates, and contract clauses to protect buyers against supply shocks and specification drift.
- Technical evaluation matrix comparing thermal stability, low‑temperature operability, and compatibility issues for typical system architectures.
- Supply‑chain heat map identifying single‑sourced materials, flexible manufacturing nodes, and near‑term expansion opportunities.
- Regulatory and safety roadmap summarizing legacy PCB phase‑out implications, testing protocols, and expected compliance milestones through 2032.
- M&A and partnership scouting: a shortlist of technology and capacity targets for acquirers seeking quick market entry or downstream integration.
- Operational playbooks for plant trials, pilot-to-scale adoption, and warranty negotiation templates aligned to fluid specification risk.
Competitive landscape: who matters and why
The competitive field is relatively concentrated and features a mix of global chemical majors and specialized regional suppliers. Several firms stand out for their differentiated positions:
- Eastman Chemical Company (Kingsport, TN, USA; https://www.eastman.com) — A global supplier with a widely recognized branded product positioned for low‑pressure liquid systems. Eastman’s strengths are global availability, technical documentation, and established customer support pathways for industrial end users.
- Nippon Chemical Texas Inc. (NCTI) (Texas, USA; https://nctius.com) — Focused on high‑temperature and cold‑start robustness, with formulations designed for extremes of service temperature and for industrial processes requiring wide operability windows. NCTI’s engineering focus supports customers with demanding thermal cycles.
- Dalian Richfortune Chemicals (Dalian, China; http://www.richfortunechem.com) — A cost‑competitive supplier with project experience in utility‑scale concentrated solar power (CSP) and other industrial applications; leverages regional manufacturing scale to support long‑term contracts for large projects.
- Jiangsu Zhongneng Chemical Technology (Lianyungang, China; https://www.dynovacn.com) — Provides a portfolio of biphenyl derivatives and IPB‑based products covering broad temperature ranges, often chosen for compatibility and formulation flexibility.
- Manto Chemistry (Jiangsu Manto Chemistry Co., Ltd.) (China; https://mantochem.com) — Noteworthy for maintaining dedicated annual production capacity for isopropyl biphenyl feedstock, a tangible advantage for customers seeking supply security and scale for serial projects.
- Rütgers GmbH (Germany) — A European technology supplier focused on high‑temperature application chemistries, with formulations and support tailored to industrial OEMs and process licensors.
The market concentration metrics we modeled underscore that the top three and top five suppliers command most commercial volumes, making strategic alignment with Tier‑1 producers an important lever for buyers and investors alike.
Strategic implications and recommended actions for 2026
- Qualify multiple supply pathways now. Firms should complete technical trials with at least two suppliers and secure conditional offtake or option agreements to guard against delivery bottlenecks in 2026–2027.
- Prioritize technical dossiers that speak to system warranty. Investment in third‑party thermal stability testing and extended operating trial data will materially improve negotiating leverage and reduce insurance and maintenance costs over equipment lifecycles.
- Embed regulatory readiness into procurement. Include traceability clauses, purity thresholds, and compliance documentation in purchase agreements to address legacy PCB concerns and to ease certification for electrical or dielectric applications.
- Design procurement for optionality. Layer shorter contracts with strategic capacity reservations from producers who maintain dedicated IPB production; this hybrid approach balances price optimization with continuity of supply.
- Scan for partnership-led expansion. For companies looking to move up the value chain, joint ventures with regional producers or minority investments in capacity-expanding players can fast-track market entry while limiting greenfield risk.
How PW Consulting’s full study adds value to your 2026 plan
Decision‑makers preparing budgets, RFPs, or capital allocation plans for 2026 will find the full report immediately usable. It contains calibrated spend models that translate market forecasts into procurement volumes and cost scenarios, a supplier risk matrix keyed to manufacturing footprints, and a set of negotiated contract templates specific to heat transfer fluids. For investors and corporate development teams, the study includes an acquisition screening model and an integration checklist tuned to the IPB chemistry space.
We intentionally keep the public summary high‑level to protect the commercial value of the underlying datasets. The full report, however, supplies the granular segmentation, regional and application splits, supplier share tables, and downloadable time-series that permit bespoke modelling for your organization’s risk tolerance and growth targets.
FAQ snapshot
- Why was IPB adopted broadly in the industry? Historically, isopropyl biphenyl mixtures were adopted as dielectric and heat transfer replacements following the regulatory phase‑out of polychlorinated biphenyls (PCBs). That context still influences procurement and compliance requirements today.
- Is supply capacity a practical constraint? Capacity varies by producer, and several manufacturers maintain dedicated IPB production lines — a fact that should be considered when evaluating long‑term project pipelines and contractual security.
- Do all IPB products perform equally? No. There are meaningful differences in purity, isomer composition, and additive strategies that affect maximum bulk temperatures, oxidation stability, and low‑temperature operability. The full report contains a validated technical comparison matrix and recommended qualification protocols.
For strategists looking to translate the market’s projected growth into executable plans for 2026, PW Consulting’s report is designed as a toolkit: it reduces technical uncertainty, clarifies supplier choice, and aligns procurement levers with broader corporate objectives. Contact PW Consulting to access the full dataset, scenario models, and supplier scorecards that will make your 2026 decisions materially more robust.
For detailed analysis of this topic, please visit the official page: Isopropyl Biphenyl Heat Transfer Fluid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Packaging Outsert and Inserts Market to Expand at 6.0% CAGR, Surging to USD 6.95 Billion by 2032 (2025: USD 4.62 Billion)
By pmarketresearch, 2026-07-15
Packaging Outsert and Inserts Market — Strategic Outlook for 2026
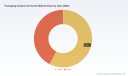
PW Consulting’s latest Packaging Outsert and Inserts Market report provides decision-grade intelligence designed to guide executive choices in 2026. Built on a 2025 base-year assessment and a 2026–2032 forecast horizon, the study demonstrates that the market reached approximately USD 4,625 Million in 2025 and is projected to expand at a steady compound annual growth rate of 6.0% over the forecast window. That trajectory—combined with near-term regulatory disruptions and raw-material volatility—creates a pivotal planning moment for manufacturers, brand owners, and packaging suppliers.
Packaging Outsert and Inserts Market
Why this report matters for choices made in 2026
-
Actionable timing: The near-term acceleration in demand and non-linear growth patterns in our base model mean choices made this year about capacity, technology, and supplier relationships will disproportionately affect 2026–2028 P&L and market access.
Packaging Outsert and Inserts Market -
Regulatory inflection: Extended Producer Responsibility (EPR) bills in multiple U.S. states and the EU’s Packaging and Packaging Waste Regulation (PPWR) are moving from policy to compliance windows—forcing packaging decisions to embed end-of-life costs and recycled-content requirements sooner than many planners anticipated.
Packaging Outsert and Inserts Market -
Cost pressure and inputs: Recent producer-price indices for folding paperboard and elevated global wood-pulp prices are increasing cost-to-serve across insert and outsert production; these input trends materially affect sourcing strategies and the economics of in-house production versus outsourcing.
-
Fragmented supplier landscape: The market remains fragmented—our concentration analysis shows low top-tier market control, creating runway for consolidation, selective partnerships, and differentiated capability plays by specialist suppliers.
Market dynamics that should drive your 2026 playbook
The report dissects four converging dynamics that will shape supplier economics and customer selection criteria in 2026:
-
Regulatory and sustainability mandates — EPR laws across multiple U.S. states and the EU’s PPWR push packaging decisions beyond labelling and into lifecycle liability. These rules increase the commercial value of recycled-content proficiency, mono-material design expertise, and documented end-of-life solutions.
-
Raw-material and input volatility — U.S. producer-price indices for folding paperboard and elevated global pulp import prices raise the risk of margin erosion. Our models quantify the sensitivity of margin to pulp and board price swings and present hedging and pass-through approaches that preserve competitiveness.
-
Technology and process innovation — Installations of digital presses and advanced folding/inline-gluing systems are enabling shorter runs, faster proofs, and more complex multilingual literature while reducing SKUs’ physical footprint. Early adopters are achieving faster time-to-market for label changes and regulatory updates.
-
Capacity and footprint shifts — Recent company-level moves—capacity additions and digital-print investments—signal supplier stratification by capability. Near-term investments will shape buyer bargaining power and the geography of service availability.
Competitive landscape — capability map and what it means for procurement
The vendor ecosystem spans niche specialists with deep pharmaceutical compliance capabilities, broad packaging houses offering integrated secondary packaging systems, and regional players focused on high-throughput carton and insert manufacturing. Key capabilities we track include high-precision folding and micro-folding, large-panel outsert conversion, cGMP and ISO-controlled production, digital print for short runs, multilingual booklets, spot-gluing and wafer-seal competence, and serialization-ready workflows.
-
Winpak — recognized for precision-engineered inserts and MedGuides suited for automated application and tight FDA dimensional tolerances; relevant for large-format-to-compact conversion needs.
-
CCL Healthcare — strong in high-panel leaflets and complex booklet builds under cGMP, useful for pharma clients with extensive multilingual and regulatory literature needs.
-
Nosco — strengths in stitched booklets and high-panel concatenations, serving pharmaceutical and natural-health markets that prioritize repeatable compliance.
-
Colbert Packaging — noted for custom paperboard cartons and recent capacity expansion to absorb higher paperboard demand in North America.
-
Graphic Packaging & Faller Packaging — system suppliers offering integrated leaflets and carton solutions; Faller’s recent investments in digital printing are enabling new short-run workflows.
-
RLG, Tursso, Flottman — boutique and specialist firms providing extreme precision folding, IFUs, serialization integration, and device-focused documentation packaging.
Strategically, buyers need a dual-track sourcing posture: maintain relationships with compliant, high-reliability suppliers for regulated product lines while cultivating digitally-capable, agile partners for short-runs, promotional campaigns, and rapid regulatory updates. Our supplier-scorecard framework in the report helps you quantify trade-offs between cost, speed, regulatory risk, and sustainability readiness.
What the PW Consulting report gives you (practical, executable content)
The study is structured to move teams from insight to implementation. Highlights of the deliverables:
-
Robust market-sizing and scenario models (base-year 2025; historical 2020–2025; forecast 2026–2032) with sensitivity to input-cost and regulatory scenarios so you can stress-test investment cases.
-
Competitive capability matrix and supplier due-diligence templates that codify GMP, ISO, digital-print, folding-panel, and multilingual competencies.
-
Procurement playbooks and total-cost-of-ownership (TCO) calculators incorporating pulp/board price pass-through, EPR liabilities, recycling-credit opportunities, and capex vs. outsourcing trade-offs.
-
Regulatory-compliance checklists and an EU/US EPR readiness tracker that align design and sourcing actions to emerging obligations.
-
Operational implementation roadmaps—90/180/365-day plans for digital-print pilots, recyclable-material trials, and inline integration pilots with packaging lines.
-
M&A and partnership playbooks highlighting target profiles, valuation sensitivities, and integration pitfalls for consolidation plays in a fragmented supplier market.
To preserve the strategic value of the report as a source product, the detailed segmented tables that break down regional and application-level shares are intentionally withheld from this release and are available in the full report package.
90/180/365-day strategic priorities for 2026
-
90 days — Rapid exposure assessment: run a cost-to-serve and supplier-risk audit focused on boards, pulp exposure, and EPR liabilities; negotiate emergency capacity agreements with high-compliance suppliers; launch a regulatory gap analysis for PPWR and state EPR requirements.
-
180 days — Capability pilots and material trials: execute a digital-print pilot for short runs and regulatory updates; trial mono-material and high-recycled-content substrates with selected SKUs; institute indexing clauses for pulp prices in supplier contracts or explore hedging solutions.
-
365 days — Structural choices: finalize decisions on outsourcing vs. in-house production based on pilot results and TCO analyses; pursue selective M&A or JV opportunities to secure critical capacity or specialist capabilities; deploy a phased sustainability transition plan aligned to EPR/PPWR timelines.
How PW Consulting can accelerate your 2026 agenda
-
Custom scenario and sensitivity modeling to quantify the value of digital-print investments, capacity expansion, and supplier consolidation.
-
End-to-end procurement transformation—supplier scorecards, RFP design, and contracting playbooks that embed regulatory and end-of-life costs.
-
M&A origination, due diligence, and post-merger integration support focused on capability capture and rapid scale-up.
-
Sustainability roadmaps and compliance implementation plans that translate EPR/PPWR obligations into actionable product and supply-chain changes.
Conclusion: 2026 is a make-or-break year for players in the outsert and inserts space. The combination of steady market growth, evolving regulations, and input-cost pressure requires a measured but decisive response—one that balances short-run agility with longer-term structural investments. PW Consulting’s Packaging Outsert and Inserts Market report supplies the analytical foundation and the executable playbooks to convert that response into measurable competitive advantage.
For access to the full dataset, segmented tables, and the implementation toolkit referenced here, please visit PW Consulting’s report page and request the complete Packaging Outsert and Inserts Market report for 2026. The full package contains the detailed regional and application breakdowns, supplier scorecards, and downloadable models that underpin the strategic recommendations summarized above.
For detailed analysis of this topic, please visit the official page: Packaging Outsert and Inserts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tris (Clorisopropyl) Phosphate Market to Hit USD 1,050 Million in 2025, Poised for 4.82% CAGR Through 2032
By pmarketresearch, 2026-07-15
Tris (Clorisopropyl) Phosphate (TCPP) Market: Strategic Intelligence for 2026 Decision‑Making
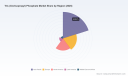
PW Consulting today releases a strategic briefing tied to our forthcoming full Tris (Clorisopropyl) Phosphate (TCPP) Market report. The briefing synthesizes the practical implications of an industry that has moved from recovery into a measured expansion phase: the TCPP market recorded USD 845.2 Million in 2020 and expanded to USD 1,050 Million in 2025, and our forecast points to a continuation of steady growth — reaching roughly USD 1,458 Million by 2032 at a compound annual growth rate (CAGR) of 4.82% across the 2026–2032 projection horizon. This release is designed as a trailer: it surfaces the analytical frameworks, strategic implications and actionable levers our clients need for 2026 planning, while reserving the detailed segment-level tables and model outputs for subscribers to the full report.
Tris (Clorisopropyl) Phosphate Market
Why this market matters in 2026
TCPP occupies a critical role in polymer flame‑retardant systems as manufacturers seek to balance regulatory compliance, cost efficiency and performance. Two structural features make TCPP strategically important for 2026 planning:
Tris (Clorisopropyl) Phosphate Market
- Resilient market trajectory: After navigating pandemic-era disruptions and feedstock volatility, historic data (2020–2025) show steady recovery and expansion, and our forecast demonstrates continued mid-single‑digit growth through 2032. Executives should treat this as a market with predictable topline growth but rising regulatory and trade complexity.
- Concentrated yet diverse supply base: The market exhibits moderate concentration among global leaders and a sizeable manufacturing footprint in Asia. The top three and top five producers collectively control a material share of supply, which creates both supplier risk and opportunities for strategic procurement partnerships.
What PW Consulting’s research delivers (practical contents)
The full PW Consulting TCPP Market report is built to support commercial strategy, procurement playbooks, technology scouting and regulatory risk mitigation. Key deliverables include:
Tris (Clorisopropyl) Phosphate Market
- Proven forecasting engine: Top‑down and bottom‑up demand scenarios for 2026–2032, with sensitivity testing for feedstock price shocks, tariff escalations and regulatory restrictions.
- Supply‑chain stress maps: Capacity overlays, logistics bottleneck indicators and vendor risk scoring that translate concentration metrics into procurement actions.
- Cost‑to‑produce models: Detailed manufacturing cost stack with feedstock composition and margin ranges. Note: primary feedstocks such as propylene oxide, phosphorus oxychloride and chlorine gas represent the dominant share of production cost — a structural input sensitivity that procurement teams must manage.
- Regulatory impact pathway: A scenario matrix that models outcomes from differential regulatory pathways (REACH, TSCA and country‑level measures), enabling compliance strategy and product re‑positioning decisions.
- Commercial playbooks: Go‑to‑market templates for producers, converters and distributors covering pricing strategy, grade-differentiation, and route-to-market for EV, construction and appliance applications.
- Competitive intelligence dossiers: Executive summaries of incumbents and challengers, channel maps and potential M&A/partnership targets, together with a deal valuation model focused on strategic fits and synergies.
- CapEx and sourcing decision tools: Project-level ROI calculators and break-even analyses for greenfield or brownfield expansions, plus import tariff and anti‑dumping impact calculators for cross‑border sourcing.
Competition and what it means for buyers & investors
The competitive landscape is shaped by multinational chemical majors that combine technology, regulatory credentials and integrated phosphorus supply chains, alongside regional producers and distributors focused on cost and logistical proximity. From a strategic standpoint:
- Global leaders with integrated supply chains bring durability and product development pipelines. Their strengths are regulatory documentation, customized formulations for high‑value applications (e.g., EV battery enclosure foams) and global logistics reach.
- Specialty chemicals firms emphasize co‑development and grade specialization, targeting automotive, electronics and engineered polymer systems where performance and compliance are premium purchasing criteria.
- Large regional producers and distributors supply commodity grades at scale. They are critical for price‑sensitive markets and for firms seeking flexible, multi‑origin sourcing to hedge against trade restrictions and feedstock swings.
Representative industry players profiled in our analysis include multinational producers with vertically integrated operations, specialty formulators focused on co-development, and a network of distributors providing channel reach into construction, resin and polymer converters. Recent market moves illustrate the competitive dynamics: new product introductions aimed at EV foam applications, trans‑regional supply partnerships to bolster availability in key markets, and new entrants targeting U.S. and European customers with manufacturing outside legacy supply hubs.
Regulatory, trade and cost headwinds to account for in 2026
Three non‑market factors are essential for 2026 planning:
- Regulatory scrutiny: TCPP has been subject to heightened regulatory attention in key jurisdictions. Certain registrants have self‑classified TCPP under specific hazard categories following long‑term toxicology studies for related chemistries, and regulatory pathways in the EU and North America remain fluid. Our report models multiple regulatory outcomes and provides mitigation strategies for formulation and substitution timelines.
- Trade barriers and remedies: Targeted trade measures and anti‑dumping determinations in major markets have altered import economics. Import duties and trade remedy actions materially change landed costs and should inform both sourcing and nearshoring choices.
- Feedstock cost exposure: Propylene oxide, phosphorus oxychloride and chlorine gas collectively dominate the TCPP cost structure. Volatility in these inputs materially shifts margin dynamics; our cost models enable procurement teams to quantify pass‑through requirements and hedge thresholds.
Actionable strategic recommendations for 2026
PW Consulting’s core advisory conclusions for executives preparing 2026 budgets and strategic roadmaps are:
- Scenario‑proof procurement: Establish multi-tier sourcing with a blend of long‑term agreements from established majors, capacity options with regional producers and dynamic spot positions. Build tariff and anti‑dumping assumptions into total landed cost calculations.
- Grade and application prioritization: Invest in market development where regulatory barriers are highest and margin uplift is greatest (for example, electrification and specialty polymer systems). Use co‑development agreements to de‑risk product qualification timelines.
- Regulatory contingency playbook: Prepare for tightening classifications and pre‑emptive documentation needs. Prioritize suppliers with robust REACH/TSCA dossiers and third‑party testing capacity to shorten qualification cycles.
- CapEx and partnership discipline: Favor flexible, debottleneckable assets over large fixed investments in the near term. Evaluate strategic partnerships, tolling arrangements or joint ventures to secure supply without over‑committing balance sheet resources.
- Value chain transparency: Deploy rapid auditing and traceability requirements for feedstock origin and impurity profiles — a small number of feedstock inputs drive the majority of manufacturing cost and regulatory exposure.
Market concentration: risk and opportunity
The industry shows measurable concentration among the largest producers; the three leading firms and the top five firms together control a significant share of global supply. For buyers, this concentration increases the value of strategic supplier relationships and of scenario planning for supply disruption. For investors, concentration can indicate both barriers to entry and potential consolidation targets — making the market attractive for selective M&A and for portfolio plays that combine upstream feedstock security with downstream application expertise.
Recent developments shaping 2026 tactics
- New product deployments aimed at electric vehicle applications indicate a shift in formulatory focus toward higher‑value segments; producers that can demonstrate regulatory readiness for EV foam applications stand to capture outsized growth.
- Partnerships expanding trans‑regional supply pools have emerged, reflecting demand for nearer‑market production and redundancy amid trade measures; these tie into the broader trend of geographic diversification of supply chains.
- New market entrants and distributor strategies in North America point to a re‑rating of logistics and supply agreements as a core commercial battleground for 2026.
How senior leaders should use the PW Consulting TCPP briefing
Procurement directors will find the cost‑to‑produce and landed‑cost calculators especially valuable for 2026 sourcing cycles. R&D and product teams should use the regulatory impact pathway and co‑development case studies to prioritize formulation investments. Corporate development and strategy teams will benefit from the competitive dossiers, concentration analytics and M&A valuation frameworks when evaluating partnership or acquisition targets.
Next steps and how to obtain the full analysis
This release highlights the frameworks, risks and strategic levers that PW Consulting believes will determine winners and losers in the TCPP market through 2026 and beyond. The full report contains the proprietary segment tables, interactive forecast models, supplier scorecards and deal valuation templates referenced here — intentionally withheld from this summary to preserve the value of the complete deliverable.
Clients and market participants seeking the complete dataset, scenario models and tailored advisory support for 2026 planning are invited to contact PW Consulting for access to the full TCPP Market report and for custom workshops that translate our findings into executable action plans.
For detailed analysis of this topic, please visit the official page: Tris (Clorisopropyl) Phosphate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Sulfonated Polyethersulfone Market Set to Expand at an 8.51% CAGR Through 2032
By pmarketresearch, 2026-07-15
Sulfonated Polyethersulfone Market 2026 Strategic Brief: What Boardrooms Need to Know
PW Consulting’s latest market research — the Sulfonated Polyethersulfone (S‑PES) Market Report (base year 2025, forecast 2026–2032) — translates granular chemical‑polymer dynamics into board‑level decision levers for 2026. This briefing highlights the report’s strategic value to corporate leaders planning investment, product development, supply‑chain resilience, and M&A in the next 12–36 months. It intentionally demonstrates our analytical depth while reserving proprietary segment tables and unit‑level forecasts for subscribers who access the full report.
Sulfonated Polyethersulfone Market
Why this market matters in 2026
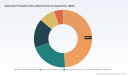
Sulfonated polyethersulfone has moved beyond a niche polymer curiosity to a commercially relevant hydrocarbon alternative in multiple membrane and ion‑exchange applications. Between 2020 and 2025 the global market expanded materially, and our modelling projects continued acceleration through the forecast window (2026–2032) at a compound annual growth rate (CAGR) of 8.51%. The market size grew from roughly USD 390 million in 2020 to USD 585.5 million by 2025, with our base scenario pointing toward a market that surpasses the USD 1 billion mark during the 2026–2032 forecast period.
Sulfonated Polyethersulfone Market
For leaders evaluating capital allocation in 2026, the message is clear: S‑PES is a growth polymer that sits at the intersection of membrane technology, industrial separations, and decarbonisation agendas. The macro trajectory justifies targeted pilots and selective upstream investments, but optimal timing and partner selection require more granular commercial and technical due diligence than public disclosures provide.
Sulfonated Polyethersulfone Market
Core market dynamics — distilled
- Demand drivers: accelerating demand for hydrocarbon‑based ion exchange membranes, intensified requirements for wastewater and industrial separations, and growing R&D activity in battery and electrochemical applications.
- Supply dynamics: a modest but rising production footprint, with industry indicators showing production volumes that remain constrained relative to conventional fluorinated counterparts, supporting favourable pricing dynamics and supplier leverage in early expansion phases.
- Regulatory and sustainability pressures: stricter environmental rules on polymer production and disposal are reshaping procurement preferences; S‑PES’s positioning as an alternative to perfluorinated sulfonic acid polymers is a strategic selling point for companies prioritising lower‑impact chemistries.
- Raw material and cost context: upstream intermediates such as diphenyl sulfone remain critical to feedstock security. Industry data suggest global S‑PES production was limited in 2024, with market participants transacting at premium per‑kilogram levels relative to mainstream engineering polymers — an important factor for price modelling and margin planning.
Competitive landscape: who’s shaping technology and supply
The S‑PES value chain is characterised by a mix of technology‑centric innovators and regional producers scaling product portfolios. Market concentration metrics indicate that the leading three players capture a meaningful but not dominant share of the market (CR3 ≈ 42.15%), while the top five firms together account for a larger portion (CR5 ≈ 58.8%). This structure creates space for differentiated technology plays, niche leadership, and strategic consolidation.
- Konishi Chemical Ind. Co., Ltd. (Japan) — technology‑led player advancing novel sulfonation chemistry. Konishi’s approach prioritises molecular weight retention during sulfonation (patented routes) and has delivered pilot‑scale material with a mid‑range sulfonation degree and high molecular weight characteristics. Their focus on antifouling membrane blends and ion‑exchange membranes for redox flow batteries positions them at the technology frontier; strategic partners should evaluate licensing, co‑development, or early off‑take to secure differentiated membrane feedstock.
- Monapoli Technology Co., Ltd. (China) — industrialised producer emphasising direct polymerisation routes to control both sulfonation degree and molecular weight, with processes claiming lower carbon intensity. For buyers seeking supply scale coupled with sustainability claims, Monapoli merits supplier qualification and process‑audit due diligence.
- SINKEN (Shanghai), Linyi Dechi, Shandong Jinlan — a cluster of Chinese firms supplying application‑focused S‑PES grades for antibacterial membranes, electrodialysis, and cation exchange membranes. These suppliers offer pragmatic access to product variants and are important tactical partners for regional manufacturers and membrane converters. Their presence also indicates a maturing domestic supply base that can compress lead times and enable aggressive product trials.
What PW Consulting’s report provides — practical, executable content
The full Sulfonated Polyethersulfone Market Report is structured to convert market intelligence into executable workstreams. Executives and strategy teams will find:
- Integrated demand scenarios (base, downside, upside) that model end‑market adoption across membranes, energy storage, and specialty separations — with sensitivity levers for feedstock price, environmental regulation, and technology substitution.
- Supply‑chain mapping and supplier scorecards designed for procurement — including audit checklists, carbon‑intensity indicators, and capacity ramp timelines for candidate suppliers.
- Technology risk matrices comparing sulfonation routes, molecular‑weight retention approaches, and process emissions — useful for R&D prioritisation and partner selection.
- Commercial playbooks for market entry and expansion: pilot design templates, sample contract terms (offtake, tolling), and go‑to‑market sequencing for membrane OEMs and chemical converters.
- Regulatory and lifecycle analysis (LCA) frameworks that translate environmental rules into compliance costs and product differentiation strategies.
- M&A and JV heatmaps that identify strategic targets and integration pitfalls, with valuation sensitivity to scale‑up CapEx and technology transfer risks.
To preserve the report’s value as a decision instrument, we present detailed segment tables, regional demand models, and supplier unit economics exclusively in the subscriber edition. The briefing here intentionally omits those raw segment figures while summarising their strategic implications.
Strategic imperatives for 2026
Based on our analysis, we recommend the following priority actions for executive teams considering exposure to S‑PES in 2026:
- Lock early access to differentiated feedstock. Prioritise partnerships or off‑take agreements with technology‑led suppliers for grades that retain high molecular weight after sulfonation — a material performance differentiator for membranes.
- De‑risk scale via staged capex and tolling. Use tolling agreements or co‑investment structures for initial production scale‑up to defer full capital commitment until clear product‑market fit is proven in targeted membrane applications.
- Embed sustainability claims into product roadmaps. Validate lifecycle assessments for low‑carbon polymer production and integrate these findings into supplier scoring and customer value propositions.
- Design pilots that focus on system‑level outcomes. Evaluate S‑PES not as a drop‑in polymer but as an enabler of membrane system performance (fouling resistance, ionic conductivity, lifetime). Pilot metrics should be aligned with end‑customer TCO, not only material properties.
- Monitor regulatory signals and position for substitution opportunities. Track jurisdictional moves away from perfluorinated chemistries; these create timing windows for S‑PES adoption, particularly where cost and environmental profiles align.
- Prepare an M&A playbook. Given the still‑moderate concentration profile, a deliberate acquisition or JV strategy can secure technology, capacity, or market access at attractive multiples relative to later consolidation phases.
Risks and mitigation
Key risks we highlight — and how to mitigate them:
- Feedstock volatility: secure dual sourcing and consider vertical integration for critical intermediates such as diphenyl sulfone.
- Technical scale‑up risk: validate sulfonation routes under production‑representative conditions and include acceptance criteria for molecular weight and sulfonation uniformity in supplier contracts.
- Regulatory reversal or alternative chemistries: maintain technology optionality by co‑investing in modular processing and by tracking competing ion‑exchange materials.
- Competitive price pressure: protect margin via differentiated grade development, service‑based contracts, and integrated membrane system offerings rather than commodity sales alone.
Data snapshot (macro figures)
Our modelling shows the global S‑PES market expanded from approximately USD 390 million in 2020 to USD 585.5 million in 2025, with an 8.51% CAGR projected across the 2026–2032 forecast window. Industry production volumes remain relatively limited at present, and market participants have transacted at elevated per‑kilogram levels consistent with constrained supply and specialised use‑cases. The top‑tier firms collectively account for a significant share of market sales, but fragmentation beyond the top five suggests opportunities for technology differentiation and strategic consolidation.
Next steps — how to convert insight into action
For companies planning board approvals, capital allocation, or partnership mandates in 2026, the full PW Consulting Sulfonated Polyethersulfone Market Report provides the executable intelligence you will need: segmented demand tables, supplier cost stacks, techno‑economic models, and negotiation playbooks. The report is deliberately designed to be used in commercial planning cycles and investment committees to shorten decision timelines while reducing execution risk.
Access the full report for comprehensive data, downloadable modelling templates, and supplier dossiers that include traceable sources and due diligence checklists. PW Consulting stands ready to support bespoke scenario modelling, supplier due diligence, and M&A execution planning informed by the dataset behind this briefing.
Contact PW Consulting to arrange a briefing, request the subscriber edition, or commission tailored strategic workstreams aligned with your 2026 priorities.
For detailed analysis of this topic, please visit the official page: Sulfonated Polyethersulfone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial‑Grade Borated Polyethylene Market Set to Expand at a 5.18% CAGR Through 2032
By pmarketresearch, 2026-07-15
Industrial Grade Borated Polyethylene Materials Market: Strategic Imperatives for 2026
Executive summary
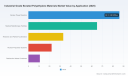
PW Consulting’s latest market intelligence on industrial grade borated polyethylene (BPE) delivers a focused strategic playbook for executives making near-term and medium-term decisions in 2026. Built from primary interviews, plant-level supply chain mapping, patent landscaping and proprietary financial modelling, the report quantifies the market’s current footprint and projects a clear growth trajectory: the industry base reaches roughly USD 217 million in 2025 and is forecast to expand to just over USD 309 million by 2032, implying a compound annual growth rate of approximately 5.18% across the 2026–2032 forecast window.
Industrial Grade Borated Polyethylene Materials Market
Why this matters for 2026 decision-makers
-
Capital allocation: With predictable, mid-single-digit CAGR, BPE is transitioning from a niche safety commodity to a portfolio-level component in energy, medical and defense asset plans. CFOs and strategy leads must now weigh steady organic growth against options for targeted capacity investments or bolt-on acquisitions.
Industrial Grade Borated Polyethylene Materials Market -
Supply chain resilience: Lead times and certification requirements increasingly differentiate suppliers. Procurement teams need an evidence-based sourcing matrix rather than ad-hoc vendor selection to avoid schedule slippage on nuclear and medical projects.
Industrial Grade Borated Polyethylene Materials Market -
Regulatory and technical risk: Compliance with military and nuclear specifications and the long service-life expectations of spent-fuel and reactor applications create unique product qualification burdens. Engineering and quality heads must plan multiyear validation programs now to be procurement-ready for projects coming online in the late 2020s.
Market dynamics driving 2026 choices
Demand is being shaped by three durable vectors: the continued renewal and expansion of civilian nuclear capacity in several markets; steady growth in medical radiotherapy infrastructure; and ongoing investments in research facilities and defense platforms that require certified neutron shielding. These drivers interact with supply-side realities—manufacturing capacity, certification lead times, and the availability of boron-loaded feedstocks—to determine who wins competitive opportunities.
Regulatory frameworks and military specifications remain a gating factor. Our analysis highlights the practical implications of long-standing standards that govern material composition and aging allowances for spent-fuel and naval applications. For procurement and engineering teams this means qualification timelines can be measured in quarters, not weeks—impacting vendor selection, contract terms and contingency planning.
Segmentation and product evolution (what we analyze, not what we disclose)
The report dissects the market across product formulations, boron loading bands, and application end-markets, and it tracks price and performance trade-offs between low-, mid- and high-loading variants. We do not publish the complete breakdown in this executive summary – the enclosed analysis in the full report preserves granular split data – but our findings emphasize a clear trend: customers increasingly demand higher functional density (more boron per unit volume) where mass and footprint matter, while cost-sensitive applications continue to favor standard loading grades with optimized manufacturing tolerances.
From a materials perspective, manufacturers are investing in process controls and secondary operations (CNC, waterjet cutting, custom fabrication) to expand addressable use-cases. For manufacturers and OEMs, the choice is between expanding fabrication capabilities to capture margin or outsourcing value-added work to regional partners for speed to market.
Competitive landscape — who to watch and why
The BPE supply base blends legacy specialty plastics producers, regional fabricators, and a growing pool of lower-cost suppliers. Our competitive review focuses on strategic positioning rather than raw sales figures, identifying the capabilities that matter most in 2026:
-
Proprietary processing and dimensional control. Firms that own specialized sheet extrusion or flattening processes provide differentiating product consistency for critical shielding panels—an important selling point in medical vault and reactor applications.
-
Certification and quality systems. Manufacturers registered to military and aerospace specifications and to ITAR/ASTM regimes shorten procurement cycles for defense and nuclear customers and justify premium pricing.
-
Customization and downstream services. Suppliers offering extensive CNC/waterjet cutting, custom blocking, and in-house fabrication capture additional value and reduce integration risk for installers and EPC firms.
-
Geographic and logistical reach. Regional stocking and quick-ship capabilities matter for time-sensitive retrofits and site fit-outs.
Illustrative vendor profiles in the report highlight how market participants are leveraging these capabilities. Some firms emphasize proprietary processing and flatness control to serve high-spec industrial customers; others compete on breadth of boron-loading options and aggressive lead times. Recent market activity—trade show visibility by marquee producers and strategic partnerships with national nuclear programs—reinforces a maturing commercial ecosystem where reputation, certification and service depth shape win rates.
Supply, pricing and margin dynamics
Raw-material cost sensitivity and the unit economics of higher-loading formulations drive product-level margin dispersion. Manufacturers with vertically integrated compounding or tight supplier agreements for boron additives maintain better gross margins when market prices spike. At the same time, buyers increasingly demand supplier-level transparency on aging performance and hydrogen density characteristics for long-life installations—creating an opportunity for suppliers that can demonstrate robust testing and lifecycle assurances.
Risk, regulation and compliance checklist for 2026
-
Material specifications: Close adherence to established military and nuclear material specifications is non-negotiable for many end markets. Expect procurement to require documented testing and traceability as part of standard RFPs.
-
Qualification lead times: Allow for extended validation timelines, especially when switching suppliers or introducing new boron loadings on certified projects.
-
Geopolitical and trade exposure: Sourcing strategies should model supply interruptions and potential tariff or export-control impacts across manufacturing nodes.
-
Lifecycle performance: Design safety margins and maintenance plans must account for conservative hydrogen-density de-ratings applied by regulators to account for aging.
Actionable guidance and tools included in the report
PW Consulting delivers pragmatic, decision-grade instruments tailored for 2026 execution:
-
Interactive financial model: Sensitivity-tested cash flow scenarios across capacity expansion, price compression and raw-material volatility.
-
Supplier selection matrix: A weighted evaluation framework that maps performance, certifications, lead times and after-sales capabilities to buyer priorities.
-
Go-to-market playbooks: Segmented strategies for suppliers targeting nuclear, medical and defense channels, including recommended commercial terms and partnership structures.
-
M&A and partnership shortlist methodology: A reproducible approach to identifying targets or JV partners that close capability gaps while preserving certification continuity.
-
Risk heat map: A triaged view of operational, regulatory and market risks with mitigation options and contingency triggers.
Implications for key stakeholders
-
Corporate Strategy: The market’s established growth profile makes BPE a defendable area for strategic focus. Decisions in 2026 should prioritize deals and investments that shorten customer qualification cycles and expand fabrication services.
-
Procurement: Implement the supplier selection matrix to balance cost, certification time and continuity risk. Prioritize dual-sourcing for mission-critical projects.
-
R&D and Engineering: Invest in accelerated qualification protocols for higher-loading materials and composite laminates that meet both neutron attenuation and longevity requirements.
-
Investors: Expect stable volumetric growth with pockets of premium margin for certified, service-rich suppliers. Private equity and strategic buyers should look for differentiated service models and certification-led barriers to entry.
What the full report provides (and why you’ll want it)
The complete PW Consulting report extends the preview above into a comprehensive suite of intelligence: detailed market sizing and verified time-series demand, scenario-based forecasts, supplier benchmarking, a complete regulatory compliance matrix, price index analysis and a downloadable financial model. To preserve competitive value for clients and to adhere to our “trailer” approach, we intentionally withhold certain granular segmentation tables and vendor share breakouts from this press release. These are available in the full report where subscribers can also access raw data and our underlying assumptions.
Next steps
For strategy teams preparing budgets and procurement pipelines in 2026, now is the time to validate assumptions, test alternative sourcing scenarios, and align certification roadmaps with project timelines. PW Consulting is offering limited advisory slots to translate this market intelligence into a tailored sourcing or M&A plan that fits your organization’s risk appetite and growth objectives.
To access the full report, download the data workbook, or schedule a briefing with our senior industry analysts, please visit the PW Consulting report page or contact our research desk for a confidential discussion.
For detailed analysis of this topic, please visit the official page: Industrial Grade Borated Polyethylene Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dragon Blood Market Poised to Top USD 379.39 Million by 2032, Growing at a 5.64% CAGR
By pmarketresearch, 2026-07-15
Dragon Blood Market 2026 Strategic Preview — What Corporate Leaders Must Know Now
PW Consulting’s Dragon Blood Market research is the definitive strategic briefing for executives preparing commercial, procurement, and R&D decisions in 2026. This preview summarizes why Dragon Blood (botanical resins and extracts commonly marketed as “Dragon’s Blood”) will be an active battleground for product differentiation, supply-chain resilience, and regulatory positioning over the next planning cycle — and how our full report turns those macro realities into executable priorities. The analysis below highlights high-level findings and operationally oriented recommendations while intentionally withholding the granular segment tables and proprietary split data included in the paid report.
Dragon Blood Market
Market at a glance
Dragon Blood is no longer a boutique ingredient: the total market expanded steadily during the 2020–2025 baseline and reached USD 258.4 Million in our 2025 base year (USD, Million). Our forecasts — underpinned by demand growth in personal care actives, wound-care formulations, and select food & beverage niches — project a compound annual growth rate (CAGR) of 5.64% across the 2026–2032 horizon, taking total market size toward the high hundreds of millions by 2032.
Dragon Blood Market
Two technical implications for decision-makers follow immediately. First, predictable overall expansion creates capacity for new product launches and for upstream investments in standardized extract technologies. Second, growth is uneven across use-cases, regulatory regimes, and sourcing geographies — a fragmentation that rewards targeted strategic initiatives rather than one-size-fits-all plays.
Dragon Blood Market
Why 2026 is an inflection year
-
Regulatory momentum: Recent approvals and regulatory clarifications — including a notable FDA approval for a standardized Dragon Blood wound-care formulation — are accelerating clinical and therapeutic use cases. At the same time, U.S. regulatory categorization remains fragmented (cosmetic, supplement, or medical product), constraining the exploitable market for some players and elevating the value of clear regulatory pathways.
-
Sourcing constraints and price volatility: Raw resin extraction remains manual and dependent on slow-growing species across Amazonian and Asian supply basins. Spot price volatility is material — our sector analysis shows annualized variations that require procurement hedging strategies and dynamic pricing approaches.
-
Sustainability premiums: Certified-organic and ethically sourced Dragon Blood capture meaningful price premiums in the market when tied to harvester welfare and agroforestry yields. Investments in supplier development projects have demonstrated sizable yield improvements in pilot geographies, increasing both supply reliability and commercial value.
-
Market structure: Concentration metrics reveal a market with established incumbents but clear white space. The leading few firms hold meaningful share, yet the breadth of suppliers — from high-volume resin merchants to specialized standardized-extract manufacturers — creates strategic pathways for new entrants and vertical consolidations.
What the PW Consulting Dragon Blood Market Report delivers (practical, operational content)
Our full report is designed as a tactical playbook for 2026 decision windows. It contains:
-
Actionable market-sizing and demand-forecast models with downloadable sheets (TAM / SAM / SOM scenarios) calibrated to product category and regulatory pathway.
-
Supply-chain mapping and a sourcing-risk matrix that identifies single-point-of-failure suppliers, seasonality windows, and climate/agroforestry exposure.
-
Supplier scorecards and contract term templates (including suggested clauses for traceability, yield-sharing, and sustainability premiums).
-
Regulatory playbooks by jurisdiction covering likely classification, dossier requirements, and clinical pathways for therapeutic claims.
-
Commercial tools: price-sensitivity ladders, private-label vs. ingredient positioning decision trees, and product-development roadmaps (formulation, sensory optimization, and stability testing protocols).
-
M&A and partnership screening frameworks: a prioritized heatmap of targets and integration risks for value-accretive consolidation.
-
Scenario planning modules that stress-test supply shocks, certification roll-outs, and demand pivots across cosmetics, pharmaceuticals, and specialty food applications.
These elements are paired with practical templates and checklists so that teams can move from insight to pilot in weeks, not quarters.
Competitive landscape — what incumbents are doing
The market shows clear strategic archetypes among active players:
-
Ingredient specialists (e.g., established cosmetic actives suppliers) are packaging Dragon Blood as performance actives for antimicrobial and skin-repair claims, offering standardized extracts with INCI-labelled formulations tailored for formulators.
-
Botanical-extract manufacturers emphasize hydro-glycolic and glycerite formats optimized for sensory profiles and emollience — important for personal care adoption.
-
Bulk resin merchants in supplier-dense geographies continue to control raw material flows, providing scale but limited product differentiation.
-
Emerging standardized-extract producers and pharmaceutical-grade suppliers are pursuing clinical pathways and regulatory approvals that can unlock higher-margin therapeutic markets.
Representative players span that spectrum: established cosmetic ingredient houses focused on formulation-ready actives; experienced botanical extract firms with long heritage in hydro-glycolic processes; wholesale specialists exporting wild-harvested resin and private-label options; and regionally dominant suppliers scaling pharmaceutical-grade standardization. Notably, one regional manufacturer has obtained regulatory clearance for a wound-care product built on standardized Dragon Blood — a development that will recalibrate therapeutic demand assumptions and raise the bar for quality and traceability across the value chain.
Market concentration metrics indicate a moderate level of consolidation among the top firms, leaving space for mid-market scale-ups and targeted acquisitions to reshape share dynamics over the next 24 months.
Strategic imperatives for 2026 decision-makers
-
Procurement: Move from spot-buying to a blended strategy of multi-year supply agreements, seasonal call-off contracts, and spot exposure limits. Build a supplier development fund focused on yield improvement and traceability; these investments often deliver outsized supply security and can justify certified-organic premiums.
-
Product strategy: Prioritize two parallel product tracks — (1) sensory-driven personal care actives optimized for formulators (emollience, texture, preservation synergy); and (2) clinical-grade standardized extracts targeted at wound-care and therapeutic claims where regulatory clarity is improving.
-
Regulatory and quality: Establish a regulatory roadmap for each intended use-case early. For medical claims, invest in standardized extract platforms and clinical partnerships; for cosmetic claims, ensure robust safety dossiers and traceability that support claims without triggering medical classification.
-
Sustainability as differentiation: Integrate community-level sourcing partnerships and agroforestry projects into supplier contracts. Certified organic and ethical-sourcing narratives command meaningful premiums and reduce reputational risks.
-
Commercial go-to-market: Use tiered pricing that internalizes raw-material volatility. Co-develop exclusives or semi-exclusives with key formulators to lock in early adoption and justify premium pricing.
-
M&A and alliances: Target bolt-on acquisitions that deliver either standardized-extract capability or secure upstream supply. Consider revenue-sharing JV models with high-quality harvest cooperatives to control both cost and CSR outcomes.
90-day playbook — from insight to pilot
-
Days 1–14: Executive alignment workshop using the report’s scenario modules and supplier scorecards. Select priority use-cases and acceptable regulatory risk profiles.
-
Days 15–45: Rapid supplier audits and negotiation of pilot contracts, with conditional clauses for certification upgrades and yield-improvement milestones.
-
Days 46–90: Launch two product pilots (one cosmetic active, one clinical-grade prototype), finalize regulatory pathway mapping, and present a commercial pilot pricing schedule for channel testing.
Concluding perspective
For companies allocating budgets and attention in 2026, Dragon Blood represents an intersection of science, culture, and supply-chain complexity. The ingredient will reward organizations that combine disciplined procurement, regulatory foresight, and a sustainability-first approach to sourcing. PW Consulting’s full Dragon Blood Market report provides the granular segmentation, supplier-level data, and downloadable tools necessary to operationalize the recommendations summarized here — including the proprietary split tables and supplier evaluations that underpin bidding and M&A decisions.
To access the complete dataset, supplier scorecards, and the ready-to-run 90-day implementation templates, visit the PW Consulting Dragon Blood Market report page and request the enterprise version of the study — designed specifically for executive teams ready to convert market momentum into defensible advantage in 2026.
For detailed analysis of this topic, please visit the official page: Dragon Blood Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Zinc L‑carnosine Market to Hit USD 205.77 Million by 2032 at a 6.15% CAGR — Asia Pacific Leads with USD 62.08 Million (2025 base year)
By pmarketresearch, 2026-07-15
Zinc L‑carnosine Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
Executive snapshot
The Zinc L‑carnosine market has evolved from a niche therapeutic ingredient into a globally traded API and specialty nutraceutical input. Our PW Consulting Zinc L‑carnosine Market report (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes primary supplier intelligence, regulatory mapping, and multi‑scenario financial modelling to support executive decision‑making in 2026. Key macro takeaways: the market reached USD 135.5 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.15% through the 2026–2032 forecast window, reaching approximately USD 205.8 Million by 2032. Market concentration is meaningful—our analysis shows the top three players account for roughly 42.5% of market supply and the top five for about 58.2%—creating both risk and opportunity for strategic entrants and incumbents.
Zinc L-carnosine Market
Why this report matters for 2026 choices
-
Timing and trajectory: 2026 is the inflection year for several regulatory and commercial vectors. Modest but steady end‑market growth, paired with emerging scientific interest beyond gastroenterology, creates a window for differentiated positioning before the market becomes commoditized.
Zinc L-carnosine Market -
Regulatory strategy shapes commercial access: Zinc L‑carnosine occupies different regulatory categories across jurisdictions—approved drug in some Asian markets, dietary supplement in many Western markets, and an emerging Novel Food dossier in Europe. These classifications determine evidence burden, pricing power, and distribution channels.
Zinc L-carnosine Market -
Supply‑side concentration and certification requirements (USDMF, JDMF, WHO‑GMP, halal/kosher, cGMP) mean supplier qualification and vertical integration choices in 2026 will materially affect cost, launch timelines, and reputational exposure.
-
Intellectual property and branded originators: the presence of an established originator and reference product(s) positions players differently for clinical partnerships, licensing, and generics development—an important consideration for portfolio and M&A teams.
What the PW Consulting report delivers (practical scope)
-
Robust market sizing & forecasting: granular topline trajectory (2020–2032) with sensitivity scenarios and demand drivers modelled across macroeconomic, clinical, and retail trends to stress‑test business plans.
-
Segmented opportunity matrices: demand levers by regulatory channel (pharmaceutical vs nutraceutical), formulation pathway (API vs finished formulations), and customer archetypes—presented in an actionable format for prioritization. Note: the full, detailed split tables and downloadable datasets are restricted to the full report.
-
Competitive intelligence pack: supplier dossiers for originators, established API producers, and emerging entrants—covering certifications, capacity indicators, recent filings, and likely strategic intents.
-
Regulatory and clinical landscaping: jurisdictional treatment of zinc L‑carnosine (from prescription drug status in some Asian markets to dietary supplement categorization in Western markets), recent filings and bioequivalence references, and an evidence roadmap for claim substantiation.
-
Supply chain and procurement toolkit: risk heatmaps, qualification checklists, contract templates, and benchmarking guidance for price and lead‑time negotiations.
-
Commercial playbooks: channel entry options, co‑promotion strategies with gastroenterology outlets, premiumization levers for nutraceutical positioning, and a go‑to‑market decision framework tuned to differing regulatory outcomes.
-
M&A & partnership yardstick: valuation lenses, due diligence checklists specific to zinc L‑carnosine assets, and scenario valuation routines for bolt‑on vs platform acquisitions.
Competitive landscape — profiles and tactical implications
The competitive fabric of this market blends a long‑standing originator with a distributed base of regional API specialists and ingredient suppliers. The landscape is best understood through three archetypes: originator/brand custodians, established API manufacturers with regulatory filings, and high‑volume commodity suppliers.
-
Originator / brand custodians — companies that own the reference branded formulations and associated clinical legacy. They are gatekeepers for clinical comparators and possess the regulatory dossiers that can be leveraged in licensing or co‑development agreements. These firms tend to prioritize scientific evidence and controlled commercialization pathways.
-
Regulatory‑filed API manufacturers — firms that have invested in DMFs/filings (USDMF, JDMF, WHO‑GMP, etc.) and therefore provide higher assurance to multinational pharmaceutical customers. Recent active filings and registration updates indicate a maturation of supply capable of servicing regulated markets.
-
High‑volume commodity suppliers — producers whose value proposition is scale and cost competitiveness, often servicing nutraceutical formulators and regional pharmaceutical manufacturers. These players are pivotal to price dynamics and inventory flexibility.
Recent, adjudicative events that will shape competitive moves in 2026 include: an active USDMF submission from a Chinese API producer (submitted in early 2025), additional Japanese DMF registrations from China‑headquartered suppliers, a bioequivalence reference study leveraging the Japanese reference granule product in 2025, and a 2026 scientific review widening interest in therapeutic applications beyond gastroenterology. These events collectively lower regulatory friction for global pharmaceutical adoption while simultaneously stimulating generic substitution and label expansion activity.
Supply‑side and regulatory dynamics to watch
-
Certification premium: USDMF/JDMF/WHO‑GMP filings materially increase addressable pharmaceutical demand; suppliers without these filings will remain concentrated in supplementary channels.
-
Regulatory bifurcation across markets: treatment as a prescription product in certain Asian markets versus a supplement in many Western markets creates parallel commercialization playbooks—each with different evidence and distribution requirements.
-
Concentration risk: with a meaningful share of supply held by a handful of firms, procurement teams must quantify single‑supplier exposure and plan dual‑sourcing or contract manufacturing strategies accordingly.
-
Scientific momentum: expanding literature that re‑evaluates the zinc‑L‑carnosine combination for broader therapeutic roles has the potential to shift demand composition from supplement to prescription channels over the medium term.
Strategic recommendations for executives in 2026
-
Synchronize regulatory and commercial plans: map regulatory category by target market and align evidence generation (bioequivalence, clinical endpoints) with intended claims and channel strategy before committing to large‑scale supply agreements.
-
De‑risk procurement through staged qualification: prioritize suppliers with active regulatory dossiers for markets where prescription status applies; for nutraceutical channels, secure long‑term contracts with flexible volume clauses to manage spot price volatility.
-
Invest in differentiated clinical evidence: a modest investment in targeted clinical or mechanistic work can unlock higher margin medical channels and protect against rapid commoditization in supplement markets.
-
Consider partnership routes with originator brands: licensing, co‑promotion, or supply arrangements with originator firms accelerate market entry and provide comparative reference products for regulatory filings.
-
Prepare for M&A windows: with supply consolidation and regulatory filings accelerating, 2026 is likely to be fertile ground for bolt‑on acquisitions—use our M&A yardstick and scenario valuations to screen targets.
How to use this preview and next steps
This article is a strategic preview designed to surface the critical decision levers for 2026. The full PW Consulting Zinc L‑carnosine Market report contains the detailed datasets, supplier dossiers, segmented demand tables, price benchmarking, and downloadable financial models that commercial teams, procurement leads, regulatory affairs, and corporate development groups will need to execute with confidence. To access the complete intelligence package—including the granular regional and application splits that underpin tailored go‑to‑market plans—please visit our report page.
For bespoke consulting engagements, scenario runs customized to your product portfolio, or confidential supplier diligence informed by our supplier interviews and primary supply‑chain checks, PW Consulting’s industry team is available to support rapid decisioning throughout 2026.
For detailed analysis of this topic, please visit the official page: Zinc L-carnosine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com