

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Isopropyl Biphenyl Heat Transfer Fluid Market to Grow from USD 238.5 Million in 2025 to USD 346.61 Million by 2032 at a 5.48% CAGR

Isopropyl Biphenyl Heat Transfer Fluid Market: Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s latest market study on Isopropyl Biphenyl (IPB) heat transfer fluids offers a concise, actionable map for commercial leaders, procurement heads, and technology strategists preparing plans for 2026. The study synthesizes historical performance, forward-looking scenario work, supplier intelligence, and regulatory context into a playbook designed to reduce execution risk while preserving optionality — a necessary balance as the market moves from niche industrial use toward broader adoption in decarbonization and advanced thermal management applications.
Isopropyl Biphenyl Heat Transfer Fluid Market
Market trajectory: what the numbers say (and what they don’t)
Over the historical window we examined (2020–2025), the IPB heat transfer fluid market demonstrated consistent expansion, growing from a clearly smaller base to an estimated USD 238.5 Million in 2025. Our baseline forecast shows the market entering 2026 with continued momentum, and a compound annual growth rate (CAGR) of approximately 5.48% over the 2026–2032 forecast horizon. By the end of the forecast period the market is projected to be materially larger, reflecting steady industrial demand, incremental displacement of legacy chemistries, and new end‑use opportunities that emerge from energy transition programs.
Isopropyl Biphenyl Heat Transfer Fluid Market
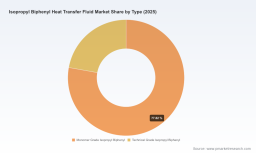
These headline figures are purposefully presented at a market level to show directionality and scale. PW Consulting’s proprietary models further decompose growth drivers into technical, regulatory, and commercial vectors — but in keeping with the “trailer” principle of this release, core segment-level datapoints and detailed regional/application shares are reserved for the full report.
Isopropyl Biphenyl Heat Transfer Fluid Market
Why 2026 is a hinge year for strategic choices
- Procurement posture matters: The combination of steady demand growth and concentrated supply dynamics means buyers will face meaningful supplier‑selection tradeoffs in 2026. Our market concentration analysis highlights a marketplace where a handful of suppliers control most of the commercially available volumes, elevating the importance of contractual terms, contingency capacity, and qualification pipelines.
- Raw material and production footprints are decisive: Producers with dedicated IPB production capacity gain a durable advantage in lead time and price resilience. For example, one major manufacturer maintains an annual dedicated production capacity in the low thousands of tonnes for isopropyl biphenyl, a practical fact that shapes sourcing strategies and potential partnership models.
- Regulatory momentum favors IPB over legacy PCBs: The historical phase-out of polychlorinated biphenyls (PCBs) has created an industry legacy that continues to influence buyer confidence, compliance requirements, and insurance economics. IPB-based fluids are widely adopted as alternatives in many applications, which simplifies entry for conservative buyers but places a premium on demonstrable purity and long-term stability data.
- New end-use vectors will drive incremental demand: Beyond traditional chemical and polyester processing, thermal energy recovery, advanced electronics cooling, and large-scale concentrated solar power projects are emerging as meaningful growth pockets. Each of these use cases imposes distinct technical and supply constraints that the full report models in scenario form.
Report contents: practical deliverables for the 2026 agenda
PW Consulting designed this study as a business tool, not just an academic exercise. Key practical outputs included in the full report are:
- Verified market sizing (historical and forecast), including sensitivity runs tied to energy policy and capital deployment assumptions.
- Commercial decision frameworks: supplier selection scorecards, total cost of ownership templates, and contract clauses to protect buyers against supply shocks and specification drift.
- Technical evaluation matrix comparing thermal stability, low‑temperature operability, and compatibility issues for typical system architectures.
- Supply‑chain heat map identifying single‑sourced materials, flexible manufacturing nodes, and near‑term expansion opportunities.
- Regulatory and safety roadmap summarizing legacy PCB phase‑out implications, testing protocols, and expected compliance milestones through 2032.
- M&A and partnership scouting: a shortlist of technology and capacity targets for acquirers seeking quick market entry or downstream integration.
- Operational playbooks for plant trials, pilot-to-scale adoption, and warranty negotiation templates aligned to fluid specification risk.
Competitive landscape: who matters and why
The competitive field is relatively concentrated and features a mix of global chemical majors and specialized regional suppliers. Several firms stand out for their differentiated positions:
- Eastman Chemical Company (Kingsport, TN, USA; https://www.eastman.com) — A global supplier with a widely recognized branded product positioned for low‑pressure liquid systems. Eastman’s strengths are global availability, technical documentation, and established customer support pathways for industrial end users.
- Nippon Chemical Texas Inc. (NCTI) (Texas, USA; https://nctius.com) — Focused on high‑temperature and cold‑start robustness, with formulations designed for extremes of service temperature and for industrial processes requiring wide operability windows. NCTI’s engineering focus supports customers with demanding thermal cycles.
- Dalian Richfortune Chemicals (Dalian, China; http://www.richfortunechem.com) — A cost‑competitive supplier with project experience in utility‑scale concentrated solar power (CSP) and other industrial applications; leverages regional manufacturing scale to support long‑term contracts for large projects.
- Jiangsu Zhongneng Chemical Technology (Lianyungang, China; https://www.dynovacn.com) — Provides a portfolio of biphenyl derivatives and IPB‑based products covering broad temperature ranges, often chosen for compatibility and formulation flexibility.
- Manto Chemistry (Jiangsu Manto Chemistry Co., Ltd.) (China; https://mantochem.com) — Noteworthy for maintaining dedicated annual production capacity for isopropyl biphenyl feedstock, a tangible advantage for customers seeking supply security and scale for serial projects.
- Rütgers GmbH (Germany) — A European technology supplier focused on high‑temperature application chemistries, with formulations and support tailored to industrial OEMs and process licensors.
The market concentration metrics we modeled underscore that the top three and top five suppliers command most commercial volumes, making strategic alignment with Tier‑1 producers an important lever for buyers and investors alike.
Strategic implications and recommended actions for 2026
- Qualify multiple supply pathways now. Firms should complete technical trials with at least two suppliers and secure conditional offtake or option agreements to guard against delivery bottlenecks in 2026–2027.
- Prioritize technical dossiers that speak to system warranty. Investment in third‑party thermal stability testing and extended operating trial data will materially improve negotiating leverage and reduce insurance and maintenance costs over equipment lifecycles.
- Embed regulatory readiness into procurement. Include traceability clauses, purity thresholds, and compliance documentation in purchase agreements to address legacy PCB concerns and to ease certification for electrical or dielectric applications.
- Design procurement for optionality. Layer shorter contracts with strategic capacity reservations from producers who maintain dedicated IPB production; this hybrid approach balances price optimization with continuity of supply.
- Scan for partnership-led expansion. For companies looking to move up the value chain, joint ventures with regional producers or minority investments in capacity-expanding players can fast-track market entry while limiting greenfield risk.
How PW Consulting’s full study adds value to your 2026 plan
Decision‑makers preparing budgets, RFPs, or capital allocation plans for 2026 will find the full report immediately usable. It contains calibrated spend models that translate market forecasts into procurement volumes and cost scenarios, a supplier risk matrix keyed to manufacturing footprints, and a set of negotiated contract templates specific to heat transfer fluids. For investors and corporate development teams, the study includes an acquisition screening model and an integration checklist tuned to the IPB chemistry space.
We intentionally keep the public summary high‑level to protect the commercial value of the underlying datasets. The full report, however, supplies the granular segmentation, regional and application splits, supplier share tables, and downloadable time-series that permit bespoke modelling for your organization’s risk tolerance and growth targets.
FAQ snapshot
- Why was IPB adopted broadly in the industry? Historically, isopropyl biphenyl mixtures were adopted as dielectric and heat transfer replacements following the regulatory phase‑out of polychlorinated biphenyls (PCBs). That context still influences procurement and compliance requirements today.
- Is supply capacity a practical constraint? Capacity varies by producer, and several manufacturers maintain dedicated IPB production lines — a fact that should be considered when evaluating long‑term project pipelines and contractual security.
- Do all IPB products perform equally? No. There are meaningful differences in purity, isomer composition, and additive strategies that affect maximum bulk temperatures, oxidation stability, and low‑temperature operability. The full report contains a validated technical comparison matrix and recommended qualification protocols.
For strategists looking to translate the market’s projected growth into executable plans for 2026, PW Consulting’s report is designed as a toolkit: it reduces technical uncertainty, clarifies supplier choice, and aligns procurement levers with broader corporate objectives. Contact PW Consulting to access the full dataset, scenario models, and supplier scorecards that will make your 2026 decisions materially more robust.
For detailed analysis of this topic, please visit the official page: Isopropyl Biphenyl Heat Transfer Fluid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com