

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
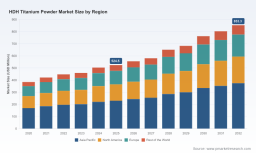
PW Consulting: HDH Titanium Powder Market to Rise from USD 524.5 Million in 2025 to USD 853.3 Million by 2032 at a 7.2% CAGR

HDH Titanium Powder Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive snapshot
PW Consulting’s HDH Titanium Powder Market report (base year 2025) delivers a focused, actionable view of a market that has transitioned from niche feedstock supply to a strategic industrial commodity. Our modelling shows the global HDH titanium powder market reached approximately USD 524.5 Million in 2025 and — under a set of consensus demand and supply assumptions — is projected to grow at a compound annual growth rate (CAGR) of 7.2% through the 2026–2032 forecast period, reaching roughly USD 853.3 Million by 2032. The report couples a granular view of dynamics with transaction-grade tools to inform 2026 capital allocation, procurement, and M&A choices.
HDH Titanium Powder Market
Why this matters for 2026 decision-makers
- Supply security is now strategic: HDH titanium powder remains feedstock-dependent, with production ultimately tied to titanium sponge availability and the hydrogenation–dehydrogenation (HDH) processing route. Policy and geopolitical shifts in sponge-producing regions elevate the value of resilient sourcing strategies.
- Cost–performance trade-offs are reshaping choices: HDH powders offer a cost-competitive alternative to spherical gas-atomized powders for many powder metallurgy, metal injection molding, and thermal spray applications. Procurement teams must weigh powder morphology, downstream processing costs, and end-use specification risks — not only headline price per kilogram.
- Regulatory and standards risk is non-trivial for critical end-markets: Medical and aerospace buyers face strict standards (e.g., ISO 23301 and relevant ASTM specifications). Certification and traceability are decisive contract terms in 2026.
- Market structure enables targeted plays: Concentration metrics show a moderately concentrated supplier market (CR3 ≈ 42.5%, CR5 ≈ 58.3%), which creates room for both incumbent scale plays and focused niche entrants to capture differentiated margins.
What the PW Consulting HDH Titanium Powder Market report contains
- Comprehensive market sizing and forecast (2020–2032): Historical reconciliation, driver-based forecasts, scenario workstreams, and sensitivity modelling to inform 2026 budgeting and capital plans.
- Methodology and data pack: Transparent assumptions, source laddering, confidence bands, and an Excel model for custom scenario analysis and integration into client financial models.
- Value-chain mapping and cost stack analysis: From sponge procurement through hydrogenation, crushing, dehydrogenation, sieving, and post-processing, with unit-cost drivers and break-even maps for vertical integration decisions.
- Pricing deck and benchmark comparators: Market price ranges by grade and particle size, comparative economics versus gas-atomized powders, and margin waterfall for typical producers and consumers.
- Demand-by-application playbooks: End-market demand drivers (aerospace, medical implants, additive manufacturing, powder metallurgy, coatings), use-case risk matrices, and adoption curves — with executable commercial tactics for suppliers and buyers.
- Supplier intelligence and competitive mapping: Transaction-ready profiles for incumbent producers, capacity maps, capability heatmaps, and a M&A watchlist.
- Regulatory, geopolitical and raw-material risk assessment: Scenario-based impact analysis of export controls, tariffs, and domestic content rules on sourcing and pricing.
- Commercial diligence toolkit: Supplier scorecards, sampling and testing checklists (oxygen/hydrogen content, PSD, morphology), contract templates, and quality audit playbooks tailored to 2026 procurement cycles.
Note: the report intentionally aggregates sensitive subsegment tables and supplier capacity schedules behind our data room. This executive briefing highlights key insights while directing practitioners to the full dataset for transaction-level decisions.
HDH Titanium Powder Market
Competitive landscape — what to watch in 2026
The HDH market is shaped by diversified players: legacy refiners and sponge integrators in East Asia; specialized powder manufacturers in North America and Europe; and high-volume producers from China that serve global industrial chains. Strategic moves in 2025–2026 underscore several themes:
HDH Titanium Powder Market
- Vertical integration and consolidation: Recent corporates actions — including a share exchange that will bring a major Japanese HDH producer into a larger metals group effective mid-2026 — illustrate a push toward upstream control of feedstock and enhanced product portfolios. Expect further consolidation in response to supply-security imperatives.
- Long-term offtakes and aerospace tie-ups: Expanded long-term agreements between titanium material suppliers and major OEMs reinforce how aerospace demand secures higher-value, certified flows of powder and sheet. These contracts raise the hurdle for new entrants seeking aerospace approvals.
- Quality and certification as market access gates: Suppliers that secure aerospace and medical certifications, and demonstrate low-impurity control, are capturing premium segments. Independent quality credentials are becoming determinative in supplier selection.
- Chinese producers remain pivotal: Large producers based in China continue to supply significant volume to global markets, offering broad PSD options and competitive pricing. Buyers must balance short-term cost advantages versus medium-term geopolitical and regulatory risk.
- Specialized Western suppliers: Select firms in North America and Europe focus on higher-spec alloys and engineered powders tailored to medical implants and additive manufacturing, positioning themselves on quality and service rather than commodity pricing.
Supply-chain risks and mitigation playbook for 2026
- Feedstock concentration: Titanium sponge production concentration makes feedstock strategies (dual-sourcing, local inventory pools, backward integration) essential. Commodity hedging alone is insufficient given non fungible specifications and certification requirements.
- Quality drift: Control of oxygen and hydrogen content is paramount for medical and aerospace. Buyers should establish inline testing, third-party validation, and contractual acceptance criteria tied to lot-based traceability.
- Geopolitical contingencies: Prepare scenario playbooks for export restrictions, tariffs, and domestic content mandates. Scenarios should include time-to-fill windows, alternate routing, and contractor substitution playbooks.
- Commercial levers: Structured, multi-year offtake agreements with performance-based pricing, capacity reservation clauses, and ramp schedules protect OEMs while providing revenue visibility to producers making capital investments.
Commercial implications & go-to-market strategies
- For suppliers: Prioritize certified product lines (medical/aerospace), augment quality management systems, and consider small-scale atomization or surface modification services to capture higher-value AM markets. Geographic diversification of customers mitigates concentration risk.
- For buyers: Rebalance procurement from lowest-cost spot buys to strategic blends of contracted volumes plus validated spot sourcing. Invest in incoming inspection capabilities and create supplier development programs to align material specifications with in-house processing constraints.
- For investors and M&A teams: Focus on targets with defensible certifications, proven low-impurity processes, and flexible particle-size distribution capabilities. The mid-market remains ripe for bolt-on plays that extend value chains into pre-alloying, blending, or downstream finishing.
How to use this report in 2026 planning
- Integrate our forecast scenarios directly into capex and inventory modelling to quantify upside and downside from feedstock disruptions.
- Use the supplier scorecards and audit templates to re-run procurement RFIs and shorten supplier qualification lead times.
- Employ our price decks and cost stacks to stress-test supplier bids and structure multi-year contracts with indexed pricing and quality KPIs.
- Apply the M&A screening checklist to prioritize acquisition targets that deliver immediate capability upgrades (certifications, specialty alloys, PSD flexibility).
Access and next steps
PW Consulting’s HDH Titanium Powder Market report is designed as an operational decision tool for 2026. It combines a validated macro forecast with drill-down analytics, supplier intelligence, and executable playbooks. For access to the full dataset — including detailed segmentation tables, supplier capacity schedules, price decks, and the interactive Excel model — please visit our report page or contact PW Consulting’s industry team to arrange a briefing and data-room access. The executive briefing above provides the strategic framing; the licensed report supplies the transaction-ready detail you will need to act this year.
For detailed analysis of this topic, please visit the official page: HDH Titanium Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com