

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Zinc L‑carnosine Market to Hit USD 205.77 Million by 2032 at a 6.15% CAGR — Asia Pacific Leads with USD 62.08 Million (2025 base year)

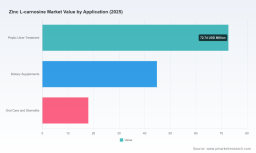
Zinc L‑carnosine Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
Executive snapshot
The Zinc L‑carnosine market has evolved from a niche therapeutic ingredient into a globally traded API and specialty nutraceutical input. Our PW Consulting Zinc L‑carnosine Market report (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes primary supplier intelligence, regulatory mapping, and multi‑scenario financial modelling to support executive decision‑making in 2026. Key macro takeaways: the market reached USD 135.5 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.15% through the 2026–2032 forecast window, reaching approximately USD 205.8 Million by 2032. Market concentration is meaningful—our analysis shows the top three players account for roughly 42.5% of market supply and the top five for about 58.2%—creating both risk and opportunity for strategic entrants and incumbents.
Zinc L-carnosine Market
Why this report matters for 2026 choices
-
Timing and trajectory: 2026 is the inflection year for several regulatory and commercial vectors. Modest but steady end‑market growth, paired with emerging scientific interest beyond gastroenterology, creates a window for differentiated positioning before the market becomes commoditized.
Zinc L-carnosine Market -
Regulatory strategy shapes commercial access: Zinc L‑carnosine occupies different regulatory categories across jurisdictions—approved drug in some Asian markets, dietary supplement in many Western markets, and an emerging Novel Food dossier in Europe. These classifications determine evidence burden, pricing power, and distribution channels.
Zinc L-carnosine Market -
Supply‑side concentration and certification requirements (USDMF, JDMF, WHO‑GMP, halal/kosher, cGMP) mean supplier qualification and vertical integration choices in 2026 will materially affect cost, launch timelines, and reputational exposure.
-
Intellectual property and branded originators: the presence of an established originator and reference product(s) positions players differently for clinical partnerships, licensing, and generics development—an important consideration for portfolio and M&A teams.
What the PW Consulting report delivers (practical scope)
-
Robust market sizing & forecasting: granular topline trajectory (2020–2032) with sensitivity scenarios and demand drivers modelled across macroeconomic, clinical, and retail trends to stress‑test business plans.
-
Segmented opportunity matrices: demand levers by regulatory channel (pharmaceutical vs nutraceutical), formulation pathway (API vs finished formulations), and customer archetypes—presented in an actionable format for prioritization. Note: the full, detailed split tables and downloadable datasets are restricted to the full report.
-
Competitive intelligence pack: supplier dossiers for originators, established API producers, and emerging entrants—covering certifications, capacity indicators, recent filings, and likely strategic intents.
-
Regulatory and clinical landscaping: jurisdictional treatment of zinc L‑carnosine (from prescription drug status in some Asian markets to dietary supplement categorization in Western markets), recent filings and bioequivalence references, and an evidence roadmap for claim substantiation.
-
Supply chain and procurement toolkit: risk heatmaps, qualification checklists, contract templates, and benchmarking guidance for price and lead‑time negotiations.
-
Commercial playbooks: channel entry options, co‑promotion strategies with gastroenterology outlets, premiumization levers for nutraceutical positioning, and a go‑to‑market decision framework tuned to differing regulatory outcomes.
-
M&A & partnership yardstick: valuation lenses, due diligence checklists specific to zinc L‑carnosine assets, and scenario valuation routines for bolt‑on vs platform acquisitions.
Competitive landscape — profiles and tactical implications
The competitive fabric of this market blends a long‑standing originator with a distributed base of regional API specialists and ingredient suppliers. The landscape is best understood through three archetypes: originator/brand custodians, established API manufacturers with regulatory filings, and high‑volume commodity suppliers.
-
Originator / brand custodians — companies that own the reference branded formulations and associated clinical legacy. They are gatekeepers for clinical comparators and possess the regulatory dossiers that can be leveraged in licensing or co‑development agreements. These firms tend to prioritize scientific evidence and controlled commercialization pathways.
-
Regulatory‑filed API manufacturers — firms that have invested in DMFs/filings (USDMF, JDMF, WHO‑GMP, etc.) and therefore provide higher assurance to multinational pharmaceutical customers. Recent active filings and registration updates indicate a maturation of supply capable of servicing regulated markets.
-
High‑volume commodity suppliers — producers whose value proposition is scale and cost competitiveness, often servicing nutraceutical formulators and regional pharmaceutical manufacturers. These players are pivotal to price dynamics and inventory flexibility.
Recent, adjudicative events that will shape competitive moves in 2026 include: an active USDMF submission from a Chinese API producer (submitted in early 2025), additional Japanese DMF registrations from China‑headquartered suppliers, a bioequivalence reference study leveraging the Japanese reference granule product in 2025, and a 2026 scientific review widening interest in therapeutic applications beyond gastroenterology. These events collectively lower regulatory friction for global pharmaceutical adoption while simultaneously stimulating generic substitution and label expansion activity.
Supply‑side and regulatory dynamics to watch
-
Certification premium: USDMF/JDMF/WHO‑GMP filings materially increase addressable pharmaceutical demand; suppliers without these filings will remain concentrated in supplementary channels.
-
Regulatory bifurcation across markets: treatment as a prescription product in certain Asian markets versus a supplement in many Western markets creates parallel commercialization playbooks—each with different evidence and distribution requirements.
-
Concentration risk: with a meaningful share of supply held by a handful of firms, procurement teams must quantify single‑supplier exposure and plan dual‑sourcing or contract manufacturing strategies accordingly.
-
Scientific momentum: expanding literature that re‑evaluates the zinc‑L‑carnosine combination for broader therapeutic roles has the potential to shift demand composition from supplement to prescription channels over the medium term.
Strategic recommendations for executives in 2026
-
Synchronize regulatory and commercial plans: map regulatory category by target market and align evidence generation (bioequivalence, clinical endpoints) with intended claims and channel strategy before committing to large‑scale supply agreements.
-
De‑risk procurement through staged qualification: prioritize suppliers with active regulatory dossiers for markets where prescription status applies; for nutraceutical channels, secure long‑term contracts with flexible volume clauses to manage spot price volatility.
-
Invest in differentiated clinical evidence: a modest investment in targeted clinical or mechanistic work can unlock higher margin medical channels and protect against rapid commoditization in supplement markets.
-
Consider partnership routes with originator brands: licensing, co‑promotion, or supply arrangements with originator firms accelerate market entry and provide comparative reference products for regulatory filings.
-
Prepare for M&A windows: with supply consolidation and regulatory filings accelerating, 2026 is likely to be fertile ground for bolt‑on acquisitions—use our M&A yardstick and scenario valuations to screen targets.
How to use this preview and next steps
This article is a strategic preview designed to surface the critical decision levers for 2026. The full PW Consulting Zinc L‑carnosine Market report contains the detailed datasets, supplier dossiers, segmented demand tables, price benchmarking, and downloadable financial models that commercial teams, procurement leads, regulatory affairs, and corporate development groups will need to execute with confidence. To access the complete intelligence package—including the granular regional and application splits that underpin tailored go‑to‑market plans—please visit our report page.
For bespoke consulting engagements, scenario runs customized to your product portfolio, or confidential supplier diligence informed by our supplier interviews and primary supply‑chain checks, PW Consulting’s industry team is available to support rapid decisioning throughout 2026.
For detailed analysis of this topic, please visit the official page: Zinc L-carnosine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com