

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electrically Heated Windshield Market for EVs to Reach USD 3,043.51 Million by 2032 at a 14.12% CAGR — Asia Pacific Leads with USD 526.44M

Electrically Heated Windshields for EVs: A Strategic Preview for 2026 Decision-Making
PW Consulting’s new market study on Electrically Heated Windshields for EVs presents a timely, actionable intelligence package aimed at executives who must convert winter-performance innovation into durable commercial advantage. The global market for electrically heated windshields has moved from niche technology to a strategic EV systems component: our model shows the market more than doubled between 2020 and 2025, reaching roughly USD 1.2 billion (Million USD) in 2025, and is forecast to grow at a compound annual growth rate (CAGR) of 14.12% across the 2026–2032 horizon to exceed USD 3.0 billion by 2032.
Electrically Heated Windshield for EV Market
Why this matters for 2026 planning
-
Energy efficiency now equals safety and comfort in EV purchasing criteria. Electrically heated windshields materially reduce HVAC load during cold-start conditions—an important lever to protect real-world driving range.
Electrically Heated Windshield for EV Market -
Electrified vehicle electrical architectures (notably the growing adoption of 48‑volt subsystems) are lowering the integration barrier for higher-power glass-based heating solutions. This is shifting heated windshields from nice-to-have luxury options into core thermal management strategy for mainstream EV platforms.
Electrically Heated Windshield for EV Market -
Market concentration is meaningful: the sector exhibits mid-to-high supplier concentration, underscoring supplier negotiation power, technology differentiation stakes, and M&A interest among glass OEMs, Tier‑1s, and new tech entrants.
Snapshot: What our numbers tell you (high-level)
Historical demand doubled in five years, driven by BEV adoption, colder-market feature expectations, and OEM-led comfort-safety differentiation. The forecast trajectory embedded in our model captures accelerating adoption as OEM platforms standardize higher-voltage architectures and as more efficient heating technologies commercialize. These macro dynamics create a multi-year runway for suppliers and OEMs, but success will hinge on integration costs, energy trade-offs, certification timeframes, and component supply resilience.
Report value: practical outputs for corporate decision-makers
-
Executive Decision Playbook: scenario-based recommendations for OEMs, Tier‑1s and suppliers to prioritize product investments, specification timing, and partnership models through 2026.
-
Market Model & Sensitivity Toolkit: a transparent forecasting engine (2026–2032) with configurable levers—adoption curves, power-architecture mix, and price erosion—that executives can use to stress-test product and pricing strategies.
-
Commercial Benchmarking: supplier scorecards that combine technical differentiation, supply capacity, certification track record, cost position, and OEM relationships—designed to support sourcing and co-development decisions.
-
Integration & Systems Guide: engineering-level checklists for electrical architecture compatibility (including 48‑volt adoption), ADAS camera/window optics considerations, and NVH/lamination trade-offs to accelerate time-to-vehicle.
-
Raw Material & Supply Risk Matrix: procurement playbooks and hedging strategies for PVB/PVA and specialty glass inputs, including scenario planning for observed price volatility and export headwinds.
-
M&A and Partnership Roadmap: valuation frameworks for acquiring or partnering with specialist technology firms (e.g., pulsed electro-thermal providers), with deal structures to protect IP and scale manufacturing rapidly.
Competitive landscape: who moves the market
Our competitive analysis blends product-level engineering differentiation with go-to-market posture. Key incumbents and challengers typify three strategic archetypes: traditional glass OEMs evolving coatings and wire embedding; specialist thermal-tech startups commercializing disruptive low-energy approaches; and OEMs internalizing glass heating to protect system-level range.
-
AGC Inc. (AGC Automotive) — plays to its glass‑OEM strengths with both conductive coating (invisible) and ultra‑fine wire approaches, positioning solutions explicitly for EV thermal management. Its dual-technology portfolio reduces client integration friction and supports multiple platform strategies.
-
Pilkington (NSG Group) — leverages established wire‑heated windshield competency and ADAS integration experience. Their proposition is speed-to-defog/defrost with compatibility for advanced driver assistance sensors—a clear value for OEMs targeting cold-climate reliability.
-
Fuyao Glass — focuses on cost-competitive manufacturing and targeted heating zones (wiper, sensor, camera) through tungsten micro-wires laminated within PVB. This zone-targeting is relevant where cost and selective functionality trump full-surface heating.
-
Saint‑Gobain Sekurit — differentiates via invisible conductive coatings (ClimaCoat) combined with heat‑reflective glass formulations, positioning for OEMs seeking integrated all‑weather performance while maintaining optical clarity for ADAS cameras.
-
Betterfrost Technologies — represents a category-defining specialist. Their pulsed electro‑thermal deicing (PETD) delivers fast clear‑times with demonstrable energy reduction versus HVAC defrost. Recent 2026 testing shows commercial traction with OEMs and Tier‑1s; this modality is attracting attention where rapid-clear times and low energy draw are prioritized.
-
Hyundai Motor Group / Genesis — as a technology adopter and developer, Genesis’ public demonstrations of a 48‑volt metal‑coated heated glass on electrified models signal a potent integrator strategy: OEMs can capture system-level energy savings by pairing glass heating with platform electrical architectures.
Collectively, these players illustrate a market in which competitive advantage will come from multi-technology roadmaps, high-quality lamination and coating expertise, fast qualification cycles for ADAS compatibility, and supply footprint close to major vehicle assembly centers.
Supply chain, raw materials, and regulatory headwinds
-
Raw material dynamics: PVB interlayers and PVA inputs remain central to lamination and wire embedding. Recent price movements and export dynamics require procurement contingency planning; small unit-cost shifts can materially change glass BOM economics at scale.
-
Certification and optical safety: electrically heated glazing must satisfy automotive glazing standards (e.g., ECE R43, FMVSS 205) while preserving ADAS camera performance. Plan for longer qualification paths where new coatings or heating topologies alter optical properties.
-
Electrical architecture fit: the rise of 48‑volt subsystems meaningfully improves the energy and integration case for higher‑power glass heaters. OEM platform strategy decisions in 2026 should explicitly include heated‑glass power budgets and harmonize with HVAC, battery thermal management, and vehicle energy management software.
Technology trajectories and trade-offs
Two technical families dominate: embedded fine‑wire heating and invisible conductive coatings; a third—pulsed electro‑thermal deicing (PETD)—is emerging as a disruptive energy-efficient alternative. Selection drivers are clear:
-
Fine wires: rapid, evenly distributed heating and proven ADAS compatibility when properly engineered; potential compromises in optical uniformity if not ultra‑fine.
-
Conductive coatings: invisible aesthetics and improved optical continuity for cameras, with power and coating durability trade-offs that require rigorous environmental testing.
-
PETD: very low steady-state energy consumption and fast clear times, but system-level integration (control electronics, pulse drivers) and long-term reliability data are still maturing.
Our report includes comparative P&L-level modeling of these approaches, showing where lifetime energy savings and customer-experience premiums offset higher unit costs.
Implications for corporate strategy in 2026
-
OEMs should codify heated‑glass strategy in platform value engineering: decide whether to insource, co-develop, or buy from established glass OEMs based on volume forecasts and ADAS requirements.
-
Glass OEMs and Tier‑1s should converge product roadmaps with electrical architecture and ADAS teams to shorten qualification cycles—time-to-spec will determine early-adopter economics.
-
Material suppliers and contract manufacturers must build price-risk mitigation into long-term supply agreements for PVB/PVA and specialty coatings.
-
Investors and M&A teams should evaluate specialists—particularly PETD providers—for bolt-on acquisitions to capture energy-efficiency differentiation, but structure earn-outs tied to OEM qualification milestones.
What’s in the full PW Consulting report (practical table of contents)
-
1) Executive summary & strategic recommendations
-
2) Market sizing & forecast model (2020–2032) with downloadable model
-
3) Segmentation analysis (region, technology, vehicle type) and adoption scenarios
-
4) Supplier benchmarking and capability heatmaps
-
5) Detailed technical annex: coating chemistries, wire metallurgy, lamination methods, and testing protocols
-
6) Procurement and raw-material risk playbooks
-
7) Integration checklists for OEM systems engineering
-
8) M&A & commercial partnership guidance with valuation templates
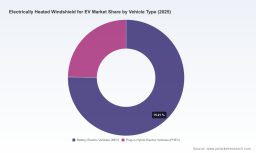
Note: this preview intentionally omits the granular regional, technology, and vehicle-type revenue splits that form the heart of the model. Those segment-level outputs—and supporting appendices with supplier price decks, BOM scenarios, and regional adoption curves—are available in the full report and the downloadable forecast tool.
Next steps for executives
-
Download the forecast model and run platform-specific scenarios (we provide templates keyed to battery pack size, 12/48‑volt subsystem availability, and expected cold‑climate penetration).
-
Initiate supplier dialogues using our scorecards to accelerate qualification with those that align to your integration roadmap.
-
Design pilot programs that combine one glass OEM and one PETD specialist to evaluate trade-offs across range preservation, user experience, and unit-cost outcomes within your 2026 program timelines.
PW Consulting’s Electrically Heated Windshield for EVs report is designed as a strategic instrument for 2026 planning cycles—giving you the market model, technical comparators, and commercial playbooks needed to convert winter-performance innovation into durable product and financial advantage. For access to the full dataset, supplier-level appendices, and the downloadable forecast workbook, please visit our report landing page.
For detailed analysis of this topic, please visit the official page: Electrically Heated Windshield for EV Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com