

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Industrial‑Grade Borated Polyethylene Market Set to Expand at a 5.18% CAGR Through 2032

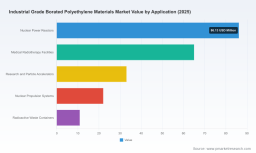
Industrial Grade Borated Polyethylene Materials Market: Strategic Imperatives for 2026
Executive summary
PW Consulting’s latest market intelligence on industrial grade borated polyethylene (BPE) delivers a focused strategic playbook for executives making near-term and medium-term decisions in 2026. Built from primary interviews, plant-level supply chain mapping, patent landscaping and proprietary financial modelling, the report quantifies the market’s current footprint and projects a clear growth trajectory: the industry base reaches roughly USD 217 million in 2025 and is forecast to expand to just over USD 309 million by 2032, implying a compound annual growth rate of approximately 5.18% across the 2026–2032 forecast window.
Industrial Grade Borated Polyethylene Materials Market
Why this matters for 2026 decision-makers
-
Capital allocation: With predictable, mid-single-digit CAGR, BPE is transitioning from a niche safety commodity to a portfolio-level component in energy, medical and defense asset plans. CFOs and strategy leads must now weigh steady organic growth against options for targeted capacity investments or bolt-on acquisitions.
Industrial Grade Borated Polyethylene Materials Market -
Supply chain resilience: Lead times and certification requirements increasingly differentiate suppliers. Procurement teams need an evidence-based sourcing matrix rather than ad-hoc vendor selection to avoid schedule slippage on nuclear and medical projects.
Industrial Grade Borated Polyethylene Materials Market -
Regulatory and technical risk: Compliance with military and nuclear specifications and the long service-life expectations of spent-fuel and reactor applications create unique product qualification burdens. Engineering and quality heads must plan multiyear validation programs now to be procurement-ready for projects coming online in the late 2020s.
Market dynamics driving 2026 choices
Demand is being shaped by three durable vectors: the continued renewal and expansion of civilian nuclear capacity in several markets; steady growth in medical radiotherapy infrastructure; and ongoing investments in research facilities and defense platforms that require certified neutron shielding. These drivers interact with supply-side realities—manufacturing capacity, certification lead times, and the availability of boron-loaded feedstocks—to determine who wins competitive opportunities.
Regulatory frameworks and military specifications remain a gating factor. Our analysis highlights the practical implications of long-standing standards that govern material composition and aging allowances for spent-fuel and naval applications. For procurement and engineering teams this means qualification timelines can be measured in quarters, not weeks—impacting vendor selection, contract terms and contingency planning.
Segmentation and product evolution (what we analyze, not what we disclose)
The report dissects the market across product formulations, boron loading bands, and application end-markets, and it tracks price and performance trade-offs between low-, mid- and high-loading variants. We do not publish the complete breakdown in this executive summary – the enclosed analysis in the full report preserves granular split data – but our findings emphasize a clear trend: customers increasingly demand higher functional density (more boron per unit volume) where mass and footprint matter, while cost-sensitive applications continue to favor standard loading grades with optimized manufacturing tolerances.
From a materials perspective, manufacturers are investing in process controls and secondary operations (CNC, waterjet cutting, custom fabrication) to expand addressable use-cases. For manufacturers and OEMs, the choice is between expanding fabrication capabilities to capture margin or outsourcing value-added work to regional partners for speed to market.
Competitive landscape — who to watch and why
The BPE supply base blends legacy specialty plastics producers, regional fabricators, and a growing pool of lower-cost suppliers. Our competitive review focuses on strategic positioning rather than raw sales figures, identifying the capabilities that matter most in 2026:
-
Proprietary processing and dimensional control. Firms that own specialized sheet extrusion or flattening processes provide differentiating product consistency for critical shielding panels—an important selling point in medical vault and reactor applications.
-
Certification and quality systems. Manufacturers registered to military and aerospace specifications and to ITAR/ASTM regimes shorten procurement cycles for defense and nuclear customers and justify premium pricing.
-
Customization and downstream services. Suppliers offering extensive CNC/waterjet cutting, custom blocking, and in-house fabrication capture additional value and reduce integration risk for installers and EPC firms.
-
Geographic and logistical reach. Regional stocking and quick-ship capabilities matter for time-sensitive retrofits and site fit-outs.
Illustrative vendor profiles in the report highlight how market participants are leveraging these capabilities. Some firms emphasize proprietary processing and flatness control to serve high-spec industrial customers; others compete on breadth of boron-loading options and aggressive lead times. Recent market activity—trade show visibility by marquee producers and strategic partnerships with national nuclear programs—reinforces a maturing commercial ecosystem where reputation, certification and service depth shape win rates.
Supply, pricing and margin dynamics
Raw-material cost sensitivity and the unit economics of higher-loading formulations drive product-level margin dispersion. Manufacturers with vertically integrated compounding or tight supplier agreements for boron additives maintain better gross margins when market prices spike. At the same time, buyers increasingly demand supplier-level transparency on aging performance and hydrogen density characteristics for long-life installations—creating an opportunity for suppliers that can demonstrate robust testing and lifecycle assurances.
Risk, regulation and compliance checklist for 2026
-
Material specifications: Close adherence to established military and nuclear material specifications is non-negotiable for many end markets. Expect procurement to require documented testing and traceability as part of standard RFPs.
-
Qualification lead times: Allow for extended validation timelines, especially when switching suppliers or introducing new boron loadings on certified projects.
-
Geopolitical and trade exposure: Sourcing strategies should model supply interruptions and potential tariff or export-control impacts across manufacturing nodes.
-
Lifecycle performance: Design safety margins and maintenance plans must account for conservative hydrogen-density de-ratings applied by regulators to account for aging.
Actionable guidance and tools included in the report
PW Consulting delivers pragmatic, decision-grade instruments tailored for 2026 execution:
-
Interactive financial model: Sensitivity-tested cash flow scenarios across capacity expansion, price compression and raw-material volatility.
-
Supplier selection matrix: A weighted evaluation framework that maps performance, certifications, lead times and after-sales capabilities to buyer priorities.
-
Go-to-market playbooks: Segmented strategies for suppliers targeting nuclear, medical and defense channels, including recommended commercial terms and partnership structures.
-
M&A and partnership shortlist methodology: A reproducible approach to identifying targets or JV partners that close capability gaps while preserving certification continuity.
-
Risk heat map: A triaged view of operational, regulatory and market risks with mitigation options and contingency triggers.
Implications for key stakeholders
-
Corporate Strategy: The market’s established growth profile makes BPE a defendable area for strategic focus. Decisions in 2026 should prioritize deals and investments that shorten customer qualification cycles and expand fabrication services.
-
Procurement: Implement the supplier selection matrix to balance cost, certification time and continuity risk. Prioritize dual-sourcing for mission-critical projects.
-
R&D and Engineering: Invest in accelerated qualification protocols for higher-loading materials and composite laminates that meet both neutron attenuation and longevity requirements.
-
Investors: Expect stable volumetric growth with pockets of premium margin for certified, service-rich suppliers. Private equity and strategic buyers should look for differentiated service models and certification-led barriers to entry.
What the full report provides (and why you’ll want it)
The complete PW Consulting report extends the preview above into a comprehensive suite of intelligence: detailed market sizing and verified time-series demand, scenario-based forecasts, supplier benchmarking, a complete regulatory compliance matrix, price index analysis and a downloadable financial model. To preserve competitive value for clients and to adhere to our “trailer” approach, we intentionally withhold certain granular segmentation tables and vendor share breakouts from this press release. These are available in the full report where subscribers can also access raw data and our underlying assumptions.
Next steps
For strategy teams preparing budgets and procurement pipelines in 2026, now is the time to validate assumptions, test alternative sourcing scenarios, and align certification roadmaps with project timelines. PW Consulting is offering limited advisory slots to translate this market intelligence into a tailored sourcing or M&A plan that fits your organization’s risk appetite and growth objectives.
To access the full report, download the data workbook, or schedule a briefing with our senior industry analysts, please visit the PW Consulting report page or contact our research desk for a confidential discussion.
For detailed analysis of this topic, please visit the official page: Industrial Grade Borated Polyethylene Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com