

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PLA Biodegradable Stretch Film Market to Grow at 12.99% CAGR, Reaching USD 1,799.75 Million by 2032

PLA Biodegradable Stretch Film Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
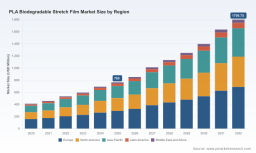
PW Consulting’s latest market study on the PLA biodegradable stretch film market delivers a focused, decision-ready view for leadership teams preparing plans in 2026. Built on a 2025 base year (with historical coverage from 2020–2025 and forecast through 2026–2032), the report quantifies a market that has roughly doubled in scale since 2020 and is poised to continue rapid expansion. Our modeling shows total market revenue rising from USD 765.0 Million in 2025 to USD 1,799.75 Million by 2032, representing a compounded expansion trajectory consistent with a 12.99% CAGR across the forecast window.
PLA Biodegradable Stretch Film Market
Why this matters now
-
Timing: 2026 is the inflection year for many procurement and innovation programs. Regulatory momentum, buyer preference shifts, and improving PLA supply economics are converging to make commercial launches and scale-ups materially more attractive this year.
PLA Biodegradable Stretch Film Market -
Margin and sourcing pressure: Raw-material dynamics and regional cost divergence are already affecting supplier selection and margin expectations. Our price and feedstock analysis highlights a narrow but meaningful band of PLA cost structures across primary markets, and a lactic-acid and PLA industry that expanded in value between 2025 and 2026 — a factor buyers and CFOs must model into 2026 budgets.
PLA Biodegradable Stretch Film Market -
Commercial differentiation: Brand owners and logistics operators face accelerating demands for credible compostable alternatives to conventional stretch film. Firms that lock in validated suppliers, performance-tested formulations, and compliant certification frameworks in 2026 will hold a decisive advantage in RFPs and sustainability reporting cycles in 2027–2028.
What PW Consulting’s report delivers — practical, executable intelligence
The report is structured to give immediate, operational lift to strategy, procurement, product, and M&A teams. Key deliverables include:
-
Market sizing and validated forecasts (2020–2032) with scenario layers that stress-test demand under conservative, base, and accelerated adoption paths.
-
Driver and restraint maps tying policy, circular-economy infrastructure, and feedstock economics to short- and medium-term adoption curves.
-
Supply-chain and cost models: landed-cost templates, supplier scorecards, sourcing playbooks, and a raw-material sensitivity matrix that quantifies EBITDA exposure to PLA price moves.
-
Regulatory and compliance roadmaps that translate EU directives, national single-use plastics restrictions, and export-compliance expectations into actionable checklists for product development and labeling.
-
Procurement negotiation kits and pilot-to-scale implementation guides, including sample technical acceptance criteria, testing protocols, and consumer-claims guardrails for compostability certifications.
-
Competitive landscape analysis and M&A playbooks that prioritize targets by technological fit, manufacturing footprint, and capability to deliver PLA/PBAT blends at scale.
-
Risk register and mitigation playbooks covering feedstock fluctuation, certification misalignment, composting infrastructure gaps, and substitution threats from other bio-based resins.
Competitive landscape: who’s shaping the market and how
The market exhibits a moderate concentration profile: the top three suppliers command a significant niche presence while the top five broaden that influence. This structure creates a dual-speed market — established players able to supply global programs, and nimble regional specialists that drive innovation in formulations and localized service models.
-
YITOPACK (Huizhou Yito Packaging Co., Ltd.) — A leading Chinese OEM focusing on PLA and PLA/PBAT blends for pallet wrapping. Strengths include scale manufacturing for industrial logistics applications and the capacity to provide customizable thicknesses and specifications tailored to customer handling systems.
-
RTG Films — US-based converter specializing in compostable PLA films with clear grades suitable for sustainable stretch and packaging. Their market positioning is built on conversion expertise and integration with North American supply chains.
-
BUHE Technology Ltd — Chinese producer emphasizing PLA + PBAT blends positioned as compostable alternatives without microplastic risk. Their go-to-market focus is industrial pallet wrapping where compostability claims must be defensible.
-
Hongren Packing — A China-based supplier with a certification-led proposition (OK Compost, EN13432, BPI). They serve customers requiring documented end-of-life performance and export-ready certification packs.
-
Torise Biomaterials — Specializes in tailored PLA/PBAT films with engineering emphasis on clarity, strength, and consistency — attractive to brand owners seeking parity with conventional film performance.
-
Taghleef Industries — A global player offering biodegradable BoPLA films (Nativia® line). Their international production footprint and product breadth make them a logical partner for multi-region rollouts.
-
Shanghai Yifu Packaging, Chintec, Hubei HYF, Easy Flux — Regional manufacturers driving localized innovation, speed-to-market, and competitive pricing. Collectively they serve fast-moving segments including food, retail, and domestic logistics.
Raw materials and regulatory context
PLA production remains anchored in renewable feedstocks, principally corn-derived starch, which continues to represent the majority route-to-market for PLA monomers. The upstream lactic-acid and PLA value chain expanded meaningfully between 2025 and 2026, reflecting both capacity additions and higher commercial uptake. PLA feedstock costs vary by market; in early 2026 we observed a meaningful band of regional price differentials that suppliers and buyers must account for when comparing landed costs and negotiating multi-territory contracts.
On the regulatory front, Europe’s sustained restrictions on single-use plastics and a mosaic of more than 70 national-level bans are accelerating adoption of PLA-based alternatives for packaging. Complementary policy drivers in China (industrial-park biodegradable packaging programs and export-aligned compliance) are encouraging PLA-PBAT hybrids as practical industrial solutions. These policy forces make 2026 a critical year for firms to align technical specifications with credible end-of-life claims and to secure supply certainty ahead of tightened compliance windows.
Scenarios and risks that should shape your 2026 roadmap
-
Price volatility: PLA feedstock swings will influence commercial thresholds for replacing conventional PE-based stretch films. Hedged purchasing and multi-supplier strategies are prudent.
-
Certification vs. infrastructure mismatch: Compostability claims are only as valuable as the composting infrastructure to process them. Market winners will couple claims with downstream processing partnerships or take-back pilots.
-
Performance trade-offs: PLA/PBAT blends bridge the mechanical gaps versus conventional film, but technical benchmarking against customer handling systems remains essential to avoid claim-based recalls or uplift costs.
-
Supply concentration: With a moderate top-tier concentration in the vendor pool, single-source exposures can create lead-time and pricing risk for large-scale rollouts.
Priority moves for 2026 — a tactical checklist
-
Procurement: Implement a two-tier sourcing strategy (global preferred suppliers + regional fast-fail converters) and model landed cost scenarios against PLA price-band sensitivities.
-
Product development: Prioritize PLA/PBAT formulations for pallet-wrap applications that meet minimum durability thresholds; embed certification and on-package guidance from the outset.
-
Commercial pilots: Launch targeted logistics pilots with tier-1 carriers and distribution centers where composting or industrial processing can be documented.
-
M&A and partnerships: Screen acquisition targets that provide either capacity to scale or specialized formulation IP that shortens time-to-market for clear, high-strength grades.
-
Regulatory readiness: Map your product claims to regional waste-processing realities and prepare labeling, chain-of-custody, and certification dossiers to support global tenders.
How PW Consulting’s report helps you execute in 2026
This publication is deliberately tactical. It equips commercial, procurement, and technical teams with the precise inputs they need to set 2026 budgets, prioritize pilots, and negotiate supplier contracts with confidence. The full report includes downloadable cost-model workbooks, supplier scorecards, test protocol templates, and an interactive scenario dashboard designed to stress-test programs against PLA price and policy shifts.
Next step
We have deliberately provided this preview to surface the strategic implications and practical actions companies must consider in 2026. The full report contains the detailed segmentation, supplier datasets, and localized market intelligence that procurement and product teams require to operationalize the recommendations shown here. Access the complete study to obtain the granular supplier profiles, regional matrices, and downloadable decision tools that will convert 2026 opportunity into measurable commercial outcomes.
For detailed analysis of this topic, please visit the official page: PLA Biodegradable Stretch Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com