

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
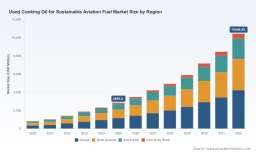
PW Consulting: Used Cooking Oil for Sustainable Aviation Fuel Market to Skyrocket from USD 2,865.4 Million in 2025 to USD 10,448.7 Million by 2032 at a 20.31% CAGR

Used Cooking Oil for Sustainable Aviation Fuel: PW Consulting Strategic Briefing for 2026 Decision-Makers
Executive snapshot
The global market for used cooking oil (UCO) as a feedstock for sustainable aviation fuel (SAF) is shifting from opportunistic aggregation to strategic industrialisation. PW Consulting’s latest market study shows the UCO-for-SAF market growing from roughly USD 2.87 billion in 2025 to an expected USD 3.49 billion in 2026, and continuing on to an estimated USD 10.45 billion by 2032 — an implied compound annual growth rate of 20.31% for the forecast horizon. For executives making 2026 capital, procurement and partnership decisions, the window to secure resilient feedstock chains and value-capture routes is narrow but actionable. This briefing outlines the report’s strategic value, the drivers reshaping the market, competitive dynamics to watch, and the practical tools included in our full deliverable that boardrooms will need as SAF policy and commercial realities converge.
Used Cooking Oil for Sustainable Aviation Fuel Market
Why 2026 is a strategic inflection point
-
Policy front-loading: Aviation-specific mandates and national SAF programmes that became effective in 2025 are now binding commercial decisions in 2026. Early compliance pathways such as HEFA using UCO are the dominant near‑term route for many markets; evolving quota timetables materially change demand profiles for certified waste feedstocks.
Used Cooking Oil for Sustainable Aviation Fuel Market -
Incentives and localisation: Regional incentive structures — notably production tax credits in North America with feedstock eligibility conditions — create asymmetries in feedstock economics and sourcing priorities. These rules are decisive when choosing between local aggregation, imports and co-processing strategies.
Used Cooking Oil for Sustainable Aviation Fuel Market -
Supply squeeze and price volatility: Increasing demand for both SAF and biodiesel has elevated UCO market tightness. Market participants are already experiencing significant price swings and episodic supply tightness, forcing procurement teams to decide between short-term spot purchases and longer-term offtake or vertical integration.
Market dynamics that will shape corporate plays in 2026
Our analysis highlights four interacting dynamics that should guide every 2026 strategic plan:
-
Demand certainty from regulatory mandates: Regional SAF blending mandates have moved the sector from speculative demand to structural offtake. Early-compliant feedstocks (notably UCO for HEFA pathways) are the default supply pool in many jurisdictions while alternative pathways scale.
-
Policy-driven regional arbitrage: Incentives that tie credits or subsidies to domestically sourced feedstock create trade flows that can rapidly realign procurement maps. Corporates must model both tariff and subsidy regimes simultaneously when sizing assets or negotiating supply.
-
Aggregation economics: Collecting UCO at scale requires dense logistics networks, contamination management and traceability systems. Scale and trusted collection partners materially lower delivered feedstock cost and quality risk.
-
Price and feedstock transparency: Volatility in bulk UCO prices has become a tactical variable for operations and contracting teams. Hedging tools, indexed contracts and blended feedstock strategies reduce short-term margin erosion but require robust data inputs.
Competitive landscape: positioning and strategic moves
The UCO-to-SAF ecosystem is already populated by a mixture of global refiners, specialised collectors, vertically integrated biofuel producers and national oil companies. Market concentration indicators in our study show a moderately consolidated structure: the top three firms account for around 38.4% of market supply by volume, while the top five approach approximately 52.2% — leaving meaningful room for strategic partnerships and consolidation targeted at the mid‑market.
Key strategic archetypes and representative players include:
-
Global integrated renewables leaders (scale + conversion capability): Companies with refinery footprints, proprietary HEFA capacity and aggregation networks are pursuing a full-value-chain play. Their advantage is end-to-end control of quality, certification and logistics, which shortens time-to-market for SAF sales and secures higher margin capture.
-
Collectors and logistics specialists: Firms focused on UCO aggregation, preprocessing and certification are increasingly critical partners for refiners and airlines. Their strategic options include exclusive long-term supply contracts, regional consolidation and investments in preprocessing to improve feedstock yields.
-
National oil companies and integrated refiners: State-backed and major refiners are deploying co-processing and dedicated HEFA units to secure domestic SAF supply. Their balance-sheet strength and fuel distribution networks accelerate market placement but require feedstock assurances that collectors must provide.
-
Emerging tech and regional converters: Smaller players and technology licensors are moving to prove scaleable, cost-competitive routes for converting UCO and other wastes. Their strategic value lies in niche capabilities and potential licence or JV upside with larger offtakers.
Recent market actions we highlight as case studies: long-term supply arrangements that lock volumes; first commercial shipments by refiners transitioning to SAF delivery; and plant ramp-ups returning capacity to market. These moves exemplify the strategic choices facing buyers and investors: secure contracted volumes at premium, invest in aggregation capability, or pursue co-processing to diversify feedstock options.
Strategic implications and recommended 2026 actions
-
Prioritise feedstock security over lowest-price procurement: Given mandate-driven demand and episodic price spikes, procurement strategies that prioritise multi-year, indexed offtakes and exclusive collection partnerships reduce supply risk and support financing of conversion assets.
-
Design contracts for policy and market volatility: Include clauses for subsidy reallocation, tariff shifts and feedstock eligibility changes. Where relevant, reserve capacity for domestic feedstock to retain incentive eligibility.
-
Invest in traceability and pre-processing: Quality variability is a persistent source of conversion inefficiency. Investment in preprocessing hubs, sampling protocols and digital traceability improves yield predictability and simplifies certification compliance.
-
Evaluate consolidation and partnership targets actively: The mid-market remains fragmented; acquisitive players can rapidly scale aggregation capabilities by targeting regional collectors and logistics specialists with strong local relationships.
-
Scenario-test conversion routes: Compare HEFA versus co-processing economics under differing feedstock availability, credit regimes and carbon prices. Align capital deployment with the route that best matches offtake structure and policy risk tolerance.
What PW Consulting’s report delivers to support 2026 decisions
Our full PW Consulting report is built as a practical decision-support suite for executives and investment committees. Deliverables include:
-
Proprietary market sizing and forecast model with downloadable worksheets — enabling custom scenario runs for prices, mandates and feedstock mixes across the 2026–2032 horizon.
-
Supply-chain maps and collection-density analytics — visualised catchment areas for aggregation hubs, estimated collection costs under differing contamination profiles, and logistics optimisation levers.
-
Contracting and procurement playbook — clause libraries for offtake, quality warranties, force majeure and indexation mechanisms adapted for UCO markets and incentive regimes.
-
Investment and M&A playbook — valuation templates, due-diligence checklists for feedstock assets, and integration roadmaps for collectors and converters.
-
Policy and incentive modelling toolkit — sensitivity analyses showing how mandate trajectories and tax-credit rules alter project IRRs and required offtake terms.
-
Competitive intelligence dossiers — strategic profiles of major collectors, refiners and converters, recent deal activity and a CR3/CR5 concentration dashboard to support strategic positioning.
-
Primary-data appendices: a curated dataset of supply agreements, recent commercial shipments and a vetted list of collection specialists and technology providers — maintained behind the report gateway.
To preserve the strategic value of the dataset and to respect commercial confidentiality in competitive segments, detailed regional and application-level splits and certain contract-level metrics are provided exclusively in the full report and interactive workbooks.
Closing guidance for boardrooms and investors
For corporate strategists, the next 12–18 months are a race for credible, contractually-secured feedstock and for conversion capacity alignment with offtake channels. For investors, the uneven regional incentive landscape and still-fragmented aggregation market create differentiated opportunities for roll-up strategies, strategic partnerships with refiners, and early-stage technology bets. PW Consulting’s analysis shows that participants who align procurement, policy hedging and vertically integrated economics early will be best placed to capture disproportionate value as SAF volumes transition from niche compliance to a structural fuel market.
How to access the full intelligence
This briefing is a strategic preview. Our comprehensive report contains the full datasets, model templates and supplier-level dossiers referenced above. For subscription access, bespoke briefings tailored to a company’s asset or procurement footprint, or to schedule a workshop on how to operationalise these insights in 2026, please visit PW Consulting’s report page or contact our advisory team.
For detailed analysis of this topic, please visit the official page: Used Cooking Oil for Sustainable Aviation Fuel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com