

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
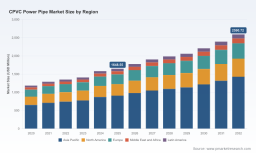
PW Consulting: CPVC Power Pipe Market to Reach USD 2.59 Billion by 2032 at 6.67% CAGR—Asia‑Pacific Leads with USD 908.1M in 2025

CPVC Power Pipe Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive preview from PW Consulting’s 2026 market intelligence suite
As power networks, telecom backbones and industrial plants accelerate upgrades, the market for CPVC power pipe is entering a phase of sustained expansion and strategic complexity. Our new PW Consulting report — covering historical performance (2020–2025) and forward forecasts through 2032 — synthesizes demand drivers, supply-chain pressures and competitive positioning into a decision-ready narrative for corporate leaders planning 2026 investments.
Cpvc Power Pipe Market
Market trajectory at a glance
After a five-year expansion through 2025, the CPVC power pipe market reached an estimated USD 1,648.6 million (base year 2025). Our model projects a continuation of growth into the forecast window (2026–2032) at a compound annual growth rate (CAGR) of 6.67%, lifting total market value toward approximately USD 2,590.7 million by 2032. The transition from retrofit-centric demand in earlier years to a blended mix of urban grid modernization, telecom cable protection upgrades and industrial infrastructure investment underpins this trajectory.
Cpvc Power Pipe Market
These headline figures are the starting point. What matters for 2026 decisions are the underlying vectors — where demand concentrates, how input-cost volatility will affect margins, and which capability investments will yield the best risk-adjusted returns. The report translates headline growth into actionable scenarios for manufacturers, EPC contractors, utilities, and strategic investors.
Cpvc Power Pipe Market
Why 2026 is a strategic inflection
- Capital cycles align with policy windows: Many utilities and governments entering multi-year modernization programs will finalize procurement roadmaps in 2026 — creating near-term volume opportunities and contractual lock-ins.
- Raw material and trade dynamics are fluid: Feedstock price movements and policy actions in 2025 have already reshaped supply economics, and 2026 will be the first year when these impacts fully propagate through procurement and customer pricing.
- Competitive posture matters more than ever: Market concentration remains moderate (CR3 ≈ 21.45%, CR5 ≈ 32.18%), meaning scale, integrated-resin relationships and certification breadth will decide which suppliers capture high-value contracts.
Supply-side dynamics and cost levers
Three forces will dominate supplier economics in 2026:
- Feedstock pricing and availability: CPVC production is closely tied to PVC resin and chlorine feedstock cycles. Notably, spot PVC-related prices were softer in Q2 2025 (with a quarter-over-quarter decline of approximately 5.96% in North America), while US CPVC pricing reached near USD 2,370/MT in June 2025. These moves create both margin pressure and purchasing windows for buyers with flexible sourcing strategies.
- Regulatory intermittency: Environmental audits and tighter emissions controls in 2025 constrained output in several production hubs, particularly in China and parts of Europe, generating transitory supply tightness for import-dependent regions. Compliance-driven capacity curtailments are likely to recur as regulators enforce upgraded standards.
- Trade and tariff volatility: Sharp tariff actions in the 2025 period increased pricing premiums for regions reliant on imports. For 2026 procurement planning, tariff risk needs to be treated as a first-order variable in supplier selection and localization decisions.
For operators and procurement teams, these dynamics translate into concrete trade-offs between spot buys, long-term contracts and near-sourcing investments. The report provides modeled cost curves and procurement scenarios to stress-test these choices under alternative feedstock and tariff pathways.
Segmentation and demand patterns (high level)
Demand for CPVC power pipe is anchored by three application clusters: urban power grid upgrades, telecommunications and cable protection, and industrial/power-plant infrastructure. Each cluster exhibits distinct project rhythms, qualification needs and price sensitivity. Our analysis maps the implications of these differences for product specification, lead times and warranty design — without disclosing proprietary segment allocations in this summary.
Key takeaways for 2026 strategy:
- Urban grid programs favor suppliers with project and logistics scale, tight quality control and long-track records on system integration.
- Telecom and cable-protection projects prioritize conduit integrity, low-install-cost solutions and agile delivery, often favoring specialized channel partners.
- Industrial and power-plant clients demand high-temperature performance, traceability and stringent compliance pedigree, creating premium pockets within the market.
Competitive landscape — capabilities that matter
The CPVC power pipe arena blends global resin leaders, established North American and European manufacturers, and highly capable regional producers across Asia. In our review, key competitors demonstrate discrete strengths:
- Resin and compound leadership: Firms with integrated resin capability maintain a dual advantage: control over raw-material availability and influence over compound specifications. This vertical edge shortens lead times and supports higher-margin engineered lines.
- System suppliers and certification breadth: Manufacturers offering end-to-end systems (pipes, fittings, valves) with robust third-party certifications (e.g., NSF/ANSI) are preferred in regulated projects and public tenders.
- Regional manufacturing & distribution footprints: Local production capacity in high-growth markets reduces tariff exposure and improves responsiveness to utility-defined schedules.
Representative company archetypes we analyze in the full report include long-established North American producers with domestic manufacturing and compliance pedigrees; European thermoplastic specialists providing full-system solutions; and large regional manufacturers across South Asia and China focused on cost competitiveness and local project penetration. Each archetype faces different strategic imperatives in 2026, from downstream integration to export-risk mitigation.
What the PW Consulting report delivers (operational takeaways)
The full report is built for executives who must convert market projections into executable plans in 2026. It contains:
- Scenario-driven revenue models for 2026–2032 reflecting alternative macro, price and regulatory assumptions.
- Supplier risk heatmaps and procurement playbooks that integrate price, lead-time and compliance vectors.
- CapEx prioritization templates for manufacturing scale-up, near-shoring and certification roadmaps.
- Commercial negotiation templates and TCO calculators calibrated for CPVC-specific inputs (resin linked costs, tariffs, logistics premium).
- M&A readiness and target-screening criteria for buyers pursuing inorganic growth in core and adjacent segments.
- Regulatory impact assessment, including country-level constraint scenarios and mitigation approaches for import-dependent markets.
These tools are grounded in our proprietary databases and scenario engines, which synthesize historical performance (2020–2025) with forward-looking demand drivers to produce stress-tested strategies — not just static forecasts.
Strategic actions recommended for 2026
Based on the analysis, PW Consulting recommends that stakeholders prioritize three strategic actions this year:
- Lock strategic feedstock agreements with flexible clauses: Given ongoing feedstock price volatility and tariff risk, suppliers and large buyers should negotiate contracts with indexed pricing collars and capacity guarantees to preserve margins while retaining optionality.
- Invest selectively in near-shoring and certification: Target investments that reduce tariff exposure and shorten lead times for high-value projects. Certifications and traceability investments unlock premium tenders and reduce compliance friction in regulated markets.
- Differentiate on solutions not just product: Move from component sales to system solutions (value-added fittings, life-cycle services, warranty programs) to capture higher-margin pockets and deepen customer stickiness.
How to use the intelligence in 90 days
- Week 1–2: Validate exposure — map your 2026 tender pipeline against supplier concentration and tariff-exposed regions.
- Week 3–6: Run the PW procurement scenario models with your actual cost inputs to identify optimal contracting strategies (spot vs. hedged volume).
- Week 7–12: Execute targeted supplier negotiations or short-term near-shoring pilots to insulate mission-critical projects from feedstock shocks.
Access and next steps
This brief is a strategic preview designed to surface core market dynamics and executive priorities. The full PW Consulting CPVC Power Pipe Market report contains the detailed segment models, supplier profiles, contract templates and downloadable financial models that operational teams will need to execute on the 2026 agenda. For procurement directors, plant managers and corporate strategists, the report converts macro trends into procurement-ready actions and investment choices.
To obtain the full report, detailed scenario tables and the proprietary decision tools described above, please visit our official report page. PW Consulting clients can contact their account lead for expedited delivery and a tailored briefing session.
PW Consulting — converting market insight into executable advantage for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Cpvc Power Pipe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com