

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
PW Consulting: Resorcinol Derivative For Skincare Market Poised to Reach USD 387.97 Million by 2032, Expanding at a 7.8% CAGR
By pmarketresearch, 2026-07-13
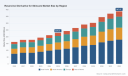
Resorcinol Derivative for Skincare Market: A Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on Resorcinol Derivatives for Skincare provides executive teams with a compact, strategy-forward synthesis of how this niche yet fast-growing segment will shape product pipelines, supply chains, and M&A agendas in 2026. Our work synthesizes historical performance (2020–2025), a rigorously modeled 2026–2032 forecast, competitive intelligence, regulatory risk mapping and actionable commercial playbooks — all calibrated to support near-term decisions without overloading readers with granular segment-level disclosure in this preview.
Resorcinol Derivative For Skincare Market
Market snapshot: Where the market stands and where it’s headed
The resorcinol-derivative market for skincare reached approximately USD 229.3 Million in the base year (2025) and is projected to expand at a compound annual growth rate (CAGR) of 7.8% during the 2026–2032 forecast horizon, reaching roughly USD 388.0 Million by 2032. This pace reflects a convergence of persistent demand for targeted brightening and antioxidant actives, accelerating product innovation in specialty actives, and selective premiumization among skincare consumers in key markets.
Resorcinol Derivative For Skincare Market
For corporate strategists, the headline numbers imply two immediate imperatives: (1) allocate R&D and commercialization resources to differentiated resorcinol-based actives that can demonstrate efficacy and safety in regulated jurisdictions; (2) shore up supply-chain flexibility to manage the well-documented volatility in upstream feedstocks that materially affect manufacturing economics.
Resorcinol Derivative For Skincare Market
Supply-chain and pricing dynamics
- Upstream feedstock exposure: Resorcinol economics remain tightly correlated with benzene and phenol markets. Recent regional pricing snapshots illustrate how feedstock swings transmit quickly to manufacturers’ cost bases, creating short windows where margins compress or temporarily expand. Executives must assume continued input-price variability when modeling product-level margins and procurement strategies.
- Regional cost dispersion: Price differentials persist across geographies due to capacity, logistics and feedstock sourcing. These differences create arbitrage opportunities for contract manufacturing and tolling strategies, but also raise counterparty risk when sourcing from single-origin suppliers during supply constraints.
- Raw-material hedging and sourcing playbook: The report outlines practical hedging frameworks and supplier segmentation matrices that help procurement teams translate volatile feedstock markets into predictable COGS scenarios for multi-year product launches.
Regulatory dynamics and their strategic implications
Regulation is the single most consequential non-market force for resorcinol derivatives in personal care. Regulatory authorities in major blocs continue to scrutinize resorcinol’s sensitization profile. Under existing EU frameworks, its use in oxidative hair dyes is restricted and accompanied by labeling requirements—an important precedent when arguing safety dossiers. Scientific committees have provided specific use-limit opinions for certain product categories, noting moderate skin sensitization potential at elevated concentrations.
For product teams and regulatory affairs, this translates to three tactical priorities for 2026:
- Design formulations to meet conservative safety thresholds and prepare robust human repeat insult patch testing (HRIPT) and in vitro sensitization dossiers.
- Accelerate alternative-derivative safety evaluation and comparative risk-benefit studies to support higher-value claims without regulatory friction.
- Pre-position regulatory submissions and labeling strategies for top-priority markets to avoid launch delays caused by unpredictable local interpretations.
Competitive landscape: concentration, capability and recent moves
Market concentration metrics indicate moderate consolidation: the top three players account for a meaningful share of the market, and the top five exert substantial combined influence. This structure shapes negotiation dynamics across pricing, innovation partnerships and distribution.
The competitive roster combines specialty ingredient houses and chemical producers. Key strategic archetypes include:
- Ingredient specialists that combine proprietary chemistries with application support and claim substantiation — exemplified by firms offering branded actives tailored to hyperpigmentation and brightening formulations.
- Large diversified chemical groups that leverage global manufacturing scale and raw-material integration to compete on cost and availability.
- Regional high-purity suppliers and specialty producers focused on cosmetic-grade resorcinol and niche derivatives for formulators seeking local sourcing and flexible order sizes.
Notable industry developments to monitor: in late 2025 a major chemical manufacturer launched a new line of chlorinated resorcinol derivatives expressly targeted at cosmetic formulators, underscoring supplier-level moves to broaden active portfolios and capture formulation share. For strategic teams, supplier roadmaps and IP positioning around new derivative chemistries warrant immediate attention.
Segmentation & growth pockets — a disciplined tease
Our analysis identifies clear pockets of demand within the broader skincare use-case set: brightening/depigmentation, antioxidant/anti-aging support, and targeted blemish therapies. Each pocket has distinct go-to-market and evidence requirements — from claim substantiation studies and aesthetic clinical trials for brightening actives to antioxidant stability and delivery optimization for anti-aging positioning.
While this preview intentionally omits granular split data, the full report maps where R&D investment and commercial focus should be concentrated to capture outsized returns. It also flags “white space” formulations where resorcinol derivatives can displace incumbents or function as differentiation layers in multi-ingredient systems.
What PW Consulting’s report delivers — practical, deal-ready intelligence
The full report is structured to be immediately operational for corporate and investor teams. Deliverables include:
- Demand-modeling suite with scenario-based forecasts, sensitivity testing, and revenue curves calibrated to multiple commercialization timelines.
- Supplier and capacity heat maps identifying high-risk single-source nodes and alternate manufacturing pathways for rapid scale-up.
- Regulatory matrix and pre-submission checklist tailored to major regional authorities, accompanied by a prioritized evidence-generation plan for claims support.
- Competitive profiles and benchmarking intelligence that go beyond public marketing, capturing product portfolios, patented derivatives, and formulation support capabilities.
- Commercial playbooks: pricing strategies, channel roll-out sequencing, co-development frameworks for ingredient-brand partnerships, and distributor engagement templates.
- M&A and partnership scorecards that surface attractive acquisition targets and JV candidates based on strategic fit, margin accretion potential, and regulatory positioning.
How 2026 exec teams should use this intelligence
For C-suite and business-unit leaders evaluating resorcinol derivative participation in 2026, we recommend a three-tiered decision flow:
- Prioritize: Use the report’s revenue-scenario outputs to rank product concepts by NPV-adjusted upside under conservative regulatory constraints.
- Mitigate: Implement the supply-chain and raw-material playbooks to limit exposure to upstream price shocks and single-supplier risks during pilot and scale phases.
- Differentiate: Invest in clinical substantiation and novel derivative chemistries where permitted — this is the most reliable pathway to command premium pricing in an increasingly crowded brightening market.
Case in point: translating insight into strategy
An international CPG player exploring a premium brightening line can use the report to model three launch scenarios: a conservative EU-first strategy that minimizes regulatory friction; an Asia-led premiumization path emphasizing rapid claim-to-market; or a hybrid approach that stages launches while building a global claim dossier. Each scenario comes with discrete procurement and formulation templates we provide, enabling the company to decide not only whether to enter but how to structure contracts, co-development agreements and pricing ladders.
Why this report matters for 2026
Resorcinol derivatives occupy a strategic intersection: they are science-driven, regulation-sensitive, and materially exposed to feedstock economics. That combination means derivatives will remain attractive to companies that can integrate regulatory foresight, supply resilience and clinical validation into their product planning. Our forecasting shows clear growth and multiple routes to commercial success, but success will require disciplined execution informed by forward-looking risk models — the very deliverables at the core of our report.
Next steps — get the full intelligence
This article is a strategic preview designed to surface the most consequential levers we see for 2026. PW Consulting’s full Resorcinol Derivative for Skincare Market report contains the underlying datasets, scenario models, and tactical templates needed to move from strategy to execution. For licensing, bespoke briefings, or to commission a tailored executive workshop that applies the findings directly to your product pipeline or M&A pipeline, contact our industry practice team.
PW Consulting remains committed to equipping decision-makers with market-proven frameworks and evidence-based forecasts that convert uncertainty into actionable strategy. Access the full report to view detailed segment maps, supplier scorecards, and the complete financial models that underpin the forecast — the intelligence you need to shape successful skincare portfolios in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Resorcinol Derivative For Skincare Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Robust Nylon Rod Market Expansion — 5.42% CAGR Expected Through 2026–2032
By pmarketresearch, 2026-07-13
Nylon Rod Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence Brief
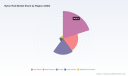
PW Consulting’s latest Nylon Rod Market report — grounded on a 2025 base year and a 2026–2032 forecast horizon — delivers the high-fidelity market intelligence senior executives need to make confident, value-accretive decisions in 2026. The global nylon rod market was sized at USD 628.54 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.42% through the forecast horizon; our base-case pathway points to approximately USD 909.49 Million by 2032. This release summarizes the strategic takeaways and decision-ready insights contained in the full report while preserving the fine-grained segmentation and model outputs that are available exclusively in the complete study.
Nylon Rod Market
Why this report matters for 2026 planning
- Actionable macro-to-micro linkages: We bridge high-level demand growth (mid-single digit CAGR) with granular operational levers — raw material exposure, grade mix, manufacturing footprint, and customer-channel dynamics — so procurement, operations, and corporate development teams can translate market signals into three-to-five-year investment plans.
- Near-term volatility mapped to strategic choices: The nylon value chain is being re-priced by raw material and regulatory movements. Our scenario suite quantifies the impact of feedstock shocks and policy shifts on margin, utilization, and payback timelines, enabling CFOs and divisional leaders to stress-test capex and M&A under realistic stress cases.
- Competitive positioning with execution playbooks: Beyond ranking suppliers and technologies, the report provides replicable playbooks — for pricing, channel expansion, and spec-substitution — that manufacturing and commercial teams can apply immediately.
Key market dynamics shaping 2026 decisions
- Feedstock and price volatility: The nylon rod cost base remains sensitive to upstream chemicals. In early 2026, major producers signalled price movement — including a caprolactam and PA6 pricing action announced by a leading producer in March 2026 — and regional adipic acid pricing has shown material swings in recent quarters. Our proprietary cost-curve model translates such moves into product-level margin impacts, identifying which grades and manufacturing routes are most resilient.
- Regulatory and trade risk: Decarbonization frameworks, such as evolving ETS coverage of nitrous oxide (N2O) from caprolactam processes and potential inclusion of upstream costs via mechanisms like CBAM, create new compliance costs and carbon-intensity differentials across supply sources. Concurrently, trade enforcement actions in certain raw-material markets are changing import economics. The report contains an actionable regulatory-risk matrix that flags where near-term policy developments could force sourcing and pricing changes.
- Consolidation pressure with niche strength: The market displays moderate concentration: our analysis indicates the top three players hold roughly one-third of market value while the top five approach half — a structure that leaves substantial room for regional champions, specialized cast-rod players, and value-chain integrators to exploit niche advantages. We map where scale matters and where technical differentiation commands premium pricing.
- End-market demand nuances: Demand growth is uneven across downstream industries. Industrial machinery and transportation-related applications remain important demand pillars, with emergent pockets of premiumization driven by electrification, automation, and food-contact regulatory requirements. Our demand-sensing framework identifies where material substitution and specification tightening are likely to accelerate purchasing cycles in 2026–2027.
What’s inside the report: practical, executable modules
The PW Consulting Nylon Rod Market report is structured for execution, not just insight. Key modules include:
Nylon Rod Market
- Market sizing & method appendix: Transparent base-year assessment, forecasting logic, and sensitivity levers. Our models reconcile consumption, production, trade, and inventory flows to produce a defensible market baseline.
- Supply chain mapping & cost curves: From monomer feedstocks to finished rod machining yields, we quantify conversion costs and identify the highest levers for margin recovery (e.g., scrap reduction, throughput optimization, grade selection).
- Raw-material surveillance tool: A concise dashboard that ties adipic acid, caprolactam, and other upstream inputs to finished-rod price elasticity; includes scenario outputs for recent price moves and announced supplier adjustments.
- Regulatory impact assessment: A chapter on emissions, trade remedies, and food-contact/electrical safety regimes with direct implications on operating permits, product claims, and market access.
- Commercial playbooks: Go-to-market templates for margin improvement — pricing ladders, OEM partnership models, distributor agreements, and value-add machining services.
- M&A & partnership screening: A prioritized list of target archetypes, valuation sensitivities, and integration risk maps tailored to both strategic acquirers and private equity sponsors.
- Plant-level techno-economic model: A modular Excel tool for site selection, brownfield expansion, and retrofit economics that internal teams can run with their own CAPEX/OPEX assumptions.
Competitive landscape: who to watch and why
The study profiles global and regional players that shape supply, product breadth, and technical capabilities. Representative companies analyzed include:
Nylon Rod Market
- Nylatech, Inc. (United States) — North American leader in cast nylon sheets, rods, and fabrication for heavy industrial uses; notable for custom machining capabilities and close OEM relationships ( https://www.nylatech.com/).
- Ensinger GmbH (Germany) — European supplier with deep capabilities in cast nylon shapes and wide-diameter offerings; differentiates through material modifications for machining and engineering-grade applications ( https://www.ensingerplastics.com/).
- Cast Nylons Limited (CNL) (United States) — A large North American cast nylon producer with established brand platforms for specialty lubricated and oil-impregnated materials.
- Modern Plastics, Inc. (United States) — Emphasizes certified supply for heavy industries; recent public positioning highlights certified capabilities for mining and material-handling segments ( https://modernplastics.com/).
- Dura Polymers (India) — A lower-cost regional producer serving textile, mining, and marine sectors, illustrative of the competitive tension between cost and customization.
- Ningbo Yinzhou Qishan Nylon Rod Mfg. Co., Ltd. (China) — Supplier cross-certified for multiple engineering plastics and capable of scale in cast rod production ( https://www.jinggu-plastics.com/).
- Distributor and specialist channels — Emco Plastics, Piedmont Plastics, Professional Plastics, Trident Plastics and others play pivotal roles in spec-sensitive, low-volume, high-mix channels and food-contact niches.
For commercial and corporate development leaders, the implication is simple: partnerships and local-service propositions will outcompete pure cost plays in many industrial applications, while scale and raw-material integration remain decisive where automotive and electrical-grade volumes concentrate.
Immediate strategic recommendations for 2026
- Hedge selectively and restructure purchasing: Following recent upstream price moves, adopt a layered procurement strategy that blends short-term hedges with strategic volume agreements; prioritize flexibility in contracts to manage regional regulatory cost pass-throughs.
- Prioritize product/market fit over scale in targeted segments: Invest in spec-driven value propositions (e.g., self-lubricating grades, FDA-compliant grades, metal-detectable variants) in segments where customers trade on performance and compliance.
- Accelerate low-regret decarbonization moves: Implement energy-efficiency and N2O abatement pilots at high-utilization sites to pre-empt compliance costs and create carbon-differentiated product narratives for buyers.
- Deploy the plant-level TEA for greenfield vs retrofit decisions: Use our techno-economic module to identify which brownfield upgrades unlock the quickest paybacks versus greenfield investments that capture future-growing geographies.
- Screen M&A for capability, not just capacity: Prioritize targets that offer channel access, technical depth, or downstream integration potential; avoid roll-ups that increase exposure to raw-material volatility without commensurate margin uplift.
Scenario planning: what to model now
Our clients are running three prioritized scenarios for 2026: a baseline reflecting mid-single-digit growth (aligned with the reported CAGR), an adverse scenario capturing sustained feedstock inflation and tightened trade conditions, and an upside scenario driven by accelerated electrification and specification upgrades in transportation and industrial automation markets. The full report includes scenario-specific P&L and ROI pathways for a set of archetypal businesses (contract manufacturer, regional cast-rod specialist, and vertically-integrated polymer producer).
How to use the report in your 2026 planning cycle
- Incorporate the report’s cost-curve and feedstock dashboard into quarterly procurement reviews to set price floors and escalation clauses.
- Use the plant TEA to prioritize capital allocation and define brownfield projects that meet a minimum IRR under conservative feedstock assumptions.
- Leverage the M&A screening chapter to build a 12–24 month pipeline of targets with quantified synergies and integration risk scores.
- Adopt the commercial playbooks to pilot new sales channels and value-added services, particularly in regulated food-contact and electric-vehicle supply chains.
Get the full intelligence
PW Consulting’s Nylon Rod Market report delivers the complete dataset, segmentation tables, and model outputs required to operationalize the strategies summarized above. The document contains the full regional and application-level breakdowns, detailed company profiles, and downloadable financial models — elements we intentionally withhold in this briefing to protect the proprietary work and to ensure you receive the full analytical context when accessing the report.
To obtain the detailed forecasts, sensitivity tables, and executable playbooks that support robust 2026 planning, please visit the PW Consulting report page or contact our industry team. In a market where raw-material shocks, policy shifts, and rapid specification changes are the new normal, this intelligence is designed to convert uncertainty into competitive advantage.
For detailed analysis of this topic, please visit the official page: Nylon Rod Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Melanin Market to Grow at 5.82% CAGR, Reaching USD 21.03 Million by 2032
By pmarketresearch, 2026-07-13
Melanin Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
Executive teaser
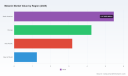
PW Consulting’s latest Melanin Market report — a comprehensive study with a 2025 base year and a 2026–2032 forecast horizon — is designed as a decision-grade playbook for corporate leaders, investors, and R&D strategists charting activity in this niche but fast-evolving specialty biomaterial sector. Measured in USD Million, the global market is estimated at 14.15 in 2025 and is projected to expand to just over 21.0 by 2032, reflecting a compound annual growth rate (CAGR) of 5.82% over the forecast window. This report synthesizes historical trends (2020–2025), mapped supply chains, regulatory friction points, and forward-looking scenarios to inform near-term investments and operational pivots in 2026.
Melanin Market
Why 2026 is a turning point
-
Macro-growth with micro-level friction: The sector’s mid-single-digit CAGR masks significant variation across applications and raw material pathways. For executives, this combination means attractive topline growth but elevated execution risk — particularly in raw-material sourcing, certification timelines, and route-to-market for higher-margin functional applications.
Melanin Market -
Regulatory inflection: Our field interviews and proprietary survey work show that a sizable share of producers have encountered regulatory hurdles when certifying natural melanin for pharmaceutical-grade use; many batches routinely undergo additional purity and safety certification. At the same time, harmonization gaps across regions continue to translate into material shipment delays and uneven market access.
Melanin Market -
Productization is accelerating: Recent commercial activity demonstrates a bifurcation between ingredient suppliers focused on high-purity, research-grade materials and formulators pushing application-specific solutions — from UV-absorbing cosmetic actives to bioelectronic functional films. These dynamics will redefine value capture across the value chain in 2026.
What the PW Consulting report delivers (operationally actionable content)
-
Supply‑chain heatmaps and resilience levers — granular mapping of upstream feedstocks, processing nodes, and logistics chokepoints with prioritized mitigation actions for 12- to 24-month horizons.
-
Regulatory playbook — a step-by-step certification roadmap for natural and synthetic melanin in cosmetics and pharmaceutical contexts, including a matrix of certification gatekeepers and recommended third‑party labs for accelerated approval.
-
Commercial segmentation framework — an outcomes-focused taxonomy that helps commercial teams choose target end-markets and craft pricing strategies without exposing proprietary split data in public channels.
-
Supplier and partner scorecards — a pragmatic sourcing toolkit to benchmark suppliers across quality, capacity, geographic redundancy, and compliance readiness, designed for integration into procurement sprints.
-
Innovation and IP roadmap — focused R&D priorities with technology readiness assessments, including opportunities in biomimetic synthesis, fermentation-derived melanin, and semiconductor-grade deposition techniques.
-
Scenario-based financial models — stress-tested revenue and margin outcomes under alternative raw-material inflation, regulatory delay, and adoption curves for high-growth applications.
-
M&A and partnership playbook — criteria-based screens for bolt-on acquisitions, strategic JV partners, and licensing models aimed at accelerating market entry or acquiring technical leadership.
Competitive landscape — who to watch and why
The market demonstrates a moderate degree of concentration: established specialty chemical and life-science distributors sit alongside nimble biotech suppliers and vertically integrated manufacturers. Collectively, leading firms command a substantial portion of the addressable market, but opportunities remain for targeted challengers with differentiated technology or supply-security advantages.
-
BIOFOUNT (Beijing; EU operations in Amsterdam) — strong production capability in high‑purity lines positions BIOFOUNT as a preferred partner for pharmaceutical and research-grade opportunities. Their cross‑regional footprint is a competitive advantage for customers seeking multi‑jurisdictional supply continuity.
-
The Innovation Company (Dreux, France) — commercializes sepia-derived melanin with a clear cosmetics focus. Their positioning as a natural antioxidant and UV-filter supplier illustrates the premium that formulators place on traceability and application-specific claims.
-
Biosynth (Staad, Switzerland) — a diversified catalog of synthetic and fungal-derived melanins, often used as standards and research reagents. Biosynth’s model underscores the recurring demand for certified reference materials within R&D ecosystems.
-
AdooQ BioScience (Irvine, CA) — a research-chemical specialist supplying high‑purity melanin that addresses life‑science and biomedical research use cases where analytic consistency matters most.
-
Hubei Xinkang Pharmaceutical Chemical Co., Ltd. (Hubei Province) — bulk chemical manufacturer emphasizing scale and cost-efficiency. Their profile highlights the bifurcation between commodity supply and specialty high‑purity offerings.
-
Thermo Fisher Scientific; MilliporeSigma (Merck KGaA); BOC Sciences; Spectrum Chemical — large distribution and reagent businesses that aggregate demand across laboratory, pharmaceutical, and industrial channels. Their brands serve as de‑risking layers for customers needing global distribution, certified material quality, and continuity.
Recent market movements to monitor in 2026
-
Chemyunion’s early‑2026 product collection launch — bringing active peptides and biotech-derived actives focused on pigmentation and hair greying — signals increasing cross-pollination between ingredient manufacturers and finished-product claims, creating both collaboration and competitive pressure for raw melanin suppliers.
-
DreamSkin AI’s platform debut — an AI-trained personalization engine built on melanin‑rich skin datasets — highlights the rapid rise of data-enabled formulation approaches. Companies that can couple ingredient performance data with personalization engines will capture disproportionate value.
-
The Innovation Company’s continued promotion of sepia melanin in cosmetic catalogs underscores the steady commercial demand for nature-derived claims, even as synthetic routes scale.
Regulatory and raw‑material headwinds
-
Certification friction is real: a significant proportion of producers report regulatory hurdles when clearing natural melanin for pharmaceutical use, and a meaningful share of production batches are subject to additional purity and safety testing. For supply‑side managers, this creates both a time-to-market premium and an opportunity to monetize certification expertise.
-
Standards fragmentation: inconsistent quality standards across regions continue to cause export frictions; in practice, this translated into documented shipment delays in recent years. Companies that proactively align to multi‑jurisdictional certification frameworks will enjoy first‑mover advantages.
-
Feedstock pressure: environmental and land‑use restrictions have materially constrained access to certain plant‑based precursors, forcing producers to accelerate alternative sourcing strategies — including fermentation, microbial biosynthesis, and chemistry-to-biology hybrid routes.
-
Regulatory focus in China: recent notices regarding cosmetic standards point to heightened scrutiny over raw‑material safety control and banned/restricted ingredient lists — developments that will ripple through supplier selection and product labeling strategies in 2026.
Strategic recommendations for 2026 decision-makers
-
Prioritize supply security over lowest-cost sourcing. In a market where certification cycles and regional standards can derail shipments, contractual arrangements that emphasize redundancy, multi-site manufacturing, and co-funded certification roadmaps reduce operational risk and protect time-to-market.
-
Invest selectively in alternative feedstocks and downstream integration. Companies that fund pilot fermentation routes or secure offtakes from specialty producers will be better positioned to control quality and margin as natural feedstock availability tightens.
-
Differentiate through application engineering. The fastest path to higher margin is not raw material arbitrage but application‑specific formulations: UV-stable cosmetic blends, bioelectronic ink formulations, and injectable-grade materials for biomedical uses. Prioritize partnerships that couple ingredient expertise with formulation science.
-
Make certification a commercial asset. Turn third‑party testing and documentation into a commercial differentiator: pre‑certified SKUs, co‑branded dossiers, and lab-as-a-service offerings materially shorten buyer procurement cycles.
-
Prepare an M&A pipeline focused on capability and location. Small- to mid‑sized manufacturers with production flexibility, proprietary purification know‑how, or access to regulated feedstocks will be the most valuable targets in 2026–2027.
-
Leverage digital and AI tools. Data-driven personalization platforms and analytical-grade standards will amplify ingredient value; companies that pair melanin supply with performance analytics and clinical datasets will command premium pricing.
How to use this report in practice
For C-suite leaders, the report provides a diagnostic and prescriptive template: identify which part of the value chain you occupy, stress-test existing contracts against certification and logistics shocks, and deploy capital to close the most impactful capability gaps. For procurement and R&D teams, the deliverables include supplier scorecards, lab-validation checklists, and integration guides to shave months off qualification cycles. For investors and corporate development teams, the scenario models and M&A playbook convert market momentum into prioritized targets and deal rationales.
Conclusion — a teaser with intent
The melanin market today sits at the intersection of life‑science rigor, specialty chemicals scale, and consumer-driven claims. Growth is healthy and predictable at the macro level, but strategic winners in 2026 will be defined by execution against three interlocking dimensions: supply security, certification leadership, and application differentiation. PW Consulting’s Melanin Market report equips decision-makers with the analytics, playbooks, and scenario tools needed to act decisively — while intentionally withholding proprietary split tables and supplier performance matrices to guide you to the full dataset and supplier benchmarks available via our report portal.
Next steps
-
Download the full report for detailed segmentation, supplier benchmarking, and the executable regulatory playbook.
-
Schedule a strategy workshop with PW Consulting to translate the report’s findings into a 90‑day implementation plan tailored to your position in the value chain.
For detailed analysis of this topic, please visit the official page: Melanin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Salmon PDRN API Market Poised to Expand at an 18.8% CAGR Through 2032
By pmarketresearch, 2026-07-13
Salmon PDRN API Market: Strategic Intelligence for 2026 Decision-Making
Executive preview
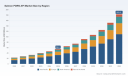
PW Consulting’s latest Salmon PDRN API Market report delivers an actionable intelligence package designed for executive teams, business development leads, and R&D strategists preparing for critical decisions in 2026. The market for salmon-derived polynucleotide (PDRN) active pharmaceutical ingredients has evolved from a niche regenerative-medicine input into a fast-growing, commercially diverse ecosystem. Our analysis quantifies that evolution: after a sustained compound annual growth trajectory through 2020–2025, the market is forecast to continue expanding at an 18.8% CAGR across the 2026–2032 horizon. By anchoring strategy to this growth profile and to the structural dynamics of supply, regulation, and product innovation, stakeholders can convert market momentum into defensible commercial advantage.
Salmon Pdrn Api Market
Why this market matters in 2026
PDRN—largely extracted from salmon sperm/testes or milt—has demonstrated high biocompatibility for tissue regeneration applications, underpinned by a reported near-genomic similarity to human DNA. That biological affinity, combined with increasing clinical integration in dermatology and wound care, has propelled demand across aesthetics, topical therapeutics, and medical wound-healing protocols. For companies positioned in API manufacturing, contract supply, or downstream device and product development, 2026 is a pivotal year: regulatory clarity in key markets, scale-ups announced by leading producers, and accelerating clinical adoption converge to create windows for market entry, partnership consolidation, and differentiated product launches.
Salmon Pdrn Api Market
Market trajectory and macro sizing
Our longitudinal market model shows consistent expansion from the historical base period through the 2025 report year, followed by a robust forecast to 2032. The market size in the report base year reflects the stage of commercialization achieved by 2025, and the forecast projects continued scaling through 2032 under a baseline scenario driven by clinical adoption and new product introductions. The 18.8% CAGR across the forecast window encapsulates recurring demand from aesthetic and regenerative use-cases, increasing pharmaceutical-grade procurement, and cross-border trade in API supply.
Salmon Pdrn Api Market
Competitive structure — concentration and strategic players
The market is already concentrated. The top three suppliers account for a dominant share of commercial supply, and the top five consolidate an even larger portion of accessible capacity, reflecting significant barriers to entry around GMP manufacturing, raw-material traceability, and regulatory documentation. High concentration favors incumbent suppliers but also raises tactical opportunities for focused challengers—particularly those that can demonstrate differentiated purity, endotoxin control, or validated sustainable sourcing.
- HTL Biotechnology (Javené, France) — Positions itself on pharma-grade polynucleotides, emphasizing gentle extraction techniques to preserve molecular integrity and a suite of molecular weights suitable for both topical and injectable uses. Their regulatory-facing deliverables (including submission-ready CTD-formatted Active Substance Master Files) make them a natural partner for firms pursuing regulated product pathways.
- Havdis AS (Bergen, Norway) — Emphasizes GMP-grade, endotoxin-controlled PDRN from Atlantic salmon with certifications spanning major regulatory frameworks. Their focus on traceability and sustainability responds to buyer expectations for ethical sourcing and auditability.
- PharmaResearch Co., Ltd. (Gangneung-si, South Korea) — A fast-moving commercial innovator with a vertically integrated model: proprietary processing (DOT™ technology), a portfolio of marketed dermal products, and recent capacity investments. Notably, PharmaResearch completed a new GMP-certified manufacturing line in late 2025 and launched differentiated consumer-facing formulations, moves that materially shift supply dynamics.
- Bloomage Biotechnology (Jinan, China) — Competes on breadth of supply and product stability claims, pushing PDRN into arthritis and wound-healing talk tracks while showcasing low-endotoxin manufacturing at international industry events.
- Mastelli S.r.l. (Sanremo, Italy) and Nanjing Cuccess Pharmaceutical (Nanjing, China) — Legacy and diverse-sourcing players respectively, each with historical IP and manufacturing techniques in polynucleotide extraction and finishing. Their presence supports a differentiated set of supply partners for European and Asian customers.
Recent industry developments to watch
- Capacity build-outs and product innovation from leading manufacturers (e.g., new GMP lines and novel finished formulations) are compressing lead times and increasing the availability of pharmaceutical-grade PDRN for injectable and topical applications.
- Companies are advancing sustainability and traceability programs—ranging from raw-material stewardship initiatives to participation in habitat restoration—responding both to regulatory scrutiny and buyer procurement policies.
- Regulatory mosaics persist: PDRN formulations have cleared routes to market in dozens of jurisdictions for cosmetic and medical-device applications, but full FDA approval for injectable aesthetic use is not yet universal as of 2026. This uneven regulatory status shapes go-to-market choices and evidence-generation priorities for sponsors.
Supply chain, sourcing and quality imperatives
Sourcing strategy is central to competitive positioning. Salmon-derived PDRN requires traceable raw-material flows (wild-caught by-products or controlled aquaculture), robust purification to minimize endotoxins, and validated pasteurization or filtration processes to remove residual proteins and contaminants. From a procurement lens, buyers are prioritizing GMP certification, supply continuity assurances, and supplier documentation such as Active Substance Master Files or equivalently comprehensive dossiers. For manufacturers, investments in flexible molecular-weight fractionation and low-endotoxin finishing provide commercial optionality across both injectable and topical product pipelines.
Regulatory and reimbursement dynamics
The regulatory environment is simultaneously an accelerant and a constraint. Several PDRN-containing products have secured clearances or approvals for cosmetic and medical-device indications across many jurisdictions; these pathways have facilitated clinical adoption in dermatology and wound care. However, regulatory asymmetries persist—particularly for injectable aesthetic indications in the United States—creating a bifurcated market where strategic regulatory planning and targeted clinical evidence become differentiators. Reimbursement remains highly localized, with procedural and therapeutic adoption often driven by private-pay aesthetics markets or hospital procurement in wound-care contexts rather than broad public reimbursement.
What PW Consulting’s report contains — practical, executable content
The report is structured for direct application by corporate strategy teams and includes:
- Demand and supply-curve modeling with scenario-based forecasts through 2032 aligned to clinical adoption scenarios;
- A regulatory roadmap mapping approval pathways, evidence requirements, and country-level product positioning considerations for cosmetic, device, and pharmaceutical routes;
- Supply-chain stress-testing: supplier due-diligence scorecards, qualification checklists, and CapEx benchmarking for setting up GMP PDRN production lines;
- Commercial playbooks for API purchasers and finished-goods sponsors—pricing frameworks, contract structures, and a go-to-market cadence for incremental launches;
- Competitive landscaping with supplier capability matrices and strategic gap analysis to identify partnership and M&A targets;
- Clinical and lab-development templates: recommended study designs to support regulatory submission or payer conversations, and analytical expectations for purity, endotoxin, and molecular-weight spec;
- Risk registers and scenario plans addressing raw-material scarcity, regulatory setbacks, and reputational issues tied to sustainability.
Strategic implications and go-to-play recommendations for 2026
- For API manufacturers: prioritize validation of low-endotoxin processes and obtain internationally recognized GMP and dossier-ready documentation; invest selectively in capacity that supports both injectable and topical-grade PDRN to capture cross-segment demand.
- For finished-product sponsors: align product development and clinical programs to the regulatory pathway you intend to pursue—medical-device/cosmetic routes can accelerate market entry in many countries, while pharmaceutical-class approvals require more substantive evidence but offer higher-value positioning.
- For investors and M&A teams: look for bolt-on acquisitions that fill traceability, regulatory dossier, or capacity gaps rather than volume plays alone; with the market concentrated at the top, strategic consolidation is likely to deliver value.
- For procurement executives in aesthetics and regenerative clinics: build multi-sourced supply strategies and demand contractual commitments around lot-release documentation to mitigate exposure to single-supplier concentration.
Why PW Consulting’s analysis is a strategic lever
Our combination of granular supplier due diligence, scenario-based financial modeling, and executable commercial templates turns market data into decision-ready intelligence. The market’s projected compound growth rate and the observed concentration among leading suppliers create both risk and opportunity—the former from potential supply bottlenecks, the latter from the value of early alignment with proven, compliant manufacturers.
Next steps and access
This article is a high-level preview designed to demonstrate the strategic thrust of our Salmon PDRN API Market report while preserving the detailed, proprietary segment analysis that informs investment-grade decisions. To review the full dataset, supplier scorecards, regulatory matrices, and the downloadable playbooks that underpin these recommendations, please consult the full report on our website. For bespoke briefings, scenario modeling tailored to your product portfolio, or supplier diligence engagements, contact PW Consulting’s life-science practice to schedule a strategic workshop.
For detailed analysis of this topic, please visit the official page: Salmon Pdrn Api Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flexible Liquid Cooled Cable Market to Surge at 23.01% CAGR, Hitting USD 2,385.19 Million by 2032
By pmarketresearch, 2026-07-13
Flexible Liquid-Cooled Cable Market: Strategic Imperatives for 2026 — PW Consulting Release
PW Consulting today publishes an executive briefing drawn from our forthcoming Flexible Liquid Cooled Cable Market report, providing senior executives and investment committees with the strategic context they need as they plan for 2026. The market for flexible liquid-cooled cables has evolved from a niche industrial enabler to a critical infrastructure component across ultra-fast EV charging, data center power delivery, and heavy industrial applications. Our analysis synthesizes historical performance, supply-chain realities, regulatory inflection points, and vendor capabilities to show where near-term competitive advantage will be created — and where risks remain embedded.
Flexible Liquid Cooled Cable Market
Market trajectory: robust expansion with structural drivers
Demand for flexible liquid-cooled cables has accelerated sharply over the past half-decade. The global market expanded from roughly USD 145 million in 2020 to an estimated USD 560 million by our 2025 base year, driven by both industrial retrofit cycles and the rapid roll‑out of megawatt-class EV charging infrastructure. As adoption moves from pilots to commercial deployments, our central forecast model projects a compound annual growth rate (CAGR) of approximately 23.0% for the 2026–2032 period, with the market scaling toward the multi‑billion-dollar range by the end of the forecast horizon.
Flexible Liquid Cooled Cable Market
This growth is not evenly distributed across applications or regions; instead, it is concentrated in use-cases that require sustained high currents (hundreds to over a thousand amps) combined with ergonomic handling characteristics. These macro numbers provide the context for 2026 decision-making: the window to secure industrial partnerships, certification paths, and supply-chain resilience is now.
Flexible Liquid Cooled Cable Market
What the report delivers — actionable, decision-grade intelligence
- Quantitative market sizing and baseline-to-2032 forecasts with scenario sensitivities to raw material price swings and accelerated EV adoption curves.
- A regulatory and standards matrix mapping IEC, UL, and ISO requirements relevant to liquid-cooled systems — plus clear pathways to certification for product teams and test laboratories.
- Supplier and technology scorecards that benchmark design approaches (water-glycol vs. oil vs. fluorinated coolants), conductor choices, and manufacturability constraints.
- Supply-chain heat maps that identify single‑source exposures, copper procurement levers, and preferred contract structures for 2026 negotiations.
- Commercial playbooks for OEMs, charge-point operators, and EPCs outlining bundling strategies, service economics, and aftermarket revenue models.
- Go-to-market options, from strategic partnerships and licensing to bolt‑on M&A targets, prioritized by ease-of-integration and ROIC under multiple adoption scenarios.
We intentionally withhold granular regional and application splits in this briefing to preserve the report’s role as the primary source for purchase-level intelligence; those detailed sub‑segment datasets and interactive models are accessible in the full PW Consulting report.
Competitive landscape: consolidation with diverse specialists
The supplier ecosystem is a mixture of specialist fabricators that serve heavy industry and high-current thermal applications, and larger electrical component players rapidly commercializing liquid-cooled solutions for the EV charging market. Market concentration metrics indicate meaningful but incomplete consolidation: the leading three players control a significant share of the market, while the top five consolidate a clear majority — a structure that favors strategic alliances without precluding new entrants from gaining traction through differentiated engineering or regional distribution strength.
- Specialist fabricators (examples include firms with deep histories in induction heating, resistance welding, and furnace leads) are distinguished by custom engineering capabilities, rapid turnaround on repairs, and intimate knowledge of high-current terminalization and coolant routing. Their strengths lie in bespoke solutions and service models tailored to heavy industry maintenance cycles.
- Industrial-scale suppliers and Tier‑1 electrification vendors are commercializing modular, standardized liquid-cooled cable systems optimized for electric-vehicle ultra-fast charging. These players leverage systems engineering, ergonomic design, and global support networks to drive commercial rollouts with large charging-station OEMs and network operators.
- Newer entrants and regional manufacturers are pushing innovation at the conductor and hose-material level, while some vendors specialize in very large cross-section cables for steel and ferroalloy plants — showcasing the breadth of technical pathways in the market.
Key names across both archetypes include recognized specialists in water-cooled power leads and a cohort of established electrification players that have introduced liquid‑cooling products and connector platforms for megawatt-class charging. Recent industry moves — such as product integrations between major connector manufacturers and charger OEMs, and field deployments charging above the megawatt threshold — underscore the rapid shift from prototype validation to commercial utilization.
Regulation, materials, and standards: non-negotiable elements of 2026 strategy
Three practical points for engineering and compliance teams:
- Copper remains the predominant conductor material because it offers the best combination of thermal and electrical performance; high‑conductivity electrolytic grades are commonly specified in performance‑critical leads. Securing material supply and specifying contract provisions for grade and traceability will be decisive for product consistency and warranty performance.
- Product designs typically use specialized protective hoses and high-temperature tubing to enclose stranded conductors and enable coolant circulation without sacrificing flexibility. Design tolerances around bend radius, thermal expansion, and terminal swivels materially affect lifecycle costs and handling ergonomics.
- Liquid-cooled systems must comply with a set of international standards — examples include IEC connector frameworks, UL safety standards, and ISO insulation and touch‑temperature limits — and suppliers who can demonstrate early certification or an auditable path to certification will be preferred partners in 2026 procurement cycles.
Notably, the industry is moving toward formalized safety certifications for megawatt-class systems; the first UL certifications supporting 1 MW-class liquid-cooling systems appeared recently, which is lowering a barrier to commercial scale deployments and giving early movers a durable advantage.
Strategic recommendations for 2026 decision-makers
Based on our modeling and vendor due diligence, PW Consulting recommends the following priority actions for organizations allocating capital or signing supply contracts in 2026:
- Prioritize certified partners: Require suppliers to demonstrate compliance roadmaps (IEC/UL/ISO) and factory test evidence; for charger OEMs, mandate fielded-system performance at target current/power levels as a contract milestone.
- Lock in copper supply with quality specifications: Negotiate grade‑specific clauses (e.g., electrolytic copper grades) and consider hedging strategies to mitigate short-term price volatility.
- Pilot ergonomics and maintainability at scale: For EV charging operators, user handling and replacement turnaround times are operational cost drivers; insist on modular terminations and field-replaceable sections in procurement specifications.
- Design for service revenue: Build service networks and remote diagnostics pathways to capture recurring maintenance margins; warranty frameworks should incentivize preventive replacement of high‑wear interfaces.
- Explore targeted M&A and partnerships: Acquire or partner with specialist fabricators to secure IP around terminalization and large-section joints, or to gain regional manufacturing footprints with lower lead times.
- Invest in lab and field validation: Allocate budget for accelerated life testing and temperature/flow profiling, and fund first-of-kind deployments to validate cooling strategies under realistic duty cycles.
Scenarios and risks
Our scenario analysis centers on two sensitivities that will shape outcomes in 2026: the cadence of EV ultra-fast charger rollouts and raw-material inflation. Under the baseline growth trajectory (the ~23% CAGR outlook), commercial scale deployments and standardized connectors will drive sizable volumes and faster maturation of supplier ecosystems. Upside scenarios incorporate regulatory incentives and faster station buildout, while downside outcomes are dominated by sustained copper price shocks or delays in equipment certification.
Operational risk is concentrated in terminal reliability, cooling loop integrity, and field repairability; each has direct consequences for uptime economics in charging networks and for maintenance budgets in industrial installations.
Why PW Consulting’s guidance matters for 2026
Our report combines granular engineering insight with strategic commercial frameworks: market-sizing that starts from audited historical shipments, a forecast model calibrated to adoption drivers, and a vendor evaluation methodology that blends technical scorecards with commercial viability assessments. For boards and investment committees, this delivers a practical bridge between engineering feasibility and balance-sheet implications — enabling conditioned commitments to capital equipment, supply agreements, and M&A pursuits that will be executed during 2026.
Next steps
PW Consulting’s full Flexible Liquid Cooled Cable Market report includes the detailed segmentation datasets, company scorecards, and downloadable forecast models that underpin the executive recommendations summarized here. For procurement teams, product leaders, and corporate strategists preparing commitments in 2026, these assets are designed to accelerate decision-making while reducing program execution risk.
Contact PW Consulting to request the full report, vendor benchmarking appendices, and an in‑person briefing with our industry analysts.
For detailed analysis of this topic, please visit the official page: Flexible Liquid Cooled Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Balanced Salt Buffer Solution Market to Reach USD 1.39 Billion by 2032 at 7.4% CAGR, North America Leads with USD 327.6 Million
By pmarketresearch, 2026-07-13
Balanced Salt Buffer Solution Market — Strategic Imperatives for 2026
As the life sciences supply chain enters a new phase of growth and operational complexity, PW Consulting’s latest market study on Balanced Salt Buffer Solutions (BSBS) provides an essential strategic compass for executives planning investments, partnerships, and capacity decisions in 2026. Our analysis synthesizes market sizing, channel economics, regulatory pressures, and supplier positioning to deliver decision-ready insight — while preserving the proprietary segment-level intelligence that underpins actionable choices. This release outlines the macro trajectory, competitive context, and recommended moves that will matter most to leaders across suppliers, bioprocessors, and institutional buyers.
Balanced Salt Buffer Solution Market
Market Outlook: Size, Pace and What It Means for Strategy
The Balanced Salt Buffer Solution market has expanded steadily through the first half of the decade and is positioned for continued growth. PW Consulting’s topline model — using 2025 as the base year — values the global market at approximately USD 842.5 million in 2025, with an anticipated rise to roughly USD 923.2 million in 2026. We forecast a compound annual growth rate (CAGR) of 7.4% over the projected horizon, driving the market toward well over USD 1.3 billion by the end of our 2026–2032 forecast window.
Balanced Salt Buffer Solution Market
For corporate strategists, the implication is clear: this is a mid-single-digit-to-high-single-digit growth market large enough to justify targeted capacity investments, but nuanced enough that success will hinge on differentiated product offerings, quality certifications, and supply chain resilience rather than pure scale alone.
Balanced Salt Buffer Solution Market
Key Market Dynamics Shaping 2026 Decisions
-
Quality and Regulatory Compliance as Table Stakes — BSBS products intended for cell culture, bioprocessing, and translational work are manufactured and marketed under stringent quality regimes. Our review of manufacturer documentation highlights universal dependence on cGMP frameworks (e.g., 21 CFR 820) and ISO certifications (9001 / 13485) to meet sterility, endotoxin, and consistency expectations. For commercial leaders, certifications are non-negotiable credentials that drive buyer trust and justify premium positioning.
-
Upstream Input Volatility — Sodium chloride represents a primary upstream feedstock. Industry data show the broader sodium chloride market was valued in the tens of billions of USD in 2025 and is experiencing modest growth; regional pricing dynamics and energy inputs remain key cost drivers. For BSBS manufacturers, small fluctuations in salt and energy costs can meaningfully affect margin when selling lower-priced, commoditized formulations — underscoring the need for hedging strategies and operational flexibility.
-
Concentration with Opportunity — Market concentration is material but incomplete. PW Consulting’s competitive mapping indicates the top three manufacturers capture roughly 42.5% of the market, while the top five control around 58.2%. This structure creates dual opportunities: established players can leverage scale and validated quality systems to defend share, while nimble specialists can seize higher-margin niches through customization, bilateral supply agreements with cell therapy developers, and targeted regulatory positioning.
-
Demand Growth Driven by Advanced Biomanufacturing — End-market demand is being propelled by expanded cell culture, stem cell research, and bioprocessing activities globally. As cell and gene therapy pipelines mature toward later-stage trials and commercial production, demand shifts from research-grade formulations to clinical and GMP-grade buffers, raising both revenue potential and qualification friction for suppliers.
Competitive Landscape: Profiles and Strategic Postures
PW Consulting examined the strategic positions and capabilities of leading BSBS suppliers to identify winning archetypes for 2026.
-
Platform & Scale Leaders — Thermo Fisher Scientific : With its Gibco product family and cGMP/ISO manufacturing footprint, Thermo Fisher exemplifies a full-spectrum supplier able to meet the needs of academic labs through to high-volume biomanufacturers. Their competitive advantage rests on brand trust, global distribution, and integrated quality systems that simplify customer qualification.
-
Industrial OEMs with Life-Science Focus — Cytiva (HyClone) & Corning : Cytiva leverages lab-to-bioprocess expertise and Danaher-scale commercialization muscle, emphasizing reproducibility and regulatory alignment. Corning’s HBSS offerings are positioned within its broader cell culture portfolio, with formulation variants addressing transport and short-term incubation use cases. Both rely on technical legacy and channel breadth to protect share.
-
Specialists & Custom Manufacturers — Boston BioProducts, Nucleus Biologics, Captivate Bio : These firms compete on customization, small-batch cGMP capabilities, and close collaboration with cell and gene therapy developers. Their value proposition is speed-to-spec and flexible formats — an attractive proposition for customers advancing clinical programs who require bespoke buffers and rapid documentation for regulatory filings.
-
Regional & Cost-Focused Players — Procell, Biowest, Sigma-Aldrich (Merck) : These suppliers combine localized manufacturing advantages and a portfolio of sterile-filtered products to serve regional scientists and biomanufacturers. Cost-competitive manufacturing, combined with acceptable quality certifications, helps them retain price-sensitive segments while advancing toward higher-spec opportunities.
-
Device/Consumable Integrators — Sartorius : Firms with adjacent technologies in bioprocessing and cell handling can cross-sell buffer solutions as part of integrated workflows (e.g., washing, transport, and closed-system processing), providing convenience advantages to customers and higher lifetime value for suppliers.
What PW Consulting’s Report Delivers — Practical, Transaction-Ready Intelligence
Our full report goes beyond high-level commentary to provide operational tools for commercial and manufacturing decision-makers. Key deliverables include:
-
Proprietary market-sizing models with scenario-based forecasts calibrated to macroeconomic, raw-material and regulatory variables;
-
Supply-chain diagnostic templates identifying single points of failure and opportunity for near-term de-risking;
-
Pricing benchmarks and margin maps that inform contract negotiation and go-to-market tactics;
-
Qualification roadmaps and checklist playbooks for moving research-grade products into GMP channels; and
-
Competitive intelligence dossiers on leading suppliers — including manufacturing footprints, certification status, product differentiation levers, and partnership case studies — designed to support M&A, JV, and distributor selection.
We intentionally withhold some proprietary segment-level splits and granular revenue-by-application tables from this executive summary in order to preserve the integrity of our modeling and to direct commercial users to the authenticated report for transaction-support materials.
Strategic Recommendations for 2026
-
Differentiate through Quality & Documentation: Secure or upgrade cGMP and relevant ISO certifications if you serve clinical or late-stage bioprocess customers. Investment in validated testing (endotoxin, osmolality, sterility) and detailed batch documentation materially reduces buyer friction and shortens qualification timelines.
-
Move Up the Value Stack: Pursue niche formulations and custom services tailored to cell and gene therapy developers. Premiumized, documented buffers command higher margins and strengthen long-term supply agreements.
-
Hedge Input Risk & Rationalize SKUs: Use procurement strategies for key feedstocks (e.g., salt contracts, energy pass-through clauses) and streamline SKU portfolios to optimize plant throughput and reduce changeover costs.
-
Forge Channel Partnerships: For suppliers without global reach, strategic distributor agreements and co-branded programs can accelerate penetration into regulated markets while preserving capital.
-
Prepare for Consolidation Opportunities: With the top-tier firms controlling a meaningful share of the market, selective M&A or technology partnerships offer an accelerated route to scale and certification access — particularly attractive for specialty players seeking to supply clinical-grade channels.
Operational Playbook for Buyers and Procurement Teams
-
Validate supplier certifications and batch release testing as part of any procurement RFQ for clinical or manufacturing use; include qualification timelines and audit provisions in contracts.
-
Build multi-supplier strategies for critical formulations and consider regional dual-sourcing to mitigate transport-related disruptions.
-
Negotiate longer lead-times for custom formulations but include performance-based SLAs and change-control frameworks to protect timelines for downstream production.
Conclusion — Why 2026 Is a Pivotal Year
The BSBS market in 2026 is neither a pure commodity race nor a narrow bespoke niche; it is a hybrid arena where rigorous quality compliance, supply-chain resilience, and targeted product differentiation determine winners. PW Consulting’s forecasted growth path and concentrated supplier landscape both create opportunities and pressing strategic choices for incumbents and new entrants alike. Companies that align investments in certification, formulation innovation, and procurement sophistication will convert growth into durable value.
For commercial teams planning market entry, M&A desks evaluating targets, or procurement leaders renegotiating supply contracts in 2026, our full report contains the granular datasets, supplier scorecards, and transaction playbooks you will need to execute with confidence. Visit the PW Consulting report page to access the comprehensive model, proprietary segmentation tables, and step-by-step implementation tools that support board-level decision-making.
For detailed analysis of this topic, please visit the official page: Balanced Salt Buffer Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Industrial-Grade Trichlorosilane Market Poised to Expand at 8.12% CAGR Through 2032
By pmarketresearch, 2026-07-13
Industrial Grade Trichlorosilane Market — Strategic Briefing from PW Consulting
PW Consulting today publishes a forward-looking industry briefing extracted from our comprehensive Industrial Grade Trichlorosilane (TCS) Market report, designed specifically to inform executive decision-making in 2026. Built on a robust historical baseline (2020–2025) and a detailed forecast (2026–2032), our analysis shows the global industrial-grade TCS market expanding from USD 4,120.5 Million in 2020 to USD 6,450.0 Million in 2025, and projecting to surpass USD 11,140 Million by 2032 at a compound annual growth rate (CAGR) of 8.12% over the 2026–2032 forecast window. This note highlights the strategic implications of those dynamics while deliberately withholding granular sub-segment tables — full datasets, regional splits and application-level detail are available in the paid report.
Industrial Grade Trichlorosilane Market
Why 2026 is a Strategic Inflection Point
Several concurrent forces converged to make 2026 a decisional watershed for TCS stakeholders. Demand-side drivers — most notably the continued scaling of polysilicon capacity for solar and semiconductor applications — are increasing feedstock pull. On the supply side, technology shifts (e.g., fluidized-bed reactor deployments and process electrification), regulatory tightening in key markets, and trade-policy interventions are reshaping cost curves and logistic footprints. These dynamics mean that capital allocation decisions made in 2026 will materially influence competitive position, cost structure and access to end markets through the next investment cycle.
Industrial Grade Trichlorosilane Market
-
Demand momentum: Growth in solar and semiconductor end-markets is the principal long-term demand vector.
Industrial Grade Trichlorosilane Market -
Technology transition: New manufacturing technologies and purification investments are improving energy efficiency and product quality, but require CAPEX and operational know-how.
-
Regulatory and trade risks: Environmental compliance regimes and trade measures are raising operating thresholds and creating regional arbitrage opportunities.
What the PW Consulting Report Delivers — Practical, Actionable Intelligence
Our report is structured as a decision-support toolkit for corporate strategy, investment committees, procurement teams, and M&A advisors. Core deliverables include:
-
High-confidence market sizing and forward demand curves by major use cases and production processes, with scenarios calibrated to alternative solar and semiconductor adoption paths.
-
Supply-side capacity mapping, utilization scenarios and an integrated cost curve that models feedstock input prices, energy, labor and environmental compliance expenditures.
-
Technology and process benchmarking (hydrochlorination, direct synthesis, FBR and purification routes), including lifecycle energy profiles and emissions differentials.
-
Regulatory impact matrix — jurisdictional compliance burdens, likely timelines, and estimated capex/OPEX impacts for well-defined scenarios.
-
Commercial playbooks for offtake agreements, feedstock contracting strategies, pricing architectures and hedging approaches, including negotiation templates and sensitivity analyses.
-
M&A and partnership diagnostic: target characteristics, valuation overlays, synergies assessment and integration roadmaps tailored for upstream, midstream and downstream players.
-
A dashboard of actionable KPIs and a downloadable financial model that lets clients run custom scenario stress-tests on price, feedstock availability and capex timing.
We intentionally present this summary as a “report trailer”: it communicates the analytic depth and immediate operational utility while steering stakeholders to the full report for transaction-grade data and proprietary segment-level intelligence.
Competitive Landscape — Who’s Shaping the Market
The industrial TCS market remains moderately concentrated. The top three producers account for a significant share of global installed capacity, with CR3 at approximately 48.3% and CR5 at roughly 62.15%. That concentration creates both stability and strategic leverage for incumbents while leaving room for new entrants with differentiated cost or technology propositions.
Key strategic profiles and implications:
-
Wacker Chemie AG (Munich, Germany): A vertically integrated player active across polysilicon and silicone chains. Recent investments in purification capabilities point to an explicit play for high-purity TCS demand from European semiconductor projects. For clients, Wacker’s positioning signals rising premiumization and the need to evaluate purity-driven product segmentation.
-
Hemlock Semiconductor Operations (USA): A core U.S.-based polysilicon and TCS supplier. Federal funding support for domestic polysilicon facilities changes the U.S. upstream economics and shortens supply chains for North American semiconductor and solar ecosystems; buyers and investors should incorporate incentivized capacity into supply-risk models.
-
OCI Company Ltd. (South Korea): Aggressive capacity expansion in Southeast Asia demonstrates a low-cost scale play. For purchasers, this highlights a bifurcated market — cost-competitive bulk suppliers vs. specialty/high-purity providers.
-
Tokuyama, Shin-Etsu, REC, Evonik, Dow and others: These diversified chemical majors and polysilicon specialists maintain strategic portfolios across purity grades and geographies. Their choices on purification technologies and emissions control will largely define premium product availability in regulated markets.
-
GCL-Poly and TBEA (China): Large-scale, energy-efficient production projects — including FBR-based operations with materially lower energy intensity — are reshaping global cost curves and creating pressure on legacy producers to modernize or consolidate.
Recent corporate moves validate our scenario work: European purification capacity additions, Southeast Asian capacity bumps, major FBR startups and government-backed domestic buildouts are altering regional balance and are explicitly modeled in our forecast scenarios.
Risks, Supply Dynamics and Cost Drivers
TCS economics are closely tied to several externally-driven variables. Our report models these with probabilistic scenario analysis and provides hedging and contingency playbooks:
-
Feedstock volatility: Metallurgical-grade silicon remains the primary feedstock. Price movements and regional availability materially affect margins. Our sensitivity matrices quantify breakpoints where margins compress or expand and provide guidance on reserve coverage and sourcing lines.
-
Energy and process efficiency: Technology shifts (e.g., fluidized-bed reactors) can cut energy per tonne significantly. We quantify payback horizons for technology retrofits and new-builds under multiple energy price pathways.
-
Regulatory compliance and environmental obligations: Regions subject to stricter chemical and emissions regulation face step-up compliance costs. The report maps regulatory schedules and associated capital and operating expenditure impacts on an operator-by-operator basis.
-
Trade policy and geopolitical developments: Export controls, anti-dumping measures, and temporary policy adjustments can reroute trade flows. We model the operational consequences of recent measures and the likely second-order effects on global logistics and inventory strategies.
Practical Takeaways for 2026 Decision-Makers
For executives planning capital, procurement or M&A activity in 2026, our analysis crystallizes high-value actions:
-
Lock down diversified feedstock supply lines and build scenario-based inventory buffers for at-risk geographies.
-
Prioritize investments in purification and emissions-reduction where customer mix tilts toward semiconductor-grade demand; these investments can unlock premium pricing and long-term contracts.
-
Consider strategic partnerships or targeted M&A to fill capability gaps (e.g., low-energy FBR technology, purification expertise or regional logistics strength).
-
Integrate regulatory cost-pass-through mechanisms into offtake contracts and adopt flexible pricing frameworks to maintain margins amid variable compliance costs.
-
Adopt a staged CAPEX approach with go/no-go triggers tied to polysilicon demand realizations and feedstock price thresholds, reducing execution risk.
How to Use the Full PW Consulting Report
The full report contains the granular inputs required to operationalize the takeaways above: downloadable models, company scorecards, regional risk matrices, supplier playbooks and transaction support documentation. This briefing is intentionally selective — it signals the analytic depth and the immediate strategic choices facing the industry while preserving the segment-level intelligence necessary for transaction execution.
Companies considering capital allocation, strategic sourcing, pricing resets or M&A activity in 2026 will find the report the most time-efficient route to evidence-based decisions. Our consulting teams are available to run bespoke workshops, customize the model to your portfolio, and translate findings into executable roadmaps.
Next Steps
PW Consulting’s Industrial Grade Trichlorosilane Market report is a comprehensive resource built for executives who must move from insight to action in 2026. To access the full report, data dashboards and scenario models — and to inquire about bespoke advisory engagements — please visit our report landing page or contact our industry practice leads. We publish periodic updates as market events unfold; the next update cycle will reflect newly announced capacity changes, policy shifts and feedstock pricing trajectories.
Note: This press briefing is an executive overview. It intentionally omits detailed regional and application splits, unit-level price forecasts and company-level revenue breakdowns to preserve the report’s value as a premium, transaction-grade product. The full dataset and proprietary analysis are available through PW Consulting’s Industrial Grade Trichlorosilane Market report.
For detailed analysis of this topic, please visit the official page: Industrial Grade Trichlorosilane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HFO Cooling Fluids for Data Centers to Surge from USD 610.5 Million in 2025 to USD 1,947.03 Million by 2032 at an 18.02% CAGR
By pmarketresearch, 2026-07-13
HFO Cooling Fluids for Data Centers: Strategic Insights for 2026 Decision-Making
PW Consulting’s new market study on HFO (hydrofluoroolefin) cooling fluids for data centers reframes how infrastructure leaders should think about thermal strategy over the next investment cycle. The market has moved beyond experimental pilots into commercially credible deployments: our 2025 base-year analysis pegs the market at approximately USD 610.5 million, with a compound annual growth rate of 18.02% through the 2026–2032 forecast window. By 2026 the market is projected to clear the mid‑hundreds of millions and, under current trajectories, approach just under USD 2.0 billion by 2032. Those headline dynamics matter for procurement, product roadmaps, compliance planning, and risk management in 2026.
Hfo Cooling Fluids For Data Center Market
Why this market matters for your 2026 strategy
-
Regulatory timing is compressing vendor and user decisions. Policy shifts—most notably recent EPA Technology Transitions rules and ongoing implementation of Kigali and F‑gas frameworks—create hard compliance milestones that will shape which cooling options are permissible, economic, or practical across major operating geographies beginning in 2027 and beyond.
Hfo Cooling Fluids For Data Center Market -
Transition economics are moving from lab to balance sheet. The combination of accelerating market adoption and a rapid capacity build-out among key suppliers means that thermal design choices made in 2026 will influence total cost of ownership over a multi‑year lifespan, not just immediate capital outlay.
Hfo Cooling Fluids For Data Center Market -
Supplier concentration is material. The market exhibits high concentration: the top three suppliers account for a clear majority share, and the top five capture almost nine in ten dollars of market value. That concentration translates into negotiation dynamics, technology lock‑in risk, and strategic leverage for a small set of global chemical and HVAC incumbents.
-
Supply‑chain and raw‑material volatility is an operational lever. HFO production depends on specific fluorinated intermediates and olefins; periodic raw material price shocks and capacity shifts (already visible through supplier price actions in 2025) affect margins, contract terms, and supplier selection.
What the PW Consulting report delivers (practical, execution‑oriented)
-
Actionable market sizing and scenario models calibrated to 2025 base data and our 2026–2032 forecasts—designed for integration into capital planning and vendor selection processes.
-
Commercial due‑diligence templates that translate chemical supplier claims into procurement KPIs, including compatibility, lifecycle emissions, and cost drivers you can use in RFIs and RFPs.
-
Technology readiness assessments mapping product types to typical deployment archetypes (immersion, direct‑to‑chip, chiller architectures) with decision trees for when to pilot versus when to scale.
-
Regulatory scenario analysis that quantifies the impact of near‑term GWP limits and phasedown timetables on acceptable refrigerant/coolant choices and retrofitting windows.
-
Supplier scorecards and concentration risk maps, with playbooks for contracting, dual sourcing, and long‑lead procurement to mitigate supplier power and feedstock exposure.
-
Compatibility and qualification checklist for hardware vendors and hyperscalers—covering materials compatibility, electronic component validation, and operational reliability benchmarks from pilot to production.
-
Financial models for total cost of ownership and carbon‑adjusted ROI that fold in energy efficiency gains, water savings potential from liquid approaches, and disposal/recapture options for end‑of‑life fluids.
-
A curated appendix of vendor dossiers, recent commercial milestones, and anonymized case studies from pilot and full‑scale trials. Note: to preserve commercial confidentiality we summarize outcomes and implications rather than disclosing counterparty commercial terms or granular trial metrics.
Competitive landscape — what matters for vendor selection in 2026
-
The marketplace is anchored by a small set of industrial incumbents that combine chemical synthesis capability with global manufacturing footprints and channel relationships into data center OEMs and integrators. These players bring differentiated propositions: proprietary dielectric two‑phase fluids, low‑GWP blends optimized for chillers and centrifugal machines, and product lines tailored to single‑ and two‑phase immersion.
-
One global chemical player has advanced its two‑phase dielectric offering into commercial qualification with at least one major SSD manufacturer and is executing strategic manufacturing and integration agreements to secure supply and accelerate system demonstrations. These moves de‑risk adoption for hyperscalers and large colo operators planning fleet rollouts.
-
Another incumbent has recently increased upstream production capacity for low‑GWP HFO formulations to meet growing demand for chiller and immersion applications—an important signal that supply constraints are being addressed, but also that customers should validate long‑term offtake and logistics terms.
-
Specialist entrants and spin‑outs from larger diversified materials businesses are pushing performance claims—very low GWP, low flammability, dielectric stability for two‑phase immersion—and have been visible in trials and niche deployments. Their agility can translate into rapid innovation, but buyers must weigh scale, qualification history, and backward‑compatibility risk.
-
Regional and subsystem OEMs (HVAC and refrigerant specialists) are leveraging decades of refrigeration know‑how to package HFO solutions for direct‑to‑chip and chilled‑loop systems, reducing integration friction for operators that prefer incremental transitions over wholesale architectural overhaul.
Regulatory and raw‑material dynamics to watch in 2026
-
Expect regulatory levers to shift the relative attractiveness of solutions. Recent rules in major jurisdictions introduce next‑generation GWP thresholds and phase‑in schedules that make ultra‑low‑GWP HFOs strategically preferable for new equipment. These timelines create windows for factory‑charged systems, grandfathering rules, and incentives that savvy buyers can exploit in procurement cycles.
-
Feedstock risk remains a live issue. Price adjustments from producers in 2025 reflected upstream cost pressure; procurement teams should bake in sensitivity to feedstock price shocks and include contractual protections or price‑adjustment mechanisms in multi‑year supply agreements.
-
Compliance goes beyond refrigerant selection. End‑to‑end lifecycle accounting—covering leak rates, end‑of‑life recovery, and equivalent CO2 accounting—will increasingly be a procurement requirement in tenders and sustainability reporting frameworks.
Practical 100‑day plan for CIOs, CTOs, and Procurement Heads
-
Day 0–30: Inventory and risk triage. Map installed thermal architectures, inventory compatible materials, and identify high‑heat, high‑value racks where economics justify immediate pilots.
-
Day 30–60: Supplier engagement and qualification. Issue targeted RFIs to a short list of qualified suppliers, request third‑party compatibility data, and negotiate pilot‑scale supply agreements with explicit qualification gates and price‑adjustment clauses.
-
Day 60–90: Pilot and measurement. Execute instrumentation‑rich pilots that capture energy, water, reliability, and operational maintenance metrics. Use a standard template (provided in our report) to ensure cross‑vendor comparability.
-
Day 90–100: Go/no‑go and contracting. Based on pilot performance and regulatory horizon, finalize procurement strategy—pilot extension, cascade deployment, or strategic partnership—and lock in long‑lead components and service packages aligned with compliance windows.
How PW Consulting supports your 2026 roadmap
-
We provide rapid‑turn advisory packages that combine our market forecast models, supplier diligence, and technical validation protocols so teams can accelerate pilot-to-scale decisions without assuming undue technical or supply risk.
-
Our vendor negotiation workstreams help buyers structure multi‑year supply frameworks that hedge feedstock volatility, secure qualification milestones, and preserve flexibility across cooling architectures.
-
For investors and M&A teams, we offer concentration and competitive stress testing that quantify the implications of market concentration on pricing power, margin compression, and strategic entry points.
Data center operators, OEMs, and investors entering procurement or investment deliberations in 2026 will find the next 12–18 months decisive. The market’s rapid growth trajectory and the interplay of supplier consolidation, regulatory push, and raw‑material dynamics make disciplined, data‑driven strategy essential. PW Consulting’s HFO Cooling Fluids for Data Center Market report synthesizes those forces into practical, executable guidance—balancing speed to market with long‑term resilience. For the complete dataset, segment level detail, and vendor scorecards that underpin these conclusions, download the full report from PW Consulting’s insights portal.
For detailed analysis of this topic, please visit the official page: Hfo Cooling Fluids For Data Center Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: General Bio‑Based Polyamide Market to Expand at a 15.02% CAGR Through 2032, Report Finds
By pmarketresearch, 2026-07-13
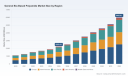
General Bio-Based Polyamide Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new market study finds the global General Bio-Based Polyamide market at an inflection point. Measured on a 2025 base year, total industry revenues stand in the low‑single‑digit billions (USD, million units), and our modelling shows a robust compound annual growth rate of 15.02% through the 2026–2032 forecast window. Under our central scenario the market expands materially by 2032, reflecting accelerated adoption across mobility, consumer, and industrial applications as OEMs and brand owners pursue carbon reduction targets and material substitution strategies.
General Bio Based Polyamide Market
Why this report matters for 2026 strategic decisions
-
High-growth but capital‑intensive transition: Double‑digit CAGR implies rapid demand formation, yet upstream feedstock dynamics and conversion capacity remain the gating factors for many product formats. Timing of capacity additions and contractual offtakes will determine who captures scale economics.
General Bio Based Polyamide Market -
Regulation and procurement are moving from optional to mandatory: EU regulatory drivers and corporate net‑zero procurement policies are accelerating commercialisation for certified bio‑attributed grades. Certification frameworks and lifecycle accounting will increasingly influence supplier selection and price premiums.
General Bio Based Polyamide Market -
Market concentration favours select integrated players: Our concentration metrics indicate a moderately concentrated supplier base with clear leaders in integrated castor‑to‑polyamide value chains, and a second tier focused on mass‑balance and bio‑attributed offerings. Competitive positioning today predicts share capture in the near term.
What PW Consulting’s General Bio‑Based Polyamide report delivers (practical assets)
-
Decision‑grade market model: a transparent, editable financial model calibrated to 2020–2025 historicals and our 2026–2032 scenarios, enabling boardrooms to stress‑test volume, price and margin outcomes under alternate feedstock, policy and technology assumptions.
-
Go‑to‑market playbooks: segmented commercial strategies for OEMs, compounders and converters, including recommended contracting structures (indexation vs fixed pricing, revenue‑sharing, strategic JV templates) and customer qualification roadmaps.
-
Supplier scorecards and investment checklists: comparative assessments across technology readiness, feedstock integration, certification status (ISCC and equivalents), carbon intensity, supply reliability and capital intensity — built to fast‑track sourcing decisions and capex approvals.
-
Supply chain stress tests and sourcing blueprints: scenario analyses for feedstock shocks, logistics disruptions and policy shifts with actionable mitigation options (multi‑sourcing, buffer inventories, forward buying, synthetic biology pathways).
-
Regulatory and incentive matrix: jurisdictional overview of regulatory levers and incentive schemes shaping adoption — including procurement preferences, allowances, and compliance timelines critical to 2026 investment windows.
Five strategic imperatives for executives planning in 2026
-
Secure feedstock optionality now. Castor oil remains a primary renewable precursor for many bio‑polyamides. Historical price volatility in key derivatives has been material, so procurement strategies should combine medium‑term contracts, diversified sourcing geographies, and exploration of alternative bio‑monomers and biotechnological routes to reduce single‑source exposure.
-
Prioritise certified supply chains. Certification (e.g., ISCC PLUS and equivalent schemes) is no longer a marketing badge alone: it is a commercial prerequisite for many automotive and consumer supply chains. Early alignment with certified suppliers or investment in certified mass‑balance capacity creates preferential access to OEM programs.
-
Design for function, not just “bio.” Material selection must balance lifecycle emissions, performance (moisture uptake, thermal stability, mechanical properties) and manufacturability. Co‑development agreements with tier‑1 material suppliers can compress validation timelines and reduce adoption friction for regulated applications such as under‑hood automotive parts and medical devices.
-
Adopt a staged capacity play. Given the market’s projected expansion, late entrants risk higher unit costs. Conversely, premature brownfield investments without offtake guarantees increase balance‑sheet risk. We recommend staged capacity expansion tied to binding offtake contracts and technology de‑risking milestones.
-
Embed lifecycle transparency into commercial offers. Buyers increasingly value verified carbon intensity metrics (for example, low kg CO2e/kg production chains enabled by renewable energy integration). Companies that can present auditable cradle‑to‑gate data will command premium pricing and faster adoption.
Competitive landscape — positioning and strategic moves
The competitive map is shaped by vertically integrated specialty producers, incumbent polymer majors leveraging bio‑attribution, and technology‑native entrants developing novel monomer pathways. Key strategic archetypes we observe:
-
Integrated castor‑to‑polyamide leaders: firms with control across feedstock processing to finished resin are able to optimise carbon intensity and security of supply and therefore occupy premium positions for demanding end markets.
-
Mass‑balance and bio‑attributed incumbents: polymer majors are extending product portfolios via biogenic credits and ISCC‑certified mass‑balance offerings to serve existing customers seeking lower‑carbon alternatives without major processing shifts.
-
Specialist biotech and monomer innovators: agents producing odd‑carbon chain diamines or alternative routes (e.g., cadaverine routes, sebacic acid substitutes) are targeting textile fibers and niche engineering applications where property differentials create value.
Notable recent developments underscore these dynamics: a major specialty producer commissioned a transparent bio‑based polyamide unit in Southeast Asia to materially increase supply of mid‑bio‑content grades for eyewear, electronics and medical uses; a leading chemical group launched extended mass‑balanced biocircular PA6 resins with certification credentials suitable for decarbonisation programs; and integrated producers report production carbon footprints for certain PA11 chains that are a fraction of fossil equivalents thanks to renewable electricity and process efficiency gains. These moves change the commercial calculus for buyers and suppliers alike.
Risk matrix and headwinds to monitor in 2026
-
Raw material price swings: upstream feedstock markets have shown significant month‑to‑month variability, which can compress margins and complicate long‑term procurement unless hedged or contractually managed.
-
Certification and greenwashing scrutiny: inconsistent accounting and labelling could trigger buyer scepticism; robust, auditable chain‑of‑custody practices are essential.
-
Application qualification timelines: heavily regulated segments (automotive safety, medical devices) have long validation cycles. Companies must plan multi‑year qualification programs to synchronise material readiness with product roadmaps.
-
Technology and substitution risk: advances in recycling, alternative polymers or biosynthetic monomers could alter cost curves and performance benchmarks; continuous technology monitoring is required.
How PW Consulting helps your 2026 playbook
Our report is designed as an executable commercial and technical playbook for senior executives, procurement leads and innovation teams. It combines a scenario‑driven financial model, supplier and technology diagnostics, and pragmatic contracting templates to guide investment, sourcing and product development decisions through 2026 and beyond. The study also quantifies market concentration dynamics and highlights which supplier archetypes are most likely to scale in our central and downside scenarios.
Call to action — where to find the full intelligence
This briefing deliberately highlights strategic conclusions while withholding detailed regional, product and application breakouts to preserve the integrated intelligence contained in the full study. For access to the complete dataset, editable forecasting model, supplier scorecards, and our detailed end‑use segmentation (including downloadable charts and procurement playbooks), visit the PW Consulting report landing page or contact our research desk to arrange a briefing. The next 12–18 months will determine who secures scale economics in a market projected to more than double from the 2025 base under our central forecast — acting with data, contracts and validated technology roadmaps will be decisive.
For detailed analysis of this topic, please visit the official page: General Bio Based Polyamide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rubidium-83 Market Poised to Expand at a 6.18% CAGR Through 2032, Driven by Research and Medical Demand
By pmarketresearch, 2026-07-13
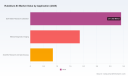
Rubidium‑83 Market: Strategic Imperatives for 2026 — PW Consulting Intelligence Brief
As the global research and specialty isotope ecosystem reconfigures around constrained feedstock, regulatory stringency, and nascent clinical applications, Rubidium‑83 (Rb‑83) emerges as a small but strategically consequential market. PW Consulting’s new Rubidium‑83 Market report (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes primary research, supplier due diligence, and scenario modeling to inform executive decisions in 2026. This briefing highlights the report’s practical value to corporate strategy teams while intentionally withholding the granular tables and segment-level datapoints reserved for the full report.
Rubidium-83 Market
Market snapshot and what changes in 2026 mean for you
Rb‑83 is a specialty isotope tied to accelerator-based production and research‑grade applications. Our topline market-sizing shows steady historical expansion from the early 2020s through 2025, followed by a multi‑year growth trajectory. The market increased from USD 4.52 Million in 2020 to USD 6.12 Million in 2025 and, under base-case assumptions, is projected to grow to USD 9.32 Million by 2032. Over the forecast window the market exhibits a compound annual growth rate (CAGR) of approximately 6.18% — a pace that is moderate in absolute terms but significant for high‑value, capacity‑constrained isotope supply chains.
Rubidium-83 Market
Two structural dynamics define the commercial logic for 2026 decisions:
Rubidium-83 Market
- Concentrated supply and buyer leverage: The market is highly concentrated among a handful of specialist suppliers. Our concentration metrics indicate that the three largest suppliers account for the vast majority of commercial supply, and the top five collectively dominate nearly the entire market. This creates both supply security risk and concentrated pricing power to those incumbents.
- Production and regulatory constraints: Rb‑83 production is accelerator‑driven (proton bombardment of RbCl targets) and subject to stringent radionuclidic purity specifications for research use. These technical and regulatory barriers raise the cost of entry for new producers but also create durable differentiation for established operators who can demonstrate compliant production and chain‑of‑custody.
Why PW Consulting’s report is strategically valuable for 2026
Executives face three intertwined questions for 2026 planning: How exposed is my organization to isotope availability and price volatility? Where are opportunity pockets for downstream productization or service bundling? And what partnership or investment posture minimizes risk while maximizing option value? Our report converts the answers into executable guidance:
- Supply‑risk quantification: We map the end‑to‑end supply chain, enumerate single‑point failure modes (from target procurement to irradiation throughput), and score counterparties on capacity resilience and regulatory compliance.
- Commercial opportunity framework: We prioritize near‑term commercial use cases that justify upstream investment (for example, tracer development or advanced R&D services) versus longer‑term platform plays that require aggregation of supply and regulatory clearances.
- M&A and partnership playbook: For companies considering vertical integration or offtake arrangements, the report provides target archetypes, valuation multipliers customized for specialist isotopes, and earn‑out structures sensitive to decay half‑life economics.
Key market dynamics to watch in 2026
- Feedstock and upstream sourcing. Rubidium is mined as a byproduct of cesium (pollucite) and lithium (lepidolite) extraction. Primary global production is geographically concentrated, and certain markets remain effectively import‑dependent. For buyers and producers alike, securing reliable access to feedstock and establishing multi‑tiered sourcing arrangements is a near‑term priority.
- Price signals. Recent commodity and material price movements have increased costs for high‑purity rubidium compounds; market offers showed meaningful year‑over‑year increases across common product forms in the latest public summaries. These upward price pressures feed directly into production economics for accelerator providers and distributors.
- Regulatory and quality thresholds. Rb‑83 supplied for research is subject to stringent radionuclidic purity specifications. Product acceptance criteria — such as maximum permissible levels of other rubidium isotopes — meaningfully affect yield, waste management, and the viability of certain production pathways. Quality compliance will be a differentiator for suppliers courting medical and biological research customers.
- Geopolitical concentration. Primary production and processing capacity are clustered in a handful of countries, reinforcing supply‑chain fragility and making strategic sourcing and defensive inventory policies business‑critical.
Competitive landscape — practical implications for partners and buyers
Our competitive analysis focuses on the active specialist suppliers and distributors who currently shape availability and standards in the Rb‑83 market. The following is a strategic distillation of public profiles and PW Consulting primary interviews. Detailed supplier scorecards and procurement playbooks are available in the full report.
- National Isotope Development Center (NIDC) / DOE Isotope Program (Oak Ridge, TN, USA)
Role and leverage: A primary U.S. government supplier, NIDC runs accelerator‑based production for research applications and enforces tight radionuclidic purity. For commercial actors, NIDC is both a source of supply and a standards‑setting reference. Strategic actions for 2026: cultivate cooperative R&D partnerships, structure special‑order logistics in advance of project milestones, and plan around lead times intrinsic to government procurement.
- American Elements (Los Angeles, CA, USA)
Role and leverage: A global supplier of rubidium compounds and research‑grade materials, with breadth across stable and radioactive variants. American Elements is well positioned to serve material requirements for downstream device makers and labs. Strategic actions: evaluate supplier qualification programs, negotiate bundled pricing for compound plus logistics, and explore co‑development agreements for application‑specific formulations.
- Trace Sciences International (Ontario, Canada; U.S. operations)
Role and leverage: Specialist in high‑purity stable and radioactive rubidium isotopes for medical and industrial research. Trace Sciences’ emphasis on purity positions it for partnerships with high‑sensitivity users. Strategic actions: pursue joint validation studies, and consider offtake or consignment models to mitigate delivery timing risk.
- AMT Ventures / AMT Isotopes (USA; global distribution)
Role and leverage: Distributor with catalog offerings for rubidium isotopes used in tracer development and generator research. As a channel player, AMT can accelerate market access for emerging applications. Strategic actions: leverage distributor networks to pilot new tracer concepts, and align contractual terms to permit rapid scale‑up if translational research succeeds.
Actionable recommendations for 2026 planning
Based on market sizing, concentration metrics, and supply dynamics, PW Consulting recommends the following five priorities for organizations active in or adjacent to the Rb‑83 value chain:
- Establish multi‑axis supply agreements: Combine long‑lead special orders with short‑term distributor contracts to balance cost and flexibility.
- Invest in supplier qualification and auditing: Given high purity thresholds and regulatory scrutiny, rigorous incoming QA/QC protocols reduce program risk and downstream validation costs.
- Pursue targeted vertical integration only when scale and duration justify capital investment: Cyclotron capacity or co‑investment in irradiation time is expensive; alternatives include strategic offtake or capacity reservation arrangements.
- Design flexible product and pricing models for research customers: Consider consignment, milestone billing, or shared‑risk pilot structures to accelerate adoption without over‑committing inventory.
- Monitor geopolitical and feedstock developments: Develop contingency plans for feedstock scarcity driven by shifts in primary mineral production or export controls.
What the full report contains (practical deliverables)
The Pw Consulting Rubidium‑83 Market report translates the above insights into tools and assets executives can use immediately in 2026. Highlights include:
- Methodology and reproducible market sizing (historical 2020–2025 and forecast 2026–2032) with sensitivity scenarios;
- Supply‑chain maps that identify critical nodes, typical lead times, and inventory best practices;
- Supplier scorecards and commercial terms playbook (procurement templates, suggested KPIs, audit checklists);
- Regulatory and quality compliance checklist tailored to research and translational applications, with sample radionuclidic specification language;
- Opportunity heatmaps for application and product development that prioritize initiatives by time‑to‑value and investment scale;
- Valuation and M&A playbook for specialty isotope targets, including deal structures suited to capacity‑constrained assets;
- Primary interview summaries and case studies demonstrating how leading institutions manage scarcity and regulatory complexity.
Note: to preserve competitive sensitivity and to support transparent commercial engagement, the report intentionally withholds granular regional and application split tables from this public summary. Those detailed segmentations — including supplier share tables, regional demand matrices, and application revenue breakdowns — are available exclusively in the full report package.
Final note — positioning for 2026
Rb‑83 will not become a commodity overnight, but its strategic profile is rising. The combination of steady demand growth, concentrated supply, and quality/regulatory constraints makes the isotope an asymmetric bet: relatively modest absolute dollars can imply substantial operational and reputational exposure for research programs and product developers. For organizations that move early to secure validated supply, build robust QA practices, and design flexible commercialization models, 2026 offers a window to convert a constrained material into a commercially differentiated capability.
For procurement teams, product leaders, and corporate development executives preparing 2026 budgets and M&A pipelines, PW Consulting’s full Rubidium‑83 Market report provides the data, supplier intelligence, and executable playbooks to convert market risk into strategic advantage. Contact PW Consulting to access the complete study and supplier scorecards.
For detailed analysis of this topic, please visit the official page: Rubidium-83 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com