

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Industrial-Grade Trichlorosilane Market Poised to Expand at 8.12% CAGR Through 2032

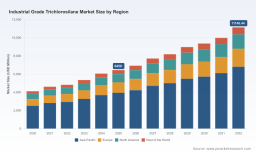
Industrial Grade Trichlorosilane Market — Strategic Briefing from PW Consulting
PW Consulting today publishes a forward-looking industry briefing extracted from our comprehensive Industrial Grade Trichlorosilane (TCS) Market report, designed specifically to inform executive decision-making in 2026. Built on a robust historical baseline (2020–2025) and a detailed forecast (2026–2032), our analysis shows the global industrial-grade TCS market expanding from USD 4,120.5 Million in 2020 to USD 6,450.0 Million in 2025, and projecting to surpass USD 11,140 Million by 2032 at a compound annual growth rate (CAGR) of 8.12% over the 2026–2032 forecast window. This note highlights the strategic implications of those dynamics while deliberately withholding granular sub-segment tables — full datasets, regional splits and application-level detail are available in the paid report.
Industrial Grade Trichlorosilane Market
Why 2026 is a Strategic Inflection Point
Several concurrent forces converged to make 2026 a decisional watershed for TCS stakeholders. Demand-side drivers — most notably the continued scaling of polysilicon capacity for solar and semiconductor applications — are increasing feedstock pull. On the supply side, technology shifts (e.g., fluidized-bed reactor deployments and process electrification), regulatory tightening in key markets, and trade-policy interventions are reshaping cost curves and logistic footprints. These dynamics mean that capital allocation decisions made in 2026 will materially influence competitive position, cost structure and access to end markets through the next investment cycle.
Industrial Grade Trichlorosilane Market
-
Demand momentum: Growth in solar and semiconductor end-markets is the principal long-term demand vector.
Industrial Grade Trichlorosilane Market -
Technology transition: New manufacturing technologies and purification investments are improving energy efficiency and product quality, but require CAPEX and operational know-how.
-
Regulatory and trade risks: Environmental compliance regimes and trade measures are raising operating thresholds and creating regional arbitrage opportunities.
What the PW Consulting Report Delivers — Practical, Actionable Intelligence
Our report is structured as a decision-support toolkit for corporate strategy, investment committees, procurement teams, and M&A advisors. Core deliverables include:
-
High-confidence market sizing and forward demand curves by major use cases and production processes, with scenarios calibrated to alternative solar and semiconductor adoption paths.
-
Supply-side capacity mapping, utilization scenarios and an integrated cost curve that models feedstock input prices, energy, labor and environmental compliance expenditures.
-
Technology and process benchmarking (hydrochlorination, direct synthesis, FBR and purification routes), including lifecycle energy profiles and emissions differentials.
-
Regulatory impact matrix — jurisdictional compliance burdens, likely timelines, and estimated capex/OPEX impacts for well-defined scenarios.
-
Commercial playbooks for offtake agreements, feedstock contracting strategies, pricing architectures and hedging approaches, including negotiation templates and sensitivity analyses.
-
M&A and partnership diagnostic: target characteristics, valuation overlays, synergies assessment and integration roadmaps tailored for upstream, midstream and downstream players.
-
A dashboard of actionable KPIs and a downloadable financial model that lets clients run custom scenario stress-tests on price, feedstock availability and capex timing.
We intentionally present this summary as a “report trailer”: it communicates the analytic depth and immediate operational utility while steering stakeholders to the full report for transaction-grade data and proprietary segment-level intelligence.
Competitive Landscape — Who’s Shaping the Market
The industrial TCS market remains moderately concentrated. The top three producers account for a significant share of global installed capacity, with CR3 at approximately 48.3% and CR5 at roughly 62.15%. That concentration creates both stability and strategic leverage for incumbents while leaving room for new entrants with differentiated cost or technology propositions.
Key strategic profiles and implications:
-
Wacker Chemie AG (Munich, Germany): A vertically integrated player active across polysilicon and silicone chains. Recent investments in purification capabilities point to an explicit play for high-purity TCS demand from European semiconductor projects. For clients, Wacker’s positioning signals rising premiumization and the need to evaluate purity-driven product segmentation.
-
Hemlock Semiconductor Operations (USA): A core U.S.-based polysilicon and TCS supplier. Federal funding support for domestic polysilicon facilities changes the U.S. upstream economics and shortens supply chains for North American semiconductor and solar ecosystems; buyers and investors should incorporate incentivized capacity into supply-risk models.
-
OCI Company Ltd. (South Korea): Aggressive capacity expansion in Southeast Asia demonstrates a low-cost scale play. For purchasers, this highlights a bifurcated market — cost-competitive bulk suppliers vs. specialty/high-purity providers.
-
Tokuyama, Shin-Etsu, REC, Evonik, Dow and others: These diversified chemical majors and polysilicon specialists maintain strategic portfolios across purity grades and geographies. Their choices on purification technologies and emissions control will largely define premium product availability in regulated markets.
-
GCL-Poly and TBEA (China): Large-scale, energy-efficient production projects — including FBR-based operations with materially lower energy intensity — are reshaping global cost curves and creating pressure on legacy producers to modernize or consolidate.
Recent corporate moves validate our scenario work: European purification capacity additions, Southeast Asian capacity bumps, major FBR startups and government-backed domestic buildouts are altering regional balance and are explicitly modeled in our forecast scenarios.
Risks, Supply Dynamics and Cost Drivers
TCS economics are closely tied to several externally-driven variables. Our report models these with probabilistic scenario analysis and provides hedging and contingency playbooks:
-
Feedstock volatility: Metallurgical-grade silicon remains the primary feedstock. Price movements and regional availability materially affect margins. Our sensitivity matrices quantify breakpoints where margins compress or expand and provide guidance on reserve coverage and sourcing lines.
-
Energy and process efficiency: Technology shifts (e.g., fluidized-bed reactors) can cut energy per tonne significantly. We quantify payback horizons for technology retrofits and new-builds under multiple energy price pathways.
-
Regulatory compliance and environmental obligations: Regions subject to stricter chemical and emissions regulation face step-up compliance costs. The report maps regulatory schedules and associated capital and operating expenditure impacts on an operator-by-operator basis.
-
Trade policy and geopolitical developments: Export controls, anti-dumping measures, and temporary policy adjustments can reroute trade flows. We model the operational consequences of recent measures and the likely second-order effects on global logistics and inventory strategies.
Practical Takeaways for 2026 Decision-Makers
For executives planning capital, procurement or M&A activity in 2026, our analysis crystallizes high-value actions:
-
Lock down diversified feedstock supply lines and build scenario-based inventory buffers for at-risk geographies.
-
Prioritize investments in purification and emissions-reduction where customer mix tilts toward semiconductor-grade demand; these investments can unlock premium pricing and long-term contracts.
-
Consider strategic partnerships or targeted M&A to fill capability gaps (e.g., low-energy FBR technology, purification expertise or regional logistics strength).
-
Integrate regulatory cost-pass-through mechanisms into offtake contracts and adopt flexible pricing frameworks to maintain margins amid variable compliance costs.
-
Adopt a staged CAPEX approach with go/no-go triggers tied to polysilicon demand realizations and feedstock price thresholds, reducing execution risk.
How to Use the Full PW Consulting Report
The full report contains the granular inputs required to operationalize the takeaways above: downloadable models, company scorecards, regional risk matrices, supplier playbooks and transaction support documentation. This briefing is intentionally selective — it signals the analytic depth and the immediate strategic choices facing the industry while preserving the segment-level intelligence necessary for transaction execution.
Companies considering capital allocation, strategic sourcing, pricing resets or M&A activity in 2026 will find the report the most time-efficient route to evidence-based decisions. Our consulting teams are available to run bespoke workshops, customize the model to your portfolio, and translate findings into executable roadmaps.
Next Steps
PW Consulting’s Industrial Grade Trichlorosilane Market report is a comprehensive resource built for executives who must move from insight to action in 2026. To access the full report, data dashboards and scenario models — and to inquire about bespoke advisory engagements — please visit our report landing page or contact our industry practice leads. We publish periodic updates as market events unfold; the next update cycle will reflect newly announced capacity changes, policy shifts and feedstock pricing trajectories.
Note: This press briefing is an executive overview. It intentionally omits detailed regional and application splits, unit-level price forecasts and company-level revenue breakdowns to preserve the report’s value as a premium, transaction-grade product. The full dataset and proprietary analysis are available through PW Consulting’s Industrial Grade Trichlorosilane Market report.
For detailed analysis of this topic, please visit the official page: Industrial Grade Trichlorosilane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com