

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Balanced Salt Buffer Solution Market to Reach USD 1.39 Billion by 2032 at 7.4% CAGR, North America Leads with USD 327.6 Million

Balanced Salt Buffer Solution Market — Strategic Imperatives for 2026
As the life sciences supply chain enters a new phase of growth and operational complexity, PW Consulting’s latest market study on Balanced Salt Buffer Solutions (BSBS) provides an essential strategic compass for executives planning investments, partnerships, and capacity decisions in 2026. Our analysis synthesizes market sizing, channel economics, regulatory pressures, and supplier positioning to deliver decision-ready insight — while preserving the proprietary segment-level intelligence that underpins actionable choices. This release outlines the macro trajectory, competitive context, and recommended moves that will matter most to leaders across suppliers, bioprocessors, and institutional buyers.
Balanced Salt Buffer Solution Market
Market Outlook: Size, Pace and What It Means for Strategy
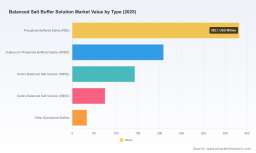
The Balanced Salt Buffer Solution market has expanded steadily through the first half of the decade and is positioned for continued growth. PW Consulting’s topline model — using 2025 as the base year — values the global market at approximately USD 842.5 million in 2025, with an anticipated rise to roughly USD 923.2 million in 2026. We forecast a compound annual growth rate (CAGR) of 7.4% over the projected horizon, driving the market toward well over USD 1.3 billion by the end of our 2026–2032 forecast window.
Balanced Salt Buffer Solution Market
For corporate strategists, the implication is clear: this is a mid-single-digit-to-high-single-digit growth market large enough to justify targeted capacity investments, but nuanced enough that success will hinge on differentiated product offerings, quality certifications, and supply chain resilience rather than pure scale alone.
Balanced Salt Buffer Solution Market
Key Market Dynamics Shaping 2026 Decisions
-
Quality and Regulatory Compliance as Table Stakes — BSBS products intended for cell culture, bioprocessing, and translational work are manufactured and marketed under stringent quality regimes. Our review of manufacturer documentation highlights universal dependence on cGMP frameworks (e.g., 21 CFR 820) and ISO certifications (9001 / 13485) to meet sterility, endotoxin, and consistency expectations. For commercial leaders, certifications are non-negotiable credentials that drive buyer trust and justify premium positioning.
-
Upstream Input Volatility — Sodium chloride represents a primary upstream feedstock. Industry data show the broader sodium chloride market was valued in the tens of billions of USD in 2025 and is experiencing modest growth; regional pricing dynamics and energy inputs remain key cost drivers. For BSBS manufacturers, small fluctuations in salt and energy costs can meaningfully affect margin when selling lower-priced, commoditized formulations — underscoring the need for hedging strategies and operational flexibility.
-
Concentration with Opportunity — Market concentration is material but incomplete. PW Consulting’s competitive mapping indicates the top three manufacturers capture roughly 42.5% of the market, while the top five control around 58.2%. This structure creates dual opportunities: established players can leverage scale and validated quality systems to defend share, while nimble specialists can seize higher-margin niches through customization, bilateral supply agreements with cell therapy developers, and targeted regulatory positioning.
-
Demand Growth Driven by Advanced Biomanufacturing — End-market demand is being propelled by expanded cell culture, stem cell research, and bioprocessing activities globally. As cell and gene therapy pipelines mature toward later-stage trials and commercial production, demand shifts from research-grade formulations to clinical and GMP-grade buffers, raising both revenue potential and qualification friction for suppliers.
Competitive Landscape: Profiles and Strategic Postures
PW Consulting examined the strategic positions and capabilities of leading BSBS suppliers to identify winning archetypes for 2026.
-
Platform & Scale Leaders — Thermo Fisher Scientific : With its Gibco product family and cGMP/ISO manufacturing footprint, Thermo Fisher exemplifies a full-spectrum supplier able to meet the needs of academic labs through to high-volume biomanufacturers. Their competitive advantage rests on brand trust, global distribution, and integrated quality systems that simplify customer qualification.
-
Industrial OEMs with Life-Science Focus — Cytiva (HyClone) & Corning : Cytiva leverages lab-to-bioprocess expertise and Danaher-scale commercialization muscle, emphasizing reproducibility and regulatory alignment. Corning’s HBSS offerings are positioned within its broader cell culture portfolio, with formulation variants addressing transport and short-term incubation use cases. Both rely on technical legacy and channel breadth to protect share.
-
Specialists & Custom Manufacturers — Boston BioProducts, Nucleus Biologics, Captivate Bio : These firms compete on customization, small-batch cGMP capabilities, and close collaboration with cell and gene therapy developers. Their value proposition is speed-to-spec and flexible formats — an attractive proposition for customers advancing clinical programs who require bespoke buffers and rapid documentation for regulatory filings.
-
Regional & Cost-Focused Players — Procell, Biowest, Sigma-Aldrich (Merck) : These suppliers combine localized manufacturing advantages and a portfolio of sterile-filtered products to serve regional scientists and biomanufacturers. Cost-competitive manufacturing, combined with acceptable quality certifications, helps them retain price-sensitive segments while advancing toward higher-spec opportunities.
-
Device/Consumable Integrators — Sartorius : Firms with adjacent technologies in bioprocessing and cell handling can cross-sell buffer solutions as part of integrated workflows (e.g., washing, transport, and closed-system processing), providing convenience advantages to customers and higher lifetime value for suppliers.
What PW Consulting’s Report Delivers — Practical, Transaction-Ready Intelligence
Our full report goes beyond high-level commentary to provide operational tools for commercial and manufacturing decision-makers. Key deliverables include:
-
Proprietary market-sizing models with scenario-based forecasts calibrated to macroeconomic, raw-material and regulatory variables;
-
Supply-chain diagnostic templates identifying single points of failure and opportunity for near-term de-risking;
-
Pricing benchmarks and margin maps that inform contract negotiation and go-to-market tactics;
-
Qualification roadmaps and checklist playbooks for moving research-grade products into GMP channels; and
-
Competitive intelligence dossiers on leading suppliers — including manufacturing footprints, certification status, product differentiation levers, and partnership case studies — designed to support M&A, JV, and distributor selection.
We intentionally withhold some proprietary segment-level splits and granular revenue-by-application tables from this executive summary in order to preserve the integrity of our modeling and to direct commercial users to the authenticated report for transaction-support materials.
Strategic Recommendations for 2026
-
Differentiate through Quality & Documentation: Secure or upgrade cGMP and relevant ISO certifications if you serve clinical or late-stage bioprocess customers. Investment in validated testing (endotoxin, osmolality, sterility) and detailed batch documentation materially reduces buyer friction and shortens qualification timelines.
-
Move Up the Value Stack: Pursue niche formulations and custom services tailored to cell and gene therapy developers. Premiumized, documented buffers command higher margins and strengthen long-term supply agreements.
-
Hedge Input Risk & Rationalize SKUs: Use procurement strategies for key feedstocks (e.g., salt contracts, energy pass-through clauses) and streamline SKU portfolios to optimize plant throughput and reduce changeover costs.
-
Forge Channel Partnerships: For suppliers without global reach, strategic distributor agreements and co-branded programs can accelerate penetration into regulated markets while preserving capital.
-
Prepare for Consolidation Opportunities: With the top-tier firms controlling a meaningful share of the market, selective M&A or technology partnerships offer an accelerated route to scale and certification access — particularly attractive for specialty players seeking to supply clinical-grade channels.
Operational Playbook for Buyers and Procurement Teams
-
Validate supplier certifications and batch release testing as part of any procurement RFQ for clinical or manufacturing use; include qualification timelines and audit provisions in contracts.
-
Build multi-supplier strategies for critical formulations and consider regional dual-sourcing to mitigate transport-related disruptions.
-
Negotiate longer lead-times for custom formulations but include performance-based SLAs and change-control frameworks to protect timelines for downstream production.
Conclusion — Why 2026 Is a Pivotal Year
The BSBS market in 2026 is neither a pure commodity race nor a narrow bespoke niche; it is a hybrid arena where rigorous quality compliance, supply-chain resilience, and targeted product differentiation determine winners. PW Consulting’s forecasted growth path and concentrated supplier landscape both create opportunities and pressing strategic choices for incumbents and new entrants alike. Companies that align investments in certification, formulation innovation, and procurement sophistication will convert growth into durable value.
For commercial teams planning market entry, M&A desks evaluating targets, or procurement leaders renegotiating supply contracts in 2026, our full report contains the granular datasets, supplier scorecards, and transaction playbooks you will need to execute with confidence. Visit the PW Consulting report page to access the comprehensive model, proprietary segmentation tables, and step-by-step implementation tools that support board-level decision-making.
For detailed analysis of this topic, please visit the official page: Balanced Salt Buffer Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com