

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rubidium-83 Market Poised to Expand at a 6.18% CAGR Through 2032, Driven by Research and Medical Demand

Rubidium‑83 Market: Strategic Imperatives for 2026 — PW Consulting Intelligence Brief
As the global research and specialty isotope ecosystem reconfigures around constrained feedstock, regulatory stringency, and nascent clinical applications, Rubidium‑83 (Rb‑83) emerges as a small but strategically consequential market. PW Consulting’s new Rubidium‑83 Market report (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes primary research, supplier due diligence, and scenario modeling to inform executive decisions in 2026. This briefing highlights the report’s practical value to corporate strategy teams while intentionally withholding the granular tables and segment-level datapoints reserved for the full report.
Rubidium-83 Market
Market snapshot and what changes in 2026 mean for you
Rb‑83 is a specialty isotope tied to accelerator-based production and research‑grade applications. Our topline market-sizing shows steady historical expansion from the early 2020s through 2025, followed by a multi‑year growth trajectory. The market increased from USD 4.52 Million in 2020 to USD 6.12 Million in 2025 and, under base-case assumptions, is projected to grow to USD 9.32 Million by 2032. Over the forecast window the market exhibits a compound annual growth rate (CAGR) of approximately 6.18% — a pace that is moderate in absolute terms but significant for high‑value, capacity‑constrained isotope supply chains.
Rubidium-83 Market
Two structural dynamics define the commercial logic for 2026 decisions:
Rubidium-83 Market
- Concentrated supply and buyer leverage: The market is highly concentrated among a handful of specialist suppliers. Our concentration metrics indicate that the three largest suppliers account for the vast majority of commercial supply, and the top five collectively dominate nearly the entire market. This creates both supply security risk and concentrated pricing power to those incumbents.
- Production and regulatory constraints: Rb‑83 production is accelerator‑driven (proton bombardment of RbCl targets) and subject to stringent radionuclidic purity specifications for research use. These technical and regulatory barriers raise the cost of entry for new producers but also create durable differentiation for established operators who can demonstrate compliant production and chain‑of‑custody.
Why PW Consulting’s report is strategically valuable for 2026
Executives face three intertwined questions for 2026 planning: How exposed is my organization to isotope availability and price volatility? Where are opportunity pockets for downstream productization or service bundling? And what partnership or investment posture minimizes risk while maximizing option value? Our report converts the answers into executable guidance:
- Supply‑risk quantification: We map the end‑to‑end supply chain, enumerate single‑point failure modes (from target procurement to irradiation throughput), and score counterparties on capacity resilience and regulatory compliance.
- Commercial opportunity framework: We prioritize near‑term commercial use cases that justify upstream investment (for example, tracer development or advanced R&D services) versus longer‑term platform plays that require aggregation of supply and regulatory clearances.
- M&A and partnership playbook: For companies considering vertical integration or offtake arrangements, the report provides target archetypes, valuation multipliers customized for specialist isotopes, and earn‑out structures sensitive to decay half‑life economics.
Key market dynamics to watch in 2026
- Feedstock and upstream sourcing. Rubidium is mined as a byproduct of cesium (pollucite) and lithium (lepidolite) extraction. Primary global production is geographically concentrated, and certain markets remain effectively import‑dependent. For buyers and producers alike, securing reliable access to feedstock and establishing multi‑tiered sourcing arrangements is a near‑term priority.
- Price signals. Recent commodity and material price movements have increased costs for high‑purity rubidium compounds; market offers showed meaningful year‑over‑year increases across common product forms in the latest public summaries. These upward price pressures feed directly into production economics for accelerator providers and distributors.
- Regulatory and quality thresholds. Rb‑83 supplied for research is subject to stringent radionuclidic purity specifications. Product acceptance criteria — such as maximum permissible levels of other rubidium isotopes — meaningfully affect yield, waste management, and the viability of certain production pathways. Quality compliance will be a differentiator for suppliers courting medical and biological research customers.
- Geopolitical concentration. Primary production and processing capacity are clustered in a handful of countries, reinforcing supply‑chain fragility and making strategic sourcing and defensive inventory policies business‑critical.
Competitive landscape — practical implications for partners and buyers
Our competitive analysis focuses on the active specialist suppliers and distributors who currently shape availability and standards in the Rb‑83 market. The following is a strategic distillation of public profiles and PW Consulting primary interviews. Detailed supplier scorecards and procurement playbooks are available in the full report.
- National Isotope Development Center (NIDC) / DOE Isotope Program (Oak Ridge, TN, USA)
Role and leverage: A primary U.S. government supplier, NIDC runs accelerator‑based production for research applications and enforces tight radionuclidic purity. For commercial actors, NIDC is both a source of supply and a standards‑setting reference. Strategic actions for 2026: cultivate cooperative R&D partnerships, structure special‑order logistics in advance of project milestones, and plan around lead times intrinsic to government procurement.
- American Elements (Los Angeles, CA, USA)
Role and leverage: A global supplier of rubidium compounds and research‑grade materials, with breadth across stable and radioactive variants. American Elements is well positioned to serve material requirements for downstream device makers and labs. Strategic actions: evaluate supplier qualification programs, negotiate bundled pricing for compound plus logistics, and explore co‑development agreements for application‑specific formulations.
- Trace Sciences International (Ontario, Canada; U.S. operations)
Role and leverage: Specialist in high‑purity stable and radioactive rubidium isotopes for medical and industrial research. Trace Sciences’ emphasis on purity positions it for partnerships with high‑sensitivity users. Strategic actions: pursue joint validation studies, and consider offtake or consignment models to mitigate delivery timing risk.
- AMT Ventures / AMT Isotopes (USA; global distribution)
Role and leverage: Distributor with catalog offerings for rubidium isotopes used in tracer development and generator research. As a channel player, AMT can accelerate market access for emerging applications. Strategic actions: leverage distributor networks to pilot new tracer concepts, and align contractual terms to permit rapid scale‑up if translational research succeeds.
Actionable recommendations for 2026 planning
Based on market sizing, concentration metrics, and supply dynamics, PW Consulting recommends the following five priorities for organizations active in or adjacent to the Rb‑83 value chain:
- Establish multi‑axis supply agreements: Combine long‑lead special orders with short‑term distributor contracts to balance cost and flexibility.
- Invest in supplier qualification and auditing: Given high purity thresholds and regulatory scrutiny, rigorous incoming QA/QC protocols reduce program risk and downstream validation costs.
- Pursue targeted vertical integration only when scale and duration justify capital investment: Cyclotron capacity or co‑investment in irradiation time is expensive; alternatives include strategic offtake or capacity reservation arrangements.
- Design flexible product and pricing models for research customers: Consider consignment, milestone billing, or shared‑risk pilot structures to accelerate adoption without over‑committing inventory.
- Monitor geopolitical and feedstock developments: Develop contingency plans for feedstock scarcity driven by shifts in primary mineral production or export controls.
What the full report contains (practical deliverables)
The Pw Consulting Rubidium‑83 Market report translates the above insights into tools and assets executives can use immediately in 2026. Highlights include:
- Methodology and reproducible market sizing (historical 2020–2025 and forecast 2026–2032) with sensitivity scenarios;
- Supply‑chain maps that identify critical nodes, typical lead times, and inventory best practices;
- Supplier scorecards and commercial terms playbook (procurement templates, suggested KPIs, audit checklists);
- Regulatory and quality compliance checklist tailored to research and translational applications, with sample radionuclidic specification language;
- Opportunity heatmaps for application and product development that prioritize initiatives by time‑to‑value and investment scale;
- Valuation and M&A playbook for specialty isotope targets, including deal structures suited to capacity‑constrained assets;
- Primary interview summaries and case studies demonstrating how leading institutions manage scarcity and regulatory complexity.
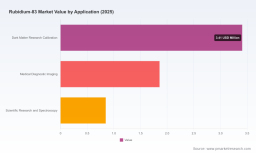
Note: to preserve competitive sensitivity and to support transparent commercial engagement, the report intentionally withholds granular regional and application split tables from this public summary. Those detailed segmentations — including supplier share tables, regional demand matrices, and application revenue breakdowns — are available exclusively in the full report package.
Final note — positioning for 2026
Rb‑83 will not become a commodity overnight, but its strategic profile is rising. The combination of steady demand growth, concentrated supply, and quality/regulatory constraints makes the isotope an asymmetric bet: relatively modest absolute dollars can imply substantial operational and reputational exposure for research programs and product developers. For organizations that move early to secure validated supply, build robust QA practices, and design flexible commercialization models, 2026 offers a window to convert a constrained material into a commercially differentiated capability.
For procurement teams, product leaders, and corporate development executives preparing 2026 budgets and M&A pipelines, PW Consulting’s full Rubidium‑83 Market report provides the data, supplier intelligence, and executable playbooks to convert market risk into strategic advantage. Contact PW Consulting to access the complete study and supplier scorecards.
For detailed analysis of this topic, please visit the official page: Rubidium-83 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com