

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Flexible Liquid Cooled Cable Market to Surge at 23.01% CAGR, Hitting USD 2,385.19 Million by 2032

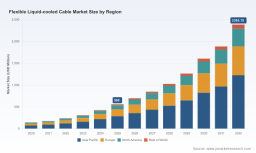
Flexible Liquid-Cooled Cable Market: Strategic Imperatives for 2026 — PW Consulting Release
PW Consulting today publishes an executive briefing drawn from our forthcoming Flexible Liquid Cooled Cable Market report, providing senior executives and investment committees with the strategic context they need as they plan for 2026. The market for flexible liquid-cooled cables has evolved from a niche industrial enabler to a critical infrastructure component across ultra-fast EV charging, data center power delivery, and heavy industrial applications. Our analysis synthesizes historical performance, supply-chain realities, regulatory inflection points, and vendor capabilities to show where near-term competitive advantage will be created — and where risks remain embedded.
Flexible Liquid Cooled Cable Market
Market trajectory: robust expansion with structural drivers
Demand for flexible liquid-cooled cables has accelerated sharply over the past half-decade. The global market expanded from roughly USD 145 million in 2020 to an estimated USD 560 million by our 2025 base year, driven by both industrial retrofit cycles and the rapid roll‑out of megawatt-class EV charging infrastructure. As adoption moves from pilots to commercial deployments, our central forecast model projects a compound annual growth rate (CAGR) of approximately 23.0% for the 2026–2032 period, with the market scaling toward the multi‑billion-dollar range by the end of the forecast horizon.
Flexible Liquid Cooled Cable Market
This growth is not evenly distributed across applications or regions; instead, it is concentrated in use-cases that require sustained high currents (hundreds to over a thousand amps) combined with ergonomic handling characteristics. These macro numbers provide the context for 2026 decision-making: the window to secure industrial partnerships, certification paths, and supply-chain resilience is now.
Flexible Liquid Cooled Cable Market
What the report delivers — actionable, decision-grade intelligence
- Quantitative market sizing and baseline-to-2032 forecasts with scenario sensitivities to raw material price swings and accelerated EV adoption curves.
- A regulatory and standards matrix mapping IEC, UL, and ISO requirements relevant to liquid-cooled systems — plus clear pathways to certification for product teams and test laboratories.
- Supplier and technology scorecards that benchmark design approaches (water-glycol vs. oil vs. fluorinated coolants), conductor choices, and manufacturability constraints.
- Supply-chain heat maps that identify single‑source exposures, copper procurement levers, and preferred contract structures for 2026 negotiations.
- Commercial playbooks for OEMs, charge-point operators, and EPCs outlining bundling strategies, service economics, and aftermarket revenue models.
- Go-to-market options, from strategic partnerships and licensing to bolt‑on M&A targets, prioritized by ease-of-integration and ROIC under multiple adoption scenarios.
We intentionally withhold granular regional and application splits in this briefing to preserve the report’s role as the primary source for purchase-level intelligence; those detailed sub‑segment datasets and interactive models are accessible in the full PW Consulting report.
Competitive landscape: consolidation with diverse specialists
The supplier ecosystem is a mixture of specialist fabricators that serve heavy industry and high-current thermal applications, and larger electrical component players rapidly commercializing liquid-cooled solutions for the EV charging market. Market concentration metrics indicate meaningful but incomplete consolidation: the leading three players control a significant share of the market, while the top five consolidate a clear majority — a structure that favors strategic alliances without precluding new entrants from gaining traction through differentiated engineering or regional distribution strength.
- Specialist fabricators (examples include firms with deep histories in induction heating, resistance welding, and furnace leads) are distinguished by custom engineering capabilities, rapid turnaround on repairs, and intimate knowledge of high-current terminalization and coolant routing. Their strengths lie in bespoke solutions and service models tailored to heavy industry maintenance cycles.
- Industrial-scale suppliers and Tier‑1 electrification vendors are commercializing modular, standardized liquid-cooled cable systems optimized for electric-vehicle ultra-fast charging. These players leverage systems engineering, ergonomic design, and global support networks to drive commercial rollouts with large charging-station OEMs and network operators.
- Newer entrants and regional manufacturers are pushing innovation at the conductor and hose-material level, while some vendors specialize in very large cross-section cables for steel and ferroalloy plants — showcasing the breadth of technical pathways in the market.
Key names across both archetypes include recognized specialists in water-cooled power leads and a cohort of established electrification players that have introduced liquid‑cooling products and connector platforms for megawatt-class charging. Recent industry moves — such as product integrations between major connector manufacturers and charger OEMs, and field deployments charging above the megawatt threshold — underscore the rapid shift from prototype validation to commercial utilization.
Regulation, materials, and standards: non-negotiable elements of 2026 strategy
Three practical points for engineering and compliance teams:
- Copper remains the predominant conductor material because it offers the best combination of thermal and electrical performance; high‑conductivity electrolytic grades are commonly specified in performance‑critical leads. Securing material supply and specifying contract provisions for grade and traceability will be decisive for product consistency and warranty performance.
- Product designs typically use specialized protective hoses and high-temperature tubing to enclose stranded conductors and enable coolant circulation without sacrificing flexibility. Design tolerances around bend radius, thermal expansion, and terminal swivels materially affect lifecycle costs and handling ergonomics.
- Liquid-cooled systems must comply with a set of international standards — examples include IEC connector frameworks, UL safety standards, and ISO insulation and touch‑temperature limits — and suppliers who can demonstrate early certification or an auditable path to certification will be preferred partners in 2026 procurement cycles.
Notably, the industry is moving toward formalized safety certifications for megawatt-class systems; the first UL certifications supporting 1 MW-class liquid-cooling systems appeared recently, which is lowering a barrier to commercial scale deployments and giving early movers a durable advantage.
Strategic recommendations for 2026 decision-makers
Based on our modeling and vendor due diligence, PW Consulting recommends the following priority actions for organizations allocating capital or signing supply contracts in 2026:
- Prioritize certified partners: Require suppliers to demonstrate compliance roadmaps (IEC/UL/ISO) and factory test evidence; for charger OEMs, mandate fielded-system performance at target current/power levels as a contract milestone.
- Lock in copper supply with quality specifications: Negotiate grade‑specific clauses (e.g., electrolytic copper grades) and consider hedging strategies to mitigate short-term price volatility.
- Pilot ergonomics and maintainability at scale: For EV charging operators, user handling and replacement turnaround times are operational cost drivers; insist on modular terminations and field-replaceable sections in procurement specifications.
- Design for service revenue: Build service networks and remote diagnostics pathways to capture recurring maintenance margins; warranty frameworks should incentivize preventive replacement of high‑wear interfaces.
- Explore targeted M&A and partnerships: Acquire or partner with specialist fabricators to secure IP around terminalization and large-section joints, or to gain regional manufacturing footprints with lower lead times.
- Invest in lab and field validation: Allocate budget for accelerated life testing and temperature/flow profiling, and fund first-of-kind deployments to validate cooling strategies under realistic duty cycles.
Scenarios and risks
Our scenario analysis centers on two sensitivities that will shape outcomes in 2026: the cadence of EV ultra-fast charger rollouts and raw-material inflation. Under the baseline growth trajectory (the ~23% CAGR outlook), commercial scale deployments and standardized connectors will drive sizable volumes and faster maturation of supplier ecosystems. Upside scenarios incorporate regulatory incentives and faster station buildout, while downside outcomes are dominated by sustained copper price shocks or delays in equipment certification.
Operational risk is concentrated in terminal reliability, cooling loop integrity, and field repairability; each has direct consequences for uptime economics in charging networks and for maintenance budgets in industrial installations.
Why PW Consulting’s guidance matters for 2026
Our report combines granular engineering insight with strategic commercial frameworks: market-sizing that starts from audited historical shipments, a forecast model calibrated to adoption drivers, and a vendor evaluation methodology that blends technical scorecards with commercial viability assessments. For boards and investment committees, this delivers a practical bridge between engineering feasibility and balance-sheet implications — enabling conditioned commitments to capital equipment, supply agreements, and M&A pursuits that will be executed during 2026.
Next steps
PW Consulting’s full Flexible Liquid Cooled Cable Market report includes the detailed segmentation datasets, company scorecards, and downloadable forecast models that underpin the executive recommendations summarized here. For procurement teams, product leaders, and corporate strategists preparing commitments in 2026, these assets are designed to accelerate decision-making while reducing program execution risk.
Contact PW Consulting to request the full report, vendor benchmarking appendices, and an in‑person briefing with our industry analysts.
For detailed analysis of this topic, please visit the official page: Flexible Liquid Cooled Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com