

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: MPPO Resin for CCL Market Set to Grow at a 12.48% CAGR During 2026–2032

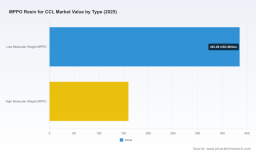
MPPO Resin for CCL Market — Strategic Intelligence Briefing for 2026 Decision-Making
Executive preview
PW Consulting’s new market research brief on MPPO (modified polyphenylene oxide) resins for copper-clad laminates (CCL) synthesizes the commercial, technical, and regulatory forces that will shape supplier and buyer strategies through 2032. The market exhibits strong momentum: from an estimated industry size in 2025 of approximately USD 545 million, we model a structural expansion at a compound annual growth rate (CAGR) of 12.48% across the 2026–2032 forecast window, reaching just over USD 1.24 billion by 2032. That trajectory reflects not only demand from high-speed and high-frequency substrates in 5G and AI data center applications but also a premiumization trend driven by regulatory constraints and raw-material-driven pricing dynamics.
Mppo Resin For Ccl Market
Why this matters to corporate leaders in 2026
As companies plan capacity, product roadmaps, and supply-chain strategies for 2026 and beyond, the MPPO-for-CCL market presents a classic high-growth, high-complexity opportunity. Our analysis is designed to convert that complexity into prioritized actions. Specifically, the report helps stakeholders assess where to invest, when to lock in feedstock agreements, how to structure partnerships with CCL fabricators, and which product attributes will command margins and customer preference over the next investment cycle.
Mppo Resin For Ccl Market
What the report delivers — practical, transaction-ready intelligence
PW Consulting’s deliverable is intentionally operational. Readers can expect a suite of tools and actionable analyses, including:
Mppo Resin For Ccl Market
- Market-sizing and a transparent forecasting model (2020–2032) with scenario toggles for demand elasticity, raw-material shocks, and regulatory tightening.
- Price-sensitivity and margin-impact simulations that translate fluctuations in the primary feedstock (notably 2,6-xylenol) into unit-cost and realized-margin outcomes for resin makers and CCL laminators.
- Capex and capacity-planning playbooks that align ramp schedules with lead indicators from electronics OEM demand (5G infrastructure, AI servers, and automotive high-speed signaling).
- Supplier and technology scorecards, including readiness for halogen-free and low-VOC formulations, certification timelines for compliance regimes such as REACH and RoHS, and manufacturing scalability assessments.
- Go-to-market blueprints for resin formulators and compounders targeting turn-key solutions for high-frequency and low-loss CCL applications, with channel strategies for APAC, North America, and EMEA customers.
- M&A and partnership heatmaps that prioritize targets by technological differentiation, geographic footprint, and near-term capacity availability — framed to support diligence rather than replace it.
- Regulatory and sustainability roadmaps that map product redesign requirements, testing windows, and cost-to-compliance estimates for flame-retardant and halogen-free material transitions.
Market dynamics — drivers, constraints, and the near-term outlook
The ongoing upgrade cycle in telecom infrastructure and the accelerating adoption of AI compute create persistent, secular demand for high-performance substrates. MPPO-derived chemistries are attractive because they balance low dielectric loss, thermal stability and dimensional fidelity — attributes central to high-speed and high-frequency PCB laminates. Our historical reconstruction (2020–2025) shows a steady adoption curve, and the forecast through 2032 embeds both conservative and aggressive scenarios to reflect uncertainty in end-market capex.
Key structural dynamics captured in the report include:
- Upstream feedstock volatility: 2,6-xylenol is the dominant upstream material for PPE/MPPO chemistry. Its price swings and availability materially influence final resin pricing and have driven recent shifts toward upstream vertical integration and long-term offtake contracts.
- Regulatory premiumization: Stricter limits on flame retardants and VOCs are accelerating demand for halogen-free and low-emission resin grades. Compliance costs and testing lead times are non-trivial and must be budgeted into product-program economics.
- Consolidation and concentration effects: The market displays meaningful concentration among a limited set of global suppliers — a structural feature that affects bargaining power, lead times, and the competitive response to demand surges.
- Technology differentiation as a margin driver: Small but meaningful dielectric and mechanical advantages deliver outsized value in applications like AI server PCBs and 5G base stations, where signal integrity and thermal reliability have direct system-level cost implications.
Competitive landscape — what established players and regional champions are doing
Our competitive intelligence section profiles the global leaders and regional specialists shaping material availability and capability sets. Highlights include strategic moves and product positioning from both multinational producers and regional champions:
- SABIC: Positioned with specialty PPE oligomers (e.g., NORYL SA9000) aimed at low-loss CCL applications in 5G and AI server markets. Recent announcements include incremental capacity expansion of PPE oligomers slated for completion in 2H 2026 to support growing demand — a material development for OEMs and laminators to monitor when planning supplier capacity commitments.
- Asahi Kasei and Mitsubishi Gas Chemical: Both Japanese players are investing in modified PPE and PPO chemistries optimized for high-frequency and high-speed CCLs, emphasizing dielectric performance, dimensional stability, and formulation flexibility for multilayer systems.
- Regional Chinese capability: Domestic producers, including major state-backed and private groups, are expanding capacity and technical competencies for PPE-based resins. Notably, recent project launches target large-scale production of low-dielectric thermosetting PPO resin for communication and server substrates.
- Specialists and niche suppliers: Several suppliers across South Korea and China are differentiating through application-specific grades (automotive high-speed signaling, halogen-free laminates) and advanced oligomer chemistries to compete on performance rather than price alone.
These dynamics create windows for strategic partnerships, selective capacity expansion, and targeted R&D investments that can capture premium segments of the value chain.
Risks, sensitivities and scenario planning
Our scenario analysis isolates the dominant risk vectors that enterprises should stress-test in 2026 planning cycles:
- Raw-material shock: A sustained spike in 2,6-xylenol prices compresses margins and shifts cost competitiveness toward integrated suppliers or those with hedging programs.
- Regulatory acceleration: Faster-than-expected bans or tighter exposure limits for legacy flame retardants shorten commercialization horizons for existing formulations.
- Supply concentration events: Capacity outages at a small number of global producers can create temporary supply tightness and price volatility in the resin market, impacting lead times for laminate manufacturers.
- End-market demand variance: Slower-than-expected upgrades in telecom infrastructure or a delay in AI server expansion materially reduces demand for premium low-loss laminates.
For each scenario, the report offers quantified P&L and cash-flow sensitivities, inventory and contract-duration recommendations, and decision thresholds that convert uncertainty into actionable triggers.
Strategic recommendations for 2026 — prioritized, time-bound actions
Based on our analysis, we recommend that corporate decision-makers prioritize the following actions in the 2026 planning horizon:
- Implement dual-sourcing or long-term offtake agreements for critical feedstocks; where possible, pursue partial vertical integration or strategic investments in upstream capacity to mitigate feedstock-driven margin compression.
- Prioritize halogen-free and low-VOC product lines in the next fiscal-year R&D portfolio, and map certification timelines against key customer qualification windows (telecom OEMs, data-center integrators, and automotive Tier 1s).
- Align capacity-expansion or brownfield conversion projects with supplier roadmaps — target funding decisions in H1–H2 2026 to capture demand ramps and avoid mid-cycle shortages.
- Negotiate flexible pricing clauses tied to benchmark feedstock indices or mutual hedging arrangements to share raw-material risk across the value chain.
- Use the report’s supplier scorecards and M&A heatmaps to identify prioritized partners for joint development agreements, licensing, or bolt-on acquisitions that fill technical gaps in low-loss or high-frequency performance.
Why PW Consulting — methodological rigor and commercial relevance
PW Consulting combines materials chemistry know-how with transaction-grade market analytics. Our proprietary forecast model integrates historical shipment data, end-market capex indicators, and raw-material input-cost mapping. The report’s confidence intervals and sensitivity matrices are designed for CFOs, R&D heads, supply-chain leaders, and corporate development teams seeking to make capital allocation decisions that are defensible to boards and investors.
Next steps — how to convert insight into advantage
This briefing is a compact preview of a full report that contains the detailed segmentation, supplier matrices, and downloadable modeling templates required to execute the actions outlined above. To preserve the strategic value of that granular intelligence — including detailed regional and application splits, supplier-specific capacity maps, and model outputs — the full dataset and interactive forecast are available on our report page.
For immediate strategic support, PW Consulting offers tailored briefings, scenario workshops, and diligence packages to operationalize these findings for supply-chain negotiation, product-development prioritization, and M&A screening in 2026.
Contact and access
To access the full MPPO Resin for CCL Market report, interactive forecast, and bespoke advisory engagements, please visit our report page or contact PW Consulting’s industry practice. The full package is structured to be execution-ready for 2026 planning cycles, with modular deliverables to fit strategic, commercial, and technical decision workflows.
For detailed analysis of this topic, please visit the official page: Mppo Resin For Ccl Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com