
Blogs
Construction Equipment Market 2026: Why 6.8% CAGR and 200M USD Revenue Signal a Structural Shift
By pmarketresearch, 2026-09-21
Navigating the Construction Equipment Market: Strategic Trends and Commercial Opportunities
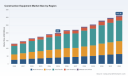
The global construction equipment market has entered a phase of accelerated transformation, driven by converging pressures around decarbonization, digitalization, and shifting infrastructure priorities. Over the 2020–2025 period, total industry revenue expanded from approximately USD 130.5 million to USD 200.0 million, reflecting both post-pandemic recovery and sustained capital deployment across heavy civil and commercial projects. Looking ahead, the market is projected to grow at a compound annual rate of 6.8% through 2032, reaching an estimated USD 313.38 million by the end of the forecast horizon. This trajectory signals more than cyclical recovery; it points to a structural recalibration in how equipment is designed, deployed, financed, and managed across the project lifecycle. For executives and investors, the imperative is no longer simply to track volume growth, but to understand where margin pools are shifting, which capabilities will dictate competitive positioning, and how supply-side constraints will reshape procurement and pricing dynamics.
The industry now operates at a crossroads. Demand fundamentals remain robust, but the prevailing operating environment introduces new layers of complexity that will separate adapting organizations from those constrained by legacy models. Two to three structural challenges define the current inflection point and will shape strategic responses over the next several years.
Cost volatility and supply chain fragmentation continue to pressure OEMs and dealers alike. Steel and aluminum input costs, influenced by domestic trade measures and global commodity fluctuations, directly affect equipment pricing and component sourcing strategies. At the same time, extended lead times for critical subsystems and mixed signals across regional demand cycles complicate production planning. Manufacturers that rely on rigid, high-volume assembly models are encountering margin compression, while those with modular architectures and diversified supplier networks retain greater flexibility.
Regulatory and emissions mandates are accelerating the transition toward electrification and hybrid powertrains, but adoption pathways differ sharply by application and geography. Emission reduction requirements and government sustainability incentives are pushing the industry toward cleaner equipment, yet fleet operators must balance upfront acquisition costs, charging or refueling infrastructure, and total cost of ownership across varied duty cycles. The pace of transition will not be uniform; instead, it will create segmented demand where compliance-driven segments move quickly while cost-sensitive or remote applications lag, requiring differentiated product strategies.
Labor dynamics and skills gaps add another layer of operational complexity. As equipment becomes more connected and automated, the workforce required to operate, maintain, and optimize fleets increasingly demands digital literacy and advanced diagnostics capabilities. Simultaneously, industry groups and OEMs are expanding training partnerships and academy-style programs to address the shortage of qualified technicians and operators. Organizations that treat workforce development as a strategic enabler—rather than a peripheral service offering—will gain advantages in uptime, customer retention, and technology adoption rates.
These challenges do not negate growth; they redefine it. The market’s expansion will be captured by players who treat cost, compliance, and capability as interconnected design constraints rather than isolated issues.
Key Drivers Shaping the Market Trajectory
Several overlapping forces are determining where demand consolidates and how competitive advantage is built. Understanding these drivers provides the foundation for evaluating opportunities across product lines, regions, and service models.
Technological Innovation and Equipment Intelligence
The integration of electrification, automation, and connected machine technologies is shifting the market from a purely hardware-centric paradigm to a performance-and-data-driven one. Manufacturers are embedding digital controls, telematics, and autonomous or semi-autonomous capabilities into mainstream product lines, enabling tighter precision, reduced fuel consumption, and improved site coordination. Electric and hybrid platforms are advancing most visibly in compact and midsize segments, where duty cycles and site infrastructure are more amenable to alternative powertrains, while larger platforms continue to pursue efficiency improvements and selective automation. Industry data indicates accelerating adoption of electric and hybrid construction equipment, fueled by emission reduction mandates and government sustainability incentives. This is not merely a compliance story; it is also an operational one, as operators seek to lower fuel exposure, reduce maintenance variability, and align with project owners’ sustainability requirements.
Recent product activity illustrates how quickly the innovation frontier is moving. At a major 2026 trade event, one manufacturer showcased a broad lineup of machines spanning compact, midsize, and full-size excavators, alongside an electric mini track loader, signaling the widening scope of electrification across categories. Parallel updates in midsize excavators have introduced new digital control architectures and cab technologies aimed at improving precision and operator experience. These developments suggest that differentiation is increasingly tied to integrated systems—where machine performance, interface design, and data availability converge—rather than raw mechanical capacity alone.
Policy and Regulatory Environment
Government spending programs and trade conditions are shaping both demand timing and cost structures. Infrastructure investment under major U.S. legislation continues to support equipment utilization, with peak disbursements through 2026 reinforcing demand across earthmoving and material handling categories. This public capital pipeline provides near-term demand visibility, but it also heightens the importance of fleet readiness and service capacity, since utilization peaks can strain maintenance networks and parts availability.
Trade policy adds complexity to sourcing and pricing. Domestic tariffs on steel and aluminum continue to influence component costs and pricing strategies for construction equipment, pushing manufacturers to reassess bill-of-materials structures, supplier geographies, and product mix. In this environment, pricing power is increasingly tied to value communication: operators are more willing to accept premium pricing when it is clearly linked to reduced operating cost, compliance assurance, or productivity gains.
PW Consulting Health Care Research Center
Demand-Side Shifts in Customer Behavior
End users are recalibrating procurement criteria around total lifecycle economics, emissions profiles, and uptime assurance. Infrastructure development remains the largest application anchor, supported by ongoing civil works, transport, and energy-related projects, while commercial, industrial, and residential activity contributes additional demand layers that vary by region and financing conditions. Across segments, there is growing interest in equipment that can support stricter site emissions expectations, reduce fuel exposure, and integrate with digital project workflows. Rental and municipal markets, in particular, are influencing product preferences for compact and midsize machines that can be deployed flexibly and maintained within shared service networks.
This behavioral shift is changing how value is sold and captured. Customers increasingly evaluate platforms based on what they enable—faster cycle times, lower emissions, better precision, or simplified maintenance—rather than on machine specifications in isolation. As a result, OEMs that provide integrated support ecosystems, including telematics, service planning, and operator training, are better positioned to defend margins and deepen customer relationships.
Supply Chain and Cost Structure Evolution
Raw material price volatility, especially in steel and fuel, remains a central margin factor for equipment manufacturers amid global commodity markets. This creates a continuing need for cost discipline, supplier diversification, and product architectures that can absorb input fluctuations without eroding competitiveness. At the same time, the shift toward electrified and connected equipment is reshaping the cost base itself: battery systems, power electronics, software development, and data infrastructure are becoming more significant components of the value chain. Companies that manage this transition as a portfolio—balancing traditional mechanical cost control with new investment in electronics, software, and energy systems—are more likely to protect profitability as the mix shifts.
Competitive Landscape and Leading Strategies
The market remains moderately concentrated, with a small group of large global players commanding a substantial share of revenue and capabilities. This concentration reflects the capital intensity of product development, the scale required to serve global infrastructure demand, and the importance of service networks in sustaining customer relationships. At the same time, the competitive field is evolving as regional specialists, emerging manufacturers, and technology-focused entrants target specific niches and application segments.
Heavy Equipment Market
Leading incumbents are pursuing a mix of scale, technology integration, and segmented specialization. Some of the largest manufacturers anchor their positions on broad equipment portfolios spanning excavators, loaders, haul trucks, graders, and cranes, paired with connected platform technologies and electrification roadmaps. Their scale advantage supports global service reach, parts availability, and the ability to invest across multiple technology tracks simultaneously. In parallel, other strong players differentiate through focused portfolio depth, whether in compact and midsize equipment, large-capacity earthmoving and lifting systems, or electric and hybrid platforms with an emphasis on zero-emission performance and operator safety.
Several distinctive strategic positions are evident across the competitive set:
- Broad-line scale and connected ecosystems: A few global manufacturers combine wide product coverage with integrated data and software offerings, emphasizing automation, remote monitoring, and service optimization. Their recent disclosures and innovation programs reflect a continued focus on profitable growth, advanced electrification, and workforce development initiatives designed to support future capability needs.
- Autonomy and construction workflow integration: One major manufacturer has moved decisively toward large-scale autonomous hauling and expanded engineering collaborations aimed at workforce development, signaling that scale automation paired with talent pipelines is becoming a strategic pillar rather than a niche experiment.
- Compact and midsize digital productivity: Another leader has updated midsize excavators with enhanced digital controls and cab technology, underscoring the importance of precision, usability, and operator-centric design in segments where rental, municipal, and smaller contractor demand is active.
- Electrification and zero-emission focus: European and other manufacturers are emphasizing electric and hybrid platforms, targeting compliance-driven applications and customers seeking to reduce on-site emissions while maintaining performance and safety standards.
- Specialist engineering for demanding applications: High-capacity excavators, cranes, and specialized earthmoving equipment continue to serve segments where engineering rigor, load capacity, and application-specific durability justify differentiated positioning.
- Cost-effective global export and infrastructure reach: Chinese manufacturers continue to compete on durable, cost-competitive machinery for emerging markets and infrastructure projects, broadening export-oriented offerings across loaders, excavators, and cranes.
- Rental and municipal adjacency: Some mid-tier manufacturers maintain strong positioning in compact and midsize categories with particular relevance to rental fleets and municipal users, where machine versatility, serviceability, and total cost of ownership are decisive.
The landscape is not static. Consolidation pressure exists where scale economics, service network coverage, and technology investment requirements favor larger players, particularly in connected and electrified platforms. At the same time, fragmentation persists in segments where application specificity, regional distribution, and price sensitivity create room for targeted specialists and new entrants. The most likely outcome over the next several years is a layered market: a concentrated core of global-scale manufacturers competing on portfolios, data, and electrification, alongside a diverse periphery of specialists serving niche duty cycles, regional demand, and specific customer segments. Companies that can navigate both layers—either by building focused strength or by partnering for distribution and service—will shape the market’s direction.
Future Trends and Commercial Implications
Based on current data and industry momentum, three trends are likely to define the market over the next three to five years, each carrying distinct commercial implications.
1. Electrification will progress in waves, not uniformly. Adoption will accelerate fastest where duty cycles, site infrastructure, and regulatory pressure align—often in compact and midsize categories, urban work, and compliance-sensitive applications. Larger platforms will see more gradual transitions as energy storage, charging logistics, and total cost economics continue to mature. The commercial opportunity lies in offering flexible powertrain choices, robust service support for alternative energy systems, and clear total cost of ownership narratives that justify premium positioning where justified. The risk is misjudging the pace in segments where infrastructure and operating conditions limit near-term viability, leading to misaligned product investment or pricing expectations.
2. Connected and data-enabled equipment will become a standard expectation rather than a premium feature. Telematics, remote diagnostics, operator-assist technologies, and workflow integration will increasingly influence purchasing decisions and service contracts. This creates opportunities to expand recurring and service-based revenue, improve fleet utilization, and differentiate through uptime and productivity outcomes. It also raises the bar for cybersecurity, software lifecycle management, and data interoperability. Organizations that treat software and data as core product components—rather than add-ons—will be better positioned to capture long-term value, while those that underinvest may face commoditization pressure.
Construction Equipment Rental Market
3. Infrastructure spending and trade conditions will drive demand peaks and cost volatility in tandem. Public capital deployment continues to support utilization through the mid-2020s, reinforcing demand for earthmoving and material handling equipment. At the same time, trade measures on key inputs and commodity fluctuations will continue to influence margins and pricing strategies. The commercial implication is that volume growth alone will not guarantee profitability; firms that can align production flexibility, supplier strategy, and value-based pricing will be better equipped to convert favorable demand into durable margins. The uncertainty lies in the timing and duration of spending peaks, as well as the potential for abrupt cost shocks that can compress returns if not managed proactively.
Strategic Actions for Decision Makers
Different stakeholders face distinct priorities, but all benefit from a disciplined view of where value is being created and where exposure is building. The following actions are most relevant across the main audiences in this market.
For manufacturers and equipment providers: Prioritize portfolio decisions that match powertrain and technology investments to real application economics rather than uniform rollout assumptions. Invest in service and data capabilities that support uptime, operator training, and lifecycle economics, since these increasingly determine customer retention and margin resilience. Strengthen supplier diversification and product architecture flexibility to absorb input cost volatility without sacrificing competitiveness. Where scale and connectivity matter, pursue partnerships or platform strategies that accelerate software, electrification, and autonomy capabilities without overextending internal resources.
For investors and corporate development teams: Focus on companies that demonstrate credible progress in electrification, connected services, and cost discipline, evaluated through the lens of application fit and total cost of ownership rather than headline product announcements alone. Monitor segments where rental, municipal, and infrastructure demand intersect with compact and midsize equipment, as these areas often combine relatively faster adoption cycles with recurring service potential. Assess exposure to trade-driven cost dynamics and supply chain flexibility, which will increasingly differentiate performers in a volatile input environment.
For fleet operators, contractors, and procurement leaders: Evaluate purchases against operational outcomes—emissions compliance, fuel and energy exposure, precision, maintenance predictability, and integration with site workflows—rather than specification lists in isolation. Build internal capabilities for operating and maintaining connected and electrified equipment, including technician training and data-driven maintenance planning, to capture the productivity and uptime benefits these platforms can enable. Where utilization patterns are uneven, consider rental, leasing, or mixed-fleet strategies that preserve flexibility while aligning equipment choices with project-specific requirements.
The construction equipment market is expanding, but the next phase of value creation will be uneven and selective. Companies and investors that understand the interplay of technology, policy, demand behavior, and cost structure will be better positioned to capture growth without overexposing themselves to transition risks. For leaders who need more granular segmentation, region-specific demand dynamics, and tailored scenario analysis, the full research report provides detailed breakdowns and customized guidance to support more precise planning and execution.
For detailed analysis of this topic, please visit the official page: Construction Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Brake Calipers Market 2026: Unpacking the Real Drivers Behind 5.4% CAGR Growth Through 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Global Brake Calipers Market
The brake calipers market is navigating a period of structural transformation, driven by evolving vehicle architectures, tightening safety standards, and the electrification of mobility. Market valuations have demonstrated steady expansion over the past half decade, with revenue climbing from approximately 1.22 billion USD in 2020 to an estimated 1.59 billion USD by 2025. Forward projections indicate continued momentum, with the market expected to reach roughly 2.30 billion USD by 2032, translating to a compound annual growth rate of 5.4 percent across the 2026 to 2032 forecast horizon. This trajectory reflects more than incremental volume growth; it signals a recalibration of how braking systems are designed, integrated, and monetized across passenger cars, commercial vehicles, and two-wheelers.
PW Consulting
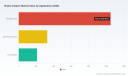
Beneath the headline figures lies a market that is increasingly segmented by technology readiness, regional manufacturing footprints, and the pace of electronic integration. The revenue distribution shows clear geographic weight, with Asia Pacific generating the largest share, followed by Europe and North America, while Latin America and the Middle East and Africa contribute smaller but strategically important volumes. On the product side, floating calipers continue to command a larger revenue pool than fixed calipers, reflecting their prevalence in mainstream passenger and commercial platforms. Application-wise, passenger cars dominate the revenue mix, with commercial vehicles and two-wheelers forming meaningful secondary segments. Industry concentration remains moderately high, with the top three players accounting for approximately 45 percent of market revenue and the top five reaching around 65 percent, underscoring the influence of established OEMs suppliers and Tier 1 integrators.
This landscape is not static. The market stands at an inflection point where conventional hydraulic braking is being augmented, and in some segments displaced, by electronically controlled architectures. Recognizing where the market is headed requires looking past aggregate growth rates and examining the forces reshaping supplier positioning, cost structures, and demand patterns.
Brake Disc Market
Market Snapshot: Scale, Structure, and the Pressure Points
A Growing but Increasingly Complex Revenue Base
The market's expansion from 2020 through 2025 reflects a steady recovery and normalization in global automotive production, coupled with ongoing replacement demand in aftermarket channels. The projected climb to 2.30 billion USD by 2032 suggests that volume growth will be supported by platform refreshes, fleet modernization, and the gradual penetration of advanced braking features into mass-market segments. Yet growth is uneven. Regions with faster electrification adoption and stronger commercial vehicle activity are likely to outpace mature markets where replacement cycles are longer and price competition is more intense.
The concentration profile indicates that scale, engineering depth, and long-term OEM relationships still matter. Suppliers with broad portfolios spanning passenger and commercial segments, along with the ability to integrate electronic components, are well positioned to capture disproportionate value. At the same time, the presence of specialized high-performance and aftermarket-focused players highlights a market that rewards differentiated technical positioning as much as volume scale.
Key Challenges and Turning Points
Three pressure points are reshaping how participants approach the market.
- Technology transition and integration complexity. The shift toward electronically controlled braking and brake-by-wire architectures is changing the caliper from a purely mechanical actuator into a node within a broader safety-critical system. This raises engineering barriers, validates new testing and certification pathways, and forces suppliers to manage software and hardware development in tandem.
- Cost and sourcing pressures amid electrification. Vehicle platforms are evolving, and the brake caliper's role is being re-evaluated in the context of regenerative braking, weight targets, and packaging constraints. Suppliers must balance material choices, machining precision, and calibration costs while competing on price in segments where electrification does not immediately translate into higher unit economics.
- Regional volatility and supply chain realignment. Manufacturing footprints, logistics reliability, and regulatory divergence across markets are creating uneven operating conditions. Suppliers that depend on concentrated sourcing or single-region assembly face greater exposure to disruptions, while those with diversified production and localized engineering support are better equipped to maintain continuity.
These challenges are not merely operational headaches; they are strategic signals. They point to a market where the value equation is moving from component volume toward system capability, regional responsiveness, and the ability to meet functional safety requirements in electronically controlled environments.
Key Drivers Reshaping the Brake Calipers Market
Technology Innovation and the Rise of Electronically Controlled Braking
The most consequential driver is the accelerating integration of electronics into braking systems. Brake-by-wire and electro-hydraulic architectures are extending the role of the caliper beyond traditional actuation, enabling faster response, adaptive force distribution, and tighter integration with vehicle stability and regenerative braking strategies. Fourth-generation brake-by-wire systems have demonstrated full electronic actuation of calipers while meeting high automotive functional safety standards, marking a practical step toward software-defined braking. This evolution matters because it changes the caliper's development cycle: suppliers must account for sensor feedback loops, fail-safe behavior, and calibration across a wider range of driving conditions.
Worldwide Aircraft Brake Calipers Market
In parallel, high-performance and motorsport applications continue to push material and hydraulic design boundaries. New small-bore caliper configurations and carbon ceramic big brake kits illustrate how specialized segments are advancing thermal management, stiffness, and packaging efficiency. While these are niche volumes, they often serve as technology proving grounds and brand amplifiers that can influence premium OE programs and aftermarket credibility.
Policy and Regulatory Environment: Safety, Localization, and Functional Standards
Regulatory and safety requirements are increasingly shaping both product design and market access. Functional safety expectations for electronically controlled braking are rising, with ASIL-D class compliance becoming a relevant benchmark for systems that rely on electronic actuation. This raises the bar for validation, traceability, and supplier capability, favoring organizations with established safety engineering processes and mature testing infrastructure.
Localization trends are also influencing market dynamics. Partnerships and joint ventures aimed at adapting advanced braking technologies for regional markets illustrate how suppliers are responding to content requirements, cost structures, and speed-to-market considerations. For instance, collaborations focused on localizing brake-by-wire solutions in China and forming air brake joint ventures in India reflect a broader pattern: advanced brake systems are being adapted to regional manufacturing ecosystems rather than distributed solely through centralized global supply chains.
Demand-Side Shifts: Electrification, Fleet Mix, and Performance Expectations
Demand is being reshaped by three interrelated shifts. First, electrification is altering brake duty cycles. Regenerative braking reduces friction braking usage in certain driving conditions, which can affect wear patterns, caliper utilization, and the relative importance of precision actuation and thermal stability. Second, commercial vehicle demand remains a structural pillar, with fleet operators prioritizing downtime reduction, safety performance, and integrated braking solutions that can support higher vehicle weights and demanding duty cycles. Third, consumer and fleet expectations around safety, stopping performance, and system responsiveness are rising, encouraging adoption of advanced braking features that were once confined to premium or motorsport contexts.
These demand dynamics create a bifurcated opportunity set. In mainstream passenger vehicles, the focus is on reliability, cost efficiency, and incremental electronic integration. In premium, performance, and commercial segments, the opportunity lies in higher-specification calipers, tighter system integration, and solutions that support advanced safety and vehicle dynamics functions.
Supply Chain and Cost Structure Realignment
Cost structures are being reexamined as suppliers balance precision manufacturing with the added complexity of electronic integration. Material selection, machining tolerances, and assembly automation remain critical levers, but the growing presence of software-defined components means that value capture is increasingly tied to engineering capability and system-level optimization rather than component pricing alone. Supply chain resilience has also gained prominence, with participants enhancing multi-source sourcing, regional assembly options, and inventory strategies to reduce exposure to logistics bottlenecks and demand swings.
Recent product and funding activity reflects this environment. Investments in caliper production capabilities, launches of matched brake caliper, pad, and rotor packages, and continued motorsport-focused innovations all point to a market where suppliers are pursuing both scale efficiency and differentiated performance positioning simultaneously.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Leading Participants
The competitive field is shaped by companies with distinct technological emphases and customer bases. Several patterns stand out.
- High-performance and motorsport specialization. Some suppliers concentrate on high-performance calipers for luxury vehicles, supercars, and motorsport applications. This positioning emphasizes thermal performance, stiffness, weight optimization, and brand prestige. Specialized caliper designs, including small-bore configurations and carbon ceramic big brake kits, reinforce a premium performance narrative that can spill over into broader OE credibility and aftermarket demand.
- Electronic integration and OE breadth. Other leaders focus on brake calipers integrated with electronic control systems and ABS for global automotive OEMs, or on advanced calipers for intelligent safety systems and electric vehicle platforms. These players benefit from system-level engineering capabilities, broad OEM relationships, and the ability to align caliper design with vehicle-wide braking and safety architectures.
- Commercial vehicle and integrated braking solutions. Suppliers with strong commercial vehicle footprints are expanding integrated braking solutions and caliper offerings tailored to heavier-duty applications. This segment values durability, serviceability, and system reliability, and is increasingly receptive to electronically supported braking functions where they improve safety and operational efficiency.
- Regional OEM integration and component breadth. Additional participants emphasize brake calipers and related components for OEM integration across Asian and global vehicle markets, often combining calipers with complementary elements such as ceramic pads. This breadth can strengthen package value and improve positioning in cost-sensitive but volume-rich segments.
- Aftermarket and replacement focus. Some companies concentrate on replacement and OEM brake calipers for standard and heavy-duty vehicles, or on premium calipers matched with pads and rotors for enhanced safety and performance. This strategy targets continuity, fitment assurance, and the aftermarket's need for reliable, application-specific solutions.
Differentiation and Competitive Advantage
Differentiation in this market is increasingly multidimensional. Volume scale remains important, but it is no longer sufficient on its own. Suppliers that can combine precision mechanical design with electronic system integration, functional safety competence, and regional manufacturing flexibility are gaining relative advantage. High-performance specialists leverage technical heritage and brand association to command premium positioning, while broader OE-focused suppliers rely on integration depth, platform coverage, and system-level support. Meanwhile, aftermarket-oriented players compete on application coverage, quality consistency, and package completeness.
A notable competitive dynamic is the growing relevance of partnerships and joint ventures. Collaborations that localize advanced braking technologies or combine complementary capabilities are enabling faster market access, improved cost alignment, and stronger regional presence. This suggests that competitive advantage will increasingly depend on both internal engineering strength and the ability to structure alliances that reduce time-to-market and improve local responsiveness.
Market Structure Evolution: Consolidation, Differentiation, and New Entrants
The market is likely to continue evolving along three paths. Consolidation pressure will persist among suppliers seeking to strengthen OEM coverage, expand geographic reach, and build electronic integration capabilities through scale and acquisition. Differentiation will deepen as performance, commercial, and electronically controlled braking segments diverge in spec, validation requirements, and pricing dynamics. New entrants and niche players may find opportunities in specialized applications, regional localization, or targeted aftermarket packages, especially where they can offer clear technical or service advantages without needing to match the full breadth of global Tier 1 portfolios.
Recent launches and investment activity support this image of a market in motion. From motorsport small-bore calipers and premium matched brake packages to fourth-generation brake-by-wire systems and funded production advancements, participants are pursuing multiple routes to growth. The common thread is a push toward higher technical value and stronger application alignment rather than reliance on commodity volume alone.
Future Outlook: Trends and Commercial Opportunities
Trend 1: Software-Defined and Electronically Actuated Braking Will Move Deeper into Production
Electronically controlled braking is poised to expand beyond premium and specialized applications as vehicle architectures increasingly accommodate brake-by-wire and electro-hydraulic solutions. The commercial opportunity lies in calipers and associated system components that can meet strict functional safety requirements, support precise electronic actuation, and integrate cleanly with vehicle control strategies. Suppliers that can deliver validated, ASIL-compliant actuation performance and offer scalable integration pathways will be better positioned to participate in next-generation platform programs. The uncertainty here relates to adoption pace across mass-market segments, where cost sensitivity and validation timelines can slow deployment.
Trend 2: Regionalization and Localized Brake Technology Deployment Will Intensify
Market access strategies are increasingly shaped by localization. Partnerships and joint ventures that adapt advanced braking technologies for specific regions reflect the reality that cost, content expectations, and manufacturing ecosystems vary significantly by market. The commercial opportunity is twofold: suppliers can build stronger regional footholds by aligning production and engineering support with local demand, while customers can benefit from shorter lead times and improved cost structures. The risk is that localization efforts can fragment engineering resources and complicate harmonization across global platforms if not managed with clear architecture standards.
Trend 3: Performance, Commercial, and Aftermarket Segments Will Diverge Further in Spec and Value
The market is likely to see greater divergence between mainstream, performance, commercial, and aftermarket requirements. Mainstream passenger applications will continue to emphasize reliability, cost efficiency, and incremental electronic features. Performance and motorsport-related segments will keep pushing thermal, structural, and packaging boundaries, serving as both revenue niches and brand enablers. Commercial vehicle demand will favor integrated solutions that reduce downtime and support safety under demanding duty cycles. Aftermarket buyers will continue to value fitment confidence, application coverage, and package completeness.
The commercial opportunity is to align product portfolios and service models with these distinct value equations rather than treating the caliper market as a single homogeneous segment. Suppliers and investors that can identify which segment offers the best mix of margin, growth, and competitive defensibility will be better placed to allocate capital and engineering resources.
Strategic Actions for Decision-Makers
For Brake System Manufacturers and Tier 1 Suppliers
- Prioritize electronic integration and functional safety capability as core competencies, not optional add-ons. Investing in validation, calibration, and system-level engineering will increasingly determine eligibility for advanced braking programs.
- Align production footprints and sourcing strategies with regional demand patterns. Where localization trends are strengthening, consider partnerships or assembly options that improve responsiveness while preserving engineering consistency.
- Segment the portfolio deliberately. Mainstream, performance, commercial, and aftermarket applications require different design priorities, pricing strategies, and service models. Avoid diluting focus by treating all segments with the same value proposition.
For Investors and Strategic Planners
- Evaluate exposure to electronic braking adoption curves and regional localization trends when assessing growth potential. Revenue expansion will be uneven, and value capture will favor suppliers with the right combination of technology readiness and market access.
- Look beyond top-line growth to concentration and differentiation dynamics. In a market where leading players already hold substantial share, incremental opportunity often comes from specialization, regional positioning, or system-integration depth rather than undifferentiated volume gains.
- Monitor partnership activity and product launches as early indicators of strategic direction. Joint ventures, funded production expansions, and advanced system unveilings often signal where capabilities and market access are being built.
For Procurement and Fleet Decision-Makers
- Assess braking solutions based on total system fit, including electronic compatibility, functional safety readiness, and serviceability, rather than component price alone. As braking architectures become more integrated, the caliper's role within the broader system becomes more consequential.
- Plan for segment-specific requirements. Commercial fleets, passenger vehicle operations, and performance-oriented applications have distinct priorities, and purchasing strategies should reflect those differences in spec, validation, and support expectations.
- Build supplier evaluation frameworks that account for regional continuity, engineering support, and the ability to support evolving electronic braking functions over the vehicle lifecycle.
Closing Perspective
The brake calipers market is expanding, but the more important story is how its value base is shifting. Growth to roughly 2.30 billion USD by 2032, at a 5.4 percent CAGR across the forecast period, provides a useful macro frame, yet the real strategic challenge lies in navigating technology transition, regionalization, and segmentation divergence. Suppliers and investors that treat the market as a set of distinct value equations, and that invest accordingly in electronic integration, functional safety, and regional responsiveness, are more likely to capture durable advantage.
Detailed segment trajectories, regional breakdowns, competitor benchmarking, and application-level demand scenarios can sharpen these decisions further. For decision-makers seeking a deeper, customizable view of the market landscape and its commercial implications, the full PW Consulting research report offers expanded data and tailored analysis across the segments and dynamics discussed here.
For detailed analysis of this topic, please visit the official page: Brake Calipers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Appliance Power Cord Market: How 6.8% CAGR and PVC-Dominant Supply Chains Are Reshaping Competition
By pmarketresearch, 2026-09-21
The Appliance Power Cord Market: Strategic Trends and Commercial Opportunities in a Growing Ecosystem
The appliance power cord market has evolved far beyond its origins as a basic utility component, transforming into a strategically significant segment where safety, material science, and global compatibility converge. Over the past five years, the industry has navigated supply chain recalibrations, tightening regulatory frameworks, and shifting appliance architectures that collectively redefine how manufacturers, distributors, and end-users value power connectivity. As households and commercial facilities increasingly prioritize reliability, energy efficiency, and interoperability, power cords are no longer viewed as interchangeable commodities. They function as critical interface components that influence product safety certifications, warranty exposure, and brand reputation. Understanding the structural dynamics of this market requires looking beyond unit volumes and examining the underlying forces shaping pricing, innovation, and competitive positioning.
Market Landscape and Core Challenges
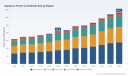
The global appliance power cord market has demonstrated steady expansion, with revenues growing from approximately $160.5 million in 2020 to an estimated $211.5 million in 2025, and is projected to reach roughly $333.4 million by 2032. This trajectory reflects a compound annual growth rate of approximately 6.8 percent, signaling sustained demand supported by replacement cycles, appliance modernization, and expanding manufacturing footprints. The market structure remains moderately fragmented, with the top three participants collectively holding roughly 27.5 percent of total revenue and the top five accounting for approximately 35.2 percent. This concentration level suggests that while scale players command meaningful share, specialized manufacturers retain viable positioning through customization, regional compliance expertise, and rapid fulfillment capabilities.
Beneath the headline growth, several structural challenges are reshaping how participants compete and allocate capital. First, safety certification and standardization complexity has intensified. Compliance with testing protocols such as UL 817 requires rigorous validation of durability, insulation integrity, and continuous load performance, raising the technical barrier for new entrants and increasing time-to-market for product lines. Second, material cost volatility and supply continuity remain persistent pressures. Copper conductor pricing and PVC insulation availability influence margin structures, and while supply trends have remained relatively stable through mid-2026, geopolitical trade flows, freight fluctuations, and regional manufacturing capacity still create pockets of disruption. Third, the market faces a tipping point in application diversity. As appliance categories expand and electrical architectures become more sophisticated, manufacturers must balance standardized inventory with highly customized configurations that meet local plug types, voltage requirements, and specialty use cases such as hospital-grade or heavy-duty environments.
Worldwide Domestic Appliances Market
These challenges are not merely operational friction points; they are strategic filters. Companies that can efficiently navigate certification pathways, maintain resilient material sourcing, and align product portfolios with evolving appliance lifecycles are better positioned to capture margin while defending against commoditization. Conversely, players relying on undifferentiated volume strategies risk exposure to price compression and interchangeability substitution.
Key Drivers Shaping Market Direction
Technological Innovation and Product Differentiation
Advancements in cord construction, terminal design, and insulation materials are steadily redefining performance expectations. Manufacturers are expanding high-voltage configurations, specialized ROJ-style connections, and hospital-grade variants that meet stringent durability and safety thresholds. These innovations respond directly to appliance architectures that demand higher continuous loads, improved heat resistance, and longer operational lifespans. The introduction of new heavy-duty and international configurations, alongside expanded high-voltage options compatible with major household appliances, illustrates how product roadmaps are being shaped by real-world usage requirements rather than baseline compliance alone. For commercial and residential appliance makers, access to differentiated cord sets translates into reduced warranty risk, simplified regional deployment, and stronger value proposition in premium product lines.
Regulatory and Standards Evolution
Regulatory frameworks continue to act as both a constraint and a catalyst. The UL 817 standard establishes rigorous testing expectations for safety and durability, effectively functioning as a market gatekeeper that rewards manufacturers with mature quality systems and transparent supply traceability. At the same time, electrical code updates are altering load management expectations. Recent NEC revisions addressing continuous load calculations for electric appliances, including dishwashers, ease certain engineering assumptions while reinforcing the importance of reliable cord performance under sustained operation. These regulatory shifts push manufacturers to design for durability rather than minimal compliance, and they increase the value of configurations that are pre-validated for specific appliance categories. In practical terms, certification readiness has become a strategic asset, not just a checkbox.
Demand-Side Shifts in Consumer and Commercial Behavior
End-user expectations are increasingly shaped by energy efficiency mandates and total cost of ownership considerations. Efficiency-driven appliance adoption places greater emphasis on components that can sustain performance over longer service lives, creating demand for durable, longer-lasting power cords in consumer households. Simultaneously, commercial facilities and rental housing operators prioritize configurations that minimize maintenance interruptions and simplify inventory management across multiple appliance types. The growing availability of hospital-grade and heavy-duty options reflects this broadening demand spectrum, where reliability specifications are tied directly to operational continuity. For manufacturers, this means product portfolios must accommodate both everyday replacement cycles and specialty applications without fragmenting production efficiency.
Supply Chain and Cost Structure Dynamics
Material stability has provided a favorable backdrop, with copper and PVC insulation remaining the primary inputs and supply trends holding relatively steady through mid-2026. Yet stability in raw materials does not eliminate structural cost pressures. Freight variability, regional labor dynamics, and the cost of maintaining multiple plug combinations and international variants can erode margins if production is poorly optimized. Companies that reduce minimum order friction, consolidate configurable SKUs, and align production with regional demand clusters achieve better cost discipline while preserving flexibility. In an environment where differentiation increasingly hinges on availability, lead time, and compliance assurance, supply chain agility has become a direct competitive advantage.
Competitive Landscape and Leading Strategies
The competitive field features a mix of focused domestic manufacturers and globally positioned suppliers, each leveraging distinct strategic angles. Quail Electronics has built a reputation around North American and international appliance power cords, including two- and three-prong options and high-voltage configurations tailored for refrigerators, washers, dryers, and ranges. Its approach emphasizes broad compatibility with major household appliances, which supports OEM and distributor relationships that value standardized yet robust solutions. Kord King positions itself as a large-scale U.S. manufacturer of custom appliance power cords, offering a wide range of plug combinations alongside hospital-grade and heavy-duty variants for both household and commercial applications. This customization-heavy model enables the company to serve customers with specialized requirements while maintaining a recognizable domestic manufacturing footprint. Interpower Corporation differentiates through country-specific international and North American cord sets, with a notable emphasis on accessibility through no-minimum-order policies. This flexibility lowers entry barriers for smaller appliance assemblers and export-focused operations that need localized compliance without large inventory commitments.
Additional players reinforce the market's diversity. Consolidated Electronic Wire & Cable and Electri-Cord Manufacturing both emphasize custom and standard power cords for household appliances, with offerings that span shielded, hospital-grade, and domestically or internationally compliant configurations. Volex Group brings a more global manufacturing perspective, supplying power cords and plugs across appliance and consumer electronics applications, which allows it to address multi-region demand with broader scale and cross-market synergies.
Strategic differentiation among these leaders clusters around three themes. First, certification and safety positioning functions as a trust signal that reduces buyer risk, particularly in applications where failure carries significant operational or liability consequences. Second, configuration breadth and customization capability determine how well a supplier can serve mixed appliance portfolios without forcing customers into overly narrow SKU sets. Third, fulfillment flexibility, including low minimum order thresholds and rapid international variant availability, enables smaller and mid-sized appliance manufacturers to source reliably without incurring excess inventory risk.
The competitive landscape is evolving through selective consolidation and persistent differentiation. While the market remains accessible to specialized suppliers, the premium increasingly flows to firms that can combine compliance assurance, regional variant depth, and efficient configuration management. New entrants face a meaningful hurdle in certification infrastructure and material continuity, but opportunities exist for players that identify underserved regional plug requirements or niche application segments such as specialty commercial appliances and higher-duty cycle environments. The result is a market that rewards operational precision and customer-specific value creation rather than pure volume competition.
Power Cords & Extension Cords Market
Forward Outlook: Three Trends Shaping the Next Three to Five Years
First, compliance-integrated product design will become a standard expectation rather than a differentiator. As safety and durability testing requirements remain entrenched and electrical code adjustments continue to influence load assumptions, cord suppliers that embed validation into their development cycles will reduce customer onboarding friction and shorten qualification timelines. The commercial opportunity lies in offering pre-certified configurations mapped to common appliance categories, which can lower procurement complexity and support faster time-to-market for appliance manufacturers. The primary risk is regulatory drift; if testing expectations tighten further or regional standards diverge, suppliers with less agile quality systems may face repeated redesign cycles.
Second, regional interoperability will drive demand for highly configurable yet efficiently managed cord portfolios. Global appliance trade and multi-market product launches require power solutions that accommodate local plug types, voltage standards, and specialty ratings without fragmenting into unmanageable SKU proliferation. Suppliers that invest in modular design, strategic inventory clustering, and clear international variant management will be better equipped to serve export-oriented and multi-region appliance programs. The upside is expanded addressable demand across cross-border appliance supply chains. The uncertainty lies in trade policy shifts and regional manufacturing localization pressures, which could alter sourcing patterns and favor domestic production in certain markets.
Third, durability and lifecycle value will command growing commercial attention. Energy efficiency mandates and total cost of ownership considerations are shifting buyer focus toward components that sustain performance through longer appliance lifespans. This dynamic favors reinforced insulation, higher-duty construction, and configurations validated for continuous use, particularly in households and commercial settings where replacement disruption is costly. The opportunity is to position durable cord sets as risk-reduction assets that support appliance reliability claims and reduce field failure exposure. The risk is that durability premiums must be justified through demonstrable performance and clear warranty or maintenance benefits; otherwise, price-sensitive buyers may continue favoring lower-cost alternatives in non-critical applications.
Strategic Considerations for Decision-Makers
For appliance manufacturers and original equipment suppliers, the priority is to treat power cord selection as a design-and-compliance decision with downstream operational implications. Selecting configurations that align with target market plug types, voltage ranges, and durability expectations can streamline certification, reduce field failure risk, and simplify warranty management. It is equally important to evaluate suppliers not only on unit price but on configuration breadth, certification readiness, and fulfillment flexibility, since these factors influence program launch speed and inventory efficiency. Where product roadmaps include international variants or specialty applications, partnering with suppliers that already maintain validated regional options can shorten development cycles and reduce qualification burden.
For investors evaluating exposure to this segment, the value proposition lies less in headline growth alone and more in the structural resilience of compliant, differentiated product lines. Companies with mature safety validation processes, manageable material exposure, and the ability to serve both standard and specialty applications are better positioned to defend margins across demand cycles. Investment theses should account for the impact of regulatory continuity, regional trade dynamics, and the extent to which a supplier can translate configuration complexity into commercial advantage rather than operational cost. Diversification across standard household applications and higher-specification commercial or hospital-grade segments can provide a more balanced exposure profile.
For procurement and supply chain leaders, the practical focus should be on minimizing qualification risk and inventory friction while preserving access to required configurations. Where demand spans multiple appliance types or regions, consolidating around suppliers with pre-validated variants and flexible order thresholds can reduce administrative overhead and improve responsiveness to design changes or late-stage program adjustments. Maintaining clear visibility into material continuity, certification status, and lead-time behavior for critical cord variants supports more resilient sourcing decisions, particularly when appliance launch schedules or regulatory updates introduce timing pressure.
PW Consulting
For organizations seeking deeper segmentation data, competitive benchmarking, and tailored recommendations aligned with specific product portfolios or regional strategies, the full research report provides expanded detail across market size trajectories, segmentation dynamics, and actionable planning frameworks. The complete version includes granular breakdowns and customized guidance designed to support precise sourcing, product roadmap, and investment decisions.
For detailed analysis of this topic, please visit the official page: Appliance Power Cord Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Medical Rubber Stoppers Market: Why Butyl Dominance and 5.5% CAGR Reshape Strategy
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Medical Rubber Stoppers Market
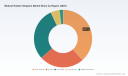
The medical rubber stoppers market stands at the intersection of pharmaceutical innovation and packaging reliability, serving as a critical component in the safe delivery of injectable drugs, biologics, and vaccines. Over the past five years, the market has progressed from a stable $900 million baseline in 2020 to an estimated $1.15 billion in 2025, reflecting consistent demand growth, expanded biopharmaceutical pipelines, and tightening quality expectations across global supply chains. Looking ahead through 2032, the market is projected to reach approximately $1.66 billion, extrapolating to a compound annual growth rate of 5.5 percent. This trajectory signals more than incremental expansion; it points to structural shifts in how elastomeric closures are specified, validated, manufactured, and integrated into drug packaging systems. For executives and investors navigating healthcare packaging, understanding what is driving this growth, where competitive advantages are being built, and how the regulatory and supply chain environment is evolving is essential for positioning portfolios and capital allocation effectively.
Market Snapshot and Structural Challenges
The medical rubber stoppers market today operates within a highly specialized segment of pharmaceutical packaging where performance, sterility, and compatibility are non-negotiable. Revenue growth over the historical period has been supported by rising volumes in injectable therapies, increased adoption of ready-to-use closure formats, and steady expansion in regions with growing centralized pharmacy operations and biotech manufacturing. The forecast period through 2032 suggests continued expansion, with growth rates that reflect both volume increases and higher value capture around premium, low-extractable, and pre-sterilized solutions. In a market of this kind, size alone does not explain competitive outcomes. The real story is in the concentration of capability, the pace of regulatory change, and the way demand-side requirements are reshaping product architectures.
Several structural challenges define the current inflection point for the industry. First, the cost environment for petroleum-derived feedstocks has introduced volatility into the production economics of butyl and bromobutyl rubber stoppers. During 2024, roughly 43 percent of manufacturers reported increased raw material costs driven by feedstock price swings, pressuring margins and complicating long-term pricing agreements. Second, regulatory expectations around extractables, leachables, compatibility, and sterilization are tightening at a pace that raises both technical and financial barriers. Updated guidance from the U.S. Food and Drug Administration in July 2024 on container closure systems underscored the need for manufacturers to document compatibility and perform container closure integrity testing, particularly for glass vials and stoppers. At the same time, the transition of USP Chapter 381 for elastomeric closures to new chapters 1381 and 1382, with a final implementation date of December 1, 2025, imposes updated testing requirements for functionality, extractables, and leachables. These shifts are not marginal; they change how products are validated, how documentation is maintained, and how quickly new formats can be qualified for clinical and commercial use.
Third, the market is experiencing an uncompromising demand for biological safety and sterility assurance. Biological evaluation of medical rubber stoppers must comply with ISO 10993 standards, and more than 58 percent of pharmaceutical packaging manufacturers cited increased validation and sterilization compliance expenses in 2024. Compliance costs are now a meaningful part of product economics and a differentiator in supplier selection. Taken together, these challenges reshape the playing field: suppliers that can deliver lower-extractable profiles, validated ready-to-use formats, and predictable cost structures gain disproportionate traction, while those relying on legacy designs and ad hoc compliance approaches face growing risk of displacement.
Key Drivers Propelling Market Change
The market’s trajectory is not simply a function of volume growth. It is being reshaped by overlapping forces that alter product requirements, customer expectations, and the economics of production. Three to four core drivers explain why the sector is evolving now and why the next several years will reward companies that align technology, regulatory readiness, and supply chain resilience.
Technology Innovation and Low-Extractable, Ready-to-Use Formats
Technological progress in elastomeric closure design is one of the most visible drivers. The shift toward low-extractable, ready-to-use stoppers addresses a long-standing requirement in injectable and biologic drug packaging: minimizing interaction between the closure and the drug product over extended shelf life. Recent product introductions illustrate this direction. Datwyler introduced Omniflex ready-to-use low-extractable stoppers targeted at long-shelf-life mRNA and monoclonal antibody applications. West Pharmaceutical Services expanded its NovaPure line with enhanced barrier properties for mRNA and biologic therapies. These developments are not incremental marketing moves; they respond to real formulation and stability needs in advanced therapies where closure integrity, extractables control, and sterilization readiness directly affect product viability. The commercial message is clear: premium, performance-led stopper designs are becoming the default choice for high-value biologics and mRNA platforms, and suppliers that can validate such formats at scale are moving up the value chain.
Policy, Regulatory Evolution, and Validation Intensity
Regulatory dynamics are accelerating the market’s shift toward standardized, well-documented, and rigorously tested closure solutions. The FDA’s July 2024 guidance on container closure system and component changes emphasizes compatibility documentation and container closure integrity testing for glass vials and stoppers. Simultaneously, the reorganization of USP elastomeric closure chapters, with final implementation by December 1, 2025, re-sets testing expectations for functionality, extractables, and leachables. For manufacturers and buyers alike, this environment increases the importance of pre-validated formats, traceable material specifications, and robust testing data. The burden is not only technical; it is operational. Suppliers must manage validation timelines, maintain documentation across product changes, and ensure that closures meet changing expectations without disrupting client onboarding. In practice, this favors suppliers with mature quality systems, broad test capabilities, and established relationships with pharmaceutical and biotech customers who value continuity and reduced qualification risk.
Butyl Rubber Market
Demand-Side Shifts in Biologics, Hospital Pharmacy, and Chronic Care
Demand is being shaped by the changing mix of drug therapies and the settings in which they are administered. The continued expansion of biologics, monoclonal antibodies, and mRNA-based products increases the need for closures that maintain stability and integrity over longer storage periods and in diverse climate conditions. At the same time, hospital pharmacy settings remain a significant demand center for sterile rubber stoppers used in injectable drugs and vaccines. Sterile stoppers used in these settings benefit from included reimbursement under existing DRG codes for parenteral therapies, with hospitals accounting for a substantial share of end-user demand. This reimbursement linkage matters because it stabilizes demand for sterile, high-compliance closures and creates a persistent pull for validated, hospital-ready products. The broader implication is that demand growth is not uniform across all closure types; it is concentrated where therapy complexity, sterility requirements, and reimbursement dynamics converge.
Supply Chain Cost Structures and Raw Material Dynamics
Beyond product and regulatory drivers, the supply chain environment is influencing competitiveness. Feedstock volatility for butyl and bromobutyl rubber has become a defining cost theme, affecting pricing stability and forcing manufacturers to manage input risk more actively. The impact is twofold. First, cost variability can compress margins unless suppliers have hedging strategies, flexible sourcing, or product mixes that balance higher-margin premium lines with volume-oriented formats. Second, cost pressures can accelerate regional sourcing decisions as buyers seek predictability, shorter lead times, and closer technical collaboration. Suppliers with scale, diversified feedstock strategies, and transparent cost management are better positioned to maintain commercial stability. In this respect, the market is rewarding operational discipline as much as product technology.
Competitive Landscape and Leading Strategies
The competitive field combines global elastomeric specialists, established pharmaceutical packaging groups, and high-capacity regional manufacturers. This mix creates a market where differentiation comes from product architecture, validation readiness, scale, and customer intimacy rather than commodity pricing alone. The market is also concentrated: the top three firms account for approximately 65 percent of revenue, and the top five reach around 72 percent. Such concentration indicates that scale, technology leadership, and long-term customer relationships are decisive in capturing premium segments.
Divergent Strategic Positions Among Leading Players
Leading companies are pursuing distinct strategic positions that reflect their capabilities and target segments. West Pharmaceutical Services focuses on premium elastomeric closures, including NovaPure and LyoTec ready-to-sterilize stoppers for injectable and lyophilized drug vials, and has expanded its NovaPure line with enhanced barrier properties for mRNA and biologic therapies. This positions West around reliability, advanced barrier performance, and compatibility with high-value drug programs. Datwyler Holding AG emphasizes high-quality butyl rubber stoppers and ready-to-use formats such as Omniflex for pharmaceutical and biotech packaging, recently introducing low-extractable stoppers for long-shelf-life mRNA and monoclonal antibody applications. Datwyler’s posture reflects a strategy centered on readiness, extractables control, and bioprocessing alignment.
In the capacity and scale segment, Hebei First Rubber Medical Technology manufactures medical-grade butyl and bromobutyl rubber stoppers with annual capacity of 10 billion units and supplies more than 40 countries with FDA and ISO certifications. Its participation in INTERPHEX USA in 2025 to promote bromobutyl rubber stoppers and related pharmaceutical packaging illustrates a strategy of combining scale, certification breadth, and active engagement with global buyers. Jiangsu Best New Medical Materials produces medical-grade grey rubber stoppers and plugs for pharmaceutical vials and infusion applications, adding further capacity and product variety in the regional supply base. On the diversified packaging side, AptarGroup offers elastomeric closures and related stoppers for drug delivery and pharmaceutical packaging, while Saint-Gobain Performance Plastics supplies medical and pharmaceutical elastomeric components including stoppers for healthcare applications. These firms extend the competitive field by leveraging broader packaging platforms and cross-segment capabilities. Japanese participants such as Sumitomo Rubber Industries and Nipro Corporation add a regional dimension: Sumitomo invested in a new R&D production line for advanced pharmaceutical rubber stoppers, signaling a commitment to technology and capacity for Asian and global biotech packaging needs, while Nipro offers rubber stoppers and related closures for injectable drug packaging and medical devices.
Market Evolution: Consolidation, Differentiation, and New Entrants
The competitive landscape is evolving along three axes. Consolidation remains a plausible path as larger players seek to strengthen scale, broaden product portfolios, and reduce customer switching risk through integrated offerings. Differentiation is intensifying around low-extractable, ready-to-use formats, faster qualification cycles, and compliance documentation, where the winners are those that can reduce time-to-market for drug manufacturers. New entrants and regional capacity expansions continue to challenge incumbents on cost and supply flexibility, particularly where certifications, volume capacity, and international distribution networks are in place. The likely outcome is a layered market: premium, technology-led suppliers capture high-margin biologic and mRNA programs; scale-oriented manufacturers win on volume, cost, and multi-country supply; and diversified packaging groups leverage platform breadth to serve multi-component packaging needs. Companies that can operate across more than one layer, or that can anchor a strong position in a specific high-value layer, will be best positioned to sustain growth.
Forward-Looking Scenarios and Commercial Opportunities
The next three to five years will likely be defined by three interrelated trends that translate directly into commercial opportunities for suppliers, buyers, and investors who can act on them early.
Acrylic Rubber Market
The first trend is the acceleration of low-extractable, ready-to-use closures as a standard expectation rather than a premium option. As mRNA platforms, monoclonal antibodies, and other biologics continue to expand, drug manufacturers will increasingly require closures that minimize interaction, support longer shelf life, and integrate seamlessly into sterile workflows. The opportunity lies in building validated formats that reduce qualification friction, shorten onboarding timelines, and provide documented compatibility and integrity data. Suppliers that can demonstrate repeatable performance across multiple therapy classes will be better positioned to secure long-term supply agreements.
The second trend is the deepening influence of regulatory and standards-driven compliance on sourcing decisions. With FDA guidance reinforcing container closure integrity documentation and USP chapters re-establishing testing expectations for elastomeric closures, buyers will place greater weight on suppliers’ validation records, test capabilities, and change control maturity. This creates a commercial opening for suppliers that can package compliance as a value proposition: faster qualification, comprehensive documentation, and lower risk of disruption during component changes. At the same time, the trend introduces risk for suppliers that rely on loosely documented processes or that underestimate the cost and time required to maintain alignment with evolving requirements.
The third trend is a more deliberate approach to cost and supply resilience, shaped by feedstock volatility and the need for predictable economics. Manufacturers and buyers will likely favor sourcing strategies that reduce exposure to raw material swings, balance multi-region supply where appropriate, and align product mix with margin realities. For suppliers, the opportunity is to combine cost discipline with technology value, offering transparent pricing mechanisms, flexible capacity, and a portfolio that spans both volume-oriented and premium formats. For investors, the signal is that competitive advantage will accrue to operators that can manage input volatility without sacrificing compliance or quality, especially in an environment where downstream demand remains robust.
These trends carry uncertainty. Regulatory timelines and interpretation can shift, particularly as chapters are implemented and guidance is applied in practice. Feedstock prices may move in ways that challenge margin assumptions. Demand for specific therapy platforms can change with clinical outcomes and reimbursement evolution. The commercial response should therefore be to build flexibility into product planning, maintain strong compliance capabilities, and avoid over-indexing on any single therapy or region. Opportunities will favor those who can adapt quickly while keeping quality and documentation intact.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product development with the direction of therapy and compliance evolution. Invest in low-extractable, ready-to-use formats that can be validated for biologics and mRNA applications, and ensure that documentation, testing, and change control systems are robust enough to meet FDA and USP expectations without protracted qualification cycles. Build feedstock risk management into commercial planning through diversification, hedging where feasible, and product mix strategies that protect margins. Where scale matters, use capacity and certification breadth to serve multi-country demand, but do so without compromising the performance profile that premium segments require. Balance volume and value by clearly segmenting the portfolio and assigning the right resources to each layer.
For investors, the market offers exposure to a sector with steady growth, clear differentiation potential, and rising barriers to entry around compliance and validation. The most promising targets are companies with demonstrated capability in low-extractable and ready-to-use formats, strong quality and documentation systems, and a credible strategy for managing raw material volatility. Evaluate customer concentration, certification breadth, and the ability to support faster qualification as part of any investment thesis. Watch for consolidation signals, regional capacity expansion with international certifications, and R&D investments that expand the performance envelope of closures. In this market, the durability of competitive advantage is closely tied to compliance readiness and the ability to reduce risk for drug manufacturers.
PW Consulting
For procurement and sourcing teams, the emphasis should be on qualification efficiency, supply resilience, and total cost of ownership rather than unit price alone. Prioritize suppliers that can provide validated, low-extractable, ready-to-use options with clear compatibility and integrity documentation, especially for injectable and biologic programs. Assess the supplier’s ability to manage feedstock-driven cost changes transparently and to sustain supply continuity across regions and demand cycles. Where hospital pharmacy demand and reimbursement linkages matter, ensure that the selected closures meet the sterility and compliance expectations that support parenteral therapy delivery. A balanced sourcing strategy that includes both premium-performance suppliers and capable scale providers can reduce risk while preserving flexibility.
The strategic picture is clear: the medical rubber stoppers market is moving toward higher performance expectations, more rigorous compliance, and greater emphasis on supply predictability. Navigating this environment requires detailed, segment-level data on product types, applications, regional demand patterns, pricing dynamics, and supplier capabilities. For decision makers seeking to translate these trends into sourcing choices, portfolio plans, or investment theses, a comprehensive report with granular segmentation and customized scenarios can sharpen the direction and reduce uncertainty. Access to that level of detail is the difference between reacting to change and shaping it.
For detailed analysis of this topic, please visit the official page: Medical Rubber Stoppers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Panoramic Sunroof Market 2026: 7.8% CAGR Trajectory and Regional Shifts
By pmarketresearch, 2026-09-21
Panoramic Sunroof Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Overview: A Sector in Structural Expansion
The panoramic sunroof market has transitioned from a premium comfort upgrade to a core architectural feature in modern vehicle design. From 2020 to 2025, the market expanded steadily, growing from approximately 2.0 billion USD to 2.75 billion USD in 2025. The trajectory is projected to accelerate through the forecast horizon, with the market expected to reach 4.75 billion USD by 2032. This expansion reflects a compound annual growth rate of 7.8 percent, driven by a combination of vehicle platform redesigns, electrification trends, and evolving consumer expectations around cabin experience.
Automotive Sunroof Market
The growth is not uniform across all categories. Multi-panel configurations currently command the largest share of revenue, indicating a sustained preference for flexible light and ventilation solutions over single fixed panels. Application-wise, sedans and hatchbacks continue to represent the dominant volume, though SUV integration remains a significant and growing contributor. Geographically, the Asia Pacific region accounts for the largest revenue pool, followed by Europe and North America, with Latin America and the Mideast and Africa regions representing smaller but increasingly relevant demand centers.
Structural Challenges and Inflection Points
The sector is navigating several simultaneous pressures that are reshaping investment priorities and product roadmaps.
One of the most pressing challenges is the tension between aesthetic and experiential demands and physical constraints. Panoramic roof systems are expected to deliver larger glazed areas, lighter weight, improved thermal insulation, and higher structural integrity, all while meeting increasingly stringent safety requirements. Engineers are being asked to deliver more glass without adding mass, and to integrate switchable glazing, ambient lighting, and electronic actuators without compromising sealing performance or crash behavior. This pushes manufacturers toward material innovation and tighter system integration rather than incremental design changes.
A second inflection point comes from regulatory and certification complexity. Panoramic roofs must satisfy safety glazing standards and new requirements related to pedestrian protection in roof zones. At the same time, electronic actuator and control systems must align with functional safety expectations for automotive applications. These requirements raise the bar for validation, change the cost structure of product development, and make compliance capability a meaningful competitive differentiator.
A third challenge lies in the changing vehicle mix and the specific demands of electric platforms. Electrification affects roof architecture in multiple ways. Battery packaging, body stiffness targets, and drag coefficient management all influence how panoramic systems are specified and integrated. Consumer preference is moving toward openable panoramic configurations in EVs and SUVs, motivated by perceived improvements in interior space and air circulation. That shift creates opportunities, but also forces suppliers to adapt to different assembly sequences, thermal requirements, and volume patterns compared with traditional internal combustion platforms.
Core Growth Drivers
Technological Innovation and Material Evolution
The market is being shaped by a steady push toward lighter, smarter, and more integrated roof systems. Glass specification is a major focus area. Recent technical guidance in the sector notes that PVB interlayer films used in panoramic roof glass are moving toward reduced layers and gradient applications. This approach aims to lower weight and simplify installation in fixed panoramic modules, while preserving optical quality and structural performance. The same trajectory supports broader industry efforts to reduce component mass without sacrificing safety or durability.
Beyond glazing, actuator technology and electronic integration are becoming central to product differentiation. Openable panoramic systems increasingly combine smooth operation, low noise, and higher reliability with embedded controls that support diagnostic and safety functions. Suppliers that can package these features into compact, robust modules are better positioned to win on next-generation platforms where roof assembly space is tightly constrained.
Policy, Regulation, and Certification Dynamics
Regulatory frameworks are not merely compliance hurdles; they are actively influencing product architecture and supplier selection. Vehicle roofs are subject to safety glazing requirements and newer pedestrian protection considerations that affect how panoramic systems are designed and tested. For electronic components, functional safety expectations are now a baseline requirement for actuators and control modules. These standards raise the cost of entry for casual participants and reward suppliers with established validation infrastructure and documented engineering processes.
At the same time, broader vehicle regulation and testing protocols are indirectly increasing the strategic value of panoramic roofs. Emission-related standards and testing cycles place greater emphasis on aerodynamic efficiency and perceived vehicle drag reduction. In that context, a well-integrated roof system can contribute to packaging efficiency and overall design coherence, even if its direct emissions impact is indirect. The result is a market where regulatory alignment and engineering maturity reinforce each other.
Demand-Side Shifts in Passenger Vehicle Expectations
Buyers and OEMs are increasingly treating the roof as part of the lifestyle and cabin experience rather than a purely structural element. The preference for openable panoramic sunroofs in EVs and SUVs underscores a desire for improved headspace and fresh air circulation, along with the visual and experiential benefits of larger glazed areas. For manufacturers, these features can support vehicle positioning, especially in segments where cabin ambiance and perceived premium quality influence purchase decisions.
This demand shift is also pushing attention toward ambient lighting, switchable glazing, and other features that blur the line between roof and interior environment. As these elements become more common, the roof assembly becomes a more complex subsystem, and suppliers with broader integration capabilities gain leverage in the value chain.
Supply Chain and Cost Structure Pressures
Cost and weight targets remain persistent drivers of engineering decisions. Lightweighting goals are especially important as manufacturers balance safety, packaging, and efficiency requirements. At the same time, the integration of advanced glazing, electronics, and sealing technology changes the cost profile of panoramic systems. Suppliers are responding by designing modules that consolidate functions, reduce assembly complexity, and support more efficient installation on production lines.
Supply chain resilience is also increasingly relevant. Roof systems require coordinated inputs from glass manufacturers, polymer and interlayer suppliers, actuator producers, and module integrators. Any disruption in specialized materials or component availability can affect program timing and cost. Companies that can manage multi-tier sourcing, standardize designs across platforms, and maintain disciplined quality controls are better placed to withstand volatility and protect margins.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with the top three players capturing a significant share and the top five firms accounting for a majority of revenue. This structure suggests that scale, platform relationships, and engineering breadth matter, but it also leaves room for specialists who can win on specific attributes such as lightweight construction, glazing quality, or system integration.
Webasto SE remains a prominent reference point in openable panoramic roof systems, with a positioning that emphasizes market-leading glass, ambient lighting, and switchable glazing for passenger cars and SUVs. Its recent Infinity Roof panoramic roof system launch for Mahindra Electric Origin SUVs illustrates how suppliers are aligning product portfolios with electrification and premium cabin features. The launch highlights the growing relevance of lighting-integrated and experience-led roof designs in electrified SUVs.
Inalfa Roof Systems competes as a specialist in panoramic and openable modules, with an emphasis on lightweight designs and system integration. Its value proposition fits naturally into platforms where weight reduction and assembly efficiency are priorities. Magna International brings a broader module and sealing technology perspective, offering customizable panoramic sunroof modules and roof system solutions that can be tailored across multiple vehicle architectures.
CIE Automotive contributes through lightweight and composite panoramic sunroof components and full roof systems, reinforcing the importance of material choice in cost-and-weight-sensitive programs. Aisin Seiki and Yachiyo Industry represent established manufacturing depth in premium panoramic systems and sunroof mechanisms, with Aisin focused on OEM-facing integrated roof components and Yachiyo on specialized sunroof and related system production. Inteva Products and Johnan America, Inc. add further breadth in engineered roof systems and sunroof mechanisms, including subsidiary-linked Japanese manufacturing capability. Saint-Gobain Sekurit and Bosch GmbH extend the competitive picture into critical subcomponents, with Saint-Gobain Sekurit focused on advanced glazing systems for panoramic glass panels and Bosch producing panoramic sunroof actuators and full roof module systems.
Risks, Uncertainties, and Strategic Implications
The outlook remains favorable, but several uncertainties could alter the pace or shape of growth. Regulatory requirements will continue to evolve, and changes in safety glazing, pedestrian protection, or functional safety expectations could increase development costs or force redesigns on active programs. Macroeconomic conditions affecting vehicle production volumes, especially in price-sensitive segments, can influence component demand and pricing power. Material availability and the cost of specialized glass, interlayers, and electronic subsystems may create margin variability, particularly for suppliers with less diversified sourcing or limited scale.
There is also the risk that consumer preferences shift toward fixed panoramic designs in some applications if cost, durability, or reliability concerns outweigh the appeal of openable systems. In parallel, platform consolidation and OEM sourcing strategies could concentrate volume among a smaller set of suppliers, making it harder for smaller or less established players to maintain program wins. The strategic implication is clear: competitive advantage will increasingly depend on engineering versatility, compliance readiness, and the ability to deliver lighter, smarter systems that fit tightly constrained vehicle architectures.
Strategic Takeaways for Decision-Makers
For Manufacturers and Suppliers
Prioritize integration and weight reduction as core product development themes. Designs that consolidate sealing, actuation, and glazing functions while reducing mass are likely to align well with OEM priorities on efficiency and assembly practicality. Build explicit capability around regulatory and functional safety requirements, since these are becoming gate checks for program qualification rather than optional add-ons. Expand platform leverage where possible by standardizing core modules across multiple vehicle programs, which can improve cost position and reduce launch risk.
In parallel, monitor electric vehicle and SUV platforms closely. These segments are shaping demand for openable panoramic systems and experience-led features such as ambient lighting and switchable glazing. Suppliers that can demonstrate reliable integration in electrified architectures will be better positioned to capture the next wave of volume.
For Investors and Strategic Planners
Assess exposure to the full value chain, not just final assembly. Glazing, interlayer materials, actuators, and sealing technologies each carry different growth profiles and risk characteristics. Companies with diversified capabilities across multiple subcomponents may offer more resilient positioning than pure single-function players. Pay attention to the balance between consolidation and specialization: while the market is moderately concentrated, niche differentiation in lightweight materials or advanced glazing can still create competitive advantage.
Track program timing, platform cycles, and OEM sourcing shifts as leading indicators. Volume growth will be uneven across regions and vehicle types, and the mix between fixed and openable configurations will influence which supplier profiles benefit most.
For Procurement and OEM Strategy Teams
Treat panoramic roof sourcing as a system integration decision rather than a commodity purchase. Evaluate suppliers on total system performance, including sealing reliability, weight, electronic safety alignment, and support for future feature integration such as switchable glazing or ambient lighting. Where possible, clarify long-term platform requirements early to enable suppliers to optimize designs for cost, weight, and assembly efficiency.
Roof Windows Market
Balance cost objectives with resilience. Resilient multi-tier sourcing and clear quality expectations can reduce the risk of launch delays or compliance issues, particularly when specialized materials and electronic components are involved. A disciplined sourcing strategy can also create room to negotiate better total cost positions without sacrificing performance.
Looking Ahead
The panoramic sunroof market is entering a phase where growth is increasingly tied to engineering depth, regulatory readiness, and alignment with electrification and SUV trends. The sector is expanding toward the 4.75 billion USD range by 2032, but the value will be captured by companies that can deliver lighter, smarter, and more integrated roof systems while meeting rising safety and functional safety expectations. The combination of material innovation, experience-led features, and tighter integration points toward a market that rewards capability rather than scale alone.
For organizations operating in or around this space, the most valuable next step is to map the specific platform, regulatory, and sourcing implications that will shape individual programs and regional demand. Detailed segmentation, regional nuance, and company-level scenario analysis can sharpen execution plans and reveal where the most durable opportunities are forming. The full research report provides that deeper breakdown, including detailed segmentation data, regional dynamics, and tailored recommendations for procurement, product development, and investment planning.
PW Consulting Automotive & Machinery Research Center
For detailed analysis of this topic, please visit the official page: Panoramic Sunroof Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Silicone-Based Fouling Release Coatings Market: Why 6.8% CAGR Reshapes Strategy
By pmarketresearch, 2026-09-21
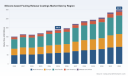
Strategic Trends and Commercial Opportunities in the Silicone-based Fouling Release Coatings Market
Market Landscape and Core Challenges
The global market for silicone-based fouling release coatings has entered a phase of steady expansion, driven by the maritime industry's evolving needs and regulatory pressures. From 2020 to 2025, the market demonstrated resilience despite fluctuations, growing from approximately 151.2 million USD to 190.5 million USD. This trajectory reflects a compound annual growth rate (CAGR) of 6.8% projected from 2026 through 2032, indicating sustained demand momentum. By 2032, the market is expected to surpass 297.5 million USD, signaling a maturing but still growing sector.
This growth is not uniform across all segments. The market exhibits moderate concentration, with the top three players holding 35.7% of the share and the top five capturing 48.2%. This structure suggests a competitive environment where established giants coexist with specialized players, creating room for strategic differentiation rather than pure price competition.
Despite the positive outlook, the industry faces critical challenges that could shape its future direction:
- Raw Material Volatility: The reliance on silicone raw materials makes the market susceptible to price swings driven by energy costs, logistics disruptions, and geopolitical tensions. Recent price revisions by major suppliers highlight the vulnerability of cost structures in this segment.
- Regulatory Compliance Complexity: Stricter environmental regulations, such as EU REACH and IMO conventions, mandate biocide-free formulations and organotin-free catalysts. While these regulations push innovation, they also increase formulation costs and require significant R&D investment to maintain performance standards without biocides.
- Performance vs. Cost Trade-offs: End-users, particularly ship operators, balance the long-term fuel savings from reduced fouling against the higher upfront costs of silicone-based coatings compared to traditional antifouling solutions. Demonstrating total cost of ownership benefits remains a key hurdle in broader adoption across all vessel types.
Key Drivers of Market Dynamics
Technological Innovation and Formulation Breakthroughs
Innovation in silicone chemistry is central to the market's evolution. Leading companies are developing advanced silicone elastomer systems that offer superior fouling release properties while adhering to biocide-free requirements. For instance, AkzoNobel's Intersleek series, including the 1100SR variant, exemplifies the focus on high-performance silicone systems that minimize drag and fuel consumption. Similarly, Hempel's Silic One and hydrogel-enhanced Hempasil systems represent efforts to combine silicone efficacy with enhanced surface properties for biocide-free hull protection.
These technological strides are not merely about replacing biocides; they are about improving durability and self-renewing capabilities. Jotun's SeaQuantum silicone elastomer coatings, designed for self-renewing hull performance, illustrate how formulators are tackling the challenge of coating longevity and consistent performance over multiple service intervals. Such innovations reduce the frequency of repainting, addressing a key concern for shipowners regarding maintenance downtime and lifecycle costs.
Regulatory Pressure as a Catalyst
Regulatory frameworks are acting as a powerful accelerator for silicone-based fouling release coatings. The International Convention on the Control of Harmful Antifouling Systems on Ships (IMO) mandates the use of biocide-free silicone fouling release coatings in sensitive ecological zones. With over 3,500 vessels restricted in 2024 under these provisions, the addressable market for compliant coatings is expanding. Furthermore, EU REACH regulations require organotin-free catalysts, pushing manufacturers to refine curing systems without compromising performance.
These regulations create a clear pull for silicone-based solutions, as traditional biocidal antifouling coatings face increasing restrictions. The shift is particularly pronounced in regions with stringent environmental enforcement, where compliance becomes a non-negotiable requirement for vessel operations. This regulatory tailwind is transforming silicone coatings from a niche premium option to a mainstream necessity in specific maritime segments.
Demand-Side Shifts Toward Sustainability and Efficiency
Ship operators and maritime companies are increasingly prioritizing fuel efficiency and carbon footprint reduction. Fouling release coatings directly contribute to these goals by reducing hydrodynamic drag, which lowers fuel consumption and emissions. As energy costs fluctuate and environmental, social, and governance (ESG) criteria gain weight in corporate decision-making, the economic and reputational benefits of silicone-based coatings become more compelling.
The demand is also being shaped by the expansion of sensitive ecological zones and port state control measures. Vessels operating in these areas must utilize compliant coatings, driving adoption among fleets that previously might have relied on conventional solutions. This demand-side pressure is reinforcing the market growth trajectory and encouraging investment in next-generation silicone formulations.
Supply Chain and Cost Structure Pressures
The cost structure of silicone-based fouling release coatings is undergoing significant stress due to upstream factors. Major silicone raw material producers have announced price increases, reflecting the impact of energy costs, logistics expenses, and raw material availability. Wacker Chemie AG, for example, implemented a price increase for all silicone-based products effective April 2026, citing disruptions in global supply chains related to energy, raw materials, and logistics. Similarly, Shin-Etsu Chemical Co., Ltd. revised selling prices for all silicone products by 10% or more starting May 2026, driven by sharply rising derived raw materials, energy, and logistics expenses.
These price revisions ripple through the value chain, affecting coating manufacturers' input costs and potentially impacting end-user pricing. The industry is navigating a period where cost escalation must be managed without eroding the value proposition of silicone coatings. This dynamic is prompting companies to optimize formulations, secure long-term supply agreements, and explore alternative sourcing strategies to mitigate volatility.
Competitive Landscape and Leading Strategies
The market is characterized by a mix of global coatings giants and specialized marine paint manufacturers, each pursuing distinct strategic positioning. AkzoNobel N.V., headquartered in Amsterdam, leverages its extensive marine coatings portfolio to offer Intersleek silicone elastomer foul release systems. Its strategy centers on integrating silicone technology into broader hull protection solutions, emphasizing performance data and fleet-wide efficiency gains. By tying silicone coatings to tie coats and complete systems, AkzoNobel aims to lock in customers through comprehensive service offerings.
PW Consulting
Hempel A/S, based in Copenhagen, differentiates through innovation in biocide-free systems. Its Silic One silicone-based foul release coating and Hempasil hydrogel-enhanced silicone systems target customers seeking advanced protection without biocides. Hempel's focus on hydrogel technology adds a layer of differentiation, potentially offering enhanced fouling release properties and durability, appealing to operators in ecologically sensitive regions.
PPG Industries, Inc., from Pittsburgh, provides SigmaWild and other silicone fouling release coatings as part of its biocide-free marine solutions. PPG's strength lies in its global reach and ability to scale innovation across diverse maritime markets. The company's strategy involves positioning silicone coatings within a wider suite of marine protection products, leveraging brand recognition and technical service networks to capture market share.
Jotun A/S, located in Asker, Norway, emphasizes self-renewing hull performance with its SeaQuantum silicone elastomer foul release coatings. Jotun's approach highlights the operational benefits of reduced maintenance frequency and consistent performance, resonating with shipowners focused on minimizing dry-docking intervals and maximizing vessel uptime.
Chugoku Marine Paints, Ltd., based in Osaka, markets the CMP BIOCLEAN series of advanced silicone foul release coatings for ocean-going vessels. As a regional player with strong ties to Asian maritime markets, Chugoku focuses on tailoring solutions to the specific operational profiles of vessels in the Pacific region, potentially offering competitive pricing and localized service support.
Sherwin-Williams Company, headquartered in Cleveland, supplies silicone-based foul release coatings under its marine and specialty coatings portfolio. Its strategy involves leveraging its vast distribution network and cross-selling opportunities across industrial and marine segments. Sherwin-Williams aims to integrate silicone coatings into broader coating solutions, appealing to customers seeking a single-source provider for multiple coating needs.
Pettit Marine Paint, located in Rockaway, New Jersey, provides silicone foul release coatings and systems for recreational and commercial marine applications. Pettit's niche focus allows it to cater to smaller vessel operators and recreational boaters, segments where ease of application and specialized customer service can be decisive factors.
The competitive landscape is evolving through consolidation and differentiation. While the top five players hold nearly half the market, the presence of specialized firms indicates opportunities for fragmentation in niche applications or regional markets. New entrants may find traction by focusing on specific vessel types, emerging regions, or novel formulation technologies that address unmet needs. However, the high barriers to entry posed by regulatory compliance, performance validation, and established supply chains favor incumbents with robust R&D and customer relationships.
Future Trends and Strategic Outlook
Accelerating Adoption Driven by Regulatory Expansion
Over the next three to five years, regulatory pressures are expected to intensify, further expanding the addressable market for biocide-free silicone fouling release coatings. As more regions implement stringent environmental protections and IMO regulations evolve, the number of vessels required to use compliant coatings will grow. This trend creates a clear opportunity for manufacturers to scale production and secure market share in advance of demand surges. However, companies must also anticipate potential regulatory fragmentation, where differing regional standards could complicate formulation strategies and market access.
Supply Chain Resilience and Cost Management as Competitive Differentiators
The recent wave of price increases from silicone raw material suppliers underscores the importance of supply chain resilience. Future market leaders will likely be those who can secure stable raw material supplies, optimize formulations to reduce silicone content without sacrificing performance, or develop partnerships that mitigate cost volatility. This trend may lead to strategic alliances between coating manufacturers and silicone producers, or inspire investment in alternative raw material sources. Businesses that fail to address cost structures risk margin erosion or loss of competitiveness in price-sensitive segments.
Silicone Resin Market
Performance Enhancements and Lifecycle Value Propositions
Innovation will continue to focus on enhancing the performance and lifecycle value of silicone coatings. Expect developments in multi-layer systems, improved adhesion promoters, and coatings that offer longer service life or easier application processes. The commercial opportunity lies in demonstrating total cost of ownership benefits that justify higher initial costs. Manufacturers that can provide robust data on fuel savings, reduced maintenance, and extended coating life will be better positioned to capture value. Conversely, a risk exists if performance claims are not consistently validated across diverse operating conditions, potentially leading to customer skepticism or reversion to traditional solutions where regulations permit.
Marine Anti-Fouling Coatings Market
Actionable Insights for Decision Makers
For Coating Manufacturers and Formulators
- Invest in Bio-based or Cost-Optimized Formulations: With raw material costs rising, exploring formulations that maintain performance while reducing dependency on high-cost silicone components can protect margins. R&D efforts should prioritize organotin-free curing systems and biocide-free architectures that comply with evolving regulations without compromising efficacy.
- Strengthen Supply Chain Partnerships: Engaging in long-term agreements with silicone suppliers or diversifying the supplier base can mitigate price volatility. Collaborative innovation with raw material producers may yield tailored solutions that address specific coating needs while stabilizing input costs.
- Expand Value-Added Services: Offering technical support, performance monitoring, and lifecycle cost analysis can differentiate offerings in a competitive market. Helping customers quantify fuel savings and maintenance reductions strengthens the value proposition and fosters loyalty.
For Investors and Financial Stakeholders
- Focus on Regulatory Tailwinds and Market Concentration: The market's moderate concentration and regulatory-driven growth present opportunities in companies with strong compliance capabilities and global reach. Evaluate players based on their R&D pipelines, regulatory responsiveness, and ability to scale silicone-based solutions across key maritime regions.
- Monitor Raw Material Dynamics Closely: Price revisions by major silicone producers can impact profitability across the value chain. Analyze how potential investments or portfolio companies manage input cost risks, as resilience in supply chain management will be a key determinant of long-term financial performance.
- Assess Niche and Regional Opportunities: While global giants dominate, specialized players serving recreational marine, specific vessel types, or emerging regions may offer high-growth potential. Look for companies with strong local relationships, tailored product lines, and the agility to adapt to regional regulatory changes.
For Shipowners and Procurement Teams
- Prioritize Total Cost of Ownership Assessments: When evaluating silicone-based fouling release coatings, look beyond initial price and consider fuel savings, reduced dry-docking frequency, and compliance benefits. Engage with manufacturers to obtain performance data relevant to your vessel types and operating profiles to make informed comparisons.
- Ensure Regulatory Compliance Proactively: Verify that selected coatings meet current and anticipated regulations in all operational zones, including sensitive ecological areas. Non-compliance can result in operational restrictions or penalties, making proactive selection of biocide-free and organotin-free solutions a strategic necessity.
- Leverage Supplier Expertise for Application Optimization: Proper application is critical to achieving the claimed performance of silicone coatings. Work closely with suppliers to ensure correct surface preparation, application conditions, and tie-coat usage. Investing in training or partnering with experienced applicators can maximize the return on coating investments.
The silicone-based fouling release coatings market is at a inflection point, shaped by regulatory mandates, technological advancements, and supply chain dynamics. Navigating this landscape requires a nuanced understanding of competitive strategies, cost structures, and emerging opportunities. Stakeholders seeking deeper granularity on segment-level data, regional breakdowns, and customized strategic scenarios are encouraged to explore comprehensive research resources that provide detailed market intelligence tailored to specific business needs.
For detailed analysis of this topic, please visit the official page: Silicone-based Fouling Release Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Acute Care Needleless Connector Market 1634M in 2026 Why Positive Displacement Shift Matters
By pmarketresearch, 2026-09-21
Acute Care Needleless Connector Market: Strategic Trends and Commercial Opportunities Through 2032
The acute care needleless connector market represents a critical intersection of patient safety, clinical efficiency, and supply chain economics. As vascular access practices continue to evolve alongside growing emphasis on healthcare-associated infection prevention, the connector segment has transitioned from a commoditized consumable to a strategically differentiated product category. Understanding where the market stands today, what forces are reshaping it, and how competitive players are positioning themselves provides essential context for executives navigating procurement, product development, or capital allocation decisions.
Acupuncture Needles Market
Market Landscape and Core Challenges
The global acute care needleless connector market has demonstrated steady expansion over the past half-decade, reaching an estimated 1.55 billion USD in 2025, with trajectory modeling pointing toward approximately 2.29 billion USD by 2032. The compound annual growth rate across the 2026 to 2032 horizon sits at 5.83 percent, reflecting a market that is growing at a pace consistent with broader medical device consumables while benefiting from compounding clinical and operational tailwinds. Growth is not merely volume-driven; it reflects a structural shift in how acute care facilities approach vascular access, infection prevention, and supply standardization.
Geographically, the market remains heavily anchored in North America, followed by Europe and Asia Pacific, with Latin America and the Middle East and Africa representing smaller but steadily developing demand pools. Application-wise, hospital settings dominate consumption, reflecting the concentration of high-acuity patients, multilumen catheter use, and institutional pressure to standardize vascular access protocols. Clinics and ambulatory settings form a secondary demand base, while other care environments contribute incremental volume. Revenue distribution across product types shows a market increasingly aligned around fluid displacement performance, with positive and negative displacement configurations commanding the largest shares and neutral displacement gaining traction as clinical evidence around reflux control and microbial ingress prevention accumulates.
Key Challenges and Inflection Points
Despite the favorable growth backdrop, several structural challenges and decision points define the current market environment.
- Standardization versus clinical differentiation tension. Acute care procurement teams increasingly seek product standardization across departments to simplify training, reduce inventory complexity, and consolidate volume for contracting leverage. At the same time, clinical evidence is driving interest in differentiated connector performance around reflux characteristics, microbial ingress prevention, and occlusion management. Manufacturers must navigate the balance between offering clinically meaningful variation and meeting hospital demands for simplified formularies.
- Infection prevention accountability and total cost of care. Clinician awareness of catheter-related bloodstream infection risks has matured, but translating that awareness into purchasing behavior depends on how clearly connector performance associates with downstream outcomes and operating costs. Decision-makers are under pressure to justify product selection not just on unit price, but on risk reduction, flush frequency, thrombolytic use, and labor implications. This shifts the commercial battleground from specifications alone to demonstrated clinical and economic value.
- Pricing pressure amid supply chain normalization. After the volatility experienced in earlier years, supply chains have largely stabilized, and hospitals have regained bargaining leverage in group purchasing arrangements. This has intensified price scrutiny, particularly for commoditized connector SKUs. Suppliers that cannot articulate differentiated clinical value face margin compression, while those with evidence-backed positioning can defend premium pricing or secure longer contract cycles.
These challenges converge on a central question for the market: whether needleless connectors will continue to consolidate around a few clinically differentiated platforms, or whether buyers will privilege cost and standardization to the detriment of performance variation. The answer will shape competitive dynamics across the next several years.
Key Drivers Shaping Market Evolution
Clinical Evidence and Differentiation Around CLABSI Risk Management
One of the most consequential drivers in the market is the growing weight of clinical evidence connecting connector design to catheter-related bloodstream infection outcomes and treatment efficiency. Needleless connector performance is no longer evaluated only on ease of use or compatibility. Procurement and infection prevention teams are increasingly attentive to reflux behavior, microbial ingress prevention, occlusion risk, and downstream implications such as flush and thrombolytic consumption.
Recent regulatory labeling updates and peer-reviewed data have begun to crystallize these claims in ways that matter for purchasing decisions. For instance, clearances associated with neutral-displacement connector platforms have incorporated CMS study data indicating a measurable relative risk reduction in CLABSI within high-volume acute care hospitals, alongside claims related to pressure infusion performance and extended microbial ingress prevention windows. In parallel, independent systematic in vitro assessments of neutral displacement connectors have documented bidirectional fluid flow control with low reflux volumes, reinforcing the technical rationale behind neutral displacement as a clinically relevant parameter. These developments are not abstract; they directly inform formulary discussions where infection prevention metrics and nursing workflow matter.
Regulatory and Labeling Evolution as a Commercial Lever
The regulatory environment has evolved from a compliance floor into a commercial differentiator. FDA 510(k) labeling clearances are increasingly used to substantiate performance claims that support hospital adoption and value-based purchasing conversations. When labeling incorporates outcomes-linked evidence or functional claims such as pressure infusion capability and extended microbial ingress prevention, it offers clinicians and procurement teams a clearer basis for standardizing specific connector types across services.
This regulatory dynamic favors companies with established clinical data packages and regulatory execution capabilities. It also raises the bar for new entrants, since meaningful labeling claims require robust data generation and clear regulatory alignment. For incumbents, proactive labeling strategy can extend product lifecycle relevance and strengthen negotiating position in group purchasing discussions.
Demand-Side Shifts in Hospital Purchasing and Care Delivery
On the demand side, acute care facilities are optimizing vascular access programs to reduce variability, improve nurse efficiency, and manage total cost of care. HAIs remain a persistent concern, and connector selection is increasingly viewed as one component of a broader vascular access bundle rather than an isolated consumable decision. This mindset supports longer contract cycles for products that demonstrate consistent performance and compatibility within closed-system environments.
At the same time, labor constraints continue to influence consumable selection. Products that reduce flush frequency, minimize occlusion interventions, or simplify access routines can translate into meaningful workflow improvements. Evidence associating connector platforms with reduced thrombolytic use has gained commercial relevance because it ties device performance to drug cost savings and nursing time. These demand-side dynamics are nudging hospitals toward products with demonstrable operational benefits, especially in high-throughput acute care environments.
Supply Chain Maturation and Cost Structure Realignment
Supply chain stabilization has changed how both manufacturers and buyers think about cost. Earlier disruption-era urgency has given way to more disciplined contracting, inventory planning, and total cost evaluation. For manufacturers, this environment rewards scale, consistent quality, and strong GPO relationships. For buyers, it enables more deliberate evaluation of value over time rather than short-term price alone.
Worldwide Acute Care Electronic Health Recorder (EHR) Market
Cost structure considerations also affect OEM and precision-molded connector supply. Manufacturers that can combine design control, molding precision, and regulatory readiness are well positioned to serve global acute care suppliers seeking reliable sourcing. At the same time, any renewed cost pressure from raw materials, sterilization, or logistics could compress margins on undifferentiated products, reinforcing the trend toward value-based competition.
Competitive Landscape and Leading Strategies
The market is moderately concentrated, with the largest players commanding a meaningful share of global revenue while operating across different strategic positions. The competitive field includes broad-line medical device manufacturers with established acute care franchises, specialized connector companies with focused product platforms, and OEM suppliers that serve the broader supply chain through precision molding and custom engineering.
Strategic Positioning of Leading Players
Several companies illustrate distinct approaches to capturing value in this segment.
- ICU Medical has leveraged a comprehensive needlefree connector portfolio around neutral-displacement technology, with a notable emphasis on infection-control positioning. Recent labeling activity has strengthened claims associated with CLABSI risk reduction and microbial ingress prevention, and the company has paired regulatory progress with group purchasing access through multi-year contracts. This combination of evidence, labeling support, and purchasing channel access illustrates a strategy centered on clinical differentiation and institutional adoption.
- Becton, Dickinson and Company maintains a strong acute care presence with needle-free connector offerings positioned around reduced CLABSI and occlusion risk. Clinical data associating certain connector platforms with lower thrombolytic use has added an economic dimension to product positioning, helping frame the discussion around total cost of care rather than device unit price. This approach aligns with BD's broader strength in hospital supply ecosystems.
- B. Braun Medical offers connector platforms optimized around neutral displacement and anti-reflux performance within hospital IV therapy workflows. Its positioning reflects integration into broader infusion and vascular access portfolios, which can be advantageous for customers seeking workflow compatibility and standardized consumables across multiple device categories.
- Vygon S.A. continues to serve acute care vascular access needs with neutral displacement connector options, emphasizing compatibility and clinical usability within hospital settings. The company's strategy reflects steady penetration through product reliability and regional distribution strength.
- Nexus Medical illustrates a more focused approach, with neutral displacement connectors engineered for minimal reflux volume and acute care applications. Independent testing documenting low reflux ranges supports its technical positioning and offers a basis for differentiation in clinically sensitive environments.
- RyMed Technologies has emphasized enhanced infection control through antimicrobial-impregnated connector designs, targeting institutions looking for additional layers of protection beyond mechanical displacement characteristics. This illustrates a complementary differentiation path that emphasizes material and surface-level interventions.
- Terumo Corporation and Smiths Medical both participate through needle-free connector offerings tied to broader infusion and catheter systems, reinforcing the value of portfolio integration and closed-system compatibility in hospital purchasing.
- Baxter International Inc. maintains connector offerings within acute care IV therapy, benefiting from established relationships and system-level compatibility. Its presence reflects the importance of broad acute care distribution and clinical familiarity.
- CHI FENG Co., Ltd. operates in a different part of the value chain, providing OEM/ODM precision-molded neutral needle-free connectors for global acute care suppliers. This role highlights the strategic importance of manufacturing precision, scalability, and design support in serving larger branded participants.
- PuraCath Medical has entered the conversation with new connector technology cleared for vascular access in critical care, using IT-based approaches to reduce CLABSIs in acute care settings. New entrants with distinct technical mechanisms can reshuffle attention within the segment if clinical data and adoption pathways align.
How the Landscape Is Evolving
The competitive environment is shifting along several axes. First, evidence-based differentiation is becoming more central, and labeling advances are turning clinical claims into commercial assets. Second, purchasing consolidation is increasing the importance of group purchasing access and multi-year contract readiness, especially for products that can demonstrate infection prevention and workflow value. Third, there is an ongoing tension between portfolio breadth and focused specialization. Broad-line players benefit from system compatibility and supply relationships, while focused players can compete on specific performance characteristics and clinical storytelling. Fourth, new entrants with novel mechanisms, such as IT-enabled connector designs, introduce potential disruption if they can generate compelling evidence and secure adoption in high-acuity settings.
Overall, the market is moving toward a split between clinically validated platforms competing on outcomes and operational value, and cost-optimized SKUs competing primarily on price and standardization. The former are likely to capture more durable share in acute care settings where infection prevention and workflow efficiency carry real financial and clinical weight.
PW Consulting
Future Outlook and Emerging Opportunities
Clinical Evidence Will Become a Licensing and Adoption Asset
Over the next three to five years, clinical evidence is expected to play an even greater role in connector selection. As hospitals refine vascular access protocols and infection prevention programs, products with robust data packages and regulatory-supported labeling claims will have an advantage in formulary discussions and GPO negotiations. This creates opportunity for companies that can sustain data generation, translate results into procurement-friendly narratives, and align clinical claims with total cost of care arguments. It also raises the importance of post-market evidence and real-world consistency, since hospital adoption increasingly depends on demonstrated performance over time.
Neutral Displacement and Reflux Control Will Remain Strategic Parameters
Neutral displacement design, reflux control, and microbial ingress prevention will continue to be central technical parameters in acute care applications. Independent testing, systematic reviews, and labeling developments are reinforcing the relevance of these characteristics. Companies that can clearly communicate reflux behavior, compatibility, and workflow implications will be better positioned to compete in high-acuity environments where occlusion management and infection risk matter. This also creates opportunities for product development investment aimed at reducing reflux volume, improving pressure infusion capability, and strengthening microbial barrier claims without sacrificing usability.
Consolidation in Procurement and the Rise of Value-Based Selection
Hospital procurement is likely to continue consolidating around fewer connector choices within individual institutions, driven by standardization, training efficiency, and purchasing leverage. Within that constraint, value-based selection will become more important, meaning products that can show reduced thrombolytic use, lower occlusion intervention frequency, and meaningful infection prevention association will have stronger staying power. For manufacturers, this implies that price competition alone will be insufficient in many acute care accounts; commercial success will depend on aligning device performance with hospital cost and quality priorities. For investors, it suggests that the most durable growth stories will emerge from platforms with both evidence and purchasing channel access.
Potential Risks and Uncertainties
Several uncertainties could alter the trajectory of the market. If clinical evidence remains fragmented or difficult to compare across products, buyers may default to price and standardization, compressing differentiation value. If reimbursement and cost pressures intensify, hospitals may prioritize short-term savings over performance-based selection, particularly in margin-constrained settings. Supply chain disruptions, raw material volatility, or regulatory changes affecting labeling claims could also affect product positioning and margin profiles. Finally, new technology entrants must prove not only technical merit but also adoption feasibility within hospital workflows and purchasing structures, which can slow the impact of otherwise promising innovations.
Strategic Implications for Decision-Makers
For Manufacturers
- Invest in evidence generation and labeling strategy as core commercial capabilities, not just regulatory exercises. Clinical claims that link connector performance to CLABSI risk, occlusion, and drug use can shape formulary discussions when supported by regulatory clearances and peer-reviewed data.
- Balance portfolio breadth with focused technical differentiation. If products are positioned around neutral displacement and reflux control, make those performance characteristics measurable, credible, and easy for clinical and procurement teams to understand.
- Strengthen group purchasing relationships and multi-year contract readiness. In a consolidating procurement environment, access to contracted volume can matter as much as product quality for sustained share growth.
For Investors
- Prioritize platforms with both clinical evidence and purchasing channel access. Revenue growth in this segment is increasingly tied to institutional adoption, and adoption depends on demonstrated value plus contract presence.
- Track labeling and clearance activity as leading indicators of competitive positioning. Regulatory-supported claims can shift purchasing attention and create differentiation that persists beyond feature comparisons.
- Monitor new entrants with distinct mechanisms, but assess adoption feasibility carefully. Technical novelty alone does not guarantee acute care uptake; workflow compatibility, evidence strength, and commercial execution determine whether innovation translates into share.
For Procurement and Hospital Leadership
- Evaluate connector selection as part of a broader vascular access and infection prevention strategy, not solely as a consumable price decision. Total cost implications, including thrombolytic use, flush frequency, and occlusion management, can materially affect operating economics.
- Seek standardized formularies where clinically appropriate, but preserve room for evidence-backed differentiation in high-acuity settings. Not all use cases demand the same connector performance profile, and segmentation can improve both safety and cost efficiency.
- Ask suppliers for clear, comparable performance data on reflux behavior, microbial ingress prevention, occlusion risk, and compatibility within existing systems. Consistency of evidence and post-market performance should weigh heavily in long-term contracting decisions.
The acute care needleless connector market is entering a phase in which clinical evidence, regulatory-supported labeling, and value-based procurement will increasingly determine competitive outcomes. Companies and buyers that treat connector selection as a strategic lever for infection prevention, workflow efficiency, and total cost management will be better positioned than those competing only on unit price or feature lists. For decision-makers seeking detailed segmentation data, regional dynamics, contract structures, and customized commercial implications, the full research report provides a deeper operational view of the market and the specific pathways most relevant to individual business contexts.
For detailed analysis of this topic, please visit the official page: Acute Care Needleless Connector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
UV LEDs Market at 11.9% CAGR: Why Asia Pacific and UV Curing Are Redefining Growth
By pmarketresearch, 2026-09-21
Strategic Shifts and Commercial Opportunities in the UV LEDs Market
The ultraviolet LED sector has moved from a specialized component niche to a critical enabler of industrial, environmental, and healthcare infrastructure. Between 2020 and 2025, the global UV LEDs market expanded from $700.0 million to $1,230.0 million, reflecting a compound annual growth rate of 11.9% that extends through the forecast horizon to 2032. By the close of the projection period, revenue trajectories point toward $2,694.0 million, signaling a market that has crossed the threshold from incremental adoption to structural expansion. This growth trajectory is not merely a reflection of incremental efficiency gains; it captures a broader transition in how industries approach disinfection, curing, and environmental control as regulatory, technological, and supply chain conditions reshape competitive dynamics.
The market’s expansion has been uneven, shaped by material bottlenecks, geopolitical trade controls, and the uneven pace of certification and standardization across end-use sectors. While the headline numbers indicate robust demand absorption, the underlying mechanics reveal a landscape where competitive advantage increasingly depends on manufacturing scale, substrate availability, and the ability to align product development with regulatory timelines. Understanding these mechanics is essential for executives evaluating capital allocation, supply chain strategy, and product roadmap decisions.
Market Landscape and the Structural Challenges Shaping Growth
The UV LEDs market’s progression from $700.0 million in 2020 to $1,230.0 million in 2025 underscores a sustained demand pull, but the growth path has not been frictionless. The compounding rate of 11.9% masks underlying volatility in input costs, substrate constraints, and the uneven deployment of certified systems across regions and applications. The market remains moderately concentrated, with the top three firms holding a 24.6% share and the top five reaching 52.0%, a structure that reflects both the technical barriers to entry and the persistent fragmentation across wavelength-specific applications.
UV Lasers Market
Substrate Constraints and Per-Unit Economics
A persistent bottleneck lies in large-diameter aluminum nitride substrates, which remain limited to 3 inches or smaller. This constraint directly affects UV-C LED production economics by increasing per-unit costs and limiting wafer-scale yield improvements. For manufacturers, the implication is clear: scaling volume alone does not automatically translate into margin expansion when substrate supply restricts throughput and forces reliance on smaller-batch processing. Companies that can secure consistent substrate access or develop alternative packaging and yield-management strategies are better positioned to maintain cost competitiveness as demand intensifies.
Geopoliticized Material Supply Chains
Raw material access has become a strategic variable rather than a background procurement issue. China’s gallium and germanium export controls, implemented in August 2023 and tightened through 2025, restrict gallium nitride materials essential for UV LED substrates and chips. Licensing requirements and end-user restrictions targeting the United States have created parallel pressure on Asian producers reliant on Chinese materials, while U.S. export controls on gallium-related items have increased supply chain risk across the manufacturing ecosystem. In practical terms, this translates into longer qualification cycles, inventory hedging, and a growing premium on supply chain diversification and regional sourcing strategies.
Labor Intensity and Process Complexity
The market’s growth trajectory is also shaped by rising manufacturing complexity. UV LED manufacturing labor costs have risen by 10-12% annually in 2025 as a result of skilled semiconductor process requirements. This increase is not simply an inflationary headwind; it reflects the technical demands of wavelength precision, packaging reliability, and performance validation. Organizations that treat labor as a variable cost rather than a capability constraint risk underinvesting in process engineering, automation, and workforce development, which can erode competitiveness even as demand expands.
Core Drivers Accelerating Market Expansion
The market’s growth is being propelled by several reinforcing forces that extend beyond simple demand substitution. These drivers interact with one another, creating both acceleration and new constraints depending on how companies position their capabilities.
PW Consulting
Technology Innovation and Performance Breakthroughs
Performance gains are reshaping adoption economics, particularly in disinfection and curing applications where efficiency and output directly influence total cost of ownership. Recent developments illustrate the pace of progress: in August 2025, ams-OSRAM AG doubled UV-C LED efficiency to 10.2% through enhanced semiconductor technology, a milestone that strengthens the case for UV-C deployment in air, water, and surface applications where energy consumption and thermal management have historically constrained scalability. Separately, Nichia Corporation expanded its portfolio in October 2025 with new UV-A LED series at 365nm and 385nm wavelengths featuring improved flux output for industrial UV curing, alongside new UV-B 308nm and UV-A 330nm LEDs. These product moves reflect a broader industry push to broaden wavelength coverage and improve output consistency, enabling customers to tailor solutions to more demanding curing and disinfection requirements.
The technology trajectory is also visible in system-level innovations. Kyocera Corporation’s May 2025 launch of the Air-cooled UV LED light source G7A Series with revolutionary curing performance highlights how thermal management and integration can change performance expectations in industrial settings. As LED efficiency and light-source design improve, the conversation shifts from feasibility to deployment scale, particularly in applications that previously relied on mercury-based alternatives.
Policy and Regulatory Momentum
Regulatory frameworks are increasingly shaping adoption pathways by establishing performance benchmarks and compliance expectations. Mercury phase-down pressures and broader environmental regulations continue to favor mercury-free alternatives, reinforcing interest in UV LEDs across disinfection, curing, and purification use cases. At the same time, certification requirements add both credibility and cost. NSF/ANSI Standard 55 certification, for example, requires UV LED systems to meet specific testing for residential water treatment, adding compliance validation time and costs. For suppliers, this means that time-to-market is not only a function of product readiness but also of testing, documentation, and certification strategy. For buyers, certified products reduce deployment risk but require a longer evaluation cycle and more disciplined vendor qualification.
Demand-Side Shifts in Disinfection, Curing, and Environmental Control
Demand is being driven by a combination of hygiene expectations, industrial productivity requirements, and sustainability scrutiny. Disinfection and sterilization applications have gained institutional traction in settings where water, air, and surface treatment are prioritized, while UV curing continues to benefit from the broader industrial push toward faster processing and reduced chemical exposure. Medical and scientific uses add a more specialized but high-value demand layer, particularly where wavelength precision and reliability are essential. Security-related applications occupy a smaller share of the market but remain relevant where specialized detection and verification functions depend on UV illumination.
What distinguishes the current demand environment is the move from pilot deployment to broader integration. As performance improves and compliance pathways become clearer, more organizations are evaluating UV LEDs not as experimental alternatives but as core components of operational strategy. This shift increases volume potential while also raising expectations for consistency, durability, and integration support.
Synthetic Quartz Glass UV-LED Market
Supply Chain Restructuring and Cost Dynamics
Supply chain and cost structure changes are reshaping how value is captured across the value chain. The combination of substrate limitations, export-controlled materials, and rising skilled-labor costs is pushing companies to rethink sourcing, inventory management, and manufacturing geography. At the same time, efficiency improvements are altering the relative importance of component cost versus system-level performance. In many cases, a higher-performing LED can justify a higher unit cost if it reduces energy usage, simplifies thermal design, or accelerates throughput. This reframing favors suppliers that can demonstrate total system value rather than competing solely on component pricing.
Competitive Landscape and the Strategies Defining Leadership
The competitive field is defined by a blend of established LED manufacturers, specialty deep UV players, and vertically oriented solution providers. Market leadership is not simply a function of scale; it increasingly depends on wavelength-specific expertise, certification readiness, and the ability to align product portfolios with high-priority application segments.
Differentiation Through Application Focus and Wavelength Breadth
Seoul Viosys Co., Ltd. has concentrated on its Violeds UV-C LED series optimized for UVC disinfection in water, air, and surface applications, an approach that emphasizes targeted performance in high-demand sanitation use cases. Nichia Corporation has pursued a broader wavelength strategy, offering full-range UV-C, UV-B, and UV-A LEDs for disinfection and mercury-free applications, while also expanding its portfolio with recent UV-A and UV-B products aimed at curing and specialized uses. This breadth supports flexibility across customer requirements and positions the company to capture demand across multiple application layers.
Crystal IS and Sensor Electronic Technology, Inc. continue to emphasize high-performance UVC and deep UV LEDs spanning 240-365nm for sterilization, sensors, and biomedical uses, focusing on technical performance in settings where wavelength precision and reliability carry disproportionate weight. STANLEY ELECTRIC CO., LTD. differentiates with UV-C and UV-A LEDs featuring hermetic sealing for disinfection and curing, an engineering choice that highlights durability and integration reliability. ams-OSRAM AG has built a recognizable portfolio through its OSLON UV-C LED line for air, water, and surface disinfection, and its recent efficiency gains reinforce the strategic value of semiconductor-level performance improvement.
Luminus Devices supports healthcare disinfection, water purification, and industrial curing with UVC and UVA LEDs, aligning its portfolio with both public-health and industrial demand. Nikkiso Co., Ltd. focuses on deep UV-LEDs for mercury lamp replacement in water purification and air sterilization, a positioning that directly addresses the substitution dynamic across environmental applications. LG Innotek Co., Ltd. integrates UV LEDs into lighting and disinfection solutions, reflecting a different competitive angle that emphasizes system-level integration and broader product ecosystems rather than component-only positioning.
Market Evolution: Consolidation, Specialization, and New Entrants
The market’s moderate concentration suggests room for both consolidation and continued specialization. Top players are likely to deepen application-specific capabilities, especially where certification, substrate access, and efficiency gains provide durable differentiation. At the same time, the fragmentation across wavelengths and applications creates entry points for firms that can solve a specific performance, integration, or compliance problem more effectively than generalist competitors.
Consolidation pressure is expected to intensify where scale matters most, particularly in substrate-dependent manufacturing and in segments that require extensive qualification and customer support. Conversely, specialization is likely to remain attractive in deep UV, medical/scientific, and curing applications where performance requirements are tightly defined and the cost of underperformance is high. New entrants will need to navigate material constraints and skilled-labor costs, but they can still compete by targeting underserved wavelength gaps, developing novel packaging or thermal-management approaches, or building strong certification and compliance capabilities early.
Forward-Looking Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to define the market’s direction and the commercial opportunities attached to them.
Efficiency Gains as a Deployment Catalyst
Continued improvements in UV-C and UV-A efficiency are likely to accelerate adoption in applications where energy consumption, thermal load, and system size have previously limited scale. As efficiency rises, total cost of ownership comparisons become more favorable against legacy alternatives, especially in disinfection and curing settings where operating costs and space constraints matter. The commercial opportunity here is not limited to component sales; it extends to system design, integration services, and performance-based value propositions that tie product selection to operational outcomes.
Supply Chain Resilience Becomes a Competitive Differentiator
Material controls and substrate limitations are likely to keep supply chain resilience at the center of strategy. Companies that diversify sourcing, negotiate long-term substrate access, and build transparent compliance and traceability processes will be better positioned to manage cost volatility and customer qualification cycles. For buyers, supplier resilience is increasingly part of procurement risk assessment, which creates an advantage for vendors that can demonstrate stable access to critical inputs and predictable delivery performance.
Certification and Standardization as Adoption Accelerators and Gatekeepers
Regulatory and standards activity is expected to remain a dual force: enabling broader deployment by establishing trust and performance benchmarks, while also extending validation timelines and adding cost for suppliers. The companies that treat certification as a strategic capability rather than a late-stage compliance task will gain speed and credibility in sensitive applications such as residential water treatment and public-health-related disinfection. For the market as a whole, this trend raises the bar for entry but also rewards organizations that can align product development with regulatory expectations early.
Potential Risks and Uncertainties
Several uncertainties bear monitoring. Further tightening of material export controls could disrupt supplier planning and increase input volatility, particularly for producers with concentrated sourcing exposure. Substrate constraints may persist if large-diameter aluminum nitride supply does not expand at a pace matching demand, maintaining pressure on per-unit costs in UV-C production. Labor cost inflation could also compress margins if process automation and workforce development lag behind manufacturing complexity. Finally, regulatory divergence across regions may create uneven adoption speeds, making it harder to scale standardized solutions globally without localized compliance investment.
Actionable Guidance for Decision-Makers
The market’s trajectory offers distinct implications depending on an organization’s role in the value chain. The following considerations can help translate market dynamics into prioritized actions.
For Manufacturers and Technology Developers
Focus investment where performance differentiation is most defensible. That means prioritizing wavelength-specific improvements, packaging reliability, thermal management, and certification readiness in high-value applications rather than competing broadly on price alone. Strengthening supply chain resilience should be treated as a strategic capability, including substrate access, material sourcing diversification, and process automation to offset skilled-labor cost pressure. Companies should also evaluate whether they can capture more value through system-level integration or partnered solutions, particularly in disinfection and curing where end users increasingly evaluate total operating performance.
For Investors
Evaluate exposure not just by revenue potential but by supply chain positioning, wage and substrate risk, and the ability to navigate certification timelines. The most attractive opportunities are likely to be in companies that combine meaningful efficiency gains with application-specific traction and credible compliance pathways. Diversification across wavelength segments may reduce reliance on any single bottleneck, but specialization can also create durable advantages where performance requirements are strict and substitution options are limited. Track material control developments and substrate supply progress, as these factors are likely to influence both cost structures and the pace of scaling.
For Procurement and End-User Organizations
Treat UV LED selection as a total-cost and risk decision rather than a component purchase. Prioritize suppliers with demonstrated certification readiness, stable material access, and evidence of efficiency and reliability in the target application. Build evaluation cycles that account for compliance validation, integration requirements, and long-term supply continuity, especially in water treatment, healthcare disinfection, and industrial curing settings where downtime or failure carries operational penalties. Align specification decisions with actual duty cycles and environmental conditions rather than maximum output claims, since real-world performance is often determined by thermal design, packaging quality, and system integration as much as by LED output.
The UV LEDs market is moving from a phase of capability demonstration to one of scaled deployment, where efficiency, compliance, and supply chain resilience determine who captures value and how quickly adoption broadens. Detailed segment-level data, company benchmarking, and scenario-based forecasts can sharpen these decisions further and help organizations convert market momentum into a coherent strategy. For decision-makers seeking a deeper, application-specific view of the landscape, the full research report provides expanded segmentation detail, competitive profiling, and tailored recommendations designed to support capital, product, and procurement decisions with greater precision.
For detailed analysis of this topic, please visit the official page: UV LEDs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
LIS Market 2032: How 7.8% CAGR and 65% Concentration Shape Strategic Decisions
By pmarketresearch, 2026-09-21
Laboratory Information System (LIS) Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Navigating Growth Amid Structural Complexity
The Laboratory Information System market has matured from a niche operational tool into a core infrastructure layer for modern diagnostic and research laboratories. Over the historical period from 2020 to 2025, the market expanded from approximately $110.0 million to an estimated $157.5 million, reflecting a compound annual growth rate that underscores sustained institutional adoption. Forward projections through 2032 point toward continued expansion, with the market anticipated to reach roughly $264.6 million. This trajectory implies a steady annualized growth rate of approximately 7.8 percent, signaling that demand is no longer driven solely by baseline digitization but by deeper integration of data workflows, regulatory compliance, and analytical capabilities.
Several structural features characterize the current landscape. Market concentration remains notable, with the top three participants collectively accounting for roughly 65 percent of revenue and the top five capturing approximately 78 percent. This concentration suggests that scale, established compliance frameworks, and interoperability with legacy clinical systems continue to act as meaningful barriers to entry, while also creating room for specialized or cloud-native challengers in underserved segments. The composition of the installed base further highlights a shift in how organizations view laboratory software: integrated laboratory information systems now command a larger share of the total addressable spend compared with standalone deployments, reflecting a preference for platforms that unify test ordering, specimen tracking, result reporting, and billing within a single workflow.
At the application level, clinical diagnostics represents the dominant use case, absorbing the majority of system investments as hospitals, reference labs, and specialty testing facilities prioritize turnaround time, result accuracy, and seamless electronic health record connectivity. Laboratory management functions, while smaller in aggregate spend, are gaining strategic importance as operations scale, regulatory documentation requirements intensify, and managers seek centralized control over inventory, calibration, and audit trails. Regionally, North America continues to anchor the largest revenue pool, followed by Europe and the Asia Pacific region. Latin America and the Middle East and Africa represent smaller but structurally interesting markets, often characterized by evolving accreditation expectations and incremental modernization of public and private laboratory networks.
Key Challenges and Inflection Points
Despite the constructive demand environment, the market is encountering several pressure points that are reshaping purchasing decisions and implementation timelines.
- Regulatory acceleration is compressing adaptation windows. Upcoming changes to quality management expectations, including the transition toward ISO 13485 alignment referenced through updated quality system requirements, are forcing laboratories and vendors to reassess documentation logic, validation protocols, and audit readiness. For many organizations, compliance is no longer a one-time project but an ongoing operational discipline that must be embedded directly into LIS templates and reporting structures.
- Legacy integration and interoperability remain persistent friction. Laboratories frequently operate across heterogeneous instrument fleets, disconnected data repositories, and varying electronic health record environments. Deploying a new system therefore involves more than software installation; it requires reconciling data dictionaries, managing interface lifecycles, and ensuring that digitized workflows do not inadvertently increase manual reconciliation work.
- Total cost of ownership expectations are rising alongside functionality demands. As laboratories pursue faster turnaround, stronger traceability, and advanced analytics, decision-makers increasingly scrutinize not only license or subscription costs but also implementation effort, training overhead, interface maintenance, and long-term scalability. Organizations that underestimated these operational realities are reframing procurement around lifecycle value rather than initial price.
Core Drivers Reshaping the LIS Landscape
Technology Innovation and the Analytics Turn
Technology evolution is shifting the value proposition of laboratory information systems from transaction processing toward decision support. Cloud deployment models, modular architectures, and API-first designs are making it more practical to connect instruments, middleware, and enterprise applications without building heavily customized point-to-point interfaces. At the same time, the integration of data analytics capabilities is becoming a differentiator. Recent market activity illustrates this shift clearly: one major vendor acquired a data analytics firm to establish a dedicated innovations center, signaling that the next competitive frontier is not merely storing results but transforming them into actionable operational intelligence.
For laboratory operators, this trajectory means the most valuable systems are those that reduce manual handoffs, support real-time dashboards, and enable trend analysis across specimen volume, turnaround times, and quality metrics. The presence of artificial intelligence and machine learning features, when implemented responsibly, is increasingly associated with workload prioritization, anomaly flagging, and predictive staffing insights. Importantly, these capabilities are not uniformly mature across all vendors, which creates a meaningful evaluation gap for buyers comparing platforms on future extensibility rather than current feature lists.
Blood Bank Information Systems Market
Policy and Regulatory Dynamics as Both Constraint and Catalyst
Regulatory change is functioning as both a compliance burden and an adoption catalyst. The mandatory shift toward quality management system expectations aligned with ISO 13485, effective in early 2026, is prompting medical device and in-vitro diagnostic manufacturers to align documentation and process controls more tightly with international standards. For laboratory information systems, this translates into renewed emphasis on validated workflows, electronic record integrity, and traceable change control. Laboratories must also prepare for updated Centers for Medicare & Medicaid Services rules expected as early as late 2025, which may require adjustments to reporting templates and data handling practices.
Simultaneously, the accreditation landscape continues to reward digitization. Implementation cycles for ISO 17025 typically span 12 to 18 months from planning through accreditation, encouraging laboratories to select systems that can support standardized method validation, proficiency testing documentation, and audit-ready record retention from the outset. Administrative modernization is also reshaping operational routines; for example, regulatory survey fee payments have moved to online channels, reflecting a broader push toward digital process hygiene. Collectively, these developments raise the cost of lagging behind and strengthen the case for platforms that embed compliance logic into everyday workflows.
Demand-Side Shifts in Laboratory Operations
On the demand side, laboratories are under pressure to do more with constrained staffing while meeting rising expectations for speed and transparency. Clinical operators are increasingly prioritizing end-to-end visibility, from specimen accessioning through result verification and physician delivery, because delays or data gaps can cascade into downstream care delays and patient satisfaction erosion. In parallel, specialized testing and molecular workflows are expanding in complexity, requiring systems that can handle richer data structures, chain-of-custody tracking, and multi-step interpretive reporting.
Laboratory Water Purifier Market
Recent partnership activity in digital pathology illustrates how demand is pulling vendors toward seamless workflow integration. A notable collaboration brought together a laboratory information system provider and a digital pathology platform to streamline image and report integration, reducing the friction between slide review and result reporting. Such initiatives indicate that laboratories are no longer satisfied with isolated tools; they want connected ecosystems that support multidisciplinary review, remote consultation, and unified data access.
PW Consulting
Supply-Side and Cost Structure Evolution
The vendor side is adjusting to these expectations through targeted consolidation, capability expansion, and a growing emphasis on compliance-ready configurations. Acquisitions that add molecular capabilities or analytics depth are enabling established players to offer broader workflow coverage within a single relationship, which can simplify procurement and reduce integration risk for larger laboratories. At the same time, smaller and cloud-focused providers are competing on implementation speed, subscription economics, and niche conformance features, particularly for environmental, quality, and specialized testing labs that require ISO 17025-aligned documentation support.
Cost structures are therefore diverging. Large integrated platforms often command premium positioning but may lower the total number of vendor relationships and interface projects a laboratory must manage. Smaller or modular solutions can reduce initial procurement barriers and accelerate time to value, though they may require additional effort in connecting to enterprise systems or scaling across multiple sites. The practical implication is that cost comparisons are increasingly incomplete without an assessment of implementation burden, interface count, and ongoing support requirements.
Competitive Landscape: Positioning, Differentiation, and Consolidation Signals
The competitive field blends mature diagnostics and enterprise software companies with specialized informatics providers and emerging cloud-native entrants. The largest players benefit from broad installed bases, established device ecosystems, and the ability to position laboratory information systems within wider clinical or analytical portfolios. This positioning can be advantageous for organizations seeking a single vendor relationship across instruments, middleware, and reporting layers, but it may also introduce complexity if the broader portfolio is not equally optimized for laboratory workflow specifics.
Mid-tier and specialized vendors tend to compete on depth of laboratory-centered functionality, configuration flexibility, and domain-specific compliance support. Companies with strong roots in laboratory operations often emphasize intuitive accessioning, specimen tracking, result verification, and audit trail management, appealing to laboratories that prioritize usability and operational control. Cloud-oriented providers, meanwhile, differentiate through rapid deployment, subscription models, and simplified maintenance, which can be attractive to smaller labs or those with limited internal IT capacity. Some of these providers have also advanced compliance narratives, including demonstrations of AI-enabled environmental laboratory setups aligned with ISO 17025 expectations, reflecting a broader push to connect modern informatics with accreditation requirements.
Recent transactions and partnerships underscore a market in motion. The acquisition of a data analytics firm by a long-standing laboratory software vendor points to a strategy of embedding analytical horsepower directly into the platform. Another vendor completed a purchase to strengthen molecular capabilities, illustrating how companies are expanding into higher-complexity testing domains where data handling and interpretive workflows carry greater value. At the same time, partnerships focused on digital pathology integration show a willingness to build ecosystems rather than relying solely on proprietary end-to-end suites. These moves suggest a market that is consolidating around broader capability bundles while still encouraging targeted alliances where specialized functionality is critical.
Strategic Positioning Themes Among Leaders
- Ecosystem breadth versus workflow depth. Larger companies often compete on the strength of integrated device and enterprise connections, while smaller specialists compete on fine-grained laboratory workflow fit and faster configuration cycles.
- Compliance-by-design narratives. With regulatory expectations tightening, vendors that can demonstrate validated templates, robust change control, and accreditation-ready documentation gain a tangible advantage during evaluation cycles.
- Deployment and ownership models. Cloud subscriptions, hybrid architectures, and on-premises options continue to shape purchasing decisions, with laboratories weighing data control, IT capacity, and long-term scalability.
- Analytics and interoperability as future-proofing. Vendors investing in analytics centers or digital pathology partnerships are signaling that the next phase of competition will hinge on how well systems convert operational data into usable insight and connect across disciplinary boundaries.
How the Landscape Is Evolving
Three patterns are likely to shape the next phase of competition. First, consolidation will continue where scale, compliance portfolios, and analytics ambitions justify mergers or acquisitions, particularly among vendors seeking to add molecular, digital pathology, or data science capabilities. Second, differentiation will increasingly emerge in subsegments, as environmental labs, molecular diagnostics providers, and high-volume clinical operations each prioritize distinct compliance and workflow requirements. Third, new entrants and cloud-native challengers will persist in niches where implementation speed, transparent subscription economics, and modern user experience can outweigh the advantages of incumbent scale. The net effect is a market that is neither fully homogeneous nor fully fragmented, but rather stratified by the balance of integration needs, compliance demands, and operational complexity.
Forward Outlook: Three Trends to Watch Through 2032
Trend One: Compliance-EmbodiedPlatforms Become Table Stakes
As quality management expectations align more closely with international standards and CMS-related rules evolve, laboratory information systems will be judged not only on functionality but on how naturally they support documentation, validation, and audit readiness. Platforms that embed these requirements into daily workflows will reduce the lag between regulatory change and operational adaptation. For buyers, this increases the value of configurable templates, traceable record structures, and vendor support during accreditation cycles. For vendors, it raises the stakes around validation services, release discipline, and ongoing regulatory monitoring. A key uncertainty is the pace and granularity of rule implementation across jurisdictions, which may create uneven adoption timing and divergent regional requirements.
Trend Two: Analytics and Interoperability Move from Enhancement to Core Value
The next phase of growth will likely be driven by systems that transform laboratory data into operational insight. Dashboards for turnaround time, error rates, specimen flow, and resource utilization are becoming central to laboratory management, while smoother data exchange with electronic health records and external reporting systems is increasingly expected rather than optional. A notable acquisition establishing a data analytics innovations center suggests that leading vendors see analytical integration as a strategic growth lever rather than a peripheral feature. The commercial opportunity lies in helping laboratories make staffing, workflow, and quality decisions with greater precision. The risk is that overpromised analytics can create disappointment if data quality, integration scope, or change management are insufficient to support meaningful insight generation.
Trend Three: Modular, Cloud-Forward Deployments Expand in Select Segments
Cloud-native and modular deployment models are expected to continue gaining traction, particularly where laboratories seek faster implementation, lower upfront capital exposure, and simplified maintenance. Specialized and mid-sized laboratories may favor these models if they reduce the operational burden of hosting, patching, and interface upkeep. However, adoption will remain uneven in settings where data residency requirements, internal IT policy, or complex instrument ecosystems favor more controlled deployment approaches. The commercial implication is a bifurcated purchasing environment: cloud-forward solutions will likely grow fastest where agility and compliance configurability align, while integrated on-premises or hybrid solutions will retain strength in large, complex environments with substantial legacy investments.
Strategic Actions for Decision-Makers
For Laboratory Operators and Procurement Teams
- Evaluate platforms against the full operational lifecycle, including interface count, configuration effort, training burden, validation support, and long-term scalability, rather than focusing primarily on initial license or subscription cost.
- Prioritize systems that embed compliance logic and audit-ready documentation into daily workflows, especially where accreditation cycles and quality management transitions are imminent.
- Treat interoperability as a first-order requirement; map the current instrument and electronic health record landscape early to understand the integration scope a new system will need to absorb.
For Vendors and Manufacturers
- Invest in analytics, interoperability, and domain-specific compliance features that reduce the operational burden on laboratories, since these capabilities increasingly differentiate platforms in competitive evaluations.
- Use targeted partnerships and selective acquisitions to expand into molecular, digital pathology, or data science capabilities where organic development would be slower or riskier.
- Clarify deployment and ownership options with transparent total cost narratives, because buyers are increasingly comparing lifecycle economics across cloud, hybrid, and on-premises models.
For Investors and Strategic Planners
- Focus on vendors demonstrating measurable progress in analytics integration, compliance readiness, and workflow breadth, since these attributes are shaping the next round of procurement advantage.
- Watch for consolidation activity that signals shifts in capability boundaries, particularly where acquisitions add molecular depth, data science capacity, or specialized accreditation support.
- Assess regional variation carefully; market maturity, regulatory expectations, and laboratory modernization pace differ enough across geographies to influence both growth timing and competitive entry strategies.
Why Detailed Intelligence Matters Now
The laboratory information system market is entering a period in which regulatory timing, integration complexity, and analytics expectations will separate decision-makers who plan around lifecycle value from those who evaluate systems primarily on feature checklists. The trends outlined here point to a landscape where compliance-embodied design, connected workflows, and data-driven operations are increasingly central to commercial success. Yet the specifics that determine outcomes—such as regional rule timing, segment-specific accreditation demands, interface complexity, and vendor capability maturity—are difficult to assess from high-level trends alone.
For organizations making procurement, investment, or product strategy decisions, detailed segmentation data, vendor capability comparisons, and implementation-pattern analysis can materially improve the quality of the choice. A deeper examination of how spending is distributed across deployment models, laboratory types, and geographies, along with a closer look at recent transactions and compliance-driven purchasing shifts, provides the granularity needed to calibrate timing, scope, and risk. Readers seeking that level of detail can access the full PW Consulting research report for expanded segmentation data, company-level signals, and tailored scenario analysis suited to specific operational and investment contexts.
For detailed analysis of this topic, please visit the official page: Laboratory Information System (LIS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Trailer Hitch Market 2026: Why 6.5% CAGR and North America's $96M Share Redefine Growth
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Global Trailer Hitch Market
The trailer hitch market has matured into a critical infrastructure component for vehicle towing ecosystems, linking consumer recreation, commercial logistics, and specialty transport applications. As of the 2025 baseline, the industry has reached a scale where incremental growth requires deliberate positioning rather than broad participation. Historical momentum from 2020 through 2025 reflects steady expansion, followed by a forecast trajectory through 2032 that points to continued, though uneven, advancement. The trajectory is supported by a compound annual growth rate of approximately 6.5 percent, with total market revenue measured in USD millions across all segments. This scaling is not merely a function of more vehicles on the road; it reflects structural shifts in how goods, leisure assets, and specialized equipment are moved across short and medium distances.
At the macro level, the market is characterized by concentrated leadership, with the top three players accounting for roughly 65 percent of revenue and the top five expanding that share to around 80 percent. Such concentration signals a landscape where incumbents have built durable advantages in distribution, engineering know-how, and brand trust. Yet concentration does not imply stagnation. The forecast window through 2032 suggests that pockets of rapid growth persist in specific applications and geographies, while the overall curve is tempered by cost pressures, regulatory scrutiny, and shifting vehicle architectures. For decision-makers, the central question is no longer whether the market is expanding, but where value will accrue when growth becomes more selective and when compliance costs rise alongside performance expectations.
Market Snapshot and Structural Pressures
The revenue trajectory from 2020 to 2025 established a foundation that the 2026 to 2032 forecast builds upon, with the 2025 baseline serving as a pivot point for both planning and competitive investment. Growth has been broad-based enough to reward scale players, but not so uniform that every segment shares the same economics. Receiver hitches continue to anchor a large share of total revenue, reflecting their ubiquity across light and medium-duty towing. Alongside them, gooseneck, fifth wheel, weight distribution, and pintle configurations each command distinct niches tied to vehicle type, load profile, and regional towing culture. The application mix spans recreational towing, marine transport, equipment hauling, agricultural use, and other commercial activities, creating demand that is simultaneous but not homogeneous. This heterogeneity is a defining feature of the market: one product family must satisfy very different engineering tolerances, end-user expectations, and procurement cycles.
Three challenges now shape the industry’s near-term path. First, regulatory and safety scrutiny is intensifying, particularly around load security and component integrity. A notable example is the recall of more than 145,000 trailer hitch locks in 2025 due to a loose component that could allow loads to detach from towing vehicles, as documented in the NHTSA official recall notice from January 2025. Such events elevate customer sensitivity to failure modes and push manufacturers to tighten quality assurance, traceability, and design validation. Second, vehicle platform evolution is altering attachment points, electrical architectures, and clearance constraints, making vehicle-specific fit increasingly complex even as consumers and fleets expect seamless integration. Third, input cost volatility and supply chain dependencies continue to pressure margins, especially for stamped steel, castings, coatings, and electronic kits, while customers resist price increases that outpace perceived value. These forces are not independent; they interact to raise the bar on engineering rigor, process control, and go-to-market discipline.
Trailer Axle Market
Key Demand Drivers Reshaping the Market
Technology Innovation and Performance Benchmarks
Engineering differentiation has moved beyond basic load ratings to encompass integration, adjustability, corrosion resistance, and ease of installation. Manufacturers are investing in designs that reduce tongue weight transfer issues, improve maneuverability under load, and simplify accessory changes such as ball mounts and sway control. Hidden and low-profile hitch configurations, once niche considerations, are gaining relevance among passengers and commercial users who prioritize aesthetics and packaging without sacrificing functional capacity. Electrical integration, including lighting and sensing kits in OEM-quality grades, is becoming a meaningful point of value creation, especially where trailer detection, braking coordination, and vehicle electronics must work in concert. These advances do more than raise performance; they create defensible product lines that can command premium positioning and reduce substitution risk when installed correctly and supported by clear documentation.
The practical implication is that performance claims require substantiation. Products that deliver measurable improvements in towing stability, installation time, or long-term durability are better positioned to win in channels where technicians and knowledgeable buyers compare alternatives directly. Conversely, commoditized SKUs face greater pressure to compete on price alone, which can erode margins and brand equity over time. Innovation that reduces field failures and simplifies the fit process tends to generate the strongest combination of customer satisfaction and repeat demand.
Policy, Regulation, and Safety Expectations
Regulatory attention is raising the cost of nonconformance and the value of preemptive quality systems. The 2025 lock recall illustrates how a single component vulnerability can ripple through distribution networks, service channels, and consumer confidence. Beyond recalls, manufacturers must navigate evolving standards for load ratings, labeling, towing safety communications, and electrical compatibility. In Europe, OEM-quality expectations and homologation requirements often shape product specifications at the design stage, while North American channels emphasize vehicle-specific fit, installation support, and dealer education. In both contexts, compliance is shifting from a back-office function to a front-line competitive factor.
For strategy, this means quality planning and design validation are no longer optional cost centers. Companies that embed traceability, durability testing, and field monitoring into product development reduce the probability of costly corrective actions and build trust with downstream partners. Clear communication about specifications, installation requirements, and load limits also protects brand reputation and reduces misuse-related claims. In markets where safety perception influences purchasing, a track record of reliable components can support premium pricing and improve channel willingness to stock and promote a product line.
Demand-Side Behavior and Use-Case Expansion
Demand patterns are shaped by recreational towing, marine transport, equipment hauling, agricultural work, and other commercial applications, each with distinct purchasing triggers. Recreational towing drives volume through seasonal purchasing, accessory add-ons, and upgrades tied to vehicle changes. Marine and equipment transport prioritize reliability and quick attachment, often under time pressure and in demanding environments. Agricultural and specialty commercial use tends to value durability, serviceability, and compatibility with existing equipment more than appearance or low profile. These divergent priorities mean that a single product architecture rarely satisfies all segments equally, and successful portfolios are those that align features with real use-case constraints.
Behavioral shifts also matter. Buyers increasingly expect vehicle-specific solutions, clear installation guidance, and accessories that reduce friction during setup. As towing becomes more connected to broader vehicle electronics and active safety features, end users and commercial operators look for components that integrate cleanly rather than simply bolt on. In this environment, education and support become part of the product experience, influencing both initial purchase and long-term loyalty. Companies that provide precise fit information, installation clarity, and accessory ecosystems tend to convert interest into sales more efficiently than those relying on broad compatibility claims alone.
Supply Chain and Cost Structure Dynamics
Cost structure is being reshaped by material inputs, manufacturing footprints, and logistics dependencies. Steel pricing, coatings, casting capacity, and electronic content all influence the cost base for hitch assemblies and associated kits. At the same time, regional sourcing decisions affect lead times, tariff exposure, and responsiveness to local demand patterns. The result is a market where efficient operations and disciplined inventory management can create meaningful margin advantages, while brittle supply chains expose producers to stock-outs and price instability.
The commercial opportunity lies in designing for manufacturability and serviceability without sacrificing performance. Standardizing high-volume components where possible, coordinating material procurement with rolling demand plans, and reducing assembly complexity can improve throughput and lower unit cost. Equally important is aligning production location decisions with channel realities, since regional preferences for OEM-quality content, dealer support, and after-sales service can differ substantially. Companies that balance scale with flexibility tend to navigate cost volatility more effectively than those locked into rigid cost structures.
Competitive Landscape and Evolving Positioning
Incumbent Strengths and Differentiation Vectors
The market features a mix of established North American manufacturers and European suppliers with strong OEM relationships and engineering heritage. CURT Manufacturing operates with a focus on USA-made, vehicle-specific fit for both OEM and aftermarket contexts, spanning receiver, fifth wheel, and gooseneck offerings alongside a full towing product set. Draw-Tite emphasizes custom designs and hidden hitch options distributed through dealer networks, a model that rewards channel relationships and installation readiness. Reese Products is known for heavy-duty receiver and towing systems that span light to heavy applications, appealing to users who prioritize capacity and ruggedness. B&W Trailer Hitches brings American-made engineering to gooseneck and fifth wheel categories, with attention to ball mount adjustability and weight distribution systems. Blue Ox addresses towing solutions such as tow bars, baseplates, sway control, and fifth wheel hitches, aligning closely with specialty towing requirements.
European suppliers add a distinct dimension. MVG focuses on towbars and electrical kits delivered in OEM-quality grades, which supports integration into vehicle platforms where fit and finish are tightly controlled. ACPS Automotive, operating under the ORIS name, produces disappearing hitches for passenger cars, SUVs, and vans, targeting end users who value aesthetics and integrated packaging. Bosch contributes towbars and hitch components, leveraging broader automotive component credibility and engineering scale. On the consolidation side, Horizon Global Corporation manages multiple brands including Draw-Tite, REESE, Bulldog, and Fulton, enabling portfolio breadth and cross-brand distribution leverage. RANDYS Worldwide offers adjustable hitch products and continues to expand its towing solution set, including a 2025 acquisition of BulletProof Hitches aimed at broadening accessories and towing capabilities.
Integration, Differentiation, and Channel Dynamics
The competitive landscape is evolving through a blend of consolidation, portfolio extension, and niche specialization. Larger multi-brand operators can use shared engineering, procurement, and distribution to capture efficiencies while maintaining distinct brand identities for different customer segments. This structure allows them to address a wide range of vehicle types and use cases without forcing every product into a single brand narrative. At the same time, specialist manufacturers maintain advantage by deepening vehicle-specific fit, heavy-duty capacity, or OEM-quality integration, which can be difficult for broader portfolios to replicate at equal fidelity.
Channel strategy remains decisive. Dealer networks, specialty retailers, and online distribution each impose different expectations for packaging, fit information, inventory depth, and support materials. In dealer-led channels, installation readiness and technician trust often determine repeat business. In direct and e-commerce channels, clear specifications, compatibility tools, and accessory bundles influence conversion. Companies that align product design with channel realities, rather than forcing the same offering through every route, tend to achieve stronger sell-through and fewer returns. The market also rewards brands that can communicate load ratings, compatibility, and safety guidance with precision, since uncertainty at point of purchase frequently becomes friction in the sales process.
A practical development to monitor is the ongoing M&A activity that broadens accessory and towing solution portfolios. RANDYS Worldwide’s acquisition of BulletProof Hitches in April 2025 signals a continued push to assemble more complete towing ecosystems rather than competing on the hitch assembly alone. This trend suggests that future competition will increasingly be evaluated across the full set of accessories, mounting hardware, electrical kits, and support content that surround the primary hitch, making ecosystem completeness a strategic asset.
Forward-Looking Trends and Linked Opportunities
Trend One: Integration as a Baseline Expectation
Over the next three to five years, hitch products are likely to be judged not only by load capacity but by how cleanly they integrate with vehicle architecture, electrical systems, and accessory ecosystems. This trend favors designs that simplify installation, reduce ambiguity in fitment, and support compatible lighting, braking, and sensing components. The commercial opportunity is in building product lines where the hitch is the anchor for a coherent solution rather than an isolated component. Manufacturers that invest in compatibility tooling, installer guidance, and accessory coordination can capture higher ensemble value and reduce substitution risk. The risk is that integration expectations rise faster than product development cycles can accommodate, especially as vehicle platforms change and electrical architectures become more complex. Companies that treat integration as a continuous capability, supported by close coordination with vehicle data and field feedback, will be better positioned to stay current.
Trend Two: Safety and Compliance as Competitive Levers
Safety scrutiny is expected to persist as a defining influence on product design, marketing claims, and distribution standards. Recalls and field failures draw attention to load security, component integrity, and installation correctness, which in turn raises the value of robust testing, clear labeling, and traceable manufacturing. The opportunity is to convert compliance discipline into a market advantage by offering products with verifiable durability, straightforward installation, and transparent specifications. Buyers and channel partners increasingly prefer brands that reduce uncertainty, and that preference can translate into stickier relationships and more resilient pricing. The uncertainty lies in the possibility of more stringent requirements or enforcement actions that raise the cost of conformity across the sector, compressing margins for players without efficient quality systems. Firms that build quality into the process rather than inspecting it at the end will absorb regulatory shifts more effectively.
Trend Three: Portfolio Breadth and Ecosystem Completion
A third trend is the movement toward broader towing and accessory portfolios that address the full task of towing rather than a single hardware item. This is visible in acquisitions and multi-brand structures that assemble receiver solutions, weight distribution systems, gooseneck and fifth wheel options, hidden designs, and electrical kits under coordinated strategies. The opportunity is to capture more wallet share by offering compatible accessories, replacement parts, and service content that accompany the primary hitch. Complete ecosystems also support installation confidence and reduce the likelihood of mismatched components, which improves customer outcomes and reduces returns. The risk is complexity: broader portfolios require disciplined product rationalization, consistent quality across brands, and clear positioning so that customers can navigate choices without confusion. Organizations that scale portfolios while preserving clarity in fit, function, and support are more likely to convert breadth into durable advantage.
PW Consulting Automotive & Machinery Research Center
Strategic Implications for Decision-Makers
For Manufacturers
Product differentiation should be anchored in fit precision, integration quality, and verified durability rather than in broad claims of capacity. Prioritize engineering that reduces installation ambiguity and supports accessory compatibility, since these factors directly influence field performance and channel confidence. Invest in the quality systems and traceability needed to manage safety scrutiny, because recalls and field issues can quickly erode brand trust and create costly corrective cycles. Where scale allows, pursue portfolio breadth with disciplined rationalization, ensuring that each addition serves a clear use case and does not dilute positioning. Align manufacturing and sourcing decisions with channel and regional expectations, since OEM-quality content, dealer support, and service models differ meaningfully across markets.
Hitch Lock Market
For Investors
Evaluate exposure not just by top-line growth but by the defensibility of product architecture, channel relationships, and quality track record. Companies with vehicle-specific fit capabilities, strong integration content, and credible safety performance are better positioned to sustain margins as scrutiny rises. Consolidation that expands accessory and solution breadth can create value if it improves ecosystem completeness without introducing quality or brand confusion. Monitor regulatory signals closely, since changes in recall dynamics, labeling expectations, or towing safety standards can alter cost structures and competitive positioning. In portfolio construction, favor businesses that combine scale in high-volume categories with specialization where performance demands justify premium positioning.
For Procurement and Channel Partners
Source decisions should weigh total cost of reliable installation and support, not price alone. Verify vehicle-specific compatibility, load rating clarity, and accessory compatibility before committing to volume, since mismatched components create service friction and end-user dissatisfaction. Prefer suppliers that provide clear installation guidance, consistent specification communication, and responsive support, because these factors reduce returns and improve sell-through. Balance breadth and depth in inventory by focusing on high-velocity fitments and safety-critical components, while keeping access to specialized configurations for commercial and specialty applications. Where possible, request documentation that supports traceability and quality assurance, especially for components that influence load security.
Closing Perspective
The trailer hitch market is moving from broad expansion to a more selective phase where value accrues to those who combine engineering rigor, integration capability, and disciplined execution. The market’s scale and concentration indicate that leadership positions are durable, but they are not immune to reassessment when safety expectations rise, vehicle architectures change, and cost pressures intensify. The forward opportunity lies in aligning product design with real use cases, building ecosystems that reduce installation and compatibility friction, and treating quality and traceability as strategic assets rather than overhead.
For organizations seeking to act on these dynamics with finer granularity, the most useful next step is to examine detailed segmentation, regional demand patterns, and company-specific profiles that sit beyond the overview picture. A complete research report can provide the segmented data and context needed to shape product roadmaps, channel plans, and investment theses with greater precision. The strategic direction is clear: in a market where safety, fit, and integration increasingly define competitive standing, timely intelligence is not optional for decision-makers who want to move with confidence.
For detailed analysis of this topic, please visit the official page: Trailer Hitch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com