

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Appliance Power Cord Market: How 6.8% CAGR and PVC-Dominant Supply Chains Are Reshaping Competition

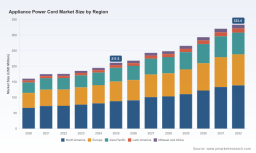
The Appliance Power Cord Market: Strategic Trends and Commercial Opportunities in a Growing Ecosystem
The appliance power cord market has evolved far beyond its origins as a basic utility component, transforming into a strategically significant segment where safety, material science, and global compatibility converge. Over the past five years, the industry has navigated supply chain recalibrations, tightening regulatory frameworks, and shifting appliance architectures that collectively redefine how manufacturers, distributors, and end-users value power connectivity. As households and commercial facilities increasingly prioritize reliability, energy efficiency, and interoperability, power cords are no longer viewed as interchangeable commodities. They function as critical interface components that influence product safety certifications, warranty exposure, and brand reputation. Understanding the structural dynamics of this market requires looking beyond unit volumes and examining the underlying forces shaping pricing, innovation, and competitive positioning.
Market Landscape and Core Challenges
The global appliance power cord market has demonstrated steady expansion, with revenues growing from approximately $160.5 million in 2020 to an estimated $211.5 million in 2025, and is projected to reach roughly $333.4 million by 2032. This trajectory reflects a compound annual growth rate of approximately 6.8 percent, signaling sustained demand supported by replacement cycles, appliance modernization, and expanding manufacturing footprints. The market structure remains moderately fragmented, with the top three participants collectively holding roughly 27.5 percent of total revenue and the top five accounting for approximately 35.2 percent. This concentration level suggests that while scale players command meaningful share, specialized manufacturers retain viable positioning through customization, regional compliance expertise, and rapid fulfillment capabilities.
Beneath the headline growth, several structural challenges are reshaping how participants compete and allocate capital. First, safety certification and standardization complexity has intensified. Compliance with testing protocols such as UL 817 requires rigorous validation of durability, insulation integrity, and continuous load performance, raising the technical barrier for new entrants and increasing time-to-market for product lines. Second, material cost volatility and supply continuity remain persistent pressures. Copper conductor pricing and PVC insulation availability influence margin structures, and while supply trends have remained relatively stable through mid-2026, geopolitical trade flows, freight fluctuations, and regional manufacturing capacity still create pockets of disruption. Third, the market faces a tipping point in application diversity. As appliance categories expand and electrical architectures become more sophisticated, manufacturers must balance standardized inventory with highly customized configurations that meet local plug types, voltage requirements, and specialty use cases such as hospital-grade or heavy-duty environments.
Worldwide Domestic Appliances Market
These challenges are not merely operational friction points; they are strategic filters. Companies that can efficiently navigate certification pathways, maintain resilient material sourcing, and align product portfolios with evolving appliance lifecycles are better positioned to capture margin while defending against commoditization. Conversely, players relying on undifferentiated volume strategies risk exposure to price compression and interchangeability substitution.
Key Drivers Shaping Market Direction
Technological Innovation and Product Differentiation
Advancements in cord construction, terminal design, and insulation materials are steadily redefining performance expectations. Manufacturers are expanding high-voltage configurations, specialized ROJ-style connections, and hospital-grade variants that meet stringent durability and safety thresholds. These innovations respond directly to appliance architectures that demand higher continuous loads, improved heat resistance, and longer operational lifespans. The introduction of new heavy-duty and international configurations, alongside expanded high-voltage options compatible with major household appliances, illustrates how product roadmaps are being shaped by real-world usage requirements rather than baseline compliance alone. For commercial and residential appliance makers, access to differentiated cord sets translates into reduced warranty risk, simplified regional deployment, and stronger value proposition in premium product lines.
Regulatory and Standards Evolution
Regulatory frameworks continue to act as both a constraint and a catalyst. The UL 817 standard establishes rigorous testing expectations for safety and durability, effectively functioning as a market gatekeeper that rewards manufacturers with mature quality systems and transparent supply traceability. At the same time, electrical code updates are altering load management expectations. Recent NEC revisions addressing continuous load calculations for electric appliances, including dishwashers, ease certain engineering assumptions while reinforcing the importance of reliable cord performance under sustained operation. These regulatory shifts push manufacturers to design for durability rather than minimal compliance, and they increase the value of configurations that are pre-validated for specific appliance categories. In practical terms, certification readiness has become a strategic asset, not just a checkbox.
Demand-Side Shifts in Consumer and Commercial Behavior
End-user expectations are increasingly shaped by energy efficiency mandates and total cost of ownership considerations. Efficiency-driven appliance adoption places greater emphasis on components that can sustain performance over longer service lives, creating demand for durable, longer-lasting power cords in consumer households. Simultaneously, commercial facilities and rental housing operators prioritize configurations that minimize maintenance interruptions and simplify inventory management across multiple appliance types. The growing availability of hospital-grade and heavy-duty options reflects this broadening demand spectrum, where reliability specifications are tied directly to operational continuity. For manufacturers, this means product portfolios must accommodate both everyday replacement cycles and specialty applications without fragmenting production efficiency.
Supply Chain and Cost Structure Dynamics
Material stability has provided a favorable backdrop, with copper and PVC insulation remaining the primary inputs and supply trends holding relatively steady through mid-2026. Yet stability in raw materials does not eliminate structural cost pressures. Freight variability, regional labor dynamics, and the cost of maintaining multiple plug combinations and international variants can erode margins if production is poorly optimized. Companies that reduce minimum order friction, consolidate configurable SKUs, and align production with regional demand clusters achieve better cost discipline while preserving flexibility. In an environment where differentiation increasingly hinges on availability, lead time, and compliance assurance, supply chain agility has become a direct competitive advantage.
Competitive Landscape and Leading Strategies
The competitive field features a mix of focused domestic manufacturers and globally positioned suppliers, each leveraging distinct strategic angles. Quail Electronics has built a reputation around North American and international appliance power cords, including two- and three-prong options and high-voltage configurations tailored for refrigerators, washers, dryers, and ranges. Its approach emphasizes broad compatibility with major household appliances, which supports OEM and distributor relationships that value standardized yet robust solutions. Kord King positions itself as a large-scale U.S. manufacturer of custom appliance power cords, offering a wide range of plug combinations alongside hospital-grade and heavy-duty variants for both household and commercial applications. This customization-heavy model enables the company to serve customers with specialized requirements while maintaining a recognizable domestic manufacturing footprint. Interpower Corporation differentiates through country-specific international and North American cord sets, with a notable emphasis on accessibility through no-minimum-order policies. This flexibility lowers entry barriers for smaller appliance assemblers and export-focused operations that need localized compliance without large inventory commitments.
Additional players reinforce the market's diversity. Consolidated Electronic Wire & Cable and Electri-Cord Manufacturing both emphasize custom and standard power cords for household appliances, with offerings that span shielded, hospital-grade, and domestically or internationally compliant configurations. Volex Group brings a more global manufacturing perspective, supplying power cords and plugs across appliance and consumer electronics applications, which allows it to address multi-region demand with broader scale and cross-market synergies.
Strategic differentiation among these leaders clusters around three themes. First, certification and safety positioning functions as a trust signal that reduces buyer risk, particularly in applications where failure carries significant operational or liability consequences. Second, configuration breadth and customization capability determine how well a supplier can serve mixed appliance portfolios without forcing customers into overly narrow SKU sets. Third, fulfillment flexibility, including low minimum order thresholds and rapid international variant availability, enables smaller and mid-sized appliance manufacturers to source reliably without incurring excess inventory risk.
The competitive landscape is evolving through selective consolidation and persistent differentiation. While the market remains accessible to specialized suppliers, the premium increasingly flows to firms that can combine compliance assurance, regional variant depth, and efficient configuration management. New entrants face a meaningful hurdle in certification infrastructure and material continuity, but opportunities exist for players that identify underserved regional plug requirements or niche application segments such as specialty commercial appliances and higher-duty cycle environments. The result is a market that rewards operational precision and customer-specific value creation rather than pure volume competition.
Power Cords & Extension Cords Market
Forward Outlook: Three Trends Shaping the Next Three to Five Years
First, compliance-integrated product design will become a standard expectation rather than a differentiator. As safety and durability testing requirements remain entrenched and electrical code adjustments continue to influence load assumptions, cord suppliers that embed validation into their development cycles will reduce customer onboarding friction and shorten qualification timelines. The commercial opportunity lies in offering pre-certified configurations mapped to common appliance categories, which can lower procurement complexity and support faster time-to-market for appliance manufacturers. The primary risk is regulatory drift; if testing expectations tighten further or regional standards diverge, suppliers with less agile quality systems may face repeated redesign cycles.
Second, regional interoperability will drive demand for highly configurable yet efficiently managed cord portfolios. Global appliance trade and multi-market product launches require power solutions that accommodate local plug types, voltage standards, and specialty ratings without fragmenting into unmanageable SKU proliferation. Suppliers that invest in modular design, strategic inventory clustering, and clear international variant management will be better equipped to serve export-oriented and multi-region appliance programs. The upside is expanded addressable demand across cross-border appliance supply chains. The uncertainty lies in trade policy shifts and regional manufacturing localization pressures, which could alter sourcing patterns and favor domestic production in certain markets.
Third, durability and lifecycle value will command growing commercial attention. Energy efficiency mandates and total cost of ownership considerations are shifting buyer focus toward components that sustain performance through longer appliance lifespans. This dynamic favors reinforced insulation, higher-duty construction, and configurations validated for continuous use, particularly in households and commercial settings where replacement disruption is costly. The opportunity is to position durable cord sets as risk-reduction assets that support appliance reliability claims and reduce field failure exposure. The risk is that durability premiums must be justified through demonstrable performance and clear warranty or maintenance benefits; otherwise, price-sensitive buyers may continue favoring lower-cost alternatives in non-critical applications.
Strategic Considerations for Decision-Makers
For appliance manufacturers and original equipment suppliers, the priority is to treat power cord selection as a design-and-compliance decision with downstream operational implications. Selecting configurations that align with target market plug types, voltage ranges, and durability expectations can streamline certification, reduce field failure risk, and simplify warranty management. It is equally important to evaluate suppliers not only on unit price but on configuration breadth, certification readiness, and fulfillment flexibility, since these factors influence program launch speed and inventory efficiency. Where product roadmaps include international variants or specialty applications, partnering with suppliers that already maintain validated regional options can shorten development cycles and reduce qualification burden.
For investors evaluating exposure to this segment, the value proposition lies less in headline growth alone and more in the structural resilience of compliant, differentiated product lines. Companies with mature safety validation processes, manageable material exposure, and the ability to serve both standard and specialty applications are better positioned to defend margins across demand cycles. Investment theses should account for the impact of regulatory continuity, regional trade dynamics, and the extent to which a supplier can translate configuration complexity into commercial advantage rather than operational cost. Diversification across standard household applications and higher-specification commercial or hospital-grade segments can provide a more balanced exposure profile.
For procurement and supply chain leaders, the practical focus should be on minimizing qualification risk and inventory friction while preserving access to required configurations. Where demand spans multiple appliance types or regions, consolidating around suppliers with pre-validated variants and flexible order thresholds can reduce administrative overhead and improve responsiveness to design changes or late-stage program adjustments. Maintaining clear visibility into material continuity, certification status, and lead-time behavior for critical cord variants supports more resilient sourcing decisions, particularly when appliance launch schedules or regulatory updates introduce timing pressure.
PW Consulting
For organizations seeking deeper segmentation data, competitive benchmarking, and tailored recommendations aligned with specific product portfolios or regional strategies, the full research report provides expanded detail across market size trajectories, segmentation dynamics, and actionable planning frameworks. The complete version includes granular breakdowns and customized guidance designed to support precise sourcing, product roadmap, and investment decisions.
For detailed analysis of this topic, please visit the official page: Appliance Power Cord Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com