

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Brake Calipers Market 2026: Unpacking the Real Drivers Behind 5.4% CAGR Growth Through 2032

Strategic Trends and Commercial Opportunities in the Global Brake Calipers Market
The brake calipers market is navigating a period of structural transformation, driven by evolving vehicle architectures, tightening safety standards, and the electrification of mobility. Market valuations have demonstrated steady expansion over the past half decade, with revenue climbing from approximately 1.22 billion USD in 2020 to an estimated 1.59 billion USD by 2025. Forward projections indicate continued momentum, with the market expected to reach roughly 2.30 billion USD by 2032, translating to a compound annual growth rate of 5.4 percent across the 2026 to 2032 forecast horizon. This trajectory reflects more than incremental volume growth; it signals a recalibration of how braking systems are designed, integrated, and monetized across passenger cars, commercial vehicles, and two-wheelers.
PW Consulting
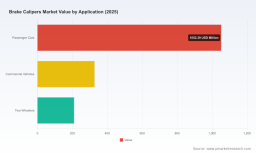
Beneath the headline figures lies a market that is increasingly segmented by technology readiness, regional manufacturing footprints, and the pace of electronic integration. The revenue distribution shows clear geographic weight, with Asia Pacific generating the largest share, followed by Europe and North America, while Latin America and the Middle East and Africa contribute smaller but strategically important volumes. On the product side, floating calipers continue to command a larger revenue pool than fixed calipers, reflecting their prevalence in mainstream passenger and commercial platforms. Application-wise, passenger cars dominate the revenue mix, with commercial vehicles and two-wheelers forming meaningful secondary segments. Industry concentration remains moderately high, with the top three players accounting for approximately 45 percent of market revenue and the top five reaching around 65 percent, underscoring the influence of established OEMs suppliers and Tier 1 integrators.
This landscape is not static. The market stands at an inflection point where conventional hydraulic braking is being augmented, and in some segments displaced, by electronically controlled architectures. Recognizing where the market is headed requires looking past aggregate growth rates and examining the forces reshaping supplier positioning, cost structures, and demand patterns.
Brake Disc Market
Market Snapshot: Scale, Structure, and the Pressure Points
A Growing but Increasingly Complex Revenue Base
The market's expansion from 2020 through 2025 reflects a steady recovery and normalization in global automotive production, coupled with ongoing replacement demand in aftermarket channels. The projected climb to 2.30 billion USD by 2032 suggests that volume growth will be supported by platform refreshes, fleet modernization, and the gradual penetration of advanced braking features into mass-market segments. Yet growth is uneven. Regions with faster electrification adoption and stronger commercial vehicle activity are likely to outpace mature markets where replacement cycles are longer and price competition is more intense.
The concentration profile indicates that scale, engineering depth, and long-term OEM relationships still matter. Suppliers with broad portfolios spanning passenger and commercial segments, along with the ability to integrate electronic components, are well positioned to capture disproportionate value. At the same time, the presence of specialized high-performance and aftermarket-focused players highlights a market that rewards differentiated technical positioning as much as volume scale.
Key Challenges and Turning Points
Three pressure points are reshaping how participants approach the market.
- Technology transition and integration complexity. The shift toward electronically controlled braking and brake-by-wire architectures is changing the caliper from a purely mechanical actuator into a node within a broader safety-critical system. This raises engineering barriers, validates new testing and certification pathways, and forces suppliers to manage software and hardware development in tandem.
- Cost and sourcing pressures amid electrification. Vehicle platforms are evolving, and the brake caliper's role is being re-evaluated in the context of regenerative braking, weight targets, and packaging constraints. Suppliers must balance material choices, machining precision, and calibration costs while competing on price in segments where electrification does not immediately translate into higher unit economics.
- Regional volatility and supply chain realignment. Manufacturing footprints, logistics reliability, and regulatory divergence across markets are creating uneven operating conditions. Suppliers that depend on concentrated sourcing or single-region assembly face greater exposure to disruptions, while those with diversified production and localized engineering support are better equipped to maintain continuity.
These challenges are not merely operational headaches; they are strategic signals. They point to a market where the value equation is moving from component volume toward system capability, regional responsiveness, and the ability to meet functional safety requirements in electronically controlled environments.
Key Drivers Reshaping the Brake Calipers Market
Technology Innovation and the Rise of Electronically Controlled Braking
The most consequential driver is the accelerating integration of electronics into braking systems. Brake-by-wire and electro-hydraulic architectures are extending the role of the caliper beyond traditional actuation, enabling faster response, adaptive force distribution, and tighter integration with vehicle stability and regenerative braking strategies. Fourth-generation brake-by-wire systems have demonstrated full electronic actuation of calipers while meeting high automotive functional safety standards, marking a practical step toward software-defined braking. This evolution matters because it changes the caliper's development cycle: suppliers must account for sensor feedback loops, fail-safe behavior, and calibration across a wider range of driving conditions.
Worldwide Aircraft Brake Calipers Market
In parallel, high-performance and motorsport applications continue to push material and hydraulic design boundaries. New small-bore caliper configurations and carbon ceramic big brake kits illustrate how specialized segments are advancing thermal management, stiffness, and packaging efficiency. While these are niche volumes, they often serve as technology proving grounds and brand amplifiers that can influence premium OE programs and aftermarket credibility.
Policy and Regulatory Environment: Safety, Localization, and Functional Standards
Regulatory and safety requirements are increasingly shaping both product design and market access. Functional safety expectations for electronically controlled braking are rising, with ASIL-D class compliance becoming a relevant benchmark for systems that rely on electronic actuation. This raises the bar for validation, traceability, and supplier capability, favoring organizations with established safety engineering processes and mature testing infrastructure.
Localization trends are also influencing market dynamics. Partnerships and joint ventures aimed at adapting advanced braking technologies for regional markets illustrate how suppliers are responding to content requirements, cost structures, and speed-to-market considerations. For instance, collaborations focused on localizing brake-by-wire solutions in China and forming air brake joint ventures in India reflect a broader pattern: advanced brake systems are being adapted to regional manufacturing ecosystems rather than distributed solely through centralized global supply chains.
Demand-Side Shifts: Electrification, Fleet Mix, and Performance Expectations
Demand is being reshaped by three interrelated shifts. First, electrification is altering brake duty cycles. Regenerative braking reduces friction braking usage in certain driving conditions, which can affect wear patterns, caliper utilization, and the relative importance of precision actuation and thermal stability. Second, commercial vehicle demand remains a structural pillar, with fleet operators prioritizing downtime reduction, safety performance, and integrated braking solutions that can support higher vehicle weights and demanding duty cycles. Third, consumer and fleet expectations around safety, stopping performance, and system responsiveness are rising, encouraging adoption of advanced braking features that were once confined to premium or motorsport contexts.
These demand dynamics create a bifurcated opportunity set. In mainstream passenger vehicles, the focus is on reliability, cost efficiency, and incremental electronic integration. In premium, performance, and commercial segments, the opportunity lies in higher-specification calipers, tighter system integration, and solutions that support advanced safety and vehicle dynamics functions.
Supply Chain and Cost Structure Realignment
Cost structures are being reexamined as suppliers balance precision manufacturing with the added complexity of electronic integration. Material selection, machining tolerances, and assembly automation remain critical levers, but the growing presence of software-defined components means that value capture is increasingly tied to engineering capability and system-level optimization rather than component pricing alone. Supply chain resilience has also gained prominence, with participants enhancing multi-source sourcing, regional assembly options, and inventory strategies to reduce exposure to logistics bottlenecks and demand swings.
Recent product and funding activity reflects this environment. Investments in caliper production capabilities, launches of matched brake caliper, pad, and rotor packages, and continued motorsport-focused innovations all point to a market where suppliers are pursuing both scale efficiency and differentiated performance positioning simultaneously.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Leading Participants
The competitive field is shaped by companies with distinct technological emphases and customer bases. Several patterns stand out.
- High-performance and motorsport specialization. Some suppliers concentrate on high-performance calipers for luxury vehicles, supercars, and motorsport applications. This positioning emphasizes thermal performance, stiffness, weight optimization, and brand prestige. Specialized caliper designs, including small-bore configurations and carbon ceramic big brake kits, reinforce a premium performance narrative that can spill over into broader OE credibility and aftermarket demand.
- Electronic integration and OE breadth. Other leaders focus on brake calipers integrated with electronic control systems and ABS for global automotive OEMs, or on advanced calipers for intelligent safety systems and electric vehicle platforms. These players benefit from system-level engineering capabilities, broad OEM relationships, and the ability to align caliper design with vehicle-wide braking and safety architectures.
- Commercial vehicle and integrated braking solutions. Suppliers with strong commercial vehicle footprints are expanding integrated braking solutions and caliper offerings tailored to heavier-duty applications. This segment values durability, serviceability, and system reliability, and is increasingly receptive to electronically supported braking functions where they improve safety and operational efficiency.
- Regional OEM integration and component breadth. Additional participants emphasize brake calipers and related components for OEM integration across Asian and global vehicle markets, often combining calipers with complementary elements such as ceramic pads. This breadth can strengthen package value and improve positioning in cost-sensitive but volume-rich segments.
- Aftermarket and replacement focus. Some companies concentrate on replacement and OEM brake calipers for standard and heavy-duty vehicles, or on premium calipers matched with pads and rotors for enhanced safety and performance. This strategy targets continuity, fitment assurance, and the aftermarket's need for reliable, application-specific solutions.
Differentiation and Competitive Advantage
Differentiation in this market is increasingly multidimensional. Volume scale remains important, but it is no longer sufficient on its own. Suppliers that can combine precision mechanical design with electronic system integration, functional safety competence, and regional manufacturing flexibility are gaining relative advantage. High-performance specialists leverage technical heritage and brand association to command premium positioning, while broader OE-focused suppliers rely on integration depth, platform coverage, and system-level support. Meanwhile, aftermarket-oriented players compete on application coverage, quality consistency, and package completeness.
A notable competitive dynamic is the growing relevance of partnerships and joint ventures. Collaborations that localize advanced braking technologies or combine complementary capabilities are enabling faster market access, improved cost alignment, and stronger regional presence. This suggests that competitive advantage will increasingly depend on both internal engineering strength and the ability to structure alliances that reduce time-to-market and improve local responsiveness.
Market Structure Evolution: Consolidation, Differentiation, and New Entrants
The market is likely to continue evolving along three paths. Consolidation pressure will persist among suppliers seeking to strengthen OEM coverage, expand geographic reach, and build electronic integration capabilities through scale and acquisition. Differentiation will deepen as performance, commercial, and electronically controlled braking segments diverge in spec, validation requirements, and pricing dynamics. New entrants and niche players may find opportunities in specialized applications, regional localization, or targeted aftermarket packages, especially where they can offer clear technical or service advantages without needing to match the full breadth of global Tier 1 portfolios.
Recent launches and investment activity support this image of a market in motion. From motorsport small-bore calipers and premium matched brake packages to fourth-generation brake-by-wire systems and funded production advancements, participants are pursuing multiple routes to growth. The common thread is a push toward higher technical value and stronger application alignment rather than reliance on commodity volume alone.
Future Outlook: Trends and Commercial Opportunities
Trend 1: Software-Defined and Electronically Actuated Braking Will Move Deeper into Production
Electronically controlled braking is poised to expand beyond premium and specialized applications as vehicle architectures increasingly accommodate brake-by-wire and electro-hydraulic solutions. The commercial opportunity lies in calipers and associated system components that can meet strict functional safety requirements, support precise electronic actuation, and integrate cleanly with vehicle control strategies. Suppliers that can deliver validated, ASIL-compliant actuation performance and offer scalable integration pathways will be better positioned to participate in next-generation platform programs. The uncertainty here relates to adoption pace across mass-market segments, where cost sensitivity and validation timelines can slow deployment.
Trend 2: Regionalization and Localized Brake Technology Deployment Will Intensify
Market access strategies are increasingly shaped by localization. Partnerships and joint ventures that adapt advanced braking technologies for specific regions reflect the reality that cost, content expectations, and manufacturing ecosystems vary significantly by market. The commercial opportunity is twofold: suppliers can build stronger regional footholds by aligning production and engineering support with local demand, while customers can benefit from shorter lead times and improved cost structures. The risk is that localization efforts can fragment engineering resources and complicate harmonization across global platforms if not managed with clear architecture standards.
Trend 3: Performance, Commercial, and Aftermarket Segments Will Diverge Further in Spec and Value
The market is likely to see greater divergence between mainstream, performance, commercial, and aftermarket requirements. Mainstream passenger applications will continue to emphasize reliability, cost efficiency, and incremental electronic features. Performance and motorsport-related segments will keep pushing thermal, structural, and packaging boundaries, serving as both revenue niches and brand enablers. Commercial vehicle demand will favor integrated solutions that reduce downtime and support safety under demanding duty cycles. Aftermarket buyers will continue to value fitment confidence, application coverage, and package completeness.
The commercial opportunity is to align product portfolios and service models with these distinct value equations rather than treating the caliper market as a single homogeneous segment. Suppliers and investors that can identify which segment offers the best mix of margin, growth, and competitive defensibility will be better placed to allocate capital and engineering resources.
Strategic Actions for Decision-Makers
For Brake System Manufacturers and Tier 1 Suppliers
- Prioritize electronic integration and functional safety capability as core competencies, not optional add-ons. Investing in validation, calibration, and system-level engineering will increasingly determine eligibility for advanced braking programs.
- Align production footprints and sourcing strategies with regional demand patterns. Where localization trends are strengthening, consider partnerships or assembly options that improve responsiveness while preserving engineering consistency.
- Segment the portfolio deliberately. Mainstream, performance, commercial, and aftermarket applications require different design priorities, pricing strategies, and service models. Avoid diluting focus by treating all segments with the same value proposition.
For Investors and Strategic Planners
- Evaluate exposure to electronic braking adoption curves and regional localization trends when assessing growth potential. Revenue expansion will be uneven, and value capture will favor suppliers with the right combination of technology readiness and market access.
- Look beyond top-line growth to concentration and differentiation dynamics. In a market where leading players already hold substantial share, incremental opportunity often comes from specialization, regional positioning, or system-integration depth rather than undifferentiated volume gains.
- Monitor partnership activity and product launches as early indicators of strategic direction. Joint ventures, funded production expansions, and advanced system unveilings often signal where capabilities and market access are being built.
For Procurement and Fleet Decision-Makers
- Assess braking solutions based on total system fit, including electronic compatibility, functional safety readiness, and serviceability, rather than component price alone. As braking architectures become more integrated, the caliper's role within the broader system becomes more consequential.
- Plan for segment-specific requirements. Commercial fleets, passenger vehicle operations, and performance-oriented applications have distinct priorities, and purchasing strategies should reflect those differences in spec, validation, and support expectations.
- Build supplier evaluation frameworks that account for regional continuity, engineering support, and the ability to support evolving electronic braking functions over the vehicle lifecycle.
Closing Perspective
The brake calipers market is expanding, but the more important story is how its value base is shifting. Growth to roughly 2.30 billion USD by 2032, at a 5.4 percent CAGR across the forecast period, provides a useful macro frame, yet the real strategic challenge lies in navigating technology transition, regionalization, and segmentation divergence. Suppliers and investors that treat the market as a set of distinct value equations, and that invest accordingly in electronic integration, functional safety, and regional responsiveness, are more likely to capture durable advantage.
Detailed segment trajectories, regional breakdowns, competitor benchmarking, and application-level demand scenarios can sharpen these decisions further. For decision-makers seeking a deeper, customizable view of the market landscape and its commercial implications, the full PW Consulting research report offers expanded data and tailored analysis across the segments and dynamics discussed here.
For detailed analysis of this topic, please visit the official page: Brake Calipers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com