

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
LIS Market 2032: How 7.8% CAGR and 65% Concentration Shape Strategic Decisions

Laboratory Information System (LIS) Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Navigating Growth Amid Structural Complexity
The Laboratory Information System market has matured from a niche operational tool into a core infrastructure layer for modern diagnostic and research laboratories. Over the historical period from 2020 to 2025, the market expanded from approximately $110.0 million to an estimated $157.5 million, reflecting a compound annual growth rate that underscores sustained institutional adoption. Forward projections through 2032 point toward continued expansion, with the market anticipated to reach roughly $264.6 million. This trajectory implies a steady annualized growth rate of approximately 7.8 percent, signaling that demand is no longer driven solely by baseline digitization but by deeper integration of data workflows, regulatory compliance, and analytical capabilities.
Several structural features characterize the current landscape. Market concentration remains notable, with the top three participants collectively accounting for roughly 65 percent of revenue and the top five capturing approximately 78 percent. This concentration suggests that scale, established compliance frameworks, and interoperability with legacy clinical systems continue to act as meaningful barriers to entry, while also creating room for specialized or cloud-native challengers in underserved segments. The composition of the installed base further highlights a shift in how organizations view laboratory software: integrated laboratory information systems now command a larger share of the total addressable spend compared with standalone deployments, reflecting a preference for platforms that unify test ordering, specimen tracking, result reporting, and billing within a single workflow.
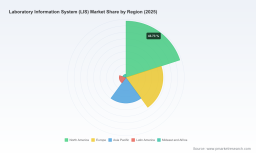
At the application level, clinical diagnostics represents the dominant use case, absorbing the majority of system investments as hospitals, reference labs, and specialty testing facilities prioritize turnaround time, result accuracy, and seamless electronic health record connectivity. Laboratory management functions, while smaller in aggregate spend, are gaining strategic importance as operations scale, regulatory documentation requirements intensify, and managers seek centralized control over inventory, calibration, and audit trails. Regionally, North America continues to anchor the largest revenue pool, followed by Europe and the Asia Pacific region. Latin America and the Middle East and Africa represent smaller but structurally interesting markets, often characterized by evolving accreditation expectations and incremental modernization of public and private laboratory networks.
Key Challenges and Inflection Points
Despite the constructive demand environment, the market is encountering several pressure points that are reshaping purchasing decisions and implementation timelines.
- Regulatory acceleration is compressing adaptation windows. Upcoming changes to quality management expectations, including the transition toward ISO 13485 alignment referenced through updated quality system requirements, are forcing laboratories and vendors to reassess documentation logic, validation protocols, and audit readiness. For many organizations, compliance is no longer a one-time project but an ongoing operational discipline that must be embedded directly into LIS templates and reporting structures.
- Legacy integration and interoperability remain persistent friction. Laboratories frequently operate across heterogeneous instrument fleets, disconnected data repositories, and varying electronic health record environments. Deploying a new system therefore involves more than software installation; it requires reconciling data dictionaries, managing interface lifecycles, and ensuring that digitized workflows do not inadvertently increase manual reconciliation work.
- Total cost of ownership expectations are rising alongside functionality demands. As laboratories pursue faster turnaround, stronger traceability, and advanced analytics, decision-makers increasingly scrutinize not only license or subscription costs but also implementation effort, training overhead, interface maintenance, and long-term scalability. Organizations that underestimated these operational realities are reframing procurement around lifecycle value rather than initial price.
Core Drivers Reshaping the LIS Landscape
Technology Innovation and the Analytics Turn
Technology evolution is shifting the value proposition of laboratory information systems from transaction processing toward decision support. Cloud deployment models, modular architectures, and API-first designs are making it more practical to connect instruments, middleware, and enterprise applications without building heavily customized point-to-point interfaces. At the same time, the integration of data analytics capabilities is becoming a differentiator. Recent market activity illustrates this shift clearly: one major vendor acquired a data analytics firm to establish a dedicated innovations center, signaling that the next competitive frontier is not merely storing results but transforming them into actionable operational intelligence.
For laboratory operators, this trajectory means the most valuable systems are those that reduce manual handoffs, support real-time dashboards, and enable trend analysis across specimen volume, turnaround times, and quality metrics. The presence of artificial intelligence and machine learning features, when implemented responsibly, is increasingly associated with workload prioritization, anomaly flagging, and predictive staffing insights. Importantly, these capabilities are not uniformly mature across all vendors, which creates a meaningful evaluation gap for buyers comparing platforms on future extensibility rather than current feature lists.
Blood Bank Information Systems Market
Policy and Regulatory Dynamics as Both Constraint and Catalyst
Regulatory change is functioning as both a compliance burden and an adoption catalyst. The mandatory shift toward quality management system expectations aligned with ISO 13485, effective in early 2026, is prompting medical device and in-vitro diagnostic manufacturers to align documentation and process controls more tightly with international standards. For laboratory information systems, this translates into renewed emphasis on validated workflows, electronic record integrity, and traceable change control. Laboratories must also prepare for updated Centers for Medicare & Medicaid Services rules expected as early as late 2025, which may require adjustments to reporting templates and data handling practices.
Simultaneously, the accreditation landscape continues to reward digitization. Implementation cycles for ISO 17025 typically span 12 to 18 months from planning through accreditation, encouraging laboratories to select systems that can support standardized method validation, proficiency testing documentation, and audit-ready record retention from the outset. Administrative modernization is also reshaping operational routines; for example, regulatory survey fee payments have moved to online channels, reflecting a broader push toward digital process hygiene. Collectively, these developments raise the cost of lagging behind and strengthen the case for platforms that embed compliance logic into everyday workflows.
Demand-Side Shifts in Laboratory Operations
On the demand side, laboratories are under pressure to do more with constrained staffing while meeting rising expectations for speed and transparency. Clinical operators are increasingly prioritizing end-to-end visibility, from specimen accessioning through result verification and physician delivery, because delays or data gaps can cascade into downstream care delays and patient satisfaction erosion. In parallel, specialized testing and molecular workflows are expanding in complexity, requiring systems that can handle richer data structures, chain-of-custody tracking, and multi-step interpretive reporting.
Laboratory Water Purifier Market
Recent partnership activity in digital pathology illustrates how demand is pulling vendors toward seamless workflow integration. A notable collaboration brought together a laboratory information system provider and a digital pathology platform to streamline image and report integration, reducing the friction between slide review and result reporting. Such initiatives indicate that laboratories are no longer satisfied with isolated tools; they want connected ecosystems that support multidisciplinary review, remote consultation, and unified data access.
PW Consulting
Supply-Side and Cost Structure Evolution
The vendor side is adjusting to these expectations through targeted consolidation, capability expansion, and a growing emphasis on compliance-ready configurations. Acquisitions that add molecular capabilities or analytics depth are enabling established players to offer broader workflow coverage within a single relationship, which can simplify procurement and reduce integration risk for larger laboratories. At the same time, smaller and cloud-focused providers are competing on implementation speed, subscription economics, and niche conformance features, particularly for environmental, quality, and specialized testing labs that require ISO 17025-aligned documentation support.
Cost structures are therefore diverging. Large integrated platforms often command premium positioning but may lower the total number of vendor relationships and interface projects a laboratory must manage. Smaller or modular solutions can reduce initial procurement barriers and accelerate time to value, though they may require additional effort in connecting to enterprise systems or scaling across multiple sites. The practical implication is that cost comparisons are increasingly incomplete without an assessment of implementation burden, interface count, and ongoing support requirements.
Competitive Landscape: Positioning, Differentiation, and Consolidation Signals
The competitive field blends mature diagnostics and enterprise software companies with specialized informatics providers and emerging cloud-native entrants. The largest players benefit from broad installed bases, established device ecosystems, and the ability to position laboratory information systems within wider clinical or analytical portfolios. This positioning can be advantageous for organizations seeking a single vendor relationship across instruments, middleware, and reporting layers, but it may also introduce complexity if the broader portfolio is not equally optimized for laboratory workflow specifics.
Mid-tier and specialized vendors tend to compete on depth of laboratory-centered functionality, configuration flexibility, and domain-specific compliance support. Companies with strong roots in laboratory operations often emphasize intuitive accessioning, specimen tracking, result verification, and audit trail management, appealing to laboratories that prioritize usability and operational control. Cloud-oriented providers, meanwhile, differentiate through rapid deployment, subscription models, and simplified maintenance, which can be attractive to smaller labs or those with limited internal IT capacity. Some of these providers have also advanced compliance narratives, including demonstrations of AI-enabled environmental laboratory setups aligned with ISO 17025 expectations, reflecting a broader push to connect modern informatics with accreditation requirements.
Recent transactions and partnerships underscore a market in motion. The acquisition of a data analytics firm by a long-standing laboratory software vendor points to a strategy of embedding analytical horsepower directly into the platform. Another vendor completed a purchase to strengthen molecular capabilities, illustrating how companies are expanding into higher-complexity testing domains where data handling and interpretive workflows carry greater value. At the same time, partnerships focused on digital pathology integration show a willingness to build ecosystems rather than relying solely on proprietary end-to-end suites. These moves suggest a market that is consolidating around broader capability bundles while still encouraging targeted alliances where specialized functionality is critical.
Strategic Positioning Themes Among Leaders
- Ecosystem breadth versus workflow depth. Larger companies often compete on the strength of integrated device and enterprise connections, while smaller specialists compete on fine-grained laboratory workflow fit and faster configuration cycles.
- Compliance-by-design narratives. With regulatory expectations tightening, vendors that can demonstrate validated templates, robust change control, and accreditation-ready documentation gain a tangible advantage during evaluation cycles.
- Deployment and ownership models. Cloud subscriptions, hybrid architectures, and on-premises options continue to shape purchasing decisions, with laboratories weighing data control, IT capacity, and long-term scalability.
- Analytics and interoperability as future-proofing. Vendors investing in analytics centers or digital pathology partnerships are signaling that the next phase of competition will hinge on how well systems convert operational data into usable insight and connect across disciplinary boundaries.
How the Landscape Is Evolving
Three patterns are likely to shape the next phase of competition. First, consolidation will continue where scale, compliance portfolios, and analytics ambitions justify mergers or acquisitions, particularly among vendors seeking to add molecular, digital pathology, or data science capabilities. Second, differentiation will increasingly emerge in subsegments, as environmental labs, molecular diagnostics providers, and high-volume clinical operations each prioritize distinct compliance and workflow requirements. Third, new entrants and cloud-native challengers will persist in niches where implementation speed, transparent subscription economics, and modern user experience can outweigh the advantages of incumbent scale. The net effect is a market that is neither fully homogeneous nor fully fragmented, but rather stratified by the balance of integration needs, compliance demands, and operational complexity.
Forward Outlook: Three Trends to Watch Through 2032
Trend One: Compliance-EmbodiedPlatforms Become Table Stakes
As quality management expectations align more closely with international standards and CMS-related rules evolve, laboratory information systems will be judged not only on functionality but on how naturally they support documentation, validation, and audit readiness. Platforms that embed these requirements into daily workflows will reduce the lag between regulatory change and operational adaptation. For buyers, this increases the value of configurable templates, traceable record structures, and vendor support during accreditation cycles. For vendors, it raises the stakes around validation services, release discipline, and ongoing regulatory monitoring. A key uncertainty is the pace and granularity of rule implementation across jurisdictions, which may create uneven adoption timing and divergent regional requirements.
Trend Two: Analytics and Interoperability Move from Enhancement to Core Value
The next phase of growth will likely be driven by systems that transform laboratory data into operational insight. Dashboards for turnaround time, error rates, specimen flow, and resource utilization are becoming central to laboratory management, while smoother data exchange with electronic health records and external reporting systems is increasingly expected rather than optional. A notable acquisition establishing a data analytics innovations center suggests that leading vendors see analytical integration as a strategic growth lever rather than a peripheral feature. The commercial opportunity lies in helping laboratories make staffing, workflow, and quality decisions with greater precision. The risk is that overpromised analytics can create disappointment if data quality, integration scope, or change management are insufficient to support meaningful insight generation.
Trend Three: Modular, Cloud-Forward Deployments Expand in Select Segments
Cloud-native and modular deployment models are expected to continue gaining traction, particularly where laboratories seek faster implementation, lower upfront capital exposure, and simplified maintenance. Specialized and mid-sized laboratories may favor these models if they reduce the operational burden of hosting, patching, and interface upkeep. However, adoption will remain uneven in settings where data residency requirements, internal IT policy, or complex instrument ecosystems favor more controlled deployment approaches. The commercial implication is a bifurcated purchasing environment: cloud-forward solutions will likely grow fastest where agility and compliance configurability align, while integrated on-premises or hybrid solutions will retain strength in large, complex environments with substantial legacy investments.
Strategic Actions for Decision-Makers
For Laboratory Operators and Procurement Teams
- Evaluate platforms against the full operational lifecycle, including interface count, configuration effort, training burden, validation support, and long-term scalability, rather than focusing primarily on initial license or subscription cost.
- Prioritize systems that embed compliance logic and audit-ready documentation into daily workflows, especially where accreditation cycles and quality management transitions are imminent.
- Treat interoperability as a first-order requirement; map the current instrument and electronic health record landscape early to understand the integration scope a new system will need to absorb.
For Vendors and Manufacturers
- Invest in analytics, interoperability, and domain-specific compliance features that reduce the operational burden on laboratories, since these capabilities increasingly differentiate platforms in competitive evaluations.
- Use targeted partnerships and selective acquisitions to expand into molecular, digital pathology, or data science capabilities where organic development would be slower or riskier.
- Clarify deployment and ownership options with transparent total cost narratives, because buyers are increasingly comparing lifecycle economics across cloud, hybrid, and on-premises models.
For Investors and Strategic Planners
- Focus on vendors demonstrating measurable progress in analytics integration, compliance readiness, and workflow breadth, since these attributes are shaping the next round of procurement advantage.
- Watch for consolidation activity that signals shifts in capability boundaries, particularly where acquisitions add molecular depth, data science capacity, or specialized accreditation support.
- Assess regional variation carefully; market maturity, regulatory expectations, and laboratory modernization pace differ enough across geographies to influence both growth timing and competitive entry strategies.
Why Detailed Intelligence Matters Now
The laboratory information system market is entering a period in which regulatory timing, integration complexity, and analytics expectations will separate decision-makers who plan around lifecycle value from those who evaluate systems primarily on feature checklists. The trends outlined here point to a landscape where compliance-embodied design, connected workflows, and data-driven operations are increasingly central to commercial success. Yet the specifics that determine outcomes—such as regional rule timing, segment-specific accreditation demands, interface complexity, and vendor capability maturity—are difficult to assess from high-level trends alone.
For organizations making procurement, investment, or product strategy decisions, detailed segmentation data, vendor capability comparisons, and implementation-pattern analysis can materially improve the quality of the choice. A deeper examination of how spending is distributed across deployment models, laboratory types, and geographies, along with a closer look at recent transactions and compliance-driven purchasing shifts, provides the granularity needed to calibrate timing, scope, and risk. Readers seeking that level of detail can access the full PW Consulting research report for expanded segmentation data, company-level signals, and tailored scenario analysis suited to specific operational and investment contexts.
For detailed analysis of this topic, please visit the official page: Laboratory Information System (LIS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com