

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Panoramic Sunroof Market 2026: 7.8% CAGR Trajectory and Regional Shifts

Panoramic Sunroof Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Overview: A Sector in Structural Expansion
The panoramic sunroof market has transitioned from a premium comfort upgrade to a core architectural feature in modern vehicle design. From 2020 to 2025, the market expanded steadily, growing from approximately 2.0 billion USD to 2.75 billion USD in 2025. The trajectory is projected to accelerate through the forecast horizon, with the market expected to reach 4.75 billion USD by 2032. This expansion reflects a compound annual growth rate of 7.8 percent, driven by a combination of vehicle platform redesigns, electrification trends, and evolving consumer expectations around cabin experience.
Automotive Sunroof Market
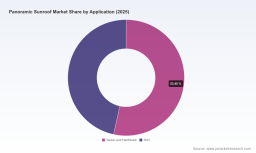
The growth is not uniform across all categories. Multi-panel configurations currently command the largest share of revenue, indicating a sustained preference for flexible light and ventilation solutions over single fixed panels. Application-wise, sedans and hatchbacks continue to represent the dominant volume, though SUV integration remains a significant and growing contributor. Geographically, the Asia Pacific region accounts for the largest revenue pool, followed by Europe and North America, with Latin America and the Mideast and Africa regions representing smaller but increasingly relevant demand centers.
Structural Challenges and Inflection Points
The sector is navigating several simultaneous pressures that are reshaping investment priorities and product roadmaps.
One of the most pressing challenges is the tension between aesthetic and experiential demands and physical constraints. Panoramic roof systems are expected to deliver larger glazed areas, lighter weight, improved thermal insulation, and higher structural integrity, all while meeting increasingly stringent safety requirements. Engineers are being asked to deliver more glass without adding mass, and to integrate switchable glazing, ambient lighting, and electronic actuators without compromising sealing performance or crash behavior. This pushes manufacturers toward material innovation and tighter system integration rather than incremental design changes.
A second inflection point comes from regulatory and certification complexity. Panoramic roofs must satisfy safety glazing standards and new requirements related to pedestrian protection in roof zones. At the same time, electronic actuator and control systems must align with functional safety expectations for automotive applications. These requirements raise the bar for validation, change the cost structure of product development, and make compliance capability a meaningful competitive differentiator.
A third challenge lies in the changing vehicle mix and the specific demands of electric platforms. Electrification affects roof architecture in multiple ways. Battery packaging, body stiffness targets, and drag coefficient management all influence how panoramic systems are specified and integrated. Consumer preference is moving toward openable panoramic configurations in EVs and SUVs, motivated by perceived improvements in interior space and air circulation. That shift creates opportunities, but also forces suppliers to adapt to different assembly sequences, thermal requirements, and volume patterns compared with traditional internal combustion platforms.
Core Growth Drivers
Technological Innovation and Material Evolution
The market is being shaped by a steady push toward lighter, smarter, and more integrated roof systems. Glass specification is a major focus area. Recent technical guidance in the sector notes that PVB interlayer films used in panoramic roof glass are moving toward reduced layers and gradient applications. This approach aims to lower weight and simplify installation in fixed panoramic modules, while preserving optical quality and structural performance. The same trajectory supports broader industry efforts to reduce component mass without sacrificing safety or durability.
Beyond glazing, actuator technology and electronic integration are becoming central to product differentiation. Openable panoramic systems increasingly combine smooth operation, low noise, and higher reliability with embedded controls that support diagnostic and safety functions. Suppliers that can package these features into compact, robust modules are better positioned to win on next-generation platforms where roof assembly space is tightly constrained.
Policy, Regulation, and Certification Dynamics
Regulatory frameworks are not merely compliance hurdles; they are actively influencing product architecture and supplier selection. Vehicle roofs are subject to safety glazing requirements and newer pedestrian protection considerations that affect how panoramic systems are designed and tested. For electronic components, functional safety expectations are now a baseline requirement for actuators and control modules. These standards raise the cost of entry for casual participants and reward suppliers with established validation infrastructure and documented engineering processes.
At the same time, broader vehicle regulation and testing protocols are indirectly increasing the strategic value of panoramic roofs. Emission-related standards and testing cycles place greater emphasis on aerodynamic efficiency and perceived vehicle drag reduction. In that context, a well-integrated roof system can contribute to packaging efficiency and overall design coherence, even if its direct emissions impact is indirect. The result is a market where regulatory alignment and engineering maturity reinforce each other.
Demand-Side Shifts in Passenger Vehicle Expectations
Buyers and OEMs are increasingly treating the roof as part of the lifestyle and cabin experience rather than a purely structural element. The preference for openable panoramic sunroofs in EVs and SUVs underscores a desire for improved headspace and fresh air circulation, along with the visual and experiential benefits of larger glazed areas. For manufacturers, these features can support vehicle positioning, especially in segments where cabin ambiance and perceived premium quality influence purchase decisions.
This demand shift is also pushing attention toward ambient lighting, switchable glazing, and other features that blur the line between roof and interior environment. As these elements become more common, the roof assembly becomes a more complex subsystem, and suppliers with broader integration capabilities gain leverage in the value chain.
Supply Chain and Cost Structure Pressures
Cost and weight targets remain persistent drivers of engineering decisions. Lightweighting goals are especially important as manufacturers balance safety, packaging, and efficiency requirements. At the same time, the integration of advanced glazing, electronics, and sealing technology changes the cost profile of panoramic systems. Suppliers are responding by designing modules that consolidate functions, reduce assembly complexity, and support more efficient installation on production lines.
Supply chain resilience is also increasingly relevant. Roof systems require coordinated inputs from glass manufacturers, polymer and interlayer suppliers, actuator producers, and module integrators. Any disruption in specialized materials or component availability can affect program timing and cost. Companies that can manage multi-tier sourcing, standardize designs across platforms, and maintain disciplined quality controls are better placed to withstand volatility and protect margins.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with the top three players capturing a significant share and the top five firms accounting for a majority of revenue. This structure suggests that scale, platform relationships, and engineering breadth matter, but it also leaves room for specialists who can win on specific attributes such as lightweight construction, glazing quality, or system integration.
Webasto SE remains a prominent reference point in openable panoramic roof systems, with a positioning that emphasizes market-leading glass, ambient lighting, and switchable glazing for passenger cars and SUVs. Its recent Infinity Roof panoramic roof system launch for Mahindra Electric Origin SUVs illustrates how suppliers are aligning product portfolios with electrification and premium cabin features. The launch highlights the growing relevance of lighting-integrated and experience-led roof designs in electrified SUVs.
Inalfa Roof Systems competes as a specialist in panoramic and openable modules, with an emphasis on lightweight designs and system integration. Its value proposition fits naturally into platforms where weight reduction and assembly efficiency are priorities. Magna International brings a broader module and sealing technology perspective, offering customizable panoramic sunroof modules and roof system solutions that can be tailored across multiple vehicle architectures.
CIE Automotive contributes through lightweight and composite panoramic sunroof components and full roof systems, reinforcing the importance of material choice in cost-and-weight-sensitive programs. Aisin Seiki and Yachiyo Industry represent established manufacturing depth in premium panoramic systems and sunroof mechanisms, with Aisin focused on OEM-facing integrated roof components and Yachiyo on specialized sunroof and related system production. Inteva Products and Johnan America, Inc. add further breadth in engineered roof systems and sunroof mechanisms, including subsidiary-linked Japanese manufacturing capability. Saint-Gobain Sekurit and Bosch GmbH extend the competitive picture into critical subcomponents, with Saint-Gobain Sekurit focused on advanced glazing systems for panoramic glass panels and Bosch producing panoramic sunroof actuators and full roof module systems.
Risks, Uncertainties, and Strategic Implications
The outlook remains favorable, but several uncertainties could alter the pace or shape of growth. Regulatory requirements will continue to evolve, and changes in safety glazing, pedestrian protection, or functional safety expectations could increase development costs or force redesigns on active programs. Macroeconomic conditions affecting vehicle production volumes, especially in price-sensitive segments, can influence component demand and pricing power. Material availability and the cost of specialized glass, interlayers, and electronic subsystems may create margin variability, particularly for suppliers with less diversified sourcing or limited scale.
There is also the risk that consumer preferences shift toward fixed panoramic designs in some applications if cost, durability, or reliability concerns outweigh the appeal of openable systems. In parallel, platform consolidation and OEM sourcing strategies could concentrate volume among a smaller set of suppliers, making it harder for smaller or less established players to maintain program wins. The strategic implication is clear: competitive advantage will increasingly depend on engineering versatility, compliance readiness, and the ability to deliver lighter, smarter systems that fit tightly constrained vehicle architectures.
Strategic Takeaways for Decision-Makers
For Manufacturers and Suppliers
Prioritize integration and weight reduction as core product development themes. Designs that consolidate sealing, actuation, and glazing functions while reducing mass are likely to align well with OEM priorities on efficiency and assembly practicality. Build explicit capability around regulatory and functional safety requirements, since these are becoming gate checks for program qualification rather than optional add-ons. Expand platform leverage where possible by standardizing core modules across multiple vehicle programs, which can improve cost position and reduce launch risk.
In parallel, monitor electric vehicle and SUV platforms closely. These segments are shaping demand for openable panoramic systems and experience-led features such as ambient lighting and switchable glazing. Suppliers that can demonstrate reliable integration in electrified architectures will be better positioned to capture the next wave of volume.
For Investors and Strategic Planners
Assess exposure to the full value chain, not just final assembly. Glazing, interlayer materials, actuators, and sealing technologies each carry different growth profiles and risk characteristics. Companies with diversified capabilities across multiple subcomponents may offer more resilient positioning than pure single-function players. Pay attention to the balance between consolidation and specialization: while the market is moderately concentrated, niche differentiation in lightweight materials or advanced glazing can still create competitive advantage.
Track program timing, platform cycles, and OEM sourcing shifts as leading indicators. Volume growth will be uneven across regions and vehicle types, and the mix between fixed and openable configurations will influence which supplier profiles benefit most.
For Procurement and OEM Strategy Teams
Treat panoramic roof sourcing as a system integration decision rather than a commodity purchase. Evaluate suppliers on total system performance, including sealing reliability, weight, electronic safety alignment, and support for future feature integration such as switchable glazing or ambient lighting. Where possible, clarify long-term platform requirements early to enable suppliers to optimize designs for cost, weight, and assembly efficiency.
Roof Windows Market
Balance cost objectives with resilience. Resilient multi-tier sourcing and clear quality expectations can reduce the risk of launch delays or compliance issues, particularly when specialized materials and electronic components are involved. A disciplined sourcing strategy can also create room to negotiate better total cost positions without sacrificing performance.
Looking Ahead
The panoramic sunroof market is entering a phase where growth is increasingly tied to engineering depth, regulatory readiness, and alignment with electrification and SUV trends. The sector is expanding toward the 4.75 billion USD range by 2032, but the value will be captured by companies that can deliver lighter, smarter, and more integrated roof systems while meeting rising safety and functional safety expectations. The combination of material innovation, experience-led features, and tighter integration points toward a market that rewards capability rather than scale alone.
For organizations operating in or around this space, the most valuable next step is to map the specific platform, regulatory, and sourcing implications that will shape individual programs and regional demand. Detailed segmentation, regional nuance, and company-level scenario analysis can sharpen execution plans and reveal where the most durable opportunities are forming. The full research report provides that deeper breakdown, including detailed segmentation data, regional dynamics, and tailored recommendations for procurement, product development, and investment planning.
PW Consulting Automotive & Machinery Research Center
For detailed analysis of this topic, please visit the official page: Panoramic Sunroof Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com