

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Silicone-Based Fouling Release Coatings Market: Why 6.8% CAGR Reshapes Strategy

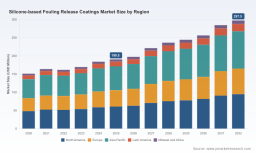
Strategic Trends and Commercial Opportunities in the Silicone-based Fouling Release Coatings Market
Market Landscape and Core Challenges
The global market for silicone-based fouling release coatings has entered a phase of steady expansion, driven by the maritime industry's evolving needs and regulatory pressures. From 2020 to 2025, the market demonstrated resilience despite fluctuations, growing from approximately 151.2 million USD to 190.5 million USD. This trajectory reflects a compound annual growth rate (CAGR) of 6.8% projected from 2026 through 2032, indicating sustained demand momentum. By 2032, the market is expected to surpass 297.5 million USD, signaling a maturing but still growing sector.
This growth is not uniform across all segments. The market exhibits moderate concentration, with the top three players holding 35.7% of the share and the top five capturing 48.2%. This structure suggests a competitive environment where established giants coexist with specialized players, creating room for strategic differentiation rather than pure price competition.
Despite the positive outlook, the industry faces critical challenges that could shape its future direction:
- Raw Material Volatility: The reliance on silicone raw materials makes the market susceptible to price swings driven by energy costs, logistics disruptions, and geopolitical tensions. Recent price revisions by major suppliers highlight the vulnerability of cost structures in this segment.
- Regulatory Compliance Complexity: Stricter environmental regulations, such as EU REACH and IMO conventions, mandate biocide-free formulations and organotin-free catalysts. While these regulations push innovation, they also increase formulation costs and require significant R&D investment to maintain performance standards without biocides.
- Performance vs. Cost Trade-offs: End-users, particularly ship operators, balance the long-term fuel savings from reduced fouling against the higher upfront costs of silicone-based coatings compared to traditional antifouling solutions. Demonstrating total cost of ownership benefits remains a key hurdle in broader adoption across all vessel types.
Key Drivers of Market Dynamics
Technological Innovation and Formulation Breakthroughs
Innovation in silicone chemistry is central to the market's evolution. Leading companies are developing advanced silicone elastomer systems that offer superior fouling release properties while adhering to biocide-free requirements. For instance, AkzoNobel's Intersleek series, including the 1100SR variant, exemplifies the focus on high-performance silicone systems that minimize drag and fuel consumption. Similarly, Hempel's Silic One and hydrogel-enhanced Hempasil systems represent efforts to combine silicone efficacy with enhanced surface properties for biocide-free hull protection.
These technological strides are not merely about replacing biocides; they are about improving durability and self-renewing capabilities. Jotun's SeaQuantum silicone elastomer coatings, designed for self-renewing hull performance, illustrate how formulators are tackling the challenge of coating longevity and consistent performance over multiple service intervals. Such innovations reduce the frequency of repainting, addressing a key concern for shipowners regarding maintenance downtime and lifecycle costs.
Regulatory Pressure as a Catalyst
Regulatory frameworks are acting as a powerful accelerator for silicone-based fouling release coatings. The International Convention on the Control of Harmful Antifouling Systems on Ships (IMO) mandates the use of biocide-free silicone fouling release coatings in sensitive ecological zones. With over 3,500 vessels restricted in 2024 under these provisions, the addressable market for compliant coatings is expanding. Furthermore, EU REACH regulations require organotin-free catalysts, pushing manufacturers to refine curing systems without compromising performance.
These regulations create a clear pull for silicone-based solutions, as traditional biocidal antifouling coatings face increasing restrictions. The shift is particularly pronounced in regions with stringent environmental enforcement, where compliance becomes a non-negotiable requirement for vessel operations. This regulatory tailwind is transforming silicone coatings from a niche premium option to a mainstream necessity in specific maritime segments.
Demand-Side Shifts Toward Sustainability and Efficiency
Ship operators and maritime companies are increasingly prioritizing fuel efficiency and carbon footprint reduction. Fouling release coatings directly contribute to these goals by reducing hydrodynamic drag, which lowers fuel consumption and emissions. As energy costs fluctuate and environmental, social, and governance (ESG) criteria gain weight in corporate decision-making, the economic and reputational benefits of silicone-based coatings become more compelling.
The demand is also being shaped by the expansion of sensitive ecological zones and port state control measures. Vessels operating in these areas must utilize compliant coatings, driving adoption among fleets that previously might have relied on conventional solutions. This demand-side pressure is reinforcing the market growth trajectory and encouraging investment in next-generation silicone formulations.
Supply Chain and Cost Structure Pressures
The cost structure of silicone-based fouling release coatings is undergoing significant stress due to upstream factors. Major silicone raw material producers have announced price increases, reflecting the impact of energy costs, logistics expenses, and raw material availability. Wacker Chemie AG, for example, implemented a price increase for all silicone-based products effective April 2026, citing disruptions in global supply chains related to energy, raw materials, and logistics. Similarly, Shin-Etsu Chemical Co., Ltd. revised selling prices for all silicone products by 10% or more starting May 2026, driven by sharply rising derived raw materials, energy, and logistics expenses.
These price revisions ripple through the value chain, affecting coating manufacturers' input costs and potentially impacting end-user pricing. The industry is navigating a period where cost escalation must be managed without eroding the value proposition of silicone coatings. This dynamic is prompting companies to optimize formulations, secure long-term supply agreements, and explore alternative sourcing strategies to mitigate volatility.
Competitive Landscape and Leading Strategies
The market is characterized by a mix of global coatings giants and specialized marine paint manufacturers, each pursuing distinct strategic positioning. AkzoNobel N.V., headquartered in Amsterdam, leverages its extensive marine coatings portfolio to offer Intersleek silicone elastomer foul release systems. Its strategy centers on integrating silicone technology into broader hull protection solutions, emphasizing performance data and fleet-wide efficiency gains. By tying silicone coatings to tie coats and complete systems, AkzoNobel aims to lock in customers through comprehensive service offerings.
PW Consulting
Hempel A/S, based in Copenhagen, differentiates through innovation in biocide-free systems. Its Silic One silicone-based foul release coating and Hempasil hydrogel-enhanced silicone systems target customers seeking advanced protection without biocides. Hempel's focus on hydrogel technology adds a layer of differentiation, potentially offering enhanced fouling release properties and durability, appealing to operators in ecologically sensitive regions.
PPG Industries, Inc., from Pittsburgh, provides SigmaWild and other silicone fouling release coatings as part of its biocide-free marine solutions. PPG's strength lies in its global reach and ability to scale innovation across diverse maritime markets. The company's strategy involves positioning silicone coatings within a wider suite of marine protection products, leveraging brand recognition and technical service networks to capture market share.
Jotun A/S, located in Asker, Norway, emphasizes self-renewing hull performance with its SeaQuantum silicone elastomer foul release coatings. Jotun's approach highlights the operational benefits of reduced maintenance frequency and consistent performance, resonating with shipowners focused on minimizing dry-docking intervals and maximizing vessel uptime.
Chugoku Marine Paints, Ltd., based in Osaka, markets the CMP BIOCLEAN series of advanced silicone foul release coatings for ocean-going vessels. As a regional player with strong ties to Asian maritime markets, Chugoku focuses on tailoring solutions to the specific operational profiles of vessels in the Pacific region, potentially offering competitive pricing and localized service support.
Sherwin-Williams Company, headquartered in Cleveland, supplies silicone-based foul release coatings under its marine and specialty coatings portfolio. Its strategy involves leveraging its vast distribution network and cross-selling opportunities across industrial and marine segments. Sherwin-Williams aims to integrate silicone coatings into broader coating solutions, appealing to customers seeking a single-source provider for multiple coating needs.
Pettit Marine Paint, located in Rockaway, New Jersey, provides silicone foul release coatings and systems for recreational and commercial marine applications. Pettit's niche focus allows it to cater to smaller vessel operators and recreational boaters, segments where ease of application and specialized customer service can be decisive factors.
The competitive landscape is evolving through consolidation and differentiation. While the top five players hold nearly half the market, the presence of specialized firms indicates opportunities for fragmentation in niche applications or regional markets. New entrants may find traction by focusing on specific vessel types, emerging regions, or novel formulation technologies that address unmet needs. However, the high barriers to entry posed by regulatory compliance, performance validation, and established supply chains favor incumbents with robust R&D and customer relationships.
Future Trends and Strategic Outlook
Accelerating Adoption Driven by Regulatory Expansion
Over the next three to five years, regulatory pressures are expected to intensify, further expanding the addressable market for biocide-free silicone fouling release coatings. As more regions implement stringent environmental protections and IMO regulations evolve, the number of vessels required to use compliant coatings will grow. This trend creates a clear opportunity for manufacturers to scale production and secure market share in advance of demand surges. However, companies must also anticipate potential regulatory fragmentation, where differing regional standards could complicate formulation strategies and market access.
Supply Chain Resilience and Cost Management as Competitive Differentiators
The recent wave of price increases from silicone raw material suppliers underscores the importance of supply chain resilience. Future market leaders will likely be those who can secure stable raw material supplies, optimize formulations to reduce silicone content without sacrificing performance, or develop partnerships that mitigate cost volatility. This trend may lead to strategic alliances between coating manufacturers and silicone producers, or inspire investment in alternative raw material sources. Businesses that fail to address cost structures risk margin erosion or loss of competitiveness in price-sensitive segments.
Silicone Resin Market
Performance Enhancements and Lifecycle Value Propositions
Innovation will continue to focus on enhancing the performance and lifecycle value of silicone coatings. Expect developments in multi-layer systems, improved adhesion promoters, and coatings that offer longer service life or easier application processes. The commercial opportunity lies in demonstrating total cost of ownership benefits that justify higher initial costs. Manufacturers that can provide robust data on fuel savings, reduced maintenance, and extended coating life will be better positioned to capture value. Conversely, a risk exists if performance claims are not consistently validated across diverse operating conditions, potentially leading to customer skepticism or reversion to traditional solutions where regulations permit.
Marine Anti-Fouling Coatings Market
Actionable Insights for Decision Makers
For Coating Manufacturers and Formulators
- Invest in Bio-based or Cost-Optimized Formulations: With raw material costs rising, exploring formulations that maintain performance while reducing dependency on high-cost silicone components can protect margins. R&D efforts should prioritize organotin-free curing systems and biocide-free architectures that comply with evolving regulations without compromising efficacy.
- Strengthen Supply Chain Partnerships: Engaging in long-term agreements with silicone suppliers or diversifying the supplier base can mitigate price volatility. Collaborative innovation with raw material producers may yield tailored solutions that address specific coating needs while stabilizing input costs.
- Expand Value-Added Services: Offering technical support, performance monitoring, and lifecycle cost analysis can differentiate offerings in a competitive market. Helping customers quantify fuel savings and maintenance reductions strengthens the value proposition and fosters loyalty.
For Investors and Financial Stakeholders
- Focus on Regulatory Tailwinds and Market Concentration: The market's moderate concentration and regulatory-driven growth present opportunities in companies with strong compliance capabilities and global reach. Evaluate players based on their R&D pipelines, regulatory responsiveness, and ability to scale silicone-based solutions across key maritime regions.
- Monitor Raw Material Dynamics Closely: Price revisions by major silicone producers can impact profitability across the value chain. Analyze how potential investments or portfolio companies manage input cost risks, as resilience in supply chain management will be a key determinant of long-term financial performance.
- Assess Niche and Regional Opportunities: While global giants dominate, specialized players serving recreational marine, specific vessel types, or emerging regions may offer high-growth potential. Look for companies with strong local relationships, tailored product lines, and the agility to adapt to regional regulatory changes.
For Shipowners and Procurement Teams
- Prioritize Total Cost of Ownership Assessments: When evaluating silicone-based fouling release coatings, look beyond initial price and consider fuel savings, reduced dry-docking frequency, and compliance benefits. Engage with manufacturers to obtain performance data relevant to your vessel types and operating profiles to make informed comparisons.
- Ensure Regulatory Compliance Proactively: Verify that selected coatings meet current and anticipated regulations in all operational zones, including sensitive ecological areas. Non-compliance can result in operational restrictions or penalties, making proactive selection of biocide-free and organotin-free solutions a strategic necessity.
- Leverage Supplier Expertise for Application Optimization: Proper application is critical to achieving the claimed performance of silicone coatings. Work closely with suppliers to ensure correct surface preparation, application conditions, and tie-coat usage. Investing in training or partnering with experienced applicators can maximize the return on coating investments.
The silicone-based fouling release coatings market is at a inflection point, shaped by regulatory mandates, technological advancements, and supply chain dynamics. Navigating this landscape requires a nuanced understanding of competitive strategies, cost structures, and emerging opportunities. Stakeholders seeking deeper granularity on segment-level data, regional breakdowns, and customized strategic scenarios are encouraged to explore comprehensive research resources that provide detailed market intelligence tailored to specific business needs.
For detailed analysis of this topic, please visit the official page: Silicone-based Fouling Release Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com