

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Acute Care Needleless Connector Market 1634M in 2026 Why Positive Displacement Shift Matters

Acute Care Needleless Connector Market: Strategic Trends and Commercial Opportunities Through 2032
The acute care needleless connector market represents a critical intersection of patient safety, clinical efficiency, and supply chain economics. As vascular access practices continue to evolve alongside growing emphasis on healthcare-associated infection prevention, the connector segment has transitioned from a commoditized consumable to a strategically differentiated product category. Understanding where the market stands today, what forces are reshaping it, and how competitive players are positioning themselves provides essential context for executives navigating procurement, product development, or capital allocation decisions.
Acupuncture Needles Market
Market Landscape and Core Challenges
The global acute care needleless connector market has demonstrated steady expansion over the past half-decade, reaching an estimated 1.55 billion USD in 2025, with trajectory modeling pointing toward approximately 2.29 billion USD by 2032. The compound annual growth rate across the 2026 to 2032 horizon sits at 5.83 percent, reflecting a market that is growing at a pace consistent with broader medical device consumables while benefiting from compounding clinical and operational tailwinds. Growth is not merely volume-driven; it reflects a structural shift in how acute care facilities approach vascular access, infection prevention, and supply standardization.
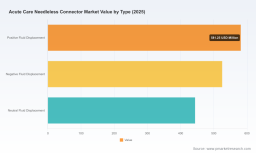
Geographically, the market remains heavily anchored in North America, followed by Europe and Asia Pacific, with Latin America and the Middle East and Africa representing smaller but steadily developing demand pools. Application-wise, hospital settings dominate consumption, reflecting the concentration of high-acuity patients, multilumen catheter use, and institutional pressure to standardize vascular access protocols. Clinics and ambulatory settings form a secondary demand base, while other care environments contribute incremental volume. Revenue distribution across product types shows a market increasingly aligned around fluid displacement performance, with positive and negative displacement configurations commanding the largest shares and neutral displacement gaining traction as clinical evidence around reflux control and microbial ingress prevention accumulates.
Key Challenges and Inflection Points
Despite the favorable growth backdrop, several structural challenges and decision points define the current market environment.
- Standardization versus clinical differentiation tension. Acute care procurement teams increasingly seek product standardization across departments to simplify training, reduce inventory complexity, and consolidate volume for contracting leverage. At the same time, clinical evidence is driving interest in differentiated connector performance around reflux characteristics, microbial ingress prevention, and occlusion management. Manufacturers must navigate the balance between offering clinically meaningful variation and meeting hospital demands for simplified formularies.
- Infection prevention accountability and total cost of care. Clinician awareness of catheter-related bloodstream infection risks has matured, but translating that awareness into purchasing behavior depends on how clearly connector performance associates with downstream outcomes and operating costs. Decision-makers are under pressure to justify product selection not just on unit price, but on risk reduction, flush frequency, thrombolytic use, and labor implications. This shifts the commercial battleground from specifications alone to demonstrated clinical and economic value.
- Pricing pressure amid supply chain normalization. After the volatility experienced in earlier years, supply chains have largely stabilized, and hospitals have regained bargaining leverage in group purchasing arrangements. This has intensified price scrutiny, particularly for commoditized connector SKUs. Suppliers that cannot articulate differentiated clinical value face margin compression, while those with evidence-backed positioning can defend premium pricing or secure longer contract cycles.
These challenges converge on a central question for the market: whether needleless connectors will continue to consolidate around a few clinically differentiated platforms, or whether buyers will privilege cost and standardization to the detriment of performance variation. The answer will shape competitive dynamics across the next several years.
Key Drivers Shaping Market Evolution
Clinical Evidence and Differentiation Around CLABSI Risk Management
One of the most consequential drivers in the market is the growing weight of clinical evidence connecting connector design to catheter-related bloodstream infection outcomes and treatment efficiency. Needleless connector performance is no longer evaluated only on ease of use or compatibility. Procurement and infection prevention teams are increasingly attentive to reflux behavior, microbial ingress prevention, occlusion risk, and downstream implications such as flush and thrombolytic consumption.
Recent regulatory labeling updates and peer-reviewed data have begun to crystallize these claims in ways that matter for purchasing decisions. For instance, clearances associated with neutral-displacement connector platforms have incorporated CMS study data indicating a measurable relative risk reduction in CLABSI within high-volume acute care hospitals, alongside claims related to pressure infusion performance and extended microbial ingress prevention windows. In parallel, independent systematic in vitro assessments of neutral displacement connectors have documented bidirectional fluid flow control with low reflux volumes, reinforcing the technical rationale behind neutral displacement as a clinically relevant parameter. These developments are not abstract; they directly inform formulary discussions where infection prevention metrics and nursing workflow matter.
Regulatory and Labeling Evolution as a Commercial Lever
The regulatory environment has evolved from a compliance floor into a commercial differentiator. FDA 510(k) labeling clearances are increasingly used to substantiate performance claims that support hospital adoption and value-based purchasing conversations. When labeling incorporates outcomes-linked evidence or functional claims such as pressure infusion capability and extended microbial ingress prevention, it offers clinicians and procurement teams a clearer basis for standardizing specific connector types across services.
This regulatory dynamic favors companies with established clinical data packages and regulatory execution capabilities. It also raises the bar for new entrants, since meaningful labeling claims require robust data generation and clear regulatory alignment. For incumbents, proactive labeling strategy can extend product lifecycle relevance and strengthen negotiating position in group purchasing discussions.
Demand-Side Shifts in Hospital Purchasing and Care Delivery
On the demand side, acute care facilities are optimizing vascular access programs to reduce variability, improve nurse efficiency, and manage total cost of care. HAIs remain a persistent concern, and connector selection is increasingly viewed as one component of a broader vascular access bundle rather than an isolated consumable decision. This mindset supports longer contract cycles for products that demonstrate consistent performance and compatibility within closed-system environments.
At the same time, labor constraints continue to influence consumable selection. Products that reduce flush frequency, minimize occlusion interventions, or simplify access routines can translate into meaningful workflow improvements. Evidence associating connector platforms with reduced thrombolytic use has gained commercial relevance because it ties device performance to drug cost savings and nursing time. These demand-side dynamics are nudging hospitals toward products with demonstrable operational benefits, especially in high-throughput acute care environments.
Supply Chain Maturation and Cost Structure Realignment
Supply chain stabilization has changed how both manufacturers and buyers think about cost. Earlier disruption-era urgency has given way to more disciplined contracting, inventory planning, and total cost evaluation. For manufacturers, this environment rewards scale, consistent quality, and strong GPO relationships. For buyers, it enables more deliberate evaluation of value over time rather than short-term price alone.
Worldwide Acute Care Electronic Health Recorder (EHR) Market
Cost structure considerations also affect OEM and precision-molded connector supply. Manufacturers that can combine design control, molding precision, and regulatory readiness are well positioned to serve global acute care suppliers seeking reliable sourcing. At the same time, any renewed cost pressure from raw materials, sterilization, or logistics could compress margins on undifferentiated products, reinforcing the trend toward value-based competition.
Competitive Landscape and Leading Strategies
The market is moderately concentrated, with the largest players commanding a meaningful share of global revenue while operating across different strategic positions. The competitive field includes broad-line medical device manufacturers with established acute care franchises, specialized connector companies with focused product platforms, and OEM suppliers that serve the broader supply chain through precision molding and custom engineering.
Strategic Positioning of Leading Players
Several companies illustrate distinct approaches to capturing value in this segment.
- ICU Medical has leveraged a comprehensive needlefree connector portfolio around neutral-displacement technology, with a notable emphasis on infection-control positioning. Recent labeling activity has strengthened claims associated with CLABSI risk reduction and microbial ingress prevention, and the company has paired regulatory progress with group purchasing access through multi-year contracts. This combination of evidence, labeling support, and purchasing channel access illustrates a strategy centered on clinical differentiation and institutional adoption.
- Becton, Dickinson and Company maintains a strong acute care presence with needle-free connector offerings positioned around reduced CLABSI and occlusion risk. Clinical data associating certain connector platforms with lower thrombolytic use has added an economic dimension to product positioning, helping frame the discussion around total cost of care rather than device unit price. This approach aligns with BD's broader strength in hospital supply ecosystems.
- B. Braun Medical offers connector platforms optimized around neutral displacement and anti-reflux performance within hospital IV therapy workflows. Its positioning reflects integration into broader infusion and vascular access portfolios, which can be advantageous for customers seeking workflow compatibility and standardized consumables across multiple device categories.
- Vygon S.A. continues to serve acute care vascular access needs with neutral displacement connector options, emphasizing compatibility and clinical usability within hospital settings. The company's strategy reflects steady penetration through product reliability and regional distribution strength.
- Nexus Medical illustrates a more focused approach, with neutral displacement connectors engineered for minimal reflux volume and acute care applications. Independent testing documenting low reflux ranges supports its technical positioning and offers a basis for differentiation in clinically sensitive environments.
- RyMed Technologies has emphasized enhanced infection control through antimicrobial-impregnated connector designs, targeting institutions looking for additional layers of protection beyond mechanical displacement characteristics. This illustrates a complementary differentiation path that emphasizes material and surface-level interventions.
- Terumo Corporation and Smiths Medical both participate through needle-free connector offerings tied to broader infusion and catheter systems, reinforcing the value of portfolio integration and closed-system compatibility in hospital purchasing.
- Baxter International Inc. maintains connector offerings within acute care IV therapy, benefiting from established relationships and system-level compatibility. Its presence reflects the importance of broad acute care distribution and clinical familiarity.
- CHI FENG Co., Ltd. operates in a different part of the value chain, providing OEM/ODM precision-molded neutral needle-free connectors for global acute care suppliers. This role highlights the strategic importance of manufacturing precision, scalability, and design support in serving larger branded participants.
- PuraCath Medical has entered the conversation with new connector technology cleared for vascular access in critical care, using IT-based approaches to reduce CLABSIs in acute care settings. New entrants with distinct technical mechanisms can reshuffle attention within the segment if clinical data and adoption pathways align.
How the Landscape Is Evolving
The competitive environment is shifting along several axes. First, evidence-based differentiation is becoming more central, and labeling advances are turning clinical claims into commercial assets. Second, purchasing consolidation is increasing the importance of group purchasing access and multi-year contract readiness, especially for products that can demonstrate infection prevention and workflow value. Third, there is an ongoing tension between portfolio breadth and focused specialization. Broad-line players benefit from system compatibility and supply relationships, while focused players can compete on specific performance characteristics and clinical storytelling. Fourth, new entrants with novel mechanisms, such as IT-enabled connector designs, introduce potential disruption if they can generate compelling evidence and secure adoption in high-acuity settings.
Overall, the market is moving toward a split between clinically validated platforms competing on outcomes and operational value, and cost-optimized SKUs competing primarily on price and standardization. The former are likely to capture more durable share in acute care settings where infection prevention and workflow efficiency carry real financial and clinical weight.
PW Consulting
Future Outlook and Emerging Opportunities
Clinical Evidence Will Become a Licensing and Adoption Asset
Over the next three to five years, clinical evidence is expected to play an even greater role in connector selection. As hospitals refine vascular access protocols and infection prevention programs, products with robust data packages and regulatory-supported labeling claims will have an advantage in formulary discussions and GPO negotiations. This creates opportunity for companies that can sustain data generation, translate results into procurement-friendly narratives, and align clinical claims with total cost of care arguments. It also raises the importance of post-market evidence and real-world consistency, since hospital adoption increasingly depends on demonstrated performance over time.
Neutral Displacement and Reflux Control Will Remain Strategic Parameters
Neutral displacement design, reflux control, and microbial ingress prevention will continue to be central technical parameters in acute care applications. Independent testing, systematic reviews, and labeling developments are reinforcing the relevance of these characteristics. Companies that can clearly communicate reflux behavior, compatibility, and workflow implications will be better positioned to compete in high-acuity environments where occlusion management and infection risk matter. This also creates opportunities for product development investment aimed at reducing reflux volume, improving pressure infusion capability, and strengthening microbial barrier claims without sacrificing usability.
Consolidation in Procurement and the Rise of Value-Based Selection
Hospital procurement is likely to continue consolidating around fewer connector choices within individual institutions, driven by standardization, training efficiency, and purchasing leverage. Within that constraint, value-based selection will become more important, meaning products that can show reduced thrombolytic use, lower occlusion intervention frequency, and meaningful infection prevention association will have stronger staying power. For manufacturers, this implies that price competition alone will be insufficient in many acute care accounts; commercial success will depend on aligning device performance with hospital cost and quality priorities. For investors, it suggests that the most durable growth stories will emerge from platforms with both evidence and purchasing channel access.
Potential Risks and Uncertainties
Several uncertainties could alter the trajectory of the market. If clinical evidence remains fragmented or difficult to compare across products, buyers may default to price and standardization, compressing differentiation value. If reimbursement and cost pressures intensify, hospitals may prioritize short-term savings over performance-based selection, particularly in margin-constrained settings. Supply chain disruptions, raw material volatility, or regulatory changes affecting labeling claims could also affect product positioning and margin profiles. Finally, new technology entrants must prove not only technical merit but also adoption feasibility within hospital workflows and purchasing structures, which can slow the impact of otherwise promising innovations.
Strategic Implications for Decision-Makers
For Manufacturers
- Invest in evidence generation and labeling strategy as core commercial capabilities, not just regulatory exercises. Clinical claims that link connector performance to CLABSI risk, occlusion, and drug use can shape formulary discussions when supported by regulatory clearances and peer-reviewed data.
- Balance portfolio breadth with focused technical differentiation. If products are positioned around neutral displacement and reflux control, make those performance characteristics measurable, credible, and easy for clinical and procurement teams to understand.
- Strengthen group purchasing relationships and multi-year contract readiness. In a consolidating procurement environment, access to contracted volume can matter as much as product quality for sustained share growth.
For Investors
- Prioritize platforms with both clinical evidence and purchasing channel access. Revenue growth in this segment is increasingly tied to institutional adoption, and adoption depends on demonstrated value plus contract presence.
- Track labeling and clearance activity as leading indicators of competitive positioning. Regulatory-supported claims can shift purchasing attention and create differentiation that persists beyond feature comparisons.
- Monitor new entrants with distinct mechanisms, but assess adoption feasibility carefully. Technical novelty alone does not guarantee acute care uptake; workflow compatibility, evidence strength, and commercial execution determine whether innovation translates into share.
For Procurement and Hospital Leadership
- Evaluate connector selection as part of a broader vascular access and infection prevention strategy, not solely as a consumable price decision. Total cost implications, including thrombolytic use, flush frequency, and occlusion management, can materially affect operating economics.
- Seek standardized formularies where clinically appropriate, but preserve room for evidence-backed differentiation in high-acuity settings. Not all use cases demand the same connector performance profile, and segmentation can improve both safety and cost efficiency.
- Ask suppliers for clear, comparable performance data on reflux behavior, microbial ingress prevention, occlusion risk, and compatibility within existing systems. Consistency of evidence and post-market performance should weigh heavily in long-term contracting decisions.
The acute care needleless connector market is entering a phase in which clinical evidence, regulatory-supported labeling, and value-based procurement will increasingly determine competitive outcomes. Companies and buyers that treat connector selection as a strategic lever for infection prevention, workflow efficiency, and total cost management will be better positioned than those competing only on unit price or feature lists. For decision-makers seeking detailed segmentation data, regional dynamics, contract structures, and customized commercial implications, the full research report provides a deeper operational view of the market and the specific pathways most relevant to individual business contexts.
For detailed analysis of this topic, please visit the official page: Acute Care Needleless Connector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com