

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Trailer Hitch Market 2026: Why 6.5% CAGR and North America's $96M Share Redefine Growth

Strategic Trends and Commercial Opportunities in the Global Trailer Hitch Market
The trailer hitch market has matured into a critical infrastructure component for vehicle towing ecosystems, linking consumer recreation, commercial logistics, and specialty transport applications. As of the 2025 baseline, the industry has reached a scale where incremental growth requires deliberate positioning rather than broad participation. Historical momentum from 2020 through 2025 reflects steady expansion, followed by a forecast trajectory through 2032 that points to continued, though uneven, advancement. The trajectory is supported by a compound annual growth rate of approximately 6.5 percent, with total market revenue measured in USD millions across all segments. This scaling is not merely a function of more vehicles on the road; it reflects structural shifts in how goods, leisure assets, and specialized equipment are moved across short and medium distances.
At the macro level, the market is characterized by concentrated leadership, with the top three players accounting for roughly 65 percent of revenue and the top five expanding that share to around 80 percent. Such concentration signals a landscape where incumbents have built durable advantages in distribution, engineering know-how, and brand trust. Yet concentration does not imply stagnation. The forecast window through 2032 suggests that pockets of rapid growth persist in specific applications and geographies, while the overall curve is tempered by cost pressures, regulatory scrutiny, and shifting vehicle architectures. For decision-makers, the central question is no longer whether the market is expanding, but where value will accrue when growth becomes more selective and when compliance costs rise alongside performance expectations.
Market Snapshot and Structural Pressures
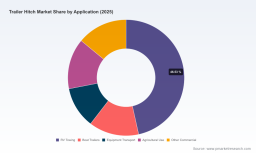
The revenue trajectory from 2020 to 2025 established a foundation that the 2026 to 2032 forecast builds upon, with the 2025 baseline serving as a pivot point for both planning and competitive investment. Growth has been broad-based enough to reward scale players, but not so uniform that every segment shares the same economics. Receiver hitches continue to anchor a large share of total revenue, reflecting their ubiquity across light and medium-duty towing. Alongside them, gooseneck, fifth wheel, weight distribution, and pintle configurations each command distinct niches tied to vehicle type, load profile, and regional towing culture. The application mix spans recreational towing, marine transport, equipment hauling, agricultural use, and other commercial activities, creating demand that is simultaneous but not homogeneous. This heterogeneity is a defining feature of the market: one product family must satisfy very different engineering tolerances, end-user expectations, and procurement cycles.
Three challenges now shape the industry’s near-term path. First, regulatory and safety scrutiny is intensifying, particularly around load security and component integrity. A notable example is the recall of more than 145,000 trailer hitch locks in 2025 due to a loose component that could allow loads to detach from towing vehicles, as documented in the NHTSA official recall notice from January 2025. Such events elevate customer sensitivity to failure modes and push manufacturers to tighten quality assurance, traceability, and design validation. Second, vehicle platform evolution is altering attachment points, electrical architectures, and clearance constraints, making vehicle-specific fit increasingly complex even as consumers and fleets expect seamless integration. Third, input cost volatility and supply chain dependencies continue to pressure margins, especially for stamped steel, castings, coatings, and electronic kits, while customers resist price increases that outpace perceived value. These forces are not independent; they interact to raise the bar on engineering rigor, process control, and go-to-market discipline.
Trailer Axle Market
Key Demand Drivers Reshaping the Market
Technology Innovation and Performance Benchmarks
Engineering differentiation has moved beyond basic load ratings to encompass integration, adjustability, corrosion resistance, and ease of installation. Manufacturers are investing in designs that reduce tongue weight transfer issues, improve maneuverability under load, and simplify accessory changes such as ball mounts and sway control. Hidden and low-profile hitch configurations, once niche considerations, are gaining relevance among passengers and commercial users who prioritize aesthetics and packaging without sacrificing functional capacity. Electrical integration, including lighting and sensing kits in OEM-quality grades, is becoming a meaningful point of value creation, especially where trailer detection, braking coordination, and vehicle electronics must work in concert. These advances do more than raise performance; they create defensible product lines that can command premium positioning and reduce substitution risk when installed correctly and supported by clear documentation.
The practical implication is that performance claims require substantiation. Products that deliver measurable improvements in towing stability, installation time, or long-term durability are better positioned to win in channels where technicians and knowledgeable buyers compare alternatives directly. Conversely, commoditized SKUs face greater pressure to compete on price alone, which can erode margins and brand equity over time. Innovation that reduces field failures and simplifies the fit process tends to generate the strongest combination of customer satisfaction and repeat demand.
Policy, Regulation, and Safety Expectations
Regulatory attention is raising the cost of nonconformance and the value of preemptive quality systems. The 2025 lock recall illustrates how a single component vulnerability can ripple through distribution networks, service channels, and consumer confidence. Beyond recalls, manufacturers must navigate evolving standards for load ratings, labeling, towing safety communications, and electrical compatibility. In Europe, OEM-quality expectations and homologation requirements often shape product specifications at the design stage, while North American channels emphasize vehicle-specific fit, installation support, and dealer education. In both contexts, compliance is shifting from a back-office function to a front-line competitive factor.
For strategy, this means quality planning and design validation are no longer optional cost centers. Companies that embed traceability, durability testing, and field monitoring into product development reduce the probability of costly corrective actions and build trust with downstream partners. Clear communication about specifications, installation requirements, and load limits also protects brand reputation and reduces misuse-related claims. In markets where safety perception influences purchasing, a track record of reliable components can support premium pricing and improve channel willingness to stock and promote a product line.
Demand-Side Behavior and Use-Case Expansion
Demand patterns are shaped by recreational towing, marine transport, equipment hauling, agricultural work, and other commercial applications, each with distinct purchasing triggers. Recreational towing drives volume through seasonal purchasing, accessory add-ons, and upgrades tied to vehicle changes. Marine and equipment transport prioritize reliability and quick attachment, often under time pressure and in demanding environments. Agricultural and specialty commercial use tends to value durability, serviceability, and compatibility with existing equipment more than appearance or low profile. These divergent priorities mean that a single product architecture rarely satisfies all segments equally, and successful portfolios are those that align features with real use-case constraints.
Behavioral shifts also matter. Buyers increasingly expect vehicle-specific solutions, clear installation guidance, and accessories that reduce friction during setup. As towing becomes more connected to broader vehicle electronics and active safety features, end users and commercial operators look for components that integrate cleanly rather than simply bolt on. In this environment, education and support become part of the product experience, influencing both initial purchase and long-term loyalty. Companies that provide precise fit information, installation clarity, and accessory ecosystems tend to convert interest into sales more efficiently than those relying on broad compatibility claims alone.
Supply Chain and Cost Structure Dynamics
Cost structure is being reshaped by material inputs, manufacturing footprints, and logistics dependencies. Steel pricing, coatings, casting capacity, and electronic content all influence the cost base for hitch assemblies and associated kits. At the same time, regional sourcing decisions affect lead times, tariff exposure, and responsiveness to local demand patterns. The result is a market where efficient operations and disciplined inventory management can create meaningful margin advantages, while brittle supply chains expose producers to stock-outs and price instability.
The commercial opportunity lies in designing for manufacturability and serviceability without sacrificing performance. Standardizing high-volume components where possible, coordinating material procurement with rolling demand plans, and reducing assembly complexity can improve throughput and lower unit cost. Equally important is aligning production location decisions with channel realities, since regional preferences for OEM-quality content, dealer support, and after-sales service can differ substantially. Companies that balance scale with flexibility tend to navigate cost volatility more effectively than those locked into rigid cost structures.
Competitive Landscape and Evolving Positioning
Incumbent Strengths and Differentiation Vectors
The market features a mix of established North American manufacturers and European suppliers with strong OEM relationships and engineering heritage. CURT Manufacturing operates with a focus on USA-made, vehicle-specific fit for both OEM and aftermarket contexts, spanning receiver, fifth wheel, and gooseneck offerings alongside a full towing product set. Draw-Tite emphasizes custom designs and hidden hitch options distributed through dealer networks, a model that rewards channel relationships and installation readiness. Reese Products is known for heavy-duty receiver and towing systems that span light to heavy applications, appealing to users who prioritize capacity and ruggedness. B&W Trailer Hitches brings American-made engineering to gooseneck and fifth wheel categories, with attention to ball mount adjustability and weight distribution systems. Blue Ox addresses towing solutions such as tow bars, baseplates, sway control, and fifth wheel hitches, aligning closely with specialty towing requirements.
European suppliers add a distinct dimension. MVG focuses on towbars and electrical kits delivered in OEM-quality grades, which supports integration into vehicle platforms where fit and finish are tightly controlled. ACPS Automotive, operating under the ORIS name, produces disappearing hitches for passenger cars, SUVs, and vans, targeting end users who value aesthetics and integrated packaging. Bosch contributes towbars and hitch components, leveraging broader automotive component credibility and engineering scale. On the consolidation side, Horizon Global Corporation manages multiple brands including Draw-Tite, REESE, Bulldog, and Fulton, enabling portfolio breadth and cross-brand distribution leverage. RANDYS Worldwide offers adjustable hitch products and continues to expand its towing solution set, including a 2025 acquisition of BulletProof Hitches aimed at broadening accessories and towing capabilities.
Integration, Differentiation, and Channel Dynamics
The competitive landscape is evolving through a blend of consolidation, portfolio extension, and niche specialization. Larger multi-brand operators can use shared engineering, procurement, and distribution to capture efficiencies while maintaining distinct brand identities for different customer segments. This structure allows them to address a wide range of vehicle types and use cases without forcing every product into a single brand narrative. At the same time, specialist manufacturers maintain advantage by deepening vehicle-specific fit, heavy-duty capacity, or OEM-quality integration, which can be difficult for broader portfolios to replicate at equal fidelity.
Channel strategy remains decisive. Dealer networks, specialty retailers, and online distribution each impose different expectations for packaging, fit information, inventory depth, and support materials. In dealer-led channels, installation readiness and technician trust often determine repeat business. In direct and e-commerce channels, clear specifications, compatibility tools, and accessory bundles influence conversion. Companies that align product design with channel realities, rather than forcing the same offering through every route, tend to achieve stronger sell-through and fewer returns. The market also rewards brands that can communicate load ratings, compatibility, and safety guidance with precision, since uncertainty at point of purchase frequently becomes friction in the sales process.
A practical development to monitor is the ongoing M&A activity that broadens accessory and towing solution portfolios. RANDYS Worldwide’s acquisition of BulletProof Hitches in April 2025 signals a continued push to assemble more complete towing ecosystems rather than competing on the hitch assembly alone. This trend suggests that future competition will increasingly be evaluated across the full set of accessories, mounting hardware, electrical kits, and support content that surround the primary hitch, making ecosystem completeness a strategic asset.
Forward-Looking Trends and Linked Opportunities
Trend One: Integration as a Baseline Expectation
Over the next three to five years, hitch products are likely to be judged not only by load capacity but by how cleanly they integrate with vehicle architecture, electrical systems, and accessory ecosystems. This trend favors designs that simplify installation, reduce ambiguity in fitment, and support compatible lighting, braking, and sensing components. The commercial opportunity is in building product lines where the hitch is the anchor for a coherent solution rather than an isolated component. Manufacturers that invest in compatibility tooling, installer guidance, and accessory coordination can capture higher ensemble value and reduce substitution risk. The risk is that integration expectations rise faster than product development cycles can accommodate, especially as vehicle platforms change and electrical architectures become more complex. Companies that treat integration as a continuous capability, supported by close coordination with vehicle data and field feedback, will be better positioned to stay current.
Trend Two: Safety and Compliance as Competitive Levers
Safety scrutiny is expected to persist as a defining influence on product design, marketing claims, and distribution standards. Recalls and field failures draw attention to load security, component integrity, and installation correctness, which in turn raises the value of robust testing, clear labeling, and traceable manufacturing. The opportunity is to convert compliance discipline into a market advantage by offering products with verifiable durability, straightforward installation, and transparent specifications. Buyers and channel partners increasingly prefer brands that reduce uncertainty, and that preference can translate into stickier relationships and more resilient pricing. The uncertainty lies in the possibility of more stringent requirements or enforcement actions that raise the cost of conformity across the sector, compressing margins for players without efficient quality systems. Firms that build quality into the process rather than inspecting it at the end will absorb regulatory shifts more effectively.
Trend Three: Portfolio Breadth and Ecosystem Completion
A third trend is the movement toward broader towing and accessory portfolios that address the full task of towing rather than a single hardware item. This is visible in acquisitions and multi-brand structures that assemble receiver solutions, weight distribution systems, gooseneck and fifth wheel options, hidden designs, and electrical kits under coordinated strategies. The opportunity is to capture more wallet share by offering compatible accessories, replacement parts, and service content that accompany the primary hitch. Complete ecosystems also support installation confidence and reduce the likelihood of mismatched components, which improves customer outcomes and reduces returns. The risk is complexity: broader portfolios require disciplined product rationalization, consistent quality across brands, and clear positioning so that customers can navigate choices without confusion. Organizations that scale portfolios while preserving clarity in fit, function, and support are more likely to convert breadth into durable advantage.
PW Consulting Automotive & Machinery Research Center
Strategic Implications for Decision-Makers
For Manufacturers
Product differentiation should be anchored in fit precision, integration quality, and verified durability rather than in broad claims of capacity. Prioritize engineering that reduces installation ambiguity and supports accessory compatibility, since these factors directly influence field performance and channel confidence. Invest in the quality systems and traceability needed to manage safety scrutiny, because recalls and field issues can quickly erode brand trust and create costly corrective cycles. Where scale allows, pursue portfolio breadth with disciplined rationalization, ensuring that each addition serves a clear use case and does not dilute positioning. Align manufacturing and sourcing decisions with channel and regional expectations, since OEM-quality content, dealer support, and service models differ meaningfully across markets.
Hitch Lock Market
For Investors
Evaluate exposure not just by top-line growth but by the defensibility of product architecture, channel relationships, and quality track record. Companies with vehicle-specific fit capabilities, strong integration content, and credible safety performance are better positioned to sustain margins as scrutiny rises. Consolidation that expands accessory and solution breadth can create value if it improves ecosystem completeness without introducing quality or brand confusion. Monitor regulatory signals closely, since changes in recall dynamics, labeling expectations, or towing safety standards can alter cost structures and competitive positioning. In portfolio construction, favor businesses that combine scale in high-volume categories with specialization where performance demands justify premium positioning.
For Procurement and Channel Partners
Source decisions should weigh total cost of reliable installation and support, not price alone. Verify vehicle-specific compatibility, load rating clarity, and accessory compatibility before committing to volume, since mismatched components create service friction and end-user dissatisfaction. Prefer suppliers that provide clear installation guidance, consistent specification communication, and responsive support, because these factors reduce returns and improve sell-through. Balance breadth and depth in inventory by focusing on high-velocity fitments and safety-critical components, while keeping access to specialized configurations for commercial and specialty applications. Where possible, request documentation that supports traceability and quality assurance, especially for components that influence load security.
Closing Perspective
The trailer hitch market is moving from broad expansion to a more selective phase where value accrues to those who combine engineering rigor, integration capability, and disciplined execution. The market’s scale and concentration indicate that leadership positions are durable, but they are not immune to reassessment when safety expectations rise, vehicle architectures change, and cost pressures intensify. The forward opportunity lies in aligning product design with real use cases, building ecosystems that reduce installation and compatibility friction, and treating quality and traceability as strategic assets rather than overhead.
For organizations seeking to act on these dynamics with finer granularity, the most useful next step is to examine detailed segmentation, regional demand patterns, and company-specific profiles that sit beyond the overview picture. A complete research report can provide the segmented data and context needed to shape product roadmaps, channel plans, and investment theses with greater precision. The strategic direction is clear: in a market where safety, fit, and integration increasingly define competitive standing, timely intelligence is not optional for decision-makers who want to move with confidence.
For detailed analysis of this topic, please visit the official page: Trailer Hitch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com