

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Medical Rubber Stoppers Market: Why Butyl Dominance and 5.5% CAGR Reshape Strategy

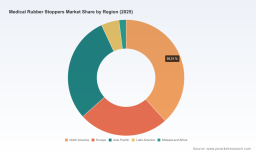
Strategic Trends and Commercial Opportunities in the Medical Rubber Stoppers Market
The medical rubber stoppers market stands at the intersection of pharmaceutical innovation and packaging reliability, serving as a critical component in the safe delivery of injectable drugs, biologics, and vaccines. Over the past five years, the market has progressed from a stable $900 million baseline in 2020 to an estimated $1.15 billion in 2025, reflecting consistent demand growth, expanded biopharmaceutical pipelines, and tightening quality expectations across global supply chains. Looking ahead through 2032, the market is projected to reach approximately $1.66 billion, extrapolating to a compound annual growth rate of 5.5 percent. This trajectory signals more than incremental expansion; it points to structural shifts in how elastomeric closures are specified, validated, manufactured, and integrated into drug packaging systems. For executives and investors navigating healthcare packaging, understanding what is driving this growth, where competitive advantages are being built, and how the regulatory and supply chain environment is evolving is essential for positioning portfolios and capital allocation effectively.
Market Snapshot and Structural Challenges
The medical rubber stoppers market today operates within a highly specialized segment of pharmaceutical packaging where performance, sterility, and compatibility are non-negotiable. Revenue growth over the historical period has been supported by rising volumes in injectable therapies, increased adoption of ready-to-use closure formats, and steady expansion in regions with growing centralized pharmacy operations and biotech manufacturing. The forecast period through 2032 suggests continued expansion, with growth rates that reflect both volume increases and higher value capture around premium, low-extractable, and pre-sterilized solutions. In a market of this kind, size alone does not explain competitive outcomes. The real story is in the concentration of capability, the pace of regulatory change, and the way demand-side requirements are reshaping product architectures.
Several structural challenges define the current inflection point for the industry. First, the cost environment for petroleum-derived feedstocks has introduced volatility into the production economics of butyl and bromobutyl rubber stoppers. During 2024, roughly 43 percent of manufacturers reported increased raw material costs driven by feedstock price swings, pressuring margins and complicating long-term pricing agreements. Second, regulatory expectations around extractables, leachables, compatibility, and sterilization are tightening at a pace that raises both technical and financial barriers. Updated guidance from the U.S. Food and Drug Administration in July 2024 on container closure systems underscored the need for manufacturers to document compatibility and perform container closure integrity testing, particularly for glass vials and stoppers. At the same time, the transition of USP Chapter 381 for elastomeric closures to new chapters 1381 and 1382, with a final implementation date of December 1, 2025, imposes updated testing requirements for functionality, extractables, and leachables. These shifts are not marginal; they change how products are validated, how documentation is maintained, and how quickly new formats can be qualified for clinical and commercial use.
Third, the market is experiencing an uncompromising demand for biological safety and sterility assurance. Biological evaluation of medical rubber stoppers must comply with ISO 10993 standards, and more than 58 percent of pharmaceutical packaging manufacturers cited increased validation and sterilization compliance expenses in 2024. Compliance costs are now a meaningful part of product economics and a differentiator in supplier selection. Taken together, these challenges reshape the playing field: suppliers that can deliver lower-extractable profiles, validated ready-to-use formats, and predictable cost structures gain disproportionate traction, while those relying on legacy designs and ad hoc compliance approaches face growing risk of displacement.
Key Drivers Propelling Market Change
The market’s trajectory is not simply a function of volume growth. It is being reshaped by overlapping forces that alter product requirements, customer expectations, and the economics of production. Three to four core drivers explain why the sector is evolving now and why the next several years will reward companies that align technology, regulatory readiness, and supply chain resilience.
Technology Innovation and Low-Extractable, Ready-to-Use Formats
Technological progress in elastomeric closure design is one of the most visible drivers. The shift toward low-extractable, ready-to-use stoppers addresses a long-standing requirement in injectable and biologic drug packaging: minimizing interaction between the closure and the drug product over extended shelf life. Recent product introductions illustrate this direction. Datwyler introduced Omniflex ready-to-use low-extractable stoppers targeted at long-shelf-life mRNA and monoclonal antibody applications. West Pharmaceutical Services expanded its NovaPure line with enhanced barrier properties for mRNA and biologic therapies. These developments are not incremental marketing moves; they respond to real formulation and stability needs in advanced therapies where closure integrity, extractables control, and sterilization readiness directly affect product viability. The commercial message is clear: premium, performance-led stopper designs are becoming the default choice for high-value biologics and mRNA platforms, and suppliers that can validate such formats at scale are moving up the value chain.
Policy, Regulatory Evolution, and Validation Intensity
Regulatory dynamics are accelerating the market’s shift toward standardized, well-documented, and rigorously tested closure solutions. The FDA’s July 2024 guidance on container closure system and component changes emphasizes compatibility documentation and container closure integrity testing for glass vials and stoppers. Simultaneously, the reorganization of USP elastomeric closure chapters, with final implementation by December 1, 2025, re-sets testing expectations for functionality, extractables, and leachables. For manufacturers and buyers alike, this environment increases the importance of pre-validated formats, traceable material specifications, and robust testing data. The burden is not only technical; it is operational. Suppliers must manage validation timelines, maintain documentation across product changes, and ensure that closures meet changing expectations without disrupting client onboarding. In practice, this favors suppliers with mature quality systems, broad test capabilities, and established relationships with pharmaceutical and biotech customers who value continuity and reduced qualification risk.
Butyl Rubber Market
Demand-Side Shifts in Biologics, Hospital Pharmacy, and Chronic Care
Demand is being shaped by the changing mix of drug therapies and the settings in which they are administered. The continued expansion of biologics, monoclonal antibodies, and mRNA-based products increases the need for closures that maintain stability and integrity over longer storage periods and in diverse climate conditions. At the same time, hospital pharmacy settings remain a significant demand center for sterile rubber stoppers used in injectable drugs and vaccines. Sterile stoppers used in these settings benefit from included reimbursement under existing DRG codes for parenteral therapies, with hospitals accounting for a substantial share of end-user demand. This reimbursement linkage matters because it stabilizes demand for sterile, high-compliance closures and creates a persistent pull for validated, hospital-ready products. The broader implication is that demand growth is not uniform across all closure types; it is concentrated where therapy complexity, sterility requirements, and reimbursement dynamics converge.
Supply Chain Cost Structures and Raw Material Dynamics
Beyond product and regulatory drivers, the supply chain environment is influencing competitiveness. Feedstock volatility for butyl and bromobutyl rubber has become a defining cost theme, affecting pricing stability and forcing manufacturers to manage input risk more actively. The impact is twofold. First, cost variability can compress margins unless suppliers have hedging strategies, flexible sourcing, or product mixes that balance higher-margin premium lines with volume-oriented formats. Second, cost pressures can accelerate regional sourcing decisions as buyers seek predictability, shorter lead times, and closer technical collaboration. Suppliers with scale, diversified feedstock strategies, and transparent cost management are better positioned to maintain commercial stability. In this respect, the market is rewarding operational discipline as much as product technology.
Competitive Landscape and Leading Strategies
The competitive field combines global elastomeric specialists, established pharmaceutical packaging groups, and high-capacity regional manufacturers. This mix creates a market where differentiation comes from product architecture, validation readiness, scale, and customer intimacy rather than commodity pricing alone. The market is also concentrated: the top three firms account for approximately 65 percent of revenue, and the top five reach around 72 percent. Such concentration indicates that scale, technology leadership, and long-term customer relationships are decisive in capturing premium segments.
Divergent Strategic Positions Among Leading Players
Leading companies are pursuing distinct strategic positions that reflect their capabilities and target segments. West Pharmaceutical Services focuses on premium elastomeric closures, including NovaPure and LyoTec ready-to-sterilize stoppers for injectable and lyophilized drug vials, and has expanded its NovaPure line with enhanced barrier properties for mRNA and biologic therapies. This positions West around reliability, advanced barrier performance, and compatibility with high-value drug programs. Datwyler Holding AG emphasizes high-quality butyl rubber stoppers and ready-to-use formats such as Omniflex for pharmaceutical and biotech packaging, recently introducing low-extractable stoppers for long-shelf-life mRNA and monoclonal antibody applications. Datwyler’s posture reflects a strategy centered on readiness, extractables control, and bioprocessing alignment.
In the capacity and scale segment, Hebei First Rubber Medical Technology manufactures medical-grade butyl and bromobutyl rubber stoppers with annual capacity of 10 billion units and supplies more than 40 countries with FDA and ISO certifications. Its participation in INTERPHEX USA in 2025 to promote bromobutyl rubber stoppers and related pharmaceutical packaging illustrates a strategy of combining scale, certification breadth, and active engagement with global buyers. Jiangsu Best New Medical Materials produces medical-grade grey rubber stoppers and plugs for pharmaceutical vials and infusion applications, adding further capacity and product variety in the regional supply base. On the diversified packaging side, AptarGroup offers elastomeric closures and related stoppers for drug delivery and pharmaceutical packaging, while Saint-Gobain Performance Plastics supplies medical and pharmaceutical elastomeric components including stoppers for healthcare applications. These firms extend the competitive field by leveraging broader packaging platforms and cross-segment capabilities. Japanese participants such as Sumitomo Rubber Industries and Nipro Corporation add a regional dimension: Sumitomo invested in a new R&D production line for advanced pharmaceutical rubber stoppers, signaling a commitment to technology and capacity for Asian and global biotech packaging needs, while Nipro offers rubber stoppers and related closures for injectable drug packaging and medical devices.
Market Evolution: Consolidation, Differentiation, and New Entrants
The competitive landscape is evolving along three axes. Consolidation remains a plausible path as larger players seek to strengthen scale, broaden product portfolios, and reduce customer switching risk through integrated offerings. Differentiation is intensifying around low-extractable, ready-to-use formats, faster qualification cycles, and compliance documentation, where the winners are those that can reduce time-to-market for drug manufacturers. New entrants and regional capacity expansions continue to challenge incumbents on cost and supply flexibility, particularly where certifications, volume capacity, and international distribution networks are in place. The likely outcome is a layered market: premium, technology-led suppliers capture high-margin biologic and mRNA programs; scale-oriented manufacturers win on volume, cost, and multi-country supply; and diversified packaging groups leverage platform breadth to serve multi-component packaging needs. Companies that can operate across more than one layer, or that can anchor a strong position in a specific high-value layer, will be best positioned to sustain growth.
Forward-Looking Scenarios and Commercial Opportunities
The next three to five years will likely be defined by three interrelated trends that translate directly into commercial opportunities for suppliers, buyers, and investors who can act on them early.
Acrylic Rubber Market
The first trend is the acceleration of low-extractable, ready-to-use closures as a standard expectation rather than a premium option. As mRNA platforms, monoclonal antibodies, and other biologics continue to expand, drug manufacturers will increasingly require closures that minimize interaction, support longer shelf life, and integrate seamlessly into sterile workflows. The opportunity lies in building validated formats that reduce qualification friction, shorten onboarding timelines, and provide documented compatibility and integrity data. Suppliers that can demonstrate repeatable performance across multiple therapy classes will be better positioned to secure long-term supply agreements.
The second trend is the deepening influence of regulatory and standards-driven compliance on sourcing decisions. With FDA guidance reinforcing container closure integrity documentation and USP chapters re-establishing testing expectations for elastomeric closures, buyers will place greater weight on suppliers’ validation records, test capabilities, and change control maturity. This creates a commercial opening for suppliers that can package compliance as a value proposition: faster qualification, comprehensive documentation, and lower risk of disruption during component changes. At the same time, the trend introduces risk for suppliers that rely on loosely documented processes or that underestimate the cost and time required to maintain alignment with evolving requirements.
The third trend is a more deliberate approach to cost and supply resilience, shaped by feedstock volatility and the need for predictable economics. Manufacturers and buyers will likely favor sourcing strategies that reduce exposure to raw material swings, balance multi-region supply where appropriate, and align product mix with margin realities. For suppliers, the opportunity is to combine cost discipline with technology value, offering transparent pricing mechanisms, flexible capacity, and a portfolio that spans both volume-oriented and premium formats. For investors, the signal is that competitive advantage will accrue to operators that can manage input volatility without sacrificing compliance or quality, especially in an environment where downstream demand remains robust.
These trends carry uncertainty. Regulatory timelines and interpretation can shift, particularly as chapters are implemented and guidance is applied in practice. Feedstock prices may move in ways that challenge margin assumptions. Demand for specific therapy platforms can change with clinical outcomes and reimbursement evolution. The commercial response should therefore be to build flexibility into product planning, maintain strong compliance capabilities, and avoid over-indexing on any single therapy or region. Opportunities will favor those who can adapt quickly while keeping quality and documentation intact.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product development with the direction of therapy and compliance evolution. Invest in low-extractable, ready-to-use formats that can be validated for biologics and mRNA applications, and ensure that documentation, testing, and change control systems are robust enough to meet FDA and USP expectations without protracted qualification cycles. Build feedstock risk management into commercial planning through diversification, hedging where feasible, and product mix strategies that protect margins. Where scale matters, use capacity and certification breadth to serve multi-country demand, but do so without compromising the performance profile that premium segments require. Balance volume and value by clearly segmenting the portfolio and assigning the right resources to each layer.
For investors, the market offers exposure to a sector with steady growth, clear differentiation potential, and rising barriers to entry around compliance and validation. The most promising targets are companies with demonstrated capability in low-extractable and ready-to-use formats, strong quality and documentation systems, and a credible strategy for managing raw material volatility. Evaluate customer concentration, certification breadth, and the ability to support faster qualification as part of any investment thesis. Watch for consolidation signals, regional capacity expansion with international certifications, and R&D investments that expand the performance envelope of closures. In this market, the durability of competitive advantage is closely tied to compliance readiness and the ability to reduce risk for drug manufacturers.
PW Consulting
For procurement and sourcing teams, the emphasis should be on qualification efficiency, supply resilience, and total cost of ownership rather than unit price alone. Prioritize suppliers that can provide validated, low-extractable, ready-to-use options with clear compatibility and integrity documentation, especially for injectable and biologic programs. Assess the supplier’s ability to manage feedstock-driven cost changes transparently and to sustain supply continuity across regions and demand cycles. Where hospital pharmacy demand and reimbursement linkages matter, ensure that the selected closures meet the sterility and compliance expectations that support parenteral therapy delivery. A balanced sourcing strategy that includes both premium-performance suppliers and capable scale providers can reduce risk while preserving flexibility.
The strategic picture is clear: the medical rubber stoppers market is moving toward higher performance expectations, more rigorous compliance, and greater emphasis on supply predictability. Navigating this environment requires detailed, segment-level data on product types, applications, regional demand patterns, pricing dynamics, and supplier capabilities. For decision makers seeking to translate these trends into sourcing choices, portfolio plans, or investment theses, a comprehensive report with granular segmentation and customized scenarios can sharpen the direction and reduce uncertainty. Access to that level of detail is the difference between reacting to change and shaping it.
For detailed analysis of this topic, please visit the official page: Medical Rubber Stoppers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com