

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
UV LEDs Market at 11.9% CAGR: Why Asia Pacific and UV Curing Are Redefining Growth

Strategic Shifts and Commercial Opportunities in the UV LEDs Market
The ultraviolet LED sector has moved from a specialized component niche to a critical enabler of industrial, environmental, and healthcare infrastructure. Between 2020 and 2025, the global UV LEDs market expanded from $700.0 million to $1,230.0 million, reflecting a compound annual growth rate of 11.9% that extends through the forecast horizon to 2032. By the close of the projection period, revenue trajectories point toward $2,694.0 million, signaling a market that has crossed the threshold from incremental adoption to structural expansion. This growth trajectory is not merely a reflection of incremental efficiency gains; it captures a broader transition in how industries approach disinfection, curing, and environmental control as regulatory, technological, and supply chain conditions reshape competitive dynamics.
The market’s expansion has been uneven, shaped by material bottlenecks, geopolitical trade controls, and the uneven pace of certification and standardization across end-use sectors. While the headline numbers indicate robust demand absorption, the underlying mechanics reveal a landscape where competitive advantage increasingly depends on manufacturing scale, substrate availability, and the ability to align product development with regulatory timelines. Understanding these mechanics is essential for executives evaluating capital allocation, supply chain strategy, and product roadmap decisions.
Market Landscape and the Structural Challenges Shaping Growth
The UV LEDs market’s progression from $700.0 million in 2020 to $1,230.0 million in 2025 underscores a sustained demand pull, but the growth path has not been frictionless. The compounding rate of 11.9% masks underlying volatility in input costs, substrate constraints, and the uneven deployment of certified systems across regions and applications. The market remains moderately concentrated, with the top three firms holding a 24.6% share and the top five reaching 52.0%, a structure that reflects both the technical barriers to entry and the persistent fragmentation across wavelength-specific applications.
UV Lasers Market
Substrate Constraints and Per-Unit Economics
A persistent bottleneck lies in large-diameter aluminum nitride substrates, which remain limited to 3 inches or smaller. This constraint directly affects UV-C LED production economics by increasing per-unit costs and limiting wafer-scale yield improvements. For manufacturers, the implication is clear: scaling volume alone does not automatically translate into margin expansion when substrate supply restricts throughput and forces reliance on smaller-batch processing. Companies that can secure consistent substrate access or develop alternative packaging and yield-management strategies are better positioned to maintain cost competitiveness as demand intensifies.
Geopoliticized Material Supply Chains
Raw material access has become a strategic variable rather than a background procurement issue. China’s gallium and germanium export controls, implemented in August 2023 and tightened through 2025, restrict gallium nitride materials essential for UV LED substrates and chips. Licensing requirements and end-user restrictions targeting the United States have created parallel pressure on Asian producers reliant on Chinese materials, while U.S. export controls on gallium-related items have increased supply chain risk across the manufacturing ecosystem. In practical terms, this translates into longer qualification cycles, inventory hedging, and a growing premium on supply chain diversification and regional sourcing strategies.
Labor Intensity and Process Complexity
The market’s growth trajectory is also shaped by rising manufacturing complexity. UV LED manufacturing labor costs have risen by 10-12% annually in 2025 as a result of skilled semiconductor process requirements. This increase is not simply an inflationary headwind; it reflects the technical demands of wavelength precision, packaging reliability, and performance validation. Organizations that treat labor as a variable cost rather than a capability constraint risk underinvesting in process engineering, automation, and workforce development, which can erode competitiveness even as demand expands.
Core Drivers Accelerating Market Expansion
The market’s growth is being propelled by several reinforcing forces that extend beyond simple demand substitution. These drivers interact with one another, creating both acceleration and new constraints depending on how companies position their capabilities.
PW Consulting
Technology Innovation and Performance Breakthroughs
Performance gains are reshaping adoption economics, particularly in disinfection and curing applications where efficiency and output directly influence total cost of ownership. Recent developments illustrate the pace of progress: in August 2025, ams-OSRAM AG doubled UV-C LED efficiency to 10.2% through enhanced semiconductor technology, a milestone that strengthens the case for UV-C deployment in air, water, and surface applications where energy consumption and thermal management have historically constrained scalability. Separately, Nichia Corporation expanded its portfolio in October 2025 with new UV-A LED series at 365nm and 385nm wavelengths featuring improved flux output for industrial UV curing, alongside new UV-B 308nm and UV-A 330nm LEDs. These product moves reflect a broader industry push to broaden wavelength coverage and improve output consistency, enabling customers to tailor solutions to more demanding curing and disinfection requirements.
The technology trajectory is also visible in system-level innovations. Kyocera Corporation’s May 2025 launch of the Air-cooled UV LED light source G7A Series with revolutionary curing performance highlights how thermal management and integration can change performance expectations in industrial settings. As LED efficiency and light-source design improve, the conversation shifts from feasibility to deployment scale, particularly in applications that previously relied on mercury-based alternatives.
Policy and Regulatory Momentum
Regulatory frameworks are increasingly shaping adoption pathways by establishing performance benchmarks and compliance expectations. Mercury phase-down pressures and broader environmental regulations continue to favor mercury-free alternatives, reinforcing interest in UV LEDs across disinfection, curing, and purification use cases. At the same time, certification requirements add both credibility and cost. NSF/ANSI Standard 55 certification, for example, requires UV LED systems to meet specific testing for residential water treatment, adding compliance validation time and costs. For suppliers, this means that time-to-market is not only a function of product readiness but also of testing, documentation, and certification strategy. For buyers, certified products reduce deployment risk but require a longer evaluation cycle and more disciplined vendor qualification.
Demand-Side Shifts in Disinfection, Curing, and Environmental Control
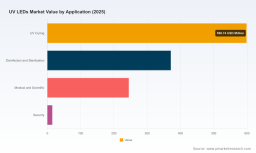
Demand is being driven by a combination of hygiene expectations, industrial productivity requirements, and sustainability scrutiny. Disinfection and sterilization applications have gained institutional traction in settings where water, air, and surface treatment are prioritized, while UV curing continues to benefit from the broader industrial push toward faster processing and reduced chemical exposure. Medical and scientific uses add a more specialized but high-value demand layer, particularly where wavelength precision and reliability are essential. Security-related applications occupy a smaller share of the market but remain relevant where specialized detection and verification functions depend on UV illumination.
What distinguishes the current demand environment is the move from pilot deployment to broader integration. As performance improves and compliance pathways become clearer, more organizations are evaluating UV LEDs not as experimental alternatives but as core components of operational strategy. This shift increases volume potential while also raising expectations for consistency, durability, and integration support.
Synthetic Quartz Glass UV-LED Market
Supply Chain Restructuring and Cost Dynamics
Supply chain and cost structure changes are reshaping how value is captured across the value chain. The combination of substrate limitations, export-controlled materials, and rising skilled-labor costs is pushing companies to rethink sourcing, inventory management, and manufacturing geography. At the same time, efficiency improvements are altering the relative importance of component cost versus system-level performance. In many cases, a higher-performing LED can justify a higher unit cost if it reduces energy usage, simplifies thermal design, or accelerates throughput. This reframing favors suppliers that can demonstrate total system value rather than competing solely on component pricing.
Competitive Landscape and the Strategies Defining Leadership
The competitive field is defined by a blend of established LED manufacturers, specialty deep UV players, and vertically oriented solution providers. Market leadership is not simply a function of scale; it increasingly depends on wavelength-specific expertise, certification readiness, and the ability to align product portfolios with high-priority application segments.
Differentiation Through Application Focus and Wavelength Breadth
Seoul Viosys Co., Ltd. has concentrated on its Violeds UV-C LED series optimized for UVC disinfection in water, air, and surface applications, an approach that emphasizes targeted performance in high-demand sanitation use cases. Nichia Corporation has pursued a broader wavelength strategy, offering full-range UV-C, UV-B, and UV-A LEDs for disinfection and mercury-free applications, while also expanding its portfolio with recent UV-A and UV-B products aimed at curing and specialized uses. This breadth supports flexibility across customer requirements and positions the company to capture demand across multiple application layers.
Crystal IS and Sensor Electronic Technology, Inc. continue to emphasize high-performance UVC and deep UV LEDs spanning 240-365nm for sterilization, sensors, and biomedical uses, focusing on technical performance in settings where wavelength precision and reliability carry disproportionate weight. STANLEY ELECTRIC CO., LTD. differentiates with UV-C and UV-A LEDs featuring hermetic sealing for disinfection and curing, an engineering choice that highlights durability and integration reliability. ams-OSRAM AG has built a recognizable portfolio through its OSLON UV-C LED line for air, water, and surface disinfection, and its recent efficiency gains reinforce the strategic value of semiconductor-level performance improvement.
Luminus Devices supports healthcare disinfection, water purification, and industrial curing with UVC and UVA LEDs, aligning its portfolio with both public-health and industrial demand. Nikkiso Co., Ltd. focuses on deep UV-LEDs for mercury lamp replacement in water purification and air sterilization, a positioning that directly addresses the substitution dynamic across environmental applications. LG Innotek Co., Ltd. integrates UV LEDs into lighting and disinfection solutions, reflecting a different competitive angle that emphasizes system-level integration and broader product ecosystems rather than component-only positioning.
Market Evolution: Consolidation, Specialization, and New Entrants
The market’s moderate concentration suggests room for both consolidation and continued specialization. Top players are likely to deepen application-specific capabilities, especially where certification, substrate access, and efficiency gains provide durable differentiation. At the same time, the fragmentation across wavelengths and applications creates entry points for firms that can solve a specific performance, integration, or compliance problem more effectively than generalist competitors.
Consolidation pressure is expected to intensify where scale matters most, particularly in substrate-dependent manufacturing and in segments that require extensive qualification and customer support. Conversely, specialization is likely to remain attractive in deep UV, medical/scientific, and curing applications where performance requirements are tightly defined and the cost of underperformance is high. New entrants will need to navigate material constraints and skilled-labor costs, but they can still compete by targeting underserved wavelength gaps, developing novel packaging or thermal-management approaches, or building strong certification and compliance capabilities early.
Forward-Looking Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to define the market’s direction and the commercial opportunities attached to them.
Efficiency Gains as a Deployment Catalyst
Continued improvements in UV-C and UV-A efficiency are likely to accelerate adoption in applications where energy consumption, thermal load, and system size have previously limited scale. As efficiency rises, total cost of ownership comparisons become more favorable against legacy alternatives, especially in disinfection and curing settings where operating costs and space constraints matter. The commercial opportunity here is not limited to component sales; it extends to system design, integration services, and performance-based value propositions that tie product selection to operational outcomes.
Supply Chain Resilience Becomes a Competitive Differentiator
Material controls and substrate limitations are likely to keep supply chain resilience at the center of strategy. Companies that diversify sourcing, negotiate long-term substrate access, and build transparent compliance and traceability processes will be better positioned to manage cost volatility and customer qualification cycles. For buyers, supplier resilience is increasingly part of procurement risk assessment, which creates an advantage for vendors that can demonstrate stable access to critical inputs and predictable delivery performance.
Certification and Standardization as Adoption Accelerators and Gatekeepers
Regulatory and standards activity is expected to remain a dual force: enabling broader deployment by establishing trust and performance benchmarks, while also extending validation timelines and adding cost for suppliers. The companies that treat certification as a strategic capability rather than a late-stage compliance task will gain speed and credibility in sensitive applications such as residential water treatment and public-health-related disinfection. For the market as a whole, this trend raises the bar for entry but also rewards organizations that can align product development with regulatory expectations early.
Potential Risks and Uncertainties
Several uncertainties bear monitoring. Further tightening of material export controls could disrupt supplier planning and increase input volatility, particularly for producers with concentrated sourcing exposure. Substrate constraints may persist if large-diameter aluminum nitride supply does not expand at a pace matching demand, maintaining pressure on per-unit costs in UV-C production. Labor cost inflation could also compress margins if process automation and workforce development lag behind manufacturing complexity. Finally, regulatory divergence across regions may create uneven adoption speeds, making it harder to scale standardized solutions globally without localized compliance investment.
Actionable Guidance for Decision-Makers
The market’s trajectory offers distinct implications depending on an organization’s role in the value chain. The following considerations can help translate market dynamics into prioritized actions.
For Manufacturers and Technology Developers
Focus investment where performance differentiation is most defensible. That means prioritizing wavelength-specific improvements, packaging reliability, thermal management, and certification readiness in high-value applications rather than competing broadly on price alone. Strengthening supply chain resilience should be treated as a strategic capability, including substrate access, material sourcing diversification, and process automation to offset skilled-labor cost pressure. Companies should also evaluate whether they can capture more value through system-level integration or partnered solutions, particularly in disinfection and curing where end users increasingly evaluate total operating performance.
For Investors
Evaluate exposure not just by revenue potential but by supply chain positioning, wage and substrate risk, and the ability to navigate certification timelines. The most attractive opportunities are likely to be in companies that combine meaningful efficiency gains with application-specific traction and credible compliance pathways. Diversification across wavelength segments may reduce reliance on any single bottleneck, but specialization can also create durable advantages where performance requirements are strict and substitution options are limited. Track material control developments and substrate supply progress, as these factors are likely to influence both cost structures and the pace of scaling.
For Procurement and End-User Organizations
Treat UV LED selection as a total-cost and risk decision rather than a component purchase. Prioritize suppliers with demonstrated certification readiness, stable material access, and evidence of efficiency and reliability in the target application. Build evaluation cycles that account for compliance validation, integration requirements, and long-term supply continuity, especially in water treatment, healthcare disinfection, and industrial curing settings where downtime or failure carries operational penalties. Align specification decisions with actual duty cycles and environmental conditions rather than maximum output claims, since real-world performance is often determined by thermal design, packaging quality, and system integration as much as by LED output.
The UV LEDs market is moving from a phase of capability demonstration to one of scaled deployment, where efficiency, compliance, and supply chain resilience determine who captures value and how quickly adoption broadens. Detailed segment-level data, company benchmarking, and scenario-based forecasts can sharpen these decisions further and help organizations convert market momentum into a coherent strategy. For decision-makers seeking a deeper, application-specific view of the landscape, the full research report provides expanded segmentation detail, competitive profiling, and tailored recommendations designed to support capital, product, and procurement decisions with greater precision.
For detailed analysis of this topic, please visit the official page: UV LEDs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com