

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Construction Equipment Market 2026: Why 6.8% CAGR and 200M USD Revenue Signal a Structural Shift

Navigating the Construction Equipment Market: Strategic Trends and Commercial Opportunities
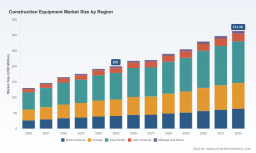
The global construction equipment market has entered a phase of accelerated transformation, driven by converging pressures around decarbonization, digitalization, and shifting infrastructure priorities. Over the 2020–2025 period, total industry revenue expanded from approximately USD 130.5 million to USD 200.0 million, reflecting both post-pandemic recovery and sustained capital deployment across heavy civil and commercial projects. Looking ahead, the market is projected to grow at a compound annual rate of 6.8% through 2032, reaching an estimated USD 313.38 million by the end of the forecast horizon. This trajectory signals more than cyclical recovery; it points to a structural recalibration in how equipment is designed, deployed, financed, and managed across the project lifecycle. For executives and investors, the imperative is no longer simply to track volume growth, but to understand where margin pools are shifting, which capabilities will dictate competitive positioning, and how supply-side constraints will reshape procurement and pricing dynamics.
The industry now operates at a crossroads. Demand fundamentals remain robust, but the prevailing operating environment introduces new layers of complexity that will separate adapting organizations from those constrained by legacy models. Two to three structural challenges define the current inflection point and will shape strategic responses over the next several years.
Cost volatility and supply chain fragmentation continue to pressure OEMs and dealers alike. Steel and aluminum input costs, influenced by domestic trade measures and global commodity fluctuations, directly affect equipment pricing and component sourcing strategies. At the same time, extended lead times for critical subsystems and mixed signals across regional demand cycles complicate production planning. Manufacturers that rely on rigid, high-volume assembly models are encountering margin compression, while those with modular architectures and diversified supplier networks retain greater flexibility.
Regulatory and emissions mandates are accelerating the transition toward electrification and hybrid powertrains, but adoption pathways differ sharply by application and geography. Emission reduction requirements and government sustainability incentives are pushing the industry toward cleaner equipment, yet fleet operators must balance upfront acquisition costs, charging or refueling infrastructure, and total cost of ownership across varied duty cycles. The pace of transition will not be uniform; instead, it will create segmented demand where compliance-driven segments move quickly while cost-sensitive or remote applications lag, requiring differentiated product strategies.
Labor dynamics and skills gaps add another layer of operational complexity. As equipment becomes more connected and automated, the workforce required to operate, maintain, and optimize fleets increasingly demands digital literacy and advanced diagnostics capabilities. Simultaneously, industry groups and OEMs are expanding training partnerships and academy-style programs to address the shortage of qualified technicians and operators. Organizations that treat workforce development as a strategic enabler—rather than a peripheral service offering—will gain advantages in uptime, customer retention, and technology adoption rates.
These challenges do not negate growth; they redefine it. The market’s expansion will be captured by players who treat cost, compliance, and capability as interconnected design constraints rather than isolated issues.
Key Drivers Shaping the Market Trajectory
Several overlapping forces are determining where demand consolidates and how competitive advantage is built. Understanding these drivers provides the foundation for evaluating opportunities across product lines, regions, and service models.
Technological Innovation and Equipment Intelligence
The integration of electrification, automation, and connected machine technologies is shifting the market from a purely hardware-centric paradigm to a performance-and-data-driven one. Manufacturers are embedding digital controls, telematics, and autonomous or semi-autonomous capabilities into mainstream product lines, enabling tighter precision, reduced fuel consumption, and improved site coordination. Electric and hybrid platforms are advancing most visibly in compact and midsize segments, where duty cycles and site infrastructure are more amenable to alternative powertrains, while larger platforms continue to pursue efficiency improvements and selective automation. Industry data indicates accelerating adoption of electric and hybrid construction equipment, fueled by emission reduction mandates and government sustainability incentives. This is not merely a compliance story; it is also an operational one, as operators seek to lower fuel exposure, reduce maintenance variability, and align with project owners’ sustainability requirements.
Recent product activity illustrates how quickly the innovation frontier is moving. At a major 2026 trade event, one manufacturer showcased a broad lineup of machines spanning compact, midsize, and full-size excavators, alongside an electric mini track loader, signaling the widening scope of electrification across categories. Parallel updates in midsize excavators have introduced new digital control architectures and cab technologies aimed at improving precision and operator experience. These developments suggest that differentiation is increasingly tied to integrated systems—where machine performance, interface design, and data availability converge—rather than raw mechanical capacity alone.
Policy and Regulatory Environment
Government spending programs and trade conditions are shaping both demand timing and cost structures. Infrastructure investment under major U.S. legislation continues to support equipment utilization, with peak disbursements through 2026 reinforcing demand across earthmoving and material handling categories. This public capital pipeline provides near-term demand visibility, but it also heightens the importance of fleet readiness and service capacity, since utilization peaks can strain maintenance networks and parts availability.
Trade policy adds complexity to sourcing and pricing. Domestic tariffs on steel and aluminum continue to influence component costs and pricing strategies for construction equipment, pushing manufacturers to reassess bill-of-materials structures, supplier geographies, and product mix. In this environment, pricing power is increasingly tied to value communication: operators are more willing to accept premium pricing when it is clearly linked to reduced operating cost, compliance assurance, or productivity gains.
PW Consulting Health Care Research Center
Demand-Side Shifts in Customer Behavior
End users are recalibrating procurement criteria around total lifecycle economics, emissions profiles, and uptime assurance. Infrastructure development remains the largest application anchor, supported by ongoing civil works, transport, and energy-related projects, while commercial, industrial, and residential activity contributes additional demand layers that vary by region and financing conditions. Across segments, there is growing interest in equipment that can support stricter site emissions expectations, reduce fuel exposure, and integrate with digital project workflows. Rental and municipal markets, in particular, are influencing product preferences for compact and midsize machines that can be deployed flexibly and maintained within shared service networks.
This behavioral shift is changing how value is sold and captured. Customers increasingly evaluate platforms based on what they enable—faster cycle times, lower emissions, better precision, or simplified maintenance—rather than on machine specifications in isolation. As a result, OEMs that provide integrated support ecosystems, including telematics, service planning, and operator training, are better positioned to defend margins and deepen customer relationships.
Supply Chain and Cost Structure Evolution
Raw material price volatility, especially in steel and fuel, remains a central margin factor for equipment manufacturers amid global commodity markets. This creates a continuing need for cost discipline, supplier diversification, and product architectures that can absorb input fluctuations without eroding competitiveness. At the same time, the shift toward electrified and connected equipment is reshaping the cost base itself: battery systems, power electronics, software development, and data infrastructure are becoming more significant components of the value chain. Companies that manage this transition as a portfolio—balancing traditional mechanical cost control with new investment in electronics, software, and energy systems—are more likely to protect profitability as the mix shifts.
Competitive Landscape and Leading Strategies
The market remains moderately concentrated, with a small group of large global players commanding a substantial share of revenue and capabilities. This concentration reflects the capital intensity of product development, the scale required to serve global infrastructure demand, and the importance of service networks in sustaining customer relationships. At the same time, the competitive field is evolving as regional specialists, emerging manufacturers, and technology-focused entrants target specific niches and application segments.
Heavy Equipment Market
Leading incumbents are pursuing a mix of scale, technology integration, and segmented specialization. Some of the largest manufacturers anchor their positions on broad equipment portfolios spanning excavators, loaders, haul trucks, graders, and cranes, paired with connected platform technologies and electrification roadmaps. Their scale advantage supports global service reach, parts availability, and the ability to invest across multiple technology tracks simultaneously. In parallel, other strong players differentiate through focused portfolio depth, whether in compact and midsize equipment, large-capacity earthmoving and lifting systems, or electric and hybrid platforms with an emphasis on zero-emission performance and operator safety.
Several distinctive strategic positions are evident across the competitive set:
- Broad-line scale and connected ecosystems: A few global manufacturers combine wide product coverage with integrated data and software offerings, emphasizing automation, remote monitoring, and service optimization. Their recent disclosures and innovation programs reflect a continued focus on profitable growth, advanced electrification, and workforce development initiatives designed to support future capability needs.
- Autonomy and construction workflow integration: One major manufacturer has moved decisively toward large-scale autonomous hauling and expanded engineering collaborations aimed at workforce development, signaling that scale automation paired with talent pipelines is becoming a strategic pillar rather than a niche experiment.
- Compact and midsize digital productivity: Another leader has updated midsize excavators with enhanced digital controls and cab technology, underscoring the importance of precision, usability, and operator-centric design in segments where rental, municipal, and smaller contractor demand is active.
- Electrification and zero-emission focus: European and other manufacturers are emphasizing electric and hybrid platforms, targeting compliance-driven applications and customers seeking to reduce on-site emissions while maintaining performance and safety standards.
- Specialist engineering for demanding applications: High-capacity excavators, cranes, and specialized earthmoving equipment continue to serve segments where engineering rigor, load capacity, and application-specific durability justify differentiated positioning.
- Cost-effective global export and infrastructure reach: Chinese manufacturers continue to compete on durable, cost-competitive machinery for emerging markets and infrastructure projects, broadening export-oriented offerings across loaders, excavators, and cranes.
- Rental and municipal adjacency: Some mid-tier manufacturers maintain strong positioning in compact and midsize categories with particular relevance to rental fleets and municipal users, where machine versatility, serviceability, and total cost of ownership are decisive.
The landscape is not static. Consolidation pressure exists where scale economics, service network coverage, and technology investment requirements favor larger players, particularly in connected and electrified platforms. At the same time, fragmentation persists in segments where application specificity, regional distribution, and price sensitivity create room for targeted specialists and new entrants. The most likely outcome over the next several years is a layered market: a concentrated core of global-scale manufacturers competing on portfolios, data, and electrification, alongside a diverse periphery of specialists serving niche duty cycles, regional demand, and specific customer segments. Companies that can navigate both layers—either by building focused strength or by partnering for distribution and service—will shape the market’s direction.
Future Trends and Commercial Implications
Based on current data and industry momentum, three trends are likely to define the market over the next three to five years, each carrying distinct commercial implications.
1. Electrification will progress in waves, not uniformly. Adoption will accelerate fastest where duty cycles, site infrastructure, and regulatory pressure align—often in compact and midsize categories, urban work, and compliance-sensitive applications. Larger platforms will see more gradual transitions as energy storage, charging logistics, and total cost economics continue to mature. The commercial opportunity lies in offering flexible powertrain choices, robust service support for alternative energy systems, and clear total cost of ownership narratives that justify premium positioning where justified. The risk is misjudging the pace in segments where infrastructure and operating conditions limit near-term viability, leading to misaligned product investment or pricing expectations.
2. Connected and data-enabled equipment will become a standard expectation rather than a premium feature. Telematics, remote diagnostics, operator-assist technologies, and workflow integration will increasingly influence purchasing decisions and service contracts. This creates opportunities to expand recurring and service-based revenue, improve fleet utilization, and differentiate through uptime and productivity outcomes. It also raises the bar for cybersecurity, software lifecycle management, and data interoperability. Organizations that treat software and data as core product components—rather than add-ons—will be better positioned to capture long-term value, while those that underinvest may face commoditization pressure.
Construction Equipment Rental Market
3. Infrastructure spending and trade conditions will drive demand peaks and cost volatility in tandem. Public capital deployment continues to support utilization through the mid-2020s, reinforcing demand for earthmoving and material handling equipment. At the same time, trade measures on key inputs and commodity fluctuations will continue to influence margins and pricing strategies. The commercial implication is that volume growth alone will not guarantee profitability; firms that can align production flexibility, supplier strategy, and value-based pricing will be better equipped to convert favorable demand into durable margins. The uncertainty lies in the timing and duration of spending peaks, as well as the potential for abrupt cost shocks that can compress returns if not managed proactively.
Strategic Actions for Decision Makers
Different stakeholders face distinct priorities, but all benefit from a disciplined view of where value is being created and where exposure is building. The following actions are most relevant across the main audiences in this market.
For manufacturers and equipment providers: Prioritize portfolio decisions that match powertrain and technology investments to real application economics rather than uniform rollout assumptions. Invest in service and data capabilities that support uptime, operator training, and lifecycle economics, since these increasingly determine customer retention and margin resilience. Strengthen supplier diversification and product architecture flexibility to absorb input cost volatility without sacrificing competitiveness. Where scale and connectivity matter, pursue partnerships or platform strategies that accelerate software, electrification, and autonomy capabilities without overextending internal resources.
For investors and corporate development teams: Focus on companies that demonstrate credible progress in electrification, connected services, and cost discipline, evaluated through the lens of application fit and total cost of ownership rather than headline product announcements alone. Monitor segments where rental, municipal, and infrastructure demand intersect with compact and midsize equipment, as these areas often combine relatively faster adoption cycles with recurring service potential. Assess exposure to trade-driven cost dynamics and supply chain flexibility, which will increasingly differentiate performers in a volatile input environment.
For fleet operators, contractors, and procurement leaders: Evaluate purchases against operational outcomes—emissions compliance, fuel and energy exposure, precision, maintenance predictability, and integration with site workflows—rather than specification lists in isolation. Build internal capabilities for operating and maintaining connected and electrified equipment, including technician training and data-driven maintenance planning, to capture the productivity and uptime benefits these platforms can enable. Where utilization patterns are uneven, consider rental, leasing, or mixed-fleet strategies that preserve flexibility while aligning equipment choices with project-specific requirements.
The construction equipment market is expanding, but the next phase of value creation will be uneven and selective. Companies and investors that understand the interplay of technology, policy, demand behavior, and cost structure will be better positioned to capture growth without overexposing themselves to transition risks. For leaders who need more granular segmentation, region-specific demand dynamics, and tailored scenario analysis, the full research report provides detailed breakdowns and customized guidance to support more precise planning and execution.
For detailed analysis of this topic, please visit the official page: Construction Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com