
Blogs
RF Switches Market 2026: Beyond the 5.6% CAGR Story – PIN, GaAs, and MEMS Drivers
By pmarketresearch, 2026-09-21
Navigating the RF Switches Market: Strategic Trends and Commercial Opportunities Through 2032
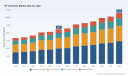
The RF switches market has entered a phase of methodical expansion, underpinned by steady revenue growth from 2020 through 2025 and a projected compound annual growth rate of 5.6 percent across the 2026–2032 forecast period. By 2025, total market revenue reached approximately 4.48 billion USD, with a clear trajectory toward 6.57 billion USD by 2032. This growth is not merely a reflection of incremental demand; it signals a structural shift in how radio frequency signal routing is designed, manufactured, and integrated across connected systems. The market’s expansion is broad-based, spanning mature telecommunications infrastructure, defense and aerospace platforms, industrial automation, and emerging satellite-linked communication networks. Yet beneath the headline numbers lies a more nuanced reality: technology transitions, regulatory pressures, and supply chain recalibration are simultaneously reshaping competitive positioning and creating asymmetric opportunities for firms that can anticipate rather than react to market shifts.
Pinpointing the Core Challenges and Market Inflection Points
Despite the favorable growth outlook, the industry is navigating several critical inflection points that will determine which players capture disproportionate value over the next five years. First, the coexistence of competing RF switch technologies is forcing design teams and procurement leaders to make increasingly complex trade-offs. PIN diode switches remain widely deployed for cost-sensitive and high-power applications, while GaAs and SOI/SOS platforms continue to dominate where isolation, linearity, and insertion loss are paramount. MEMS switches and emerging silicon-based alternatives are gradually gaining traction in scenarios where power consumption, footprint, and reliability must be optimized simultaneously. The absence of a single dominant architecture means that technology selection is becoming increasingly application-specific, raising integration complexity and lengthening qualification cycles for OEMs.
Second, the rapid expansion of low Earth orbit satellite constellations is introducing both demand tailwinds and spectrum management friction. Regulatory filings and policy analyses indicate that satellite production growth is outpacing existing coordination frameworks, creating heightened concerns over radio interference and orbital slot allocation. As operators scale constellations from thousands to tens of thousands of satellites, the RF front-end ecosystem—including switching, filtering, and amplification subsystems—must accommodate higher throughput, broader frequency coverage, and tighter thermal and reliability constraints. This dynamic is simultaneously opening new procurement pipelines for aerospace and defense suppliers while forcing terrestrial and wireless communication vendors to navigate increasingly crowded spectral environments.
Third, infrastructure deployment strategies are evolving in ways that reshape regional demand patterns. Broadband expansion initiatives are increasingly emphasizing microtrenching, surface-level deployments, and hybrid fiber-wireless architectures, which influence the mix of RF components required for last-mile and mid-mile connectivity. At the same time, sovereign spectrum rights and orbit governance frameworks are reinforcing the strategic importance of localized component sourcing, testing, and compliance. Together, these forces are pushing the market away from commoditized volume plays and toward differentiated, application-engineered solutions where switching performance, environmental ruggedness, and lifecycle support carry greater commercial weight.
Decoding the Key Demand Drivers Reshaping Revenue Trajectories
The market’s growth is being propelled by a convergence of technological, regulatory, and demand-side forces that reinforce one another rather than operate in isolation. Technological innovation remains the most direct catalyst. Recent product introductions from established manufacturers illustrate how switch architectures are being refined to meet the stringent requirements of radar, electronic warfare, broadband infrastructure, and high-reliability communications. Advancements in SOI-based SPDT platforms, high-isolation SPST/SPDT series, reflective antenna tuning switches, flip-chip architectures, and GaN-enabled high-power switching solutions demonstrate a clear industry emphasis on improving isolation, reducing loss, and expanding frequency ranges. These improvements are not incremental refinements; they enable system designers to consolidate RF paths, reduce module count, and improve overall signal integrity in increasingly dense electromagnetic environments.
Policy and regulatory developments are simultaneously acting as both an enabler and a constraint. The broadening of LEO satellite constellations has triggered heightened scrutiny around spectrum allocation, interference mitigation, and orbital coordination. Regulatory bodies and government analyses are increasingly emphasizing careful spectrum management and sovereign rights over orbital and frequency resources. For RF switch suppliers, this translates into a dual dynamic: expanded opportunities in satellite-linked communication ecosystems and test-and-measurement infrastructure, alongside stricter qualification requirements and a growing premium on components that can operate reliably under congested spectral conditions. The regulatory environment is effectively raising the barrier to entry for generic switching solutions while rewarding vendors with documented compliance, robust testing protocols, and application-specific design support.
Demand-side behavior is shifting as well. Cellular and wireless communication networks continue to anchor a substantial share of RF switch consumption, but the nature of that demand is changing. Base station architectures, antenna tuning systems, and broadband access equipment are becoming more modular and software-defined, requiring switching components that can adapt to dynamic reconfiguration without sacrificing performance. At the same time, industrial and automotive applications are gaining prominence as connectivity expands beyond traditional telecom into factory automation, vehicle-to-infrastructure communication, and sensor-heavy environments. These sectors demand switches that can tolerate harsher operating conditions, sustain long service intervals, and integrate cleanly into mixed-signal architectures. The result is a broadening of the demand base that reduces reliance on any single vertical while increasing the need for segmented product strategies.
PW Consulting Information & Electronics Research Center
Supply chain and cost structure dynamics round out the driver set. The concentration of revenue among a relatively small group of leading suppliers indicates that scale, technology maturity, and strategic customer relationships continue to confer meaningful advantages. At the same time, the market’s evolution toward specialized high-reliability and high-isolation solutions is elevating the importance of production consistency, material sourcing, and qualification documentation. Cost pressures persist, particularly in consumer-facing and mass-market wireless applications, but they are increasingly offset by value migration toward performance-critical segments where switching reliability, thermal handling, and integration flexibility directly influence system economics. The net effect is a market where cost leadership alone is no longer sufficient; competitive advantage is being redefined around design enablement, lifecycle support, and application-specific performance guarantees.
Competitive Landscape and the Strategies Defining Market Leadership
The competitive environment reflects a market that is neither fully consolidated nor fragmented beyond coherence. A concentrated core of established manufacturers anchors supply in defense, aerospace, telecommunications, and test-and-measurement applications, each pursuing distinct yet overlapping strategic positions. Leading players are differentiating not simply through product breadth, but through architecture specialization, application-specific tuning, and long-term ecosystem relationships that extend beyond component sales.
Network Switches Market
Companies focused on high-performance semiconductor-based switching are emphasizing platform continuity and portfolio expansion. Recent announcements in the first half of 2026 illustrate this pattern clearly. Qorvo introduced new X-Band amplifiers, GaN transistors, and SOI SPDT RF switches targeting defense, aerospace, radar, electronic warfare, communications, and DOCSIS 4.0 broadband applications, signaling a deliberate push to align switching solutions with high-growth, high-reliability segments. pSemi expanded its UltraCMOS+ portfolio with new high-isolation RF switches, reinforcing a strategy centered on isolation performance and integration simplicity for demanding RF front-end designs. Skyworks Solutions has continued to emphasize reflective antenna tuning switch architectures that support beamforming, coverage optimization, and adaptive impedance matching in advanced wireless systems. Analog Devices maintains a strong position in flip-chip SP4T switching for test and measurement and cellular applications, where repeatability, calibration stability, and signal path integrity are critical. MACOM’s reflective SPDT switches remain relevant across WiFi, Bluetooth, and base station ecosystems, particularly where rapid reconfiguration and compact integration are valued.
Parallel to these semiconductor-centric strategies, a cohort of suppliers is strengthening their position in electromechanical, coaxial, waveguide, and high-reliability switching for environments where solid-state alternatives face thermal, power-handling, or failure-mode constraints. Teledyne Microwave Solutions and Teledyne Relays & Coax Switches provide surface-mount and latching multi-throw coaxial switching that support communications systems and aerospace and defense deployments requiring extended lifecycle durability and deterministic switching behavior. JFW Industries’ absorptive failsafe switches and Dow-Key Microwave’s custom coaxial, waveguide, and space-grade switches highlight a persistent premium on tailored solutions for high-power and mission-critical scenarios. Narda-MITEQ and Pasternack Enterprises continue to serve wireless communication and test-and-measurement markets with reflective and electromechanical transfer switches that prioritize repeatability, isolation, and serviceability. Planar Monolithics Industries and Radiall reinforce the broader ecosystem with solid-state and microwave-component switching options that address military, industrial, and component-integration requirements.
The strategic lesson from this landscape is that leadership is increasingly defined by the ability to match switching technology to the failure modes, environmental constraints, and reconfiguration requirements of the end application. Firms that treat RF switches as interchangeable commodities risk margin erosion and displacement by suppliers offering integrated design support, application-specific qualification packages, and lifecycle reliability documentation. Conversely, suppliers that align product roadmaps with defense/aerospace ruggedness, broadband infrastructure scalability, satellite communication frequency expansion, and test infrastructure repeatability are positioning themselves to capture more resilient demand streams. The market is also showing signs of gradual consolidation pressure, as acquisition interest in specialized high-reliability portfolios and niche antenna-tuning platforms intensifies. At the same time, new entrants and smaller specialist firms can still find room in custom configurations, ultra-high isolation niches, and application-tailored electromechanical solutions where incumbents face limits in standard product coverage.
Forecasting the Next Phase: Three Trends to Watch Through 2032
The next three to five years will likely be shaped by a blend of technology migration, demand diversification, and ecosystem coordination challenges. The first trend is the continued broadening of application-specific switch architectures. As systems grow more software-defined and frequency-agile, RF switches will need to support dynamic reconfiguration, lower loss across wider bands, and improved robustness against interference. The commercial opportunity lies in developing modular switching families that can be rapidly adapted across cellular, broadband, satellite-linked, and industrial use cases without requiring full redesign cycles. Suppliers that can offer configurable isolation levels, compact integration footprints, and predictable thermal behavior will be better positioned to win in environments where system architects must balance performance, cost, and deployment speed.
Worldwide High Isolation RF Switches Market
The second trend is the deepening integration of RF switching into high-reliability and satellite-adjacent ecosystems. The scaling of LEO constellations and the growing emphasis on spectrum discipline are expanding the need for components that can operate across extended frequency ranges, withstand harsh environmental conditions, and satisfy rigorous qualification standards. This trend favors suppliers with documented aerospace and defense heritage, robust testing capabilities, and the ability to support long-lifecycle deployment models. Commercial upside will accrue to firms that can bridge the gap between terrestrial wireless demand and space-linked communication requirements, particularly where switching reliability directly affects link stability, interference resilience, and maintenance intervals.
The third trend is the gradual rebalancing of supply chain risk and regional procurement preferences. As regulatory frameworks reinforce sovereign rights over spectrum and orbital resources, and as infrastructure plans increasingly emphasize localized broadband expansion, procurement teams are placing greater weight on supply continuity, traceability, and compliance documentation. The commercial implication is a market where regional service capability, testing support, and component qualification transparency increasingly influence purchasing decisions alongside unit economics. Firms that can demonstrate consistent production quality, application engineering support, and resilient sourcing will be better positioned to retain strategic accounts and capture new programs that prioritize supply assurance over lowest-cost sourcing.
These trends carry embedded risks. Technology choices that appear advantageous today may face obsolescence pressure if network architectures shift toward new frequency plans, beamforming strategies, or integrated RF modules that reduce discrete switch count. Regulatory uncertainty around spectrum allocation and orbital coordination could delay program timing or alter component specifications mid-cycle. Cost pressure in high-volume wireless and consumer-adjacent applications could compress margins for suppliers that fail to differentiate on performance or lifecycle support. Finally, consolidation activity may accelerate, altering supplier relationships and forcing customers to reevaluate qualification pipelines, second-source strategies, and long-term roadmap alignment.
Strategic Actions for Decision-Makers Across the Value Chain
For manufacturers and product leaders, the priority is to align switch roadmaps with the applications where performance differentiation is both measurable and commercially rewarded. This means investing in architectures that improve isolation, reduce loss, and support broader frequency coverage while maintaining production consistency and qualification clarity. Teams should prioritize modular product families that can be adapted across cellular, broadband, satellite-adjacent, and industrial environments without fragmenting engineering resources. Equally important is strengthening design-in support: application notes, integration guidance, thermal and reliability documentation, and test-proven reference configurations can materially accelerate adoption in programs where switching performance affects overall system performance. Manufacturers should also evaluate second-source strategies and supply assurance capabilities early, since procurement teams increasingly weigh continuity and traceability alongside technical specifications.
For investors and corporate development teams, the market offers segmentation-specific opportunities rather than a uniform growth story. High-reliability aerospace and defense switching, broadband infrastructure expansion, and satellite-linked communication ecosystems represent segments where technical differentiation and qualification depth translate into more defensible revenue streams. In contrast, commoditized high-volume segments may deliver volume but limited margin expansion unless paired with integration advantages or platform-level partnerships. Due diligence should therefore focus on product roadmaps, technology ownership, qualification pipelines, customer concentration, and the ability to support long-lifecycle deployments. Portfolio construction should weigh the trade-off between scale-driven semiconductor platforms and specialized electromechanical or high-power solutions, recognizing that both can be attractive but require distinct execution models and customer engagement strategies.
For procurement and systems integration teams, the strategic emphasis should shift from unit price alone toward total cost of qualification, integration risk, and lifecycle reliability. Switching components that reduce design iterations, simplify calibration, and deliver predictable behavior under real-world thermal and interference conditions can lower program risk and shorten deployment timelines. Procurement strategies should incorporate supplier capability in application engineering, testing support, and documentation quality, particularly for programs where RF path integrity directly impacts throughput, coverage, or mission reliability. Where possible, qualification planning should account for regulatory evolution in spectrum management and orbital coordination, ensuring that selected components remain suitable as frequency plans, interference conditions, and system architectures evolve over the program lifecycle.
The RF switches market is expanding within a framework that rewards clarity of application focus, technical differentiation, and supply assurance. Executives who map their strategies to the segments where switching performance, reliability, and integration flexibility carry financial weight will be better positioned to capture value as the market moves from steady growth toward more segmented, performance-driven competition. For organizations seeking deeper segmentation data, region-specific demand patterns, detailed competitive benchmarking, and tailored scenario planning, the full research report provides the additional granularity required to translate these market-level insights into executable commercial decisions.
For detailed analysis of this topic, please visit the official page: RF Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PICV Market Growth at 4% CAGR: Commercial & APAC Drivers Redefining Pressure Control Strategy
By pmarketresearch, 2026-09-21
Strategic Horizons: Navigating the Pressure Independent Control Valves Market
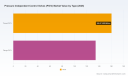
The Pressure Independent Control Valves (PICV) market has transitioned from a specialized engineering niche to a critical component of modern hydronic system design. With a global market valuation of USD 295.0 Million in 2025, the sector reflects a broader shift toward energy-efficient building operations and variable-flow HVAC architectures. The market has demonstrated consistent growth, expanding from USD 220.0 Million in 2020 at a compound annual growth rate (CAGR) of 4.0 percent through the forecast period extending to 2032. While the historical trajectory shows steady expansion, reaching USD 387.0 Million by 2032, the market is not without its complexities. Investors and strategic planners must understand not just the headline figures, but the underlying structural dynamics, competitive positioning, and technological inflection points that will determine long-term value creation.
For enterprise decision-makers, the PICV market represents a convergence of regulatory pressure, technological advancement, and evolving operational performance expectations. The widespread adoption of PICVs is no longer merely a technical preference; it is increasingly a compliance and performance imperative. ASHRAE 90.1 standards, for instance, require a 50 percent reduction in energy consumption in initial building models, and PICV technology has proven capable of delivering 20-40 percent HVAC energy performance improvements through stable flow management and reduced system inefficiency. This regulatory backdrop creates a structural tailwind that transcends short-term economic cycles, anchoring demand in long-term building performance mandates rather than discretionary capital expenditure.
Diverter Valves Market
Market Context And Structural Challenges
A Market In Transition
The PICV market's expansion to a projected USD 387.0 Million by 2032 is underpinned by a 4.0 percent CAGR, yet this aggregate figure masks regional and application-level variations that demand careful strategic navigation. Asia Pacific represents the largest revenue contribution at USD 100.65 Million, followed by Europe at USD 75.83 Million and North America at USD 69.01 Million, with Latin America and the Middle East and Africa each contributing approximately USD 24.7 Million and USD 24.81 Million respectively. On the application side, commercial buildings account for USD 159.26 Million of total revenue, residential applications contribute USD 81.36 Million, and industrial use cases represent USD 54.38 Million. By product type, threaded PICVs generate USD 160.47 Million while flange PICVs account for USD 134.53 Million. The market exhibits moderate concentration, with the top three players holding 32.0 percent and the top five commanding 48.0 percent of total market share.
These figures point to a market that is broad-based but increasingly competitive at the margins. The commercial segment's dominance reflects the ongoing retrofit and modernization of office, retail, and institutional buildings where system balancing and energy accountability are paramount. Residential growth, while smaller in absolute terms, is being propelled by higher HVAC adoption rates in new housing developments and stricter energy codes in multiple jurisdictions. Industrial applications, though the smallest segment, are gaining attention due to the thermal control demands of data centers, manufacturing facilities, and processing plants where precise flow regulation translates directly into operational cost savings.
Key Challenges And Inflection Points
Despite favorable long-term demand drivers, the PICV market faces several structural challenges that will shape competitive outcomes over the next five years. First, installer and commissioning expertise remains a bottleneck. PICV technology delivers its full value only when properly sized, integrated, and calibrated within the broader hydronic system. In markets where skilled HVAC technicians are in short supply, the performance gap between theoretical efficiency gains and realized outcomes can undermine customer confidence and slow adoption. This operational dependency means that product innovation must be paired with training, documentation, and commissioning support to sustain market momentum.
Second, the market is navigating a tension between standardization and customization. End-users increasingly demand valves that can handle wider flow ranges, integrate with building automation platforms, and support variable-flow optimization without requiring separate balancing valves. However, engineering more versatile products can increase manufacturing complexity and cost. Companies that can streamline the balance between modular design, scalability, and application-specific performance will gain a significant advantage in both commercial and industrial segments.
Pinch Valve Market
Third, certification and compliance requirements are becoming more stringent across regions. UL certification and ISO 9001:2015 compliance are now baseline expectations for commercial and industrial PICV applications, and product documentation, including Environmental Product Declarations, is increasingly tied to procurement decisions in sustainability-driven markets. Firms that treat compliance as a strategic capability rather than a checkbox exercise will be better positioned to secure specifications in large-scale tenders and public-sector projects.
Key Drivers Of Market Change
Regulatory And Energy Performance Mandates
Policy and regulatory frameworks are the most durable demand driver for PICVs. Standards such as ASHRAE 90.1 impose rigorous energy performance thresholds on new construction and major renovations, creating a compliance pathway that favors variable-flow hydronic systems with pressure-independent control. The ability of PICVs to maintain stable flow irrespective of pressure fluctuations directly reduces pump energy consumption, improves delta-T performance, and minimizes inefficient operation during part-load conditions. These outcomes align directly with building energy codes and green building certification requirements, making PICVs a pragmatic solution for developers, facility managers, and engineering consultants seeking to meet mandated targets without overbuilding system capacity.
Technological Innovation And Smart Integration
Technological advancement is transforming PICVs from passive balancing devices into active, data-enabled components of the building control ecosystem. Leading manufacturers are embedding IoT connectivity, integrated energy measurement, and actuator interfaces that support seamless integration with building automation systems. Products such as Danfoss AB-QM 4.0 and AB-QM series with NovoCon actuators, Belimo PIQCV and Energy Valve™ IoT-connected PICVs, and Johnson Controls VP140 Series and XT-range valves illustrate this shift toward combined balancing, control, and monitoring functionality. Siemens' integrated PICVs that combine differential pressure control, regulation, and 2-port valve functions further demonstrate how multi-function design is reducing the number of components required for commissioning, simplifying installation, and improving system reliability.
Recent product activity underscores the pace of this innovation cycle. Danfoss released updated data sheets and brochures for its AB-QM 4.0 PICVs and actuators in early and mid-2026, alongside Environmental Product Declarations for multiple variants, signaling a strategic emphasis on both technical performance and sustainability documentation. Griswold Controls showcased its Energy FIT system and actuator integrations at the AHR Expo 2026, highlighting the growing importance of energy-focused commissioning and monitoring capabilities. ISMA Controlli's LIBRA PICV range update in May 2026 further illustrates how manufacturers are continuously refining dynamic circuit control performance to meet evolving application requirements. These developments are not isolated product updates; they reflect a broader industry move toward valves that support both hydraulic performance and operational visibility.
Demand-Side Shifts In Building Operations
Demand-side behavior is changing in ways that favor PICV adoption. Building automation infrastructure expansion is accelerating, driven by asset owners seeking to reduce operational expenditures, improve tenant comfort, and meet sustainability commitments. At the same time, smart building adoption and heightened indoor air quality awareness are increasing the role of precise environmental control in specification decisions. PICVs with integrated control and monitoring features are increasingly valued because they provide system-level visibility that supports predictive maintenance, fault detection, and performance optimization. This demand-side preference is particularly pronounced in commercial real estate, where energy intensity and occupancy variability make stable flow control a strategic operational asset.
Supply Chain And Material Considerations
Cost structures and material choices are becoming a more visible competitive dimension. Scaling- and clogging-resistant polymer components in PICV designs are increasingly favored because they support long lifetime and reliability under varying operating conditions, reducing maintenance interventions and extending service intervals. At the same time, manufacturers must manage raw material availability, production consistency, and lead-time volatility across global supply chains. Companies that can secure reliable sources of high-performance polymers, standardize insert and body geometries where feasible, and maintain quality assurance systems aligned with ISO 9001:2015 will be better positioned to manage cost volatility while preserving product performance.
Competitive Landscape And Strategic Positioning
Leading Players And Differentiation Strategies
The PICV market is characterized by a diverse competitive set spanning established multinational manufacturers, specialized valve producers, and regional specialists. Danfoss has built a strong position around its AB-QM 4.0 and AB-QM series, emphasizing stable flow, energy savings, and commissioning ease through actuator-compatible pressure-independent balancing and control valves for heating and cooling applications. Belimo competes with a focus on precision hydronic control and energy measurement, leveraging its PIQCV, EPIV, and Energy Valve™ IoT-connected PICVs to address variable-flow optimization and operational data integration. Johnson Controls differentiates through the VP140 Series and XT-range PICVs, which are designed to eliminate the need for separate balancing valves and streamline stable flow performance within building automation contexts. Siemens takes an integration-led approach, combining differential pressure control, regulation, and 2-port valve functions in a single device to optimize delta-T and commissioning outcomes.
In the Americas, Bray International offers the SS Series and SSM Series for threaded and flanged applications respectively, emphasizing dynamic balancing and high-rangeability control in hot and chilled water systems. Griswold Controls has built recognition around its PIC-V®, MVP®, Pinnacle, and PIM series designed to replace separate balancing and control pairs in HVAC, with strong exposure in data center and industrial applications through its Tiger Controls partnership ecosystem. Xylem contributes with Bell & Gossett Ultra Setter PICVs and Press Connect fittings aimed at simplifying balancing and control adjustments. In Europe, Frese A/S maintains specialized PICV lines for Nordic and broader European hydronic applications, while Caleffi's FLOWMATIC and other PICV series address residential and commercial HVAC balancing. IVAR's LIBRA range targets dynamic circuit control in Southern European markets, supported by recent product updates. IMI PLC, Cranfield, Pettinaroli, FAR, and Schneider Electric reinforce the diversity of the competitive field, each bringing distinct strengths in portfolio breadth, regional reach, or integration with building services and automation platforms.
This breadth of offerings creates a market where differentiation occurs along several axes: product range and size coverage, actuation and IoT compatibility, commissioning and documentation support, certification and sustainability credentials, and integration with wider building services ecosystems. Companies that can demonstrate consistent performance across these dimensions are increasingly favored in specification processes, particularly where multi-vendor or multi-building deployments require standardization and reliable technical support.
Market Evolution: Consolidation, Fragmentation, And New Entrants
The market's moderate concentration, with the top five players holding 48.0 percent of revenue, suggests room for both consolidation and continued fragmentation. Larger players with broad building automation or HVAC portfolios can leverage PICVs as part of integrated solutions that span valves, controllers, and system commissioning services. This integration advantage can be decisive in large commercial and institutional projects where single-point accountability and system-level optimization are valued. At the same time, specialized manufacturers with strong technical reputations in specific regions or applications can compete effectively by focusing on differentiated features such as wide flow coverage, insertion-based designs, high-rangeability control, or targeted industrial-grade performance.
PW Consulting Automotive & Machinery Research Center
The potential for further consolidation exists, particularly where manufacturers seek to expand product portfolios, geographic reach, or commissioning capabilities. Conversely, continued fragmentation is likely where regional standards, application requirements, and installer preferences diverge. New entrants may find opportunity by addressing underserved niches, such as data center thermal control, high-performance industrial hydronic systems, or application-specific PICVs optimized for quick commissioning and minimal maintenance. The strategic question for incumbents and entrants alike is whether to compete on portfolio breadth and integration or on focused technical excellence and service depth.
Future Trends And Commercial Opportunities
Trend 1: Energy Accountability As A Procurement Driver
Over the next three to five years, energy accountability will become a more explicit factor in procurement decisions. As building operators face rising energy costs and tighter performance reporting requirements, PICVs that deliver demonstrable flow stability, reduced pump energy, and improved delta-T performance will be prioritized in both new construction and retrofit projects. The opportunity lies in building specification support tools, performance documentation, and case-study evidence that translate technical performance into operational and financial outcomes for facility owners and engineering consultants. Companies that can connect PICV performance to energy modeling outputs, commissioning checklists, and ongoing monitoring will be better positioned to win specifications and reduce post-installation rejection risk.
Trend 2: Smart Hydronics And Data-Enabled Control
The integration of PICVs with building automation, energy measurement, and monitoring platforms will continue to deepen. This trend opens opportunities for manufacturers and solution providers to offer valves that are not just flow control devices but data-generating components within a broader operational intelligence framework. Features such as actuator compatibility, IoT readiness, and integrated energy measurement are likely to become standard expectations in commercial and increasingly in industrial applications. The commercial opportunity extends beyond hardware to include commissioning services, performance tuning, and software-enabled diagnostics that help operators sustain efficiency over the asset lifecycle. However, this trend also introduces risk if interoperability, data security, and support infrastructure are not addressed comprehensively.
Trend 3: Regional Divergence And Application Specialization
Regional and application-level divergence will create both opportunities and constraints. Asia Pacific's scale and ongoing infrastructure and building development activity present a large addressable market, but success there depends on local specification practices, distributor networks, and installer training. Europe's mature building stock and stringent energy standards support demand for retrofits and replacements, favoring manufacturers with strong technical documentation, certification, and service networks. North America's commercial segment remains a significant demand center, with data center and industrial applications gaining relevance as thermal control requirements intensify. In this environment, a one-size strategy is unlikely to succeed. Companies that align product ranges, certification, and support to regional requirements, and that develop application-specific offerings for sectors such as data centers, commercial high-rises, and industrial processing, will capture more defensible growth.
Risk Considerations
These opportunities are accompanied by risks that warrant strategic attention. Installer capability gaps can erode realized performance and weaken customer satisfaction, particularly in markets where technical training and commissioning support are under-resourced. Certification and compliance complexity may increase procurement timelines and raise costs for manufacturers operating across multiple jurisdictions. Material price volatility and supply chain disruptions can affect margins and lead times, especially for products relying on specialized polymers or insert technologies. Finally, as smart integration becomes more central, firms that fail to address interoperability, cybersecurity, and software support may face reputational and commercial consequences. Managing these risks will be as important as capturing the demand upside.
Strategic Guidance For Decision Makers
For Manufacturers
- Prioritize product architectures that balance flow range, sizing flexibility, and installation simplicity, reducing the need for separate balancing components while maintaining high rangeability and reliability.
- Invest in commissioning support, training assets, and clear documentation, including Environmental Product Declarations and certification alignment, to strengthen specification win rates and reduce post-installation performance gaps.
- Develop integration pathways with building automation and energy monitoring platforms that are transparent, interoperable, and supported by service commitments, turning hardware capability into long-term value.
For Investors
- Evaluate exposure not only by revenue scale but by alignment with structural demand drivers such as energy code tightening, smart building adoption, and application growth in data centers and industrial thermal control.
- Assess manufacturing resilience, material sourcing, and certification readiness as indicators of margin stability and risk management capability in a moderately concentrated market.
- Identify companies with credible technical differentiation, strong commissioning support, and regional execution strength, as these attributes tend to translate into more durable specification positions and customer retention.
For Procurement And Specification Teams
- Treat PICV selection as a system-level decision that should account for flow stability, commissioning ease, energy performance evidence, and integration requirements rather than unit price alone.
- Require robust performance documentation, certification alignment, and clear service commitments from suppliers to reduce variability across projects and improve long-term operational outcomes.
- Engage early with engineering and commissioning teams to ensure valve sizing, actuator compatibility, and building automation integration are addressed before procurement, minimizing rework and performance shortfalls.
The PICV market is moving through a phase where regulatory mandates, technological integration, and operational accountability are reshaping both demand and competition. For stakeholders seeking deeper segmentation, regional dynamics, application-level sizing, and customized strategic recommendations, PW Consulting's comprehensive PICV market report provides the detailed data and analysis needed to translate these trends into actionable plans.
For detailed analysis of this topic, please visit the official page: Pressure Independent Control Valves (PICV) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Overactive Bladder Treatment Market: Why 4.88% CAGR and Shifting Therapies Redefine Growth
By pmarketresearch, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Overactive Bladder Treatment Market
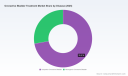
The overactive bladder treatment market has entered a phase of structural transition, moving beyond incremental drug innovation toward device-based interventions and more flexible care pathways. Total market revenue reached approximately $424 million in 2025, reflecting steady expansion from the $334 million recorded in 2020. Over the next seven years through 2032, the market is projected to grow at a compound annual growth rate of 4.88%, culminating in revenue of roughly $592 million. This trajectory signals a maturing landscape where value creation will increasingly depend on how well companies align product development, reimbursement positioning, and clinical adoption rather than on volume-driven generic substitution alone.
Despite the consistent upward revenue trend, the pace of growth and the distribution of value are being reshaped by several concurrent forces. Demographic aging continues to expand the addressable patient population, yet payer environments, guideline frameworks, and technology adoption patterns are introducing new decision points for manufacturers and investors. The market is no longer defined solely by pharmaceutical volume; it is becoming a contest over clinical differentiation, procedural convenience, and the ability to demonstrate clear patient and economic outcomes.
Three challenges are particularly prominent at this inflection point. First, the traditional reliance on anticholinergic therapies is being rebalanced by safety and tolerability considerations, prompting a slower but meaningful shift toward alternative mechanisms and procedural options. Second, reimbursement variability across care settings is influencing where and how treatments are delivered, especially for device-based therapies that require distinct coding, coverage, and site-of-care strategies. Third, the competitive field is consolidating around a smaller set of players with broad portfolios, even as targeted innovators continue to introduce niche solutions that test the boundaries of standard care models.
Key Drivers Reshaping Market Momentum
Several forces are driving the current evolution of the market, and their interplay is changing both the pace of adoption and the strategic priorities of participating companies.
Technology Innovation and Breakthroughs
Innovation momentum is strongest in two areas: refined pharmacologic options and minimally invasive neuromodulation. In pharmacotherapy, newer beta-3 adrenergic agonists have provided alternatives with more favorable tolerability profiles for patients who struggle with anticholinergic side effects. In device-based care, recent approvals and engineering improvements are reducing procedural burden and expanding access to sacral and tibial neuromodulation for urge incontinence and overactive bladder symptoms. These technologies are important not only because they offer additional treatment options, but because they create opportunities to segment patients by symptom severity, treatment history, and preference for drug-free management.
The practical implication is that clinical differentiation is becoming a more valuable asset than broad label coverage alone. Devices that simplify implantation, programming, or follow-up can accelerate adoption in clinical settings that previously hesitated due to complexity or resource requirements. Similarly, oral therapies that address specific patient subgroups, including those receiving concurrent treatment for benign prostatic hyperplasia, can unlock incremental demand in crowded therapeutic categories.
Policy and Regulatory Environment
Regulatory and guideline developments are actively reshaping treatment sequencing and payer behavior. Updated clinical guidelines from leading urology and pelvic floor societies have moved away from rigid step therapy requirements in favor of shared decision-making. This shift gives clinicians more latitude to select treatments based on patient profiles and preferences, which can accelerate the uptake of both newer drugs and procedural therapies in appropriate populations.
At the same time, reimbursement policy is exerting a powerful influence on site of care and technology uptake. Notably, CMS increased reimbursement by 40% in the ambulatory surgery center setting for a tibial nerve stimulation procedure, a change that can affect where patients receive care and how providers evaluate procedural investments. Regulatory milestones such as PMA approvals for integrated sacral neuromodulation systems also matter because they validate new device architectures and can expand the commercial footprint for companies pursuing differentiated procedural solutions.
Demand-Side Changes in Patient and Clinician Behavior
On the demand side, patients are increasingly seeking treatments that minimize systemic side effects and preserve quality of life. This preference is particularly relevant for long-term management, where adherence and tolerability determine real-world effectiveness. Clinicians, in turn, are responding to the combined influence of updated guidelines, richer outcome data, and practical workflow considerations. Shared decision-making is not merely a philosophical shift; it is changing the order in which therapies are discussed and selected, especially when patients present with comorbidities or prior treatment intolerance.
For commercial teams, this means that messaging and market access strategies must address real-world usability as much as efficacy. Treatments that are easier to initiate, monitor, and sustain are more likely to be prioritized in busy clinical environments, especially when they can be aligned with patient-centered goals and reimbursement realities.
Supply Chain and Cost Structure Dynamics
Cost structures across the market are being influenced by a combination of manufacturing complexity, procedural economics, and competitive pressure. Pharmaceutical segments face the usual balance between branded differentiation and eventual generic erosion, while device segments contend with the economics of implantation, training, service, and follow-up. In both cases, the value proposition increasingly depends on total cost of care rather than unit price alone.
This environment rewards strategies that can demonstrate downstream savings, reduce repeat interventions, or simplify the care pathway. For procedural technologies, site-of-care optimization and reimbursement alignment can be as important as the device itself. For drug therapies, lifecycle planning and patient-support programs can help protect share in categories where clinical alternatives are expanding.
Competitive Landscape and Leading Strategies
The market’s competitive structure reflects a blend of large established players, device specialists, and focused innovators. Market concentration remains moderate, with the top three companies accounting for roughly 40% of revenue and the top five approaching 50%, suggesting both the presence of influential incumbents and room for differentiated entrants.
Strategic Positioning of Leading Companies
Astellas Pharma has built a recognized position in overactive bladder pharmacotherapy through its marketed product for this indication. Its strategic emphasis has centered on brand presence in a therapeutic category where tolerability and adherence strongly influence long-term performance. In parallel, Sumitomo Pharma has advanced a newer oral branded option that received FDA approval in 2024 and was subsequently approved for men with overactive bladder symptoms receiving pharmacologic therapy for benign prostatic hyperplasia. This expansion illustrates a targeted approach to patient segmentation and label broadening rather than reliance on category-wide volume alone.
On the device side, Medtronic continues to underpin a substantial share of sacral neuromodulation offerings with SNM systems used in overactive bladder and urge incontinence care. The company’s recent FDA approval of a minimally invasive tibial neuromodulation device for urge incontinence broadens its procedural toolkit and reflects a strategy of addressing multiple points in the treatment pathway. Neuspera Medical has pursued a more focused device strategy, earning PMA approval in 2025 for an integrated sacral neuromodulation system for urinary urge incontinence. By combining system components into a more unified architecture, the company is attempting to differentiate on procedural integration and usability. BlueWind Medical contributes another device angle through its implantable tibial neuromodulation system, while Axonics Modulation Technologies has been recognized for its SNM system for overactive bladder and urge incontinence.
Recent Developments and What They Signal
Recent events point to a market that is consolidating at the high end while still encouraging specialized innovation. The acquisition of Axonics by Boston Scientific integrates sacral neuromodulation technology into a broader interventional portfolio, reinforcing the strategic value of neuromodulation as a platform rather than a standalone niche. At the same time, fresh regulatory approvals for tibial and integrated sacral neuromodulation devices indicate continued openness to new procedural options, particularly where they reduce complexity or expand patient access. The FDA approval milestones for vibegron in a BPH-adjacent population and for newer device architectures also suggest that label expansion and indication targeting are becoming central levers for growth.
Worldwide Hyperhidrosis Treatment Market
Market Structure Evolution
Three structural trends are shaping the competitive field. First, portfolio breadth is increasingly important, as companies that can offer both drug and procedural pathways, or multiple procedural modalities, are better positioned to serve varied patient needs and capture referrals across care settings. Second, differentiation through usability, integration, and clinical workflow is gaining importance alongside pure clinical performance. Third, focused innovators can still create value by solving specific adoption barriers, even in a market where larger players hold significant share. The overall direction is not toward a single dominant model, but toward a layered landscape in which pharmacological and device-based options coexist and compete on patient fit, reimbursement durability, and ease of implementation.
Worldwide Bladder Pump Market
Future Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to define where value is created and where risk accumulates.
Trend 1: Broader Use of Minimally Invasive Neuromodulation
Minimally invasive tibial and integrated sacral neuromodulation approaches are expected to play a larger role in treatment pathways, especially for patients seeking drug-free alternatives or those with insufficient response to medication. The commercial opportunity lies in simplifying adoption, aligning procedural economics with site-of-care realities, and demonstrating durable patient outcomes that support both clinical and payer acceptance. The key uncertainty is whether reimbursement and workflow advantages will be sufficient to drive broad, sustained uptake beyond early-adopter centers.
Trend 2: More Flexible Treatment Sequencing and Shared Decision-Making
Guideline shifts away from rigid step therapy toward shared decision-making are likely to persist, increasing the importance of patient-specific matching and clinician education. This creates opportunities for products that can be positioned as appropriate early options in selected patients, as well as for services that help providers navigate choice across drug and device pathways. The risk is that broader choice may also intensify comparison across therapies, making real-world evidence, tolerability, and total cost of care more central to purchase decisions.
PW Consulting Health Care Research Center
Trend 3: Portfolio Consolidation Paired with Targeted Innovation
The market is likely to continue seeing consolidation among larger device and pharmaceutical players seeking to assemble integrated portfolios, while smaller innovators pursue narrowly defined clinical or procedural problems. For investors and strategic planners, the important signal is that value will not be distributed uniformly. Companies that can combine differentiated technology with market access readiness, training support, and reimbursement strategy are more likely to convert innovation into durable share. The counterrisk is that promising technology may underperform commercially if adoption barriers, coverage gaps, or site-of-care economics are not addressed early.
Actionable Recommendations for Decision-Makers
Different stakeholders face distinct strategic priorities in this environment, but all benefit from a clear-eyed view of where adoption is likely to expand and where friction remains.
For Manufacturers and Product Developers
- Build differentiation around workflow and patient experience, not just mechanism of action. In device markets, procedural simplicity, programming burden, and follow-up requirements can influence adoption as much as clinical performance. In pharmacotherapy, tolerability, adherence support, and targeted label strategies can help defend position in competitive categories.
- Align market access and reimbursement planning with site-of-care realities. Reimbursement changes in ambulatory settings and variability across coverage environments can determine whether a technology scales quickly or remains limited to select centers. Early attention to coding, coverage, and site-of-care economics is essential.
- Invest in real-world evidence and clinician education that supports shared decision-making. As guidelines and practice patterns move toward more flexible treatment selection, providers will look for practical guidance on matching therapies to patient profiles and on comparing downstream outcomes and total cost of care.
For Investors and Strategy Teams
- Evaluate platforms as well as point products. Neuromodulation and drug-based care are both evolving toward broader pathway positioning. Companies that can span multiple patient segments or multiple modalities may have more resilient growth prospects than those dependent on a single indication or single procedural niche.
- Track regulatory and reimbursement catalysts as leading indicators of adoption speed. Recent approvals and reimbursement adjustments for procedural therapies demonstrate how quickly site of care and coverage changes can alter commercial potential. Monitoring these shifts can improve timing for diligence and partnership decisions.
- Differentiate between clinical promise and commercial readiness. Innovative devices and new oral therapies may address genuine unmet needs, but their trajectory will depend on reimbursement durability, training requirements, physician comfort, and competitive response. Due diligence should weigh adoption friction as closely as technology differentiation.
For Procurement and Payer Decision-Makers
- Assess total cost of care across options rather than focusing on unit price alone. For procedural interventions, consider training, follow-up, and site-of-care implications. For drug therapies, consider adherence, tolerability, and downstream utilization. A narrower price view can obscure the economic differences that matter most over the course of treatment.
- Prepare for more flexible treatment pathways. As guidelines and clinical practice move toward shared decision-making, evaluation frameworks should account for multiple appropriate treatment routes and the conditions under which each is likely to perform best.
- Monitor the interaction between coverage policy and technology adoption. Reimbursement changes can affect where care is delivered and which technologies become practical for broader use. Ongoing visibility into coding and coverage developments can improve planning for both access and budget forecasting.
Final Perspective
The overactive bladder treatment market is expanding at a steady pace, but the more important story is how value is being redistributed across therapies, platforms, and care settings. Revenue growth through 2032 will be supported by demographic demand and continued innovation, yet the companies and investors that benefit most will be those who can navigate reimbursement complexity, align products with practical workflow needs, and support more flexible, patient-centered treatment selection. Market concentration suggests that scale and portfolio breadth matter, but recent device approvals and targeted label expansions show that differentiated offerings can still create meaningful commercial traction.
For decision-makers seeking to act with confidence, the next step is to translate these directional signals into detailed, segment-level planning. Comprehensive segmentation data, regional comparisons, treatment-pathway dynamics, and company-specific positioning can sharpen strategic choices and reveal where to commit resources, where to partner, and where to watch for disruption. In a market where regulatory, reimbursement, and clinical-practice shifts can alter adoption trajectories quickly, deeper intelligence is not just helpful; it is a practical requirement for disciplined strategy.
For detailed analysis of this topic, please visit the official page: Overactive Bladder Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electronic Grade Hydrofluoric Acid Market: Why 6.98% CAGR Signals Strategic Shifts
By pmarketresearch, 2026-09-21
Electronic Grade Hydrofluoric Acid Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Snapshot: Scale, Trajectory, and Core Challenges
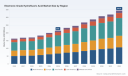
The electronic grade hydrofluoric acid sector has transitioned from a steady industrial chemical niche into a strategically critical supply chain component. Valued at approximately 163.15 million USD in 2020, the market reached 215.0 million USD by 2025 and is projected to expand to 344.8 million USD by 2032, reflecting a compound annual growth rate of 6.98 percent across the 2026–2032 forecast horizon. This trajectory signals more than incremental demand growth; it reflects a structural realignment in how advanced electronics manufacturers secure ultra-pure wet processing chemicals amid tightening quality thresholds and shifting sourcing strategies.
By the close of 2025, revenue concentration had consolidated meaningfully among established producers, with the top three firms capturing roughly 62.5 percent of global sales and the top five reaching 78.3 percent. This concentration pattern underscores two realities: first, the technical and regulatory barriers to producing semiconductor-grade acids remain steep; second, end-users increasingly prefer suppliers with validated purity consistency, localized manufacturing footprints, and audit-ready compliance frameworks.
Key Challenges and Inflection Points
Despite the favorable long-term demand curve, several structural pressures are reshaping supply planning and margin dynamics.
Raw material volatility and upstream cost transmission have emerged as a persistent margin management challenge. In April 2026, the spot price for Electronic Grade G5 material reached 110,000 RMB per ton, marking a 40 percent increase from the start of the year, while the annual average price of anhydrous hydrofluoric acid in the United States climbed to 2,565 USD per metric ton by March 2026 following quarter-over-quarter increases. Fluorspar mining also encountered restrictions, environmental inspections, and holiday-related disruptions in early 2026, reinforcing a stable-to-firm global pricing environment. For buyers and producers alike, these shifts complicate long-term cost modeling and require more agile procurement architecture.
Geopolitical risk is now a first-order pricing variable rather than a peripheral concern. In early 2026, friction around the Strait of Hormuz curtailed marine traffic by more than 90 percent, pushing Brent crude to 88.87 USD per barrel and inflating Chinese HF spot offers by 12 percent month-over-month. This episode highlighted how energy logistics, freight routing, and regional supply concentration intersect with electronic chemical pricing in ways that traditional cost models often underestimate.
On the production side, regional output fluctuations add another layer of unpredictability. By April 2026, electronic grade hydrofluoric acid production output in China registered a modest year-on-year decline amid broader operating conditions, even as downstream demand from semiconductor and display supply chains continued to strengthen. Such episodic divergences between production capacity utilization and end-market demand emphasize the importance of visibility into regional operating environments, not just headline capacity figures.
Collectively, these dynamics point to an inflection point where cost resilience, geographic diversification, and purity assurance are becoming decisive competitive levers rather than operational afterthoughts.
Key Demand Drivers: What Is Really Propelling the Market
The expansion of the electronic grade hydrofluoric acid market is not simply a function of more devices being built; it is driven by specific technological, regulatory, and structural shifts that alter how and where ultra-pure acids are consumed.
Technology Innovation and Purity Thresholds
Semiconductor wafer manufacturing remains the dominant consumption arena, and the technical demands of advanced nodes are steadily redefining acceptable impurity thresholds. As patterning, etching, and cleaning steps become more sensitive to particulate and metallic contamination, the distinction between standard electronic grade and ultra-high-purity grades takes on commercial weight. Producers that can demonstrate repeatable control over trace contaminants, supported by robust analytical certification and lot-to-lot consistency, are positioned to secure longer-term supply agreements with leading fabs. This technical premium is also encouraging dual-track supply strategies, where manufacturers maintain both standard and ultra-high-purity sourcing channels to protect yield performance across different process steps.
Policy and Regulatory Environment
Regulatory scrutiny and sustainability expectations are reshaping sourcing decisions. Environmental inspections and operational restrictions across key fluorspar and HF supply regions have tightened availability windows and reinforced pricing firmness. At the same time, broader energy and logistics disruptions have accelerated the preference for suppliers with transparent compliance records and regionally balanced production capabilities. For procurement teams, regulatory visibility is now part of supplier qualification rather than a separate risk register item. Markets where producers can demonstrate environmental diligence, controlled emissions, and stable energy sourcing are gaining a structural advantage in qualification cycles.
Demand-Side Shifts Across Electronics End Markets
Beyond semiconductors, adjacent electronics applications continue to contribute to demand breadth. Solar cell fabrication and display panel manufacturing represent substantial consumption pathways, and each carries its own pace of process refinement and capacity cycles. In solar, improvements in cell architecture and throughput efficiency influence wet chemical consumption intensity, while display manufacturing continues to depend on high-purity etching and cleaning steps for large-format panels. These diversified demand streams reduce single-market dependency for suppliers and create opportunities for those able to manage multiple purity specifications and delivery formats without sacrificing consistency.
Supply Chain and Cost Structure Dynamics
Cost structure evolution is being reshaped by both input economics and regional capacity responses. Upstream price movements have been pronounced: PTFE prices from major producers rose 15–16 percent in March 2026, the steepest increase since 2024, reflecting how input cost pressure can propagate quickly into fluorine-based chemical value chains. Meanwhile, regional production expansions aim to improve supply assurance for local electronics clusters. One notable example is the expansion activity near a major rail line in Casa Grande, where an acquisition of additional land was announced to support scaled production and direct supply to nearby semiconductor manufacturers. Such localized capacity additions illustrate how logistics adjacency and regional customer proximity are increasingly integrated into supply strategy, not just production volume.
The net effect is a market in which cost leadership alone is no longer sufficient. Suppliers that combine disciplined input cost management with geographic flexibility, grade-specific capability, and transparent logistics planning are more likely to convert demand growth into durable contract wins.
Competitive Landscape and Leading Strategies
The competitive environment in electronic grade hydrofluoric acid reflects a blend of specialized fluorine chemistry manufacturers, diversified industrial suppliers, and regional players with strong local customer relationships. Leadership in this space is increasingly defined by grade coverage, supply reliability, and the ability to operate at the intersection of high-purity chemistry and regional demand clusters.
Strategic Positioning Among Key Players
Firms with deep fluorine chemistry heritage continue to anchor the market through specialized purification expertise and broad grade portfolios. Morita Chemical Industries and Stella Chemifa, both based in Osaka, Japan, maintain strong positions by focusing on high-purity fluoride chemicals and ultra-high-purity hydrofluoric acid for semiconductor etching and display applications. Their longstanding technical reputation provides a credibility advantage in qualification-heavy environments, where purity consistency and documentation rigor often outweigh short-term price differentials.
In the United States, supply strategies are increasingly oriented around regional security of supply and direct fab proximity. Honeywell International has reinforced its position with ultra-high-purity electronic grade solutions, including Puranal grades, for wafer cleaning and etching, alongside dedicated Texas production capacity. Sunlit Arizona, LLC, based in Phoenix, operates a facility capable of supplying up to 30 kilotons per year of electronic grade hydrofluoric acid directly to U.S. semiconductor fabs. Its April 2026 expansion move, involving the acquisition of additional acreage near a major rail line in Casa Grande, further demonstrates a logistics-integrated approach designed to support scaled production for local chip manufacturers. KMG Chemicals, headquartered in Dallas, contributes a distribution and supply footprint that broadens access to electronic grade material across semiconductor and electronics manufacturing channels.
European players preserve a strong specialty chemical orientation. Solvay, based in Brussels, produces high-purity hydrofluoric acid for semiconductor wafer etching and display panel applications, emphasizing integration into broader fluorochemical portfolios and established industrial reliability.
Chinese manufacturers represent a rapidly maturing segment with expanding technical capabilities and a growing emphasis on local electronics supply chains. Do-Fluoride Chemicals in Jiaozuo, Henan, produces high-purity electronic grade acid for microelectronics and semiconductor wet processing. Jiangyin Jianghua Microelectronics Materials, in Jiangsu, supplies ultra-clean electronic chemicals including high-purity hydrofluoric acid for semiconductor, LCD, and solar cell manufacturing. Zhejiang Juhua, operating as part of a broader fluorochemical portfolio in Zhejiang, has also expanded electronic grade hydrofluoric acid production for semiconductor applications. These players are increasingly relevant not only for cost-competitive supply but also for regional responsiveness and the ability to serve domestic electronics clusters at scale.
How the Landscape Is Evolving
The market structure is moving toward a hybrid model: concentration among proven high-purity suppliers continues, but regional capacity additions and localized supply relationships are creating more diversified sourcing pathways. This pattern favors suppliers that can offer credible purity credentials while also aligning with regional demand centers and logistics realities. It also encourages integration across production, distribution, and customer-facing technical support, since end-users are increasingly evaluating the full service package rather than the molecule alone.
At the same time, cost pressure and input volatility are testing margin discipline across the value chain. Producers that can manage upstream cost shocks, pass through pricing transparently where justified by specification and reliability, and maintain capacity utilization in the face of episodic regional output fluctuations are better positioned to protect profitability through the cycle.
Forward Outlook: Three Trends to Watch (2026–2031)
Looking ahead, the electronic grade hydrofluoric acid market is likely to be shaped by a small number of powerful forces that connect technology roadmaps, supply assurance priorities, and cost dynamics.
Electronic Grade Phosphoric Acid Market
Trend 1: Purity as a Standard Procurement Criterion, Not a Premium Feature
As advanced semiconductor processes and high-value display and solar processes continue to tighten contamination tolerance, the distinction between grades will increasingly become a baseline procurement requirement rather than a specialty upsell. Suppliers that invest in analytical rigor, lot traceability, and grade-specific process control are likely to capture a larger share of long-cycle agreements. The commercial opportunity lies in building qualification-ready documentation and consistency narratives that reduce buyer risk and accelerate source approval.
PW Consulting Chemical & Energy Research Center
Trend 2: Regionalization of Supply and Logistics-Advantaged Capacity
Demand for proximity, resilience, and predictable delivery is reinforcing regional capacity strategies. Expansion near customer clusters and major transport corridors is likely to remain a strategic priority, particularly where semiconductor manufacturing density is growing. The commercial opportunity is twofold: producers can secure stronger local contracts, and buyers can reduce exposure to long-haul logistics risk. However, regionalization also raises the importance of disciplined capacity planning, because localized supply advantages can be eroded if utilization or input availability becomes unstable.
Trend 3: Cost Volatility Becoming a Core Strategic Management Discipline
Input price movement, logistics shocks, and regulatory interruptions are likely to remain part of the operating environment. The recent pattern of sharp raw material price increases, energy-driven spot offer inflation, and episodic production output changes suggests that cost resilience will be judged as a strategic capability, not merely an accounting outcome. Companies that develop diversified sourcing, scenario-based pricing, and transparent cost communication will be better equipped to sustain customer trust during volatile periods. The associated risk is that firms without flexible cost structures may face margin compression or contract instability when input shocks recur.
Strategic Recommendations for Decision-Makers
Translating market dynamics into action requires differentiated approaches depending on the role a company plays in the value chain.
For Producers and Chemical Manufacturers
Invest in grade differentiation as a commercial moat. The ability to reliably deliver ultra-high-purity and VLSI-grade options, supported by strong quality documentation and stable lot performance, can create defensible positioning in qualification-heavy accounts. Pair this with regional capacity logic that aligns production with major electronics clusters and transport infrastructure, so that supply assurance becomes a visible customer benefit rather than an internal operational metric. Maintain disciplined cost management for upstream inputs and develop transparent pricing mechanisms that preserve trust when raw material conditions shift quickly.
Electronic Grade Nitric Acid Market
For Investors and Strategic Capital Allocators
Focus on business models that combine purity credibility with regional supply relevance and resilient input economics. Assets tied to high-purity electronics demand, especially where localized supply and logistics advantages can be demonstrated, are likely to capture more durable value than undifferentiated volume plays. Monitor the interplay between regional capacity additions, input cost trends such as fluorspar availability and anhydrous HF pricing, and episodic output changes in key production regions, because these factors will influence both top-line growth and margin stability. Prioritize visibility into operating conditions, not just announced capacity, when evaluating companies in this space.
For Procurement and Supply Chain Leaders
Treat purity assurance, regional availability, and cost volatility together rather than as separate sourcing variables. Diversify across proven high-purity suppliers and regionally responsive partners to reduce single-source exposure, and integrate logistics adjacency into supplier evaluation criteria where possible. Build scenario planning into procurement strategy so that rate negotiations and supply agreements can absorb raw material swings, energy-driven freight cost changes, and regulatory interruptions more effectively. In this environment, detailed intelligence on grade availability, regional operating conditions, and input cost direction can materially improve contract structure and risk allocation.
Closing Perspective
The electronic grade hydrofluoric acid market is expanding with a clear underlying logic: advanced electronics processing continues to demand cleaner, more reliable wet chemical supply, while cost, logistics, and regulatory pressures are forcing more sophisticated supply strategies. The combination of steady demand growth, rising purity expectations, and regional supply realignment is creating opportunities for companies that can deliver both technical reliability and supply resilience. At the same time, input volatility and geopolitical exposure remind the market that volume growth alone does not guarantee margin security.
For organizations making sourcing, production, or investment decisions in this space, the most valuable next step is to move from broad market direction to granular visibility: grade-level demand shifts, regional capacity and operating conditions, raw material cost trajectories, and the strategic positioning of key suppliers. Detailed segmentation data, supplier-level assessments, and customized scenario planning can turn these broad trends into actionable, risk-adjusted decisions.
For detailed analysis of this topic, please visit the official page: Electronic Grade Hydrofluoric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Air Blowers Market: Mining & Manufacturing Demand Behind 5.5% CAGR to 2032
By pmarketresearch, 2026-09-21
Strategic Shifts in the Global Air Blowers Market: Navigating Growth, Efficiency Mandates, and Competitive Realignment
Market Overview: Steady Expansion Amid Structural Complexity
The global air blowers market has demonstrated consistent growth over the past half-decade, with industry revenue reaching approximately 215 million USD in 2025, up from 163.15 million USD in 2020. The trajectory reflects a compound annual growth rate of 1.4 percent across the forecast window extending to 2032, with projected valuations surpassing 344 million USD by the end of the period. This measured pace masks underlying volatility in demand patterns, regional execution, and technology adoption cycles that shape how companies allocate capital and position their product portfolios.
The market is characterized by moderate concentration, with the top three players capturing roughly 40 percent of total revenue and the top five approaching 60 percent. This structure suggests a competitive arena where established multinational manufacturers maintain scale advantages in distribution, service networks, and compliance capabilities, while regional specialists and emerging entrants compete on customization, speed, and localized engineering support. The presence of both broad-product-line incumbents and application-focused niche providers creates a layered competitive environment where buyers evaluate total cost of ownership, reliability under specific operating conditions, and alignment with evolving efficiency mandates.
Several inflection points are reshaping how value is created and captured. First, regulatory frameworks governing industrial fan and blower efficiency are tightening across major economies, shifting procurement criteria from upfront price toward lifecycle energy consumption and maintainability. Second, supply chain volatility in steel and precision components has pressured cost structures, forcing manufacturers to reconsider sourcing strategies, inventory buffers, and vertical integration decisions. Third, application-side buyers are increasingly integrating air movement equipment into broader automation and process-optimization initiatives, which elevates expectations for connectivity, diagnostics, and repeatable performance. Together, these forces are pulling the market away from commoditized equipment transactions toward solutions that deliver measurable operational savings and regulatory compliance.
Core Growth Drivers: Technology, Policy, Demand, and Supply Chain
Technology Innovation and Performance Breakthroughs
Advancements in blower design are centering on three interrelated objectives: higher aerodynamic efficiency, lower noise and vibration profiles, and improved adaptability to variable operating conditions. Manufacturers are refining impeller geometries, optimizing aerodynamic pathways, and integrating control systems that modulate output to match real-time demand. These developments matter because air blowers frequently run continuously in wastewater treatment, pneumatic conveying, and process aeration, where even modest efficiency gains compound into significant energy savings over equipment lifecycles.
Oil-free configurations have gained particular attention in food processing, pharmaceuticals, and environmental applications, where contamination risk and product integrity drive procurement decisions. Companies offering oil-free rotary lobe, screw, and regenerative designs are positioning these platforms as default choices for sensitive processes, reducing the need for downstream filtration and simplifying maintenance routines. At the same time, high-speed and centrifugal variants continue to serve heavier-duty duties where reliability, pressure stability, and throughput dominate specification criteria.
PW Consulting
The 2026 trade show circuit underscored this technology emphasis. Exhibitors at IFAT 2026 in Munich and IFAT India 2026 in Mumbai highlighted efficient air movement solutions designed for environmental, wastewater, and process-air applications. These appearances signaled not only product momentum but also a strategic focus on sectors where efficiency, compliance, and process reliability converge. For manufacturers, the takeaway is clear: differentiation increasingly depends on demonstrating measurable performance under realistic operating conditions rather than competing solely on catalog breadth.
Policy and Regulatory Environment
Regulatory pressure is becoming a defining force in market dynamics, particularly where motor power ranges intersect with industrial fan and blower usage. In the European Union, the Ecodesign Regulation 2024/1834 for industrial fans and blowers covering 125-500 kW motors introduces stricter performance requirements, repairability provisions, and load and speed testing protocols. The mandatory application date of 24 July 2026 places compliance timelines in sharp focus for manufacturers selling into Europe and for buyers who must justify equipment selections against evolving standards.
In the United States, the Department of Energy finalized new energy conservation standards for fans and blowers with updated efficiency requirements published in January 2024. These standards reinforce NA companies’ expectations that air movement equipment will need to meet formalized efficiency benchmarks, influencing design priorities, product line planning, and the value proposition of retrofitting versus replacing aging installations.
These policy developments create a dual effect. For manufacturers, they raise the bar for engineering and documentation while offering a credible basis for premium positioning when efficiency and serviceability are proven. For buyers, they reduce the ambiguity around what constitutes acceptable performance and increase the strategic importance of selecting equipment that will remain compliant through its service life. In practice, regulatory momentum is accelerating the shift from incremental purchasing decisions to longer-cycle planning where total energy cost, maintenance access, and documentation readiness carry greater weight.
Demand-Side Changes in Buyer Behavior
Demand patterns are shifting as end-users treat air blowers less as standalone components and more as integrated elements of process reliability and cost control. Mining and manufacturing continue to represent substantial application volumes, with air movement supporting ventilation, pneumatic conveying, aeration, and process gas handling. Food processing industries also contribute meaningfully, where hygiene, oil-free operation, and stable pressure delivery align with production quality requirements. Across these sectors, the common thread is an increasing reluctance to accept performance variability, especially in facilities where unplanned downtime carries high financial and operational consequences.
Procurement behavior reflects this mindset. Buyers are requesting more detailed performance data, broader operating envelopes, and clearer documentation of maintenance and serviceability characteristics. They are also more attentive to noise levels, footprint constraints, and integration with existing control architectures. This is particularly visible where automation initiatives are expanding. Labor shortages in manufacturing have driven demand for automated blower production lines to sustain efficiency, and on the end-user side, that same automation push encourages equipment choices that reduce manual intervention and simplify supervision.
Worldwide Hand Held Blower Market
Trade show participation from multiple companies during 2025 and 2026 further illustrates demand-side evolution. Demonstrations at events such as Best Practices 2025 EXPO & Conference and regional automation and plastics exhibitions emphasized on-site utilities, process air, and automation-compatible blower arrangements. These showcases indicate that end-users are exploring bundled or application-tailored solutions that fit into broader facility upgrades rather than purchasing generic equipment in isolation.
Supply Chain and Cost Structure Pressures
Steel remains the primary raw material for industrial blower housings and impellers, and sector analysis from 2025 points to persistent supply chain volatility affecting input costs. This reality places continuous pressure on margin management and pricing strategies, particularly for manufacturers with limited flexibility in sourcing or limited ability to pass through cost changes without eroding competitiveness.
Compounding the material challenge is the labor dimension. Automation labor shortages in manufacturing are prompting higher demand for automated blower production lines to maintain efficiency. For equipment producers, this means investment in production automation is no longer solely an elective productivity improvement; it is increasingly part of the cost-structure response to skilled-labor constraints and throughput expectations. On the buyer side, the same dynamics push demand toward equipment that supports consistent output with reduced manual oversight.
A notable external factor is the continued strength of export activity from China, where industrial blower exports rose 15 percent year-over-year in the first quarter of 2026. This increase reflects strong global demand and highlights the role of export-oriented manufacturers in shaping availability, pricing, and competitive intensity across multiple regions. For market participants, the implication is that cost discipline, design efficiency, and service differentiation will remain central to defending position even as supply expands.
Roots Blower Market
Competitive Landscape and Strategic Positioning
The competitive field spans global manufacturers with broad industrial portfolios and specialized providers with deep application knowledge. This mix creates opportunities for different strategic plays, depending on whether a company competes through scale, application expertise, service proximity, or technology differentiation.
Atlas Copco has built a recognizable position around oil-free industrial and aeration blowers, including ZL Lobe and NEOS variants intended for low-pressure applications in wastewater, food processing, and pneumatic conveying. The emphasis on oil-free solutions in sensitive and regulated environments supports a value proposition anchored in cleanliness, compliance support, and process safety. Aerzen Maschinenfabrik GmbH offers oil-free rotary lobe blowers focused on industrial aeration, wastewater, and process gas handling, aligning closely with applications where contamination avoidance and steady process conditions are paramount.
ebm-papst emphasizes process air, circulation, and drying blowers for industrial HVAC and energy-efficient applications, positioning itself where efficiency and integrated airflow management are central to customer priorities. Twin City Fan Companies provides a full-spectrum range of air moving equipment, including centrifugal and axial blowers for industrial ventilation and process applications, appealing to buyers who value breadth and engineering flexibility across multiple duty cycles. Kaeser Kompressoren contributes oil-free screw blowers and positive displacement offerings for industrial air supply and aeration, reinforcing its broader compressed-air and air-supply ecosystem play.
Ingersoll Rand focuses on industrial blowers for compressed air systems and pneumatic conveying in manufacturing, where reliable throughput and integration with plant air systems are key purchasing criteria. Gardner Denver and Howden both address heavier-duty uses: Gardner Denver through rotary lobe and centrifugal blowers for industrial aeration and process gas applications, and Howden through high-efficiency centrifugal blowers for heavy-duty industrial and energy sectors. A1 Blowers India Pvt. Ltd. and Inovair Blowers represent more regionally or operationally oriented profiles, with A1 emphasizing industrial air blowers, vacuum boosters, and engineered air solutions for manufacturing, and Inovair emphasizing centrifugal and axial blowers with vertical manufacturing to support timely industrial delivery.
Several strategic themes emerge from this landscape. First, product focus is increasingly tied to application outcomes rather than generic specifications. Companies that articulate clear value in wastewater aeration, food-grade processes, pneumatic conveying, or HVAC efficiency are better positioned to command loyalty and pricing power than those competing primarily on hardware parity. Second, service and documentation capability is becoming a competitive differentiator as efficiency standards and repairability expectations rise. Third, regional presence and delivery reliability matter where engineering support, lead-time consistency, and local troubleshooting can outweigh marginal hardware price differences.
Recent event activity reinforces the importance of visible market engagement. A1 Blowers India’s exhibit at IFAT India 2026, Nitto Kohki’s appearance at IFAT 2026 alongside pumps for environmental and energy applications, Elektror Group’s participation with industrial blowers for process air, Sahara Air Products’ demonstration of on-site utilities including blowers for automation, and Air Deviser Industrial’s showcases in automation and plastics exhibitions all point to a market where suppliers are actively targeting application-specific audiences. This pattern suggests continued segmentation by end-use and an emphasis on demonstrating fit within real operating environments rather than relying solely on broad catalog positioning.
The market is likely to see continued evolution along two paths. On one hand, larger multinational players may pursue selective integration, acquiring application-focused capabilities or strengthening service and digital-support functions to widen their value proposition. On the other hand, specialized manufacturers can thrive by deepening expertise in high-priority niches such as oil-free process air, wastewater aeration, and automation-compatible equipment layouts. New entrants and export-oriented producers will continue to test price-sensitive segments, but sustainable advantage will increasingly depend on the ability to prove efficiency, reliability, and compliance readiness in the field.
Future Outlook: Three Strategic Trends for the Next Three to Five Years
Efficiency as a Procurement Default, Not a Differentiator
As efficiency regulations take hold and energy costs remain a persistent concern, high-efficiency performance will transition from a selling point to a baseline expectation. This does not eliminate differentiation, but it shifts the basis of competition toward how clearly a manufacturer can validate performance, support repairability, and document compliance across operating conditions. Companies that invest early in test protocols, transparent performance reporting, and service-friendly designs will be better positioned to navigate purchasing scrutiny and reduce the risk of disqualification during specification reviews. The commercial opportunity lies in helping buyers quantify lifecycle savings and link equipment selection to broader energy and sustainability targets.
Application-Centric Bundling and Process Integration
Demand is moving toward solutions that fit into integrated process and automation plans rather than isolated component purchases. This trend favors suppliers that can combine appropriate blower types with control strategies, installation guidance, and service arrangements tailored to specific duties such as wastewater aeration, pneumatic conveying, food processing airflow, and industrial ventilation. The strategic implication is a shift from product catalogs to application packages, where the value proposition includes performance stability, integration ease, and reduced operational oversight. Manufacturers that build application engineering competence and strengthen field-support capabilities can capture more wallet share by becoming trusted partners in facility upgrades and process optimization projects.
Regional Demand Divergence and Supply-Side Realignment
Regional demand will likely continue to diverge in pace and priorities. Asia Pacific and North America represent substantial market bases, while Europe’s regulatory-driven efficiency focus creates distinct specification requirements. Latin America and the Middle East and Africa remain meaningful but more varied in their application mixes and procurement maturity. At the same time, export strength from Chinese manufacturers and ongoing steel cost volatility will keep pressure on global pricing and availability. Over the next three to five years, companies that can align production footprint, sourcing flexibility, and regional service presence with local demand profiles will be better equipped to manage risk and capture growth. A key uncertainty is how quickly regulatory implementation, energy price trajectories, and raw material conditions will interact, potentially compressing margins for players that cannot adapt product portfolios or cost structures with sufficient speed.
Actionable Guidance for Decision-Makers
For manufacturers and product leaders, the priority is to align engineering roadmaps with emerging compliance and efficiency expectations while reinforcing application-specific value. Invest in verifiable performance data, serviceability features, and control capabilities that support variable-duty operation. Strengthen production automation where labor constraints threaten throughput, and evaluate sourcing strategies for steel and precision components to reduce exposure to volatility. In go-to-market terms, emphasize application outcomes and lifecycle cost rather than catalog breadth alone, and prepare documentation that helps procurement teams justify selections under tighter efficiency scrutiny.
For investors and strategic planners, the market offers opportunities in companies that combine credible efficiency performance with application depth and service readiness. Favor business models that can demonstrate repeatable value in wastewater, food processing, pneumatic conveying, and industrial ventilation, particularly where regulatory momentum and automation trends increase the importance of reliability and documentation. Monitor competitive dynamics carefully: export-led price pressure, raw material swings, and selective consolidation can shift the attractiveness of different subsegments. The most resilient upside typically comes from players that can convert compliance and efficiency requirements into differentiated offerings rather than absorbing them as pure cost burdens.
For procurement and operations leaders, treat blower selection as a lifecycle decision with regulatory, energy, and integration implications. Specify equipment using documented efficiency performance and operating envelopes that match actual process variability, and include serviceability and maintenance access in evaluation criteria. Where facility upgrades or automation initiatives are underway, consider bundled solutions that reduce integration risk and support consistent supervision. Keep close attention to evolving standards and testing requirements, as early alignment can shorten specification cycles and reduce the chance of rework or replacement later in the asset life.
Detailed segmentation data, company-level benchmarks, and region-specific demand patterns can sharpen these decisions further. For executives and planning teams seeking a more granular view of subsegments, application mixes, and competitive positioning, the full PW Consulting market report provides expanded data and tailored analysis to support investment, product, and procurement strategies.
For detailed analysis of this topic, please visit the official page: Air Blowers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
XLPE Foam Market 2026: Why 6.8% CAGR Alone Misses the Real Growth Drivers
By pmarketresearch, 2026-09-21
The Cross-linked Polyethylene Foam Market: Navigating Growth, Pressure, and Strategic Positioning
Market Context and Core Challenges
The cross-linked polyethylene (XLPE) foam sector has matured into a structurally important materials segment, with global revenue expanding from approximately $163 million in 2020 to a projected $342 million by 2032. The trajectory reflects sustained demand across multiple downstream industries, with a compound annual growth rate of 6.8 percent over the 2026–2032 horizon. This baseline trajectory masks a more nuanced reality: growth is uneven across applications, value capture is shifting, and manufacturers are operating in an environment where technical differentiation must be paired with cost discipline and compliance agility.
Several structural inflection points are reshaping how incumbents and new entrants think about XLPE foam. First, energy-code tightening in major construction jurisdictions is elevating performance expectations for insulation products. Specifications for below-grade and crawlspace assemblies now routinely require higher R-value retention and moisture resistance, favoring closed-cell formulations that hold dimensional stability under prolonged exposure. This shifts demand toward grades that were previously treated as premium or specialized options, compressing the gap between standard commodity SKUs and engineered variants. Second, the cost base for custom fabrication has become a visible strategic variable. Die-cutting, molding, and one-off tooling for industrial and automotive components elevate labor and setup costs, forcing fabricators to decide whether to absorb complexity internally or move toward standardized, high-runner geometries that preserve margin. Third, regulatory clarity around recycled content and food-contact documentation is accelerating procurement screening in Europe and select North American supply chains. High-purity traceability requirements are no longer a niche concern; they are becoming a prerequisite for entering certain packaging and healthcare-adjacent applications. Together, these pressures are converting XLPE foam from a generally interchangeable cushioning material into a performance-classified input where formulation, documentation, and fabrication capability all influence win rates.
Key Drivers Shaping the Market
Technology and process innovation are redefining what XLPE foam can deliver. Irradiation and electron-beam crosslinking have expanded the range of achievable cell structures, improving balance between flexibility, shock absorption, and thermal behavior. In parallel, thermoforming-grade developments are extending the material into higher-volume forming workflows, where manufacturers seek recyclable formats that still preserve protective performance. These advances are not simply product features; they change end-use economics by enabling lighter assemblies, fewer secondary components, and more predictable tolerances in precision gaskets and composite interfaces. Where these grades are adopted, they tend to unlock value not only through material substitution but through downstream assembly savings that buyers increasingly factor into specification decisions.
Policy and regulatory signals are acting as both gatekeeper and growth catalyst. In construction, updated energy codes and moisture-resistance expectations are reinforcing the case for closed-cell XLPE in assemblies where durability and thermal continuity matter. In packaging, EU requirements around high-purity documentation for recycled-content materials in food-contact contexts are raising the bar for traceability and lot control. These rules do not uniformly slow adoption; instead, they reward operators with disciplined quality systems and penalize those that treat compliance as an afterthought. The practical effect is a two-speed market: applications with stringent documentation and performance demands consolidate around suppliers that can deliver repeatable certifications, while price-sensitive commodity uses remain more exposed to substitution and margin erosion.
Demand-side behavior is shifting as well. Lightweight construction in renewable-energy nacelles and high-speed rail composite panels is driving interest in low-density, high-integrity foam cores and interlayers. Automotive programs continue to prioritize weight reduction and acoustic comfort, pushing XLPE into interiors, gaskets, and component protection where form, fit, and long-term resilience are critical. At the same time, brand owners and industrial purchasers are increasingly weighing total installed cost rather than unit price alone, which benefits suppliers that can demonstrate reliability, short lead times, and consistent lot-to-lot performance. One-day availability in select North American operations, for example, is becoming a competitive lever in prototypes and short-run programs where schedule risk outweighs minor material savings.
Supply chain and cost structure changes reinforce the need for portfolio discipline. Raw resin volatility, energy costs, and labor intensity in custom fabrication all pressure margins, especially for specialized die-cut or molded parts. In response, some operators are expanding extrusion capacity to improve throughput and reduce per-unit processing risk, while others are diversifying into grades that support higher-value fabrication rather than competing solely on roll, bun, and sheet volume. The market is therefore rewarding companies that align capacity investments with application mix: insulation and packaging volumes support scale, while automotive, healthcare, and precision industrial uses justify tighter process control and faster customization.
Competitive Landscape and Strategic Positioning
The competitive set spans global material developers, regional extrusion specialists, and custom fabricators, each competing on a different combination of formulation ownership, fabrication capability, and service model. Zotefoams operates from a global platform with a portfolio of closed-cell crosslinked polyolefin foams, including XLPE grades designed for packaging, industrial gaskets, and thermal insulation. Its strategic advantage lies in brand continuity across applications, which supports specifier trust in programs that value material consistency across geographies and product families. Armacell positions itself around closed-cell XLPE foam lines and custom fabrication pathways for insulation, packaging, and automotive use, emphasizing application engineering and flexibility in converted solutions. Sekisui Chemical contributes a distinct irradiation-crosslinked portfolio through Volara and Minicel, with relevance in automotive, healthcare, and protective packaging, where controlled cell structure and cleanliness are important. Toray Plastics complements the field with electron-beam crosslinked XLPE foam sheets targeted at gaskets, composites, automotive interiors, and high-precision applications, reflecting a strategy oriented toward engineered sheet formats and tight tolerance work.
Regional and fabrication-focused players add a different layer of value. Worldwide Foam illustrates the capacity-driven route, with a second extruder moving into trial runs to expand throughput for XLPE foam and reduce delivery risk in North American markets. Atlas Foam Products, AM Foam, Merryweather Foam, and Flextech Foam demonstrate the importance of custom fabrication, die-cutting, and contract manufacturing in translating rolls and buns into specification-ready components. CYG TEFA represents the scale manufacturing option from China, serving insulation, packaging, and building materials with a volume-oriented model. Across these profiles, the differentiating axis is not simply who produces the most foam, but who can reliably convert a base material into a finished, certified, application-specific outcome with acceptable lead time and documentation rigor.
Phenolic Foam Board Market
The landscape is evolving along two complementary lines. In one direction, integration is increasing between raw foam production and conversion capability, because customers in automotive, construction, and healthcare increasingly prefer fewer handoffs, clearer accountability, and better control over dimensional consistency and surface quality. In the other direction, specialization is intensifying around grade families and end-use performance, especially where recyclable thermoforming formats, high-shock-absorption variants, and moisture-resistant insulation grades create more defensible positioning. New entrants are most likely to succeed where they can address a visible gap: faster short-run availability, more disciplined documentation for regulated applications, or a particular grade optimized for lightweight composite assemblies. At the same time, differentiation based purely on volume pricing is becoming riskier, as buyers in performance-sensitive segments place greater weight on reliability, traceability, and total delivered value.
Forward-Looking Trends and Commercial Opportunities
One clear direction for the next three to five years is the continued migration of XLPE foam from generic cushioning toward performance-classified roles in construction, mobility, and renewable-energy assemblies. As energy codes and lightweighting objectives become more prescriptive, insulation and composite-foam applications should benefit from stronger specification pull. The commercial opportunity here is not simply more volume, but a shift toward engineered grades that command higher margins, repeat orders, and longer program lifecycles. Manufacturers that can offer consistent thermal and moisture behavior, along with reliable documentation, are better positioned to capture these programs than those competing primarily on commodity price.
High Density Microcellular Polyurethane Foam Market
A second trend is the growing emphasis on recyclability and formability without sacrificing protective performance. Thermoforming-grade developments and shock-absorption innovations are expanding the material’s reach into higher-value packaging and forming workflows, where brands want lighter, more sustainable structures but cannot compromise on impact protection or dimensional stability. The opportunity lies in pairing material innovation with process compatibility: if a grade can be formed efficiently, recycled or reprocessed responsibly, and still meet performance thresholds, it becomes a preferred option in programs that face both sustainability targets and engineering constraints. This is especially relevant where buyers are balancing regulatory documentation requirements with the need for repeatable production outcomes.
A third trajectory is the increasing importance of supply reliability and customization economics. Capacity expansions, one-day availability models, and tighter fabricated part pipelines matter more as programs shorten, prototypes move faster, and procurement teams evaluate lead-time risk alongside unit cost. For fabricators, the commercial question is whether to standardize common geometries, invest in tooling that supports higher volumes, or retain custom flexibility at a premium. The most resilient operators tend to blend both approaches: share standardized platforms to absorb volume consistently, while reserving custom capability for applications where performance or regulation justifies the added complexity. Potential risks include raw-material price swings, regional energy-cost divergence, and the chance that overly ambitious recycled-content claims outpace documentation readiness or downstream acceptance. Companies that move too slowly on compliance systems, or too aggressively into grades without clear end-use validation, may find themselves squeezed between better-documented competitors and buyers who reduce specification risk by consolidating suppliers.
PW Consulting
Strategic Actions for Decision Makers
For material producers and fabricators, the priority is to align grade portfolios and capacity investments with the applications where performance differentiation is most valued. If construction insulation and moisture-resistant assemblies are expanding under tighter codes, ensure that closed-cell grades and conversion options support those specifications reliably. If automotive and lightweight composite demand is rising, prioritize sheet formats, tolerance control, and documentation that reduce integration risk for design engineers. Where custom fabrication drives margin, evaluate whether standardizing high-runner geometries can lower labor intensity while preserving bespoke capability for premium programs. The practical lesson is to treat specification security and delivery reliability as margin enablers, not just service features.
For investors evaluating exposure to the XLPE foam space, the most durable value creation is likely to come from operators that combine scale with application discipline. Volume growth alone is not a sufficient thesis, because commodity applications remain exposed to substitution and price pressure. A more robust view focuses on whether a target can defend margins through formulation ownership, conversion capability, documentation readiness for regulated uses, and a mix that includes construction, automotive, and renewable-energy-driven demand rather than relying heavily on a single volume category. Capacity expansion can be positive, but only if it is matched to demand mix and supported by the operational controls needed to protect yield and lead-time performance.
For procurement teams and specification engineers, the strategic move is to evaluate XLPE foam selections through a broader lens than unit cost. Consider total installed performance, moisture and thermal behavior in the intended assembly, documentation availability for regulated or food-contact-adjacent uses, and the supplier’s ability to support prototypes and short runs without excessive schedule risk. Where possible, reduce fragmentation by qualifying suppliers that can cover both base material and converted components, or by structuring relationships that give reliable access to performance grades while maintaining competitive tension on commodity SKUs. In practice, the strongest purchasing strategies balance cost control with specification certainty, because program delays and rework often outweigh marginal savings on material price alone.
Closing Perspective
The XLPE foam market is moving from broad availability to more selective value creation. Growth is real, but it is increasingly concentrated in applications where performance, compliance, and delivery reliability matter enough to justify engineered grades and tighter fabrication models. That shift gives manufacturers an opportunity to defend margins through specification relevance and service consistency, gives investors a framework for separating scale plays from durable application-focused operators, and gives buyers a stronger reason to evaluate total value rather than headline price. For organizations seeking a more granular view of regional demand patterns, type-level splits, application sizing, competitive benchmarks, and customized strategic scenarios, a full market study can provide the segmentation detail and structured analysis needed to support investment, sourcing, and product-portfolio decisions.
For detailed analysis of this topic, please visit the official page: Cross-linked Polyethylene Foam (XLPE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Life Science Reagents Market: Why 4.95% CAGR and Clinical Diagnostics Shifts Reshape Strategy
By pmarketresearch, 2026-09-21
The Life Science Reagents Market: Strategic Shifts and Commercial Opportunities Through 2032
The global life science reagents market reached USD 44.24 billion in 2025, building on a decade of steady expansion from USD 35.0 billion in 2020. Growth is projected to continue through the forecast period, with the market expected to reach USD 61.0 billion by 2032. This trajectory reflects a compound annual growth rate of approximately 4.95 percent, signaling a mature but still expanding sector. The pace of growth, however, masks significant underlying shifts in how reagents are developed, manufactured, regulated, and deployed across research, diagnostics, and bioprocessing workflows.
Market expansion is no longer driven solely by volume increases in traditional laboratory supplies. Instead, value creation is concentrating around precision reagents, integrated diagnostic platforms, and specialized inputs for cell and gene therapy development. Clinical diagnostics remains the largest application segment, while drug discovery and genetic research continue to anchor demand from pharmaceutical and biotechnology sponsors. The geographic distribution of revenue reflects entrenched demand in developed markets, though emerging regions are gradually increasing their share as local research infrastructure and diagnostic capacity expand.
Beneath these aggregate figures, the industry is navigating a period of structural transition. Pricing power is uneven, supply dependencies are being reevaluated, and regulatory harmonization is forcing operational changes that extend well beyond compliance departments. For executives and investors, the opportunity lies in understanding where differentiation is achievable, where consolidation is accelerating, and where emerging demand vectors will outpace supply.
Market Context and Core Challenges
The life science reagents sector operates at the intersection of academic research, clinical testing, and commercial biomanufacturing. Its customer base spans large pharmaceutical companies, contract research and manufacturing organizations, hospital laboratories, and academic institutions. This breadth provides resilience, but it also introduces complexity in product development, quality standards, and go-to-market models.
Several structural challenges are reshaping how companies compete:
- Input dependency and cost volatility. Production of critical enzymes, buffers, and specialty biochemicals remains concentrated among a limited number of upstream suppliers. Disruptions in this layer transmit quickly into reagent pricing and lead times, particularly for companies that rely heavily on imported intermediates.
- Regulatory synchronization and documentation burden. The alignment of quality management requirements with internationally recognized standards is raising the bar for documentation, software validation, and audit readiness. Organizations that viewed compliance as a periodic exercise are now facing continuous operational adjustments.
- Portfolio complexity versus scale. Reagent manufacturers must balance breadth of catalog with depth of performance validation. Broad portfolios attract academic and routine diagnostic buyers, but high-value contracts increasingly demand application-specific validation, lot-to-lot consistency, and regulatory-grade documentation.
These challenges are not independent. Supply concentration amplifies the cost impact of regulatory changes, while portfolio complexity increases the operational load of maintaining compliance across multiple product lines. The companies that navigate this environment effectively are those that treat supply resilience, quality systems, and application support as interconnected capabilities rather than separate functions.
A second layer of tension comes from the shifting endpoint use of reagents. Historically, many reagent categories were optimized for research flexibility. Today, a growing share of demand originates from workflows that feed directly into clinical decisions, bioprocess validation, or regulated product release. That shift changes the value proposition: buyers care less about catalog breadth and more about traceability, reproducibility, and compatibility with standardized platforms.
Key Drivers Reshaping the Market
Technical Innovation and Platform Convergence
Innovation in reagents is increasingly tied to platform-level performance rather than isolated chemical improvements. Digital PCR, advanced immunoassay formats, and enzyme-based workflows are expanding the precision and throughput of both research and diagnostic applications. The commercial impact is visible in product launches that pair reagents with dedicated instrumentation or standardized workflows, creating more integrated value propositions.
Recent platform activity illustrates this direction. One major diagnostics and life science supplier expanded its digital PCR assay portfolio with a broad set of new tests on an existing partitioning platform, reinforcing the link between reagent availability and instrument adoption. In a parallel move, another manufacturer introduced specialized ddPCR kits targeting adeno-associated virus serotypes, reflecting the growing need for precise quantification tools in gene therapy development and quality control. These examples show how reagent innovation is being engineered around specific workflow bottlenecks rather than generic laboratory needs.
For commercial strategy, this trend rewards companies that can combine reagent performance with clear application support, validated protocols, and compatibility with widely used instrumentation. Standalone catalog products face stiffer competition when buyers can obtain equivalent performance inside a supported workflow.
Regulatory Change as a Competitive Filter
Regulatory dynamics are no longer a background condition; they are actively reshaping vendor selection and internal operating models. Harmonization efforts that synchronize quality management expectations with established international standards are compelling companies to upgrade documentation, software controls, and training processes. The effect is twofold. First, compliance costs are rising across the board. Second, the relative burden is heavier for smaller or less organized suppliers, which can tilt purchasing decisions toward vendors with mature quality infrastructure.
Laboratory Chemical Reagents Market
In practice, this means regulatory readiness is becoming a commercial asset. Buyers in clinical and bioprocessing settings increasingly view documented quality systems, validated software, and predictable audit performance as part of the reagent value proposition. Suppliers that treat these capabilities as strategic differentiators can command preference even when pricing is not the lowest.
PW Consulting
Demand-Side Shifts in Therapeutics and Diagnostics
The upstream demand environment is being reshaped by three interrelated forces: continued investment in drug discovery, growth in genetic and proteomic research, and expanding clinical diagnostic throughput. Drug discovery and genetic research remain strong anchors for reagent consumption, but the fastest commercial pressure is emerging where diagnostic workflows scale and where advanced therapies require specialized reagents for process development and release testing.
This demand mix is changing buying behavior. Clinical and bioprocessing buyers are looking for suppliers who can support lot consistency, documentation, and workflow integration. Research buyers still value breadth and flexibility, but they are also increasingly sensitive to supply reliability after several years of volatile availability across life science inputs. The net effect is a market where reliability and application support are becoming as important as unit price.
Supply Chain Reconfiguration and Cost Structure
The cost structure of reagent manufacturing is being reexamined as companies reassess dependency on concentrated upstream sources for enzymes, buffers, and other critical inputs. Reliance on a narrow supplier base in specific geographies creates exposure to logistics disruption, regulatory changes at the source, and price sensitivity when demand spikes. As a result, some manufacturers are diversifying sourcing, building additional buffer inventory for critical components, or investing in closer oversight of upstream quality.
This reconfiguration is not simply a contingency measure. It is increasingly part of commercial positioning. Suppliers that can demonstrate more predictable lead times, transparent sourcing practices, and resilient inventory management gain credibility with customers whose own production or testing schedules cannot tolerate variability. In a market growing at a steady but not explosive pace, reliability can be a stronger differentiator than incremental cost savings.
Competitive Landscape and Leading Strategies
The market is moderately concentrated, with a meaningful share of revenue held by a limited group of large, diversified suppliers. This concentration supports scale advantages in manufacturing, quality systems, and global distribution, but it also leaves room for specialized players to compete on application focus, regional presence, or workflow integration. The competitive dynamics are best understood by looking at how leading companies position themselves across research, diagnostics, and bioprocessing.
Large diversified suppliers such as Thermo Fisher Scientific, Merck KGaA, Danaher Corporation, Becton, Dickinson and Company, Roche Holding AG, Agilent Technologies, bioMérieux, Bio-Rad Laboratories, Promega Corporation, QIAGEN, PerkinElmer, Waters Corporation, and Lonza Group compete on multiple fronts. Their strategic advantages generally include broad product portfolios, established quality and regulatory infrastructure, global reach, and the ability to bundle reagents with instruments, kits, or services. Several of these companies also benefit from portfolio expansion through acquisition, which allows them to enter or deepen specific application areas more quickly than organic development alone would permit.
Specialized or regional-focused players add an important layer of competition. Bio-Techne Corporation and Maravai LifeSciences Holdings, Inc. illustrate a different strategic posture: deep focus on selected reagent categories, nucleic acid and enzyme-based solutions, antibody-related offerings, and support for advanced therapy and diagnostic development. These companies often compete by building strong application expertise, targeted customer relationships, and agile product development in niches where broader suppliers may be less differentiated.
Competitive positioning is increasingly defined by three choices:
- Breadth versus depth. Broad portfolios support cross-selling and reduce customer switching, but depth in high-value applications can create stronger loyalty and pricing resilience.
- Workflow integration versus component supply. Companies that align reagents with instrumentation, kits, or validated protocols can strengthen stickiness, while component suppliers must compete on performance, availability, and support.
- Global scale versus regional responsiveness. Scale Helps with cost and consistency, but regional presence can matter for service speed, regulatory localization, and customer intimacy.
Market evolution is being shaped by both consolidation and selective new entry. Recent activity shows how these forces are playing out. In distribution, partnerships are extending reach for specialized reagent portfolios without requiring full infrastructure build-out. In product strategy, ongoing assay and kit launches are reinforcing platform-based competition. In M&A, portfolio acquisitions are being used to secure intellectual property, enzymes, or antibody-related assets that strengthen a supplier’s position in high-demand workflows. One diversified supplier, for example, expanded its transfection reagent capabilities through acquisition, while another major player strengthened its antibody and reagent supply through a completed acquisition that consolidated presence in a strategically important category.
At the same time, new entrants are appearing where technological or application gaps create opening points. One molecular biology-focused company announced entry into the molecular biology and clinical diagnostic reagents market, signaling that platform expertise and targeted capability can still open doors even in a concentrated landscape. The broader implication is that the market is not static: incumbents retain advantages in scale and infrastructure, but differentiation remains possible through application focus, workflow alignment, and strategic partnerships.
Future Trends and Commercial Implications
Trend 1: Workflow-Embedded Reagents Will Capture Disproportionate Value
Over the next three to five years, reagents that are tightly integrated with validated workflows, dedicated instruments, or standardized kits are likely to command a growing share of commercial value. The reason is straightforward: as applications move toward clinical, bioprocess, and regulated environments, buyers prioritize reproducibility and support over isolated catalog purchases. Companies that can offer reagents as part of a reliable workflow will be better positioned to protect pricing and deepen customer relationships.
The commercial opportunity lies in designing reagent portfolios around specific end-use cases rather than around chemical categories alone. This includes pairing reagents with clear protocols, compatibility information, and application support that reduces integration risk for the buyer. It also includes thinking in terms of instrument-ecosystem alignment, where reagent availability reinforces platform adoption and vice versa.
Trend 2: Quality and Supply Resilience Will Become Purchase Criteria, Not Back-Office Functions
Regulatory harmonization and upstream supply concentration are pushing quality systems and supply reliability into the foreground of purchasing decisions. Buyers are increasingly likely to evaluate suppliers not only on product performance but also on documentation readiness, software validation maturity, and the ability to maintain consistent supply for critical inputs. This shift raises the stakes for suppliers that depend on fragile upstream chains or underdeveloped quality infrastructure.
For manufacturers, the strategic response is to treat quality and supply resilience as market-facing capabilities. That can mean diversifying critical inputs, strengthening inventory planning for high-impact components, and making quality documentation more accessible and transparent to customers. Suppliers that communicate these capabilities clearly may find them becoming part of the commercial rationale for selection.
Trend 3: Targeted Expansion and Partnerships Will Outpace Broad-Based Growth Alone
As market growth settles into a steady trajectory, pure volume expansion will matter less than targeted scaling in high-value segments. The most relevant opportunities are likely to arise in specialized enzyme and nucleic acid solutions, advanced diagnostic assay support, and reagents tied to cell and gene therapy workflows. In this environment, acquisitions, asset purchases, and distribution partnerships can be faster paths to capability than organic build-out, especially when they add intellectual property, validated assays, or regional reach.
At the same time, new entry remains possible where a company can bring a distinct technical angle or an underserved application focus. The presence of recent market-entry announcements and distribution partnerships suggests that the barrier to participation is not uniform across segments. Companies that can identify pockets where workflow needs are growing faster than supplier depth may find commercially meaningful openings.
Risks and Uncertainties
These trends are not without risk. Regulatory timelines can shift the burden of compliance faster than some suppliers can retool documentation and software systems. Upstream dependency may continue to create cost and availability shocks if diversification lags. Workflow integration can also intensify competitive pressure, since platform-based offerings can marginalize standalone reagents that lack clear compatibility or support. Finally, demand concentration in diagnostics and advanced therapies can create pockets of strong growth, but it also introduces exposure to changes in therapeutic pipelines, testing volumes, and reimbursement or procurement dynamics.
The overarching uncertainty is whether growth will remain broad-based or increasingly selective. If buying behavior continues to favor workflow-embedded, quality-ready, and supply-resilient solutions, then differentiation will depend less on catalog size and more on execution in targeted segments. That outcome would reward disciplined portfolio strategy and penalize diffuse expansion.
Strategic Recommendations for Decision-Makers
For Reagent Manufacturers and Suppliers
Focus portfolio strategy on application depth in segments where workflow integration and regulatory-grade support are becoming purchase requirements. Rather than spreading resources evenly across all categories, prioritize the reagent lines that connect to high-value diagnostics, drug discovery support, genetic research tools, and bioprocessing needs. Strengthen upstream visibility for critical enzymes and buffers, and treat supply resilience as a commercial message rather than an internal contingency plan. Where acquisition, asset purchase, or distribution partnership can close a capability gap more quickly than organic development, evaluate those options against the cost of missing a window in a growing segment.
For Investors and Strategic Buyers
Assess exposure to workflow-embedded demand and regulatory readiness when evaluating opportunities in this market. Companies with strong quality systems, instrument-aligned reagent portfolios, and credible supply strategies are better positioned to defend margins and customer relationships than those competing primarily on catalog breadth or price. Pay attention to consolidation patterns, especially where acquisitions add enzymes, antibodies, assay IP, or bioprocessing-relevant capabilities. Equally important, watch for signs of new entry in specialized niches, since targeted competition can reshape pricing and share even in a moderately concentrated market.
For Procurement and Sourcing Leaders
Treat reagent selection as a balance of performance, documentation, and supply predictability. Where workflows support clinical decisions, bioprocess validation, or regulated release, prioritize suppliers that can provide consistent lot performance, clear quality documentation, and stable availability for critical inputs. Diversification of supplier base for high-impact reagent categories can reduce exposure to upstream volatility, while closer alignment with suppliers that offer validated workflows may lower integration risk and operational overhead. In practice, the lowest unit cost is not always the lowest total cost when variability, rework, or supply disruption are included.
Closing Perspective
The life science reagents market is moving from a phase defined by broad demand growth to one shaped by where value is created within specific workflows, regulatory contexts, and supply chains. Aggregate expansion remains healthy, but the more important question for decision-makers is no longer how large the market will become by 2032. It is which capabilities will separate durable suppliers from transactional ones as quality expectations rise, upstream dependencies are scrutinized, and buyers increasingly purchase outcomes rather than isolated components.
Detailed segmentation data, company-level benchmarks, regional demand patterns, and scenario analysis can sharpen these strategic choices further. Additional intelligence is available through PW Consulting’s complete market research report, which provides a more granular view of the segments, competitors, and forward scenarios discussed here.
Life Science Instruments & Reagents Market
For detailed analysis of this topic, please visit the official page: Life Science Reagents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Welding Equipment Market: 6.5% CAGR Growth and Strategic Shifts Redefining Revenue Trajectories to 2032
By pmarketresearch, 2026-09-21
Welding Equipment Market: Strategic Trends and Commercial Opportunities Through 2032
The welding equipment market stands at a convergence of structural growth, technological disruption, and regulatory recalibration. Valued at approximately $22.5 billion in 2025, the sector has expanded from $15.5 billion in 2020, reflecting a compound annual growth rate of 6.5 percent across the 2026–2032 forecast horizon. This trajectory is not merely incremental; it signals a fundamental shift in how welding is deployed, automated, and regulated across industrial ecosystems. For executives, investors, and procurement leaders, the market presents a dual narrative: steady macroeconomic demand anchored in infrastructure and manufacturing, juxtaposed against acute labor constraints, compliance complexity, and rapid technological substitution. Understanding where value is migrating—and why—requires moving beyond headline revenue figures to examine the operational, technological, and policy forces reshaping the competitive landscape.
PW Consulting
Market Context and Structural Challenges
The broader market trajectory demonstrates consistent expansion, but the composition of that growth reveals underlying tensions. Arc welding continues to dominate revenue contribution, while emerging processes such as laser beam welding and precision resistance systems are gaining share in specialized fabrication and high-throughput environments. The geographic distribution of demand reflects divergent industrial priorities: mature economies are prioritizing equipment upgrades and automation retrofits, while high-growth regions are driven by capacity expansion in heavy engineering, infrastructure, and mobile manufacturing. Meanwhile, the application landscape remains anchored by automotive, building and construction, and heavy engineering, though railway, shipbuilding, and niche fabrication segments are accelerating as fleet modernization and energy transition projects enter execution phases.
Three structural challenges define the current inflection point.
- Workforce displacement and skill scarcity. The industry faces a projected shortfall of hundreds of thousands of qualified welders by the end of the decade. This gap is not cyclical; it reflects demographic attrition, training bottlenecks, and the increasing technical complexity of modern welding processes. The consequence is a structural push toward collaborative robotics, semi-automated cells, and process digitization, but adoption remains uneven across small and mid-sized fabricators.
- Regulatory fragmentation and compliance recalibration. Welding equipment and processes are subject to an expanding matrix of product safety standards, calibration and verification requirements, and sector-specific qualification rules. Harmonization is advancing in some jurisdictions, yet divergent national implementations and proposed rule changes in critical infrastructure segments are creating compliance uncertainty. Manufacturers and end users must navigate overlapping standards that affect certification timelines, equipment selection, and operational auditability.
- Procurement economics and capital deployment cycles. End-user budgets are increasingly constrained by inflation in component costs, energy volatility, and financing conditions. Fabricators and contractors are forced to weigh upfront equipment investment against long-term total cost of ownership, particularly as automation, consumables efficiency, and predictive maintenance become meaningful differentiators. This dynamic is reshaping purchasing behavior, with greater emphasis on multi-process flexibility, lifecycle service agreements, and demonstrable productivity gains rather than unit-price competition alone.
Core Demand Drivers
Technological Innovation and Process Substitution
The most consequential driver is the ongoing redefinition of welding capability through automation, advanced power electronics, and hybrid process integration. Collaborative welding robots and adaptive handheld systems are moving from pilot deployments to routine fabrication floor usage, particularly in environments where skilled labor is scarce or where mixed-model production demands rapid changeover. Laser beam and hybrid laser-arc solutions are expanding the envelope of applicability in high-precision joining, thin-gauge materials, and heat-sensitive alloys. At the same time, equipment manufacturers are embedding software layers that enable parameter control, data capture, and process verification, shifting welding from a craft-dominant operation to a more standardized, repeatable manufacturing process. These advances are not replacing welding; they are compressing skill dependency, improving consistency, and expanding the range of projects that can be executed profitably.
Policy, Standards, and Infrastructure Mandates
Regulatory and standards activity is functioning as both a constraint and a catalyst. Updated harmonized standards for welding equipment and revised calibration and verification requirements are increasing the emphasis on traceability, process control, and documented qualification. In parallel, proposed changes to qualification and inspection practices in certain pipeline and compressor station segments are tightening the criteria under which welders and processes are deemed acceptable. For capital-intensive sectors such as heavy engineering, energy infrastructure, and defense-related fabrication, these developments raise the bar for equipment selection and operator certification. The market response is twofold: manufacturers are engineering for compliance-driven features and documentation support, while end users are accelerating the adoption of automated and semi-automated solutions that reduce variability and simplify audit readiness.
Demand-Side Shifts in End-Use Sectors
Demand is being reshaped by investment cycles in transportation, construction, and heavy industrial modernization. Automotive production continues to require high-volume joining across mixed material portfolios, including lightweight alloys and mixed-material assemblies that demand precise heat input control. Building and construction activity sustains steady equipment utilization, particularly for structural fabrication, field welding, and on-site assembly where portability and durability matter. Heavy engineering and railway and shipbuilding segments are driven by fleet renewal, component replacement, and specialized fabrication where weld integrity, metallurgical control, and throughput are paramount. The common thread across these sectors is a growing preference for equipment that can operate across multiple process modes, integrate with data systems, and support consistent output under variable conditions.
Supply Chain and Cost Structure Evolution
The cost equation for welding operations is being recalibrated by component availability, energy considerations, and the economics of automation. Fabricators are increasingly evaluating total cost of ownership rather than purchase price, factoring in consumables efficiency, downtime risk, service availability, and the labor productivity impact of automation. Supply chain pressures have heightened the value of equipment robustness, service networks, and flexible financing options. At the same time, the economics of collaborative welding cells and modular automation are improving as hardware costs decline and deployment complexity is reduced through preconfigured solutions. This is altering the investment calculus for mid-tier fabricators that previously viewed automation as out of reach, creating a broader base of potential adopters and a wider competitive field for equipment providers.
Competitive Landscape and Strategic Positioning
The market remains moderately concentrated, with leading players commanding meaningful share while retaining room for differentiation through application specialization, automation integration, and regional service depth. The competitive architecture is defined less by uniform product breadth and more by targeted capability, ecosystem positioning, and speed in translating new process capabilities into field-ready solutions.
Leading Players and Differentiation Paths
Lincoln Electric has built its positioning around advanced arc welding systems, collaborative cobots, aluminum MIG capabilities, and fabrication automation. Recent product introductions have extended this footprint into aluminum-focused MIG systems and adaptive collaborative welding platforms, signaling a focus on material-specific process needs and labor-augmentation solutions. Miller Electric Mfg. LLC continues to emphasize multiprocess flexibility, engine-driven portability for field and heavy-duty use, and collaborative robotic systems that support mixed-production environments. Its portfolio orientation reflects an emphasis on versatility across job shop, field, and production settings.
ESAB has advanced its presence in heavy industrial and pipeline applications through equipment, automation, and cutting solutions, with product lines designed for demanding service conditions and high-throughput fabrication. A major acquisition move in the sector has reinforced the industry’s direction toward consolidation around automation and advanced process control capabilities. Fronius International GmbH has concentrated on precision MIG/MAG and TIG equipment, collaborative welding cells, and automation for fabrication environments where repeatability and process control are critical. EWM GmbH has built a profile around TIG/MIG/MMA machines, automation solutions, and software-enabled process management, aligning equipment capability with digital integration for industrial users. Hobart Welding Products remains focused on construction and general fabrication through MIG platforms, engine-driven models, and a broad accessory ecosystem, emphasizing practicality, durability, and field readiness.
Engine-Driven Welders Market
Market Structure Evolution
The competitive map is evolving along three vectors. First, consolidation is accelerating around automation, software, and process verification capabilities, as larger players absorb specialized competencies to strengthen end-to-end offerings. Second, differentiation is increasingly driven by application-specific engineering—aluminum welding, field portability, precision fabrication, heavy industrial throughput—rather than generic product breadth. Third, new entrants and technology-focused suppliers are gaining traction in handheld laser welding, collaborative cells, and digital process tools, particularly where they can address labor scarcity and changeover intensity. The net effect is a market in which scale, service networks, and application expertise intersect with technology adoption cycles, creating both opportunities for incumbents to deepen moats and openings for focused innovators to capture niche advantage.
Strategic Outlook: Trends and Commercial Signaling
Automation as a Standard Operating Layer
Over the next three to five years, collaborative welding, modular automation cells, and adaptive process control are likely to transition from selective adoption to baseline capability in a broadening range of fabrication environments. The driver is structural: labor constraints, consistency requirements, and the economics of mixed-model production are aligning to make automation a practical response rather than a premium option. Commercial opportunity lies in solutions that reduce deployment friction, support rapid changeover, and integrate with existing shop-floor workflows. The risk is that automation value is overstated where change management, training, and process redesign are underinvested, leading to underperformance and stalled adoption cycles.
Process Diversification in High-Value Joining
Laser-based and hybrid joining methods are expected to gain incremental share in applications that demand precision, reduced heat input, and compatibility with advanced materials. These processes will not displace conventional arc welding broadly, but they will expand the toolkit for sectors where joint quality, material sensitivity, and throughput are decisive. The commercial implication is a growing need for equipment portfolios that can span conventional and advanced processes, along with consumables, parameter support, and training that match the chosen process. Uncertainty remains around equipment cost, operator skill requirements, and the pace of qualification acceptance across industries and regions.
Compliance-Linked Purchasing and Service Intensity
As standards and qualification expectations tighten, procurement decisions are increasingly influenced by documentation support, calibration alignment, and service reliability. Equipment that facilitates traceability, parameter consistency, and audit-ready operation will carry a growing premium in regulated and mission-critical segments. The related opportunity is in service models, lifecycle support, and software-enabled maintenance that reduce compliance burden and operational risk. A key uncertainty is the speed and uniformity of regulatory implementation, which can shift demand patterns regionally and create uneven adoption timelines.
Actionable Guidance for Decision Makers
For Equipment Manufacturers and Solution Providers
- Strengthen application-specific engineering and validation support, particularly for aluminum welding, field- portable heavy-duty use, and precision fabrication, where process expertise can differentiate beyond hardware specifications.
- Accelerate integration of collaborative automation and process data capabilities into mainstream product lines, targeting deployment simplicity and changeover agility rather than only high-end automation niches.
- Build service, training, and compliance-documentation support as core commercial elements, since lifecycle value and audit readiness are increasingly part of the purchasing equation.
For Investors and Strategic Capital Allocators
- Evaluate exposure to automation adoption curves, handheld and hybrid process technologies, and software-enabled process control, where value creation is tied to labor economics and consistency gains rather than unit volume alone.
- Monitor consolidation activity and capability transfers in automation, precision welding, and digital process management, as these moves can reshape competitive positioning and margin profiles.
- Assess regional demand drivers and regulatory trajectories separately, since market growth and compliance-linked purchasing can diverge significantly across geographies and end-use sectors.
For Procurement Leaders and End Users
- Shift evaluation criteria toward total cost of ownership, incorporating consumables efficiency, downtime risk, service proximity, and the productivity impact of automation or multi-process flexibility.
- Prioritize equipment and partner capabilities that reduce variability and support qualification or audit readiness, especially in infrastructure, heavy engineering, and regulated fabrication contexts.
- Plan for workforce adaptation alongside equipment investment, ensuring training, change management, and process documentation are funded and sequenced with deployment to realize projected gains.
The welding equipment market is moving toward a more technology-dense, compliance-aware, and labor-constrained operating environment. For decision makers, the strategic task is to align equipment choices, automation roadmaps, and service models with the specific demands of their application mix and regional context. Detailed segment-level sizing, competitive benchmarking, and scenario analysis can sharpen those decisions, and the full research report provides the deeper data architecture and customized guidance needed to translate these market-level insights into operational strategy.
Welding Helmets Market
For detailed analysis of this topic, please visit the official page: Welding Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Corporate Secretarial Services Market 2026: Beyond the 5.2% CAGR Story
By pmarketresearch, 2026-09-21
Navigating the Corporate Secretarial Services Market: Strategic Shifts and Emerging Opportunities
The corporate secretarial services landscape is undergoing a structural transformation driven by regulatory complexity, technological adoption, and evolving corporate governance expectations. Global revenue in this space reached approximately USD 1,435 million in 2025, up from USD 1,180 million in 2020, reflecting a compound annual growth rate of 5.2 percent through the 2032 outlook horizon. This growth trajectory is not uniform; it reflects a sector where routine compliance tasks are increasingly automated while high-value governance advisory, cross-border entity management, and risk mitigation services command premium positioning. For executives and investors, the market presents a dual narrative: steady top-line expansion paired with rapid shifts in how services are delivered, priced, and differentiated.
Market Landscape and Core Challenges
The corporate secretarial services market operates at the intersection of legal compliance, administrative governance, and strategic advisory. Over the past five years, revenue growth has consistently outpaced broader professional services benchmarks, yet the expansion masks underlying pressures that demand strategic attention. The sector's value is increasingly concentrated in complex jurisdictions, multinational entity structures, and organizations that cannot sustain in-house compliance teams at scale. This dynamic creates both opportunity and vulnerability for service providers and corporate buyers alike.
Regulatory Velocity and Compliance Gaps
One of the most persistent challenges is the pace of regulatory change. Directors and corporate secretaries must navigate an environment where filing requirements, governance standards, and disclosure obligations evolve faster than internal processes can adapt. Recent amendments to audit exemption frameworks and corporate governance enforcement provisions have introduced immediate compliance implications, altering statutory filing calendars and expanding the scope of director accountability. Simultaneously, broader corporate registry reforms in key markets have imposed transition periods that require updated entity documentation, enhanced beneficial ownership tracking, and revised board oversight procedures. Organizations that rely on reactive compliance workflows face elevated risk of late filings, governance lapses, or reputational exposure.
Cost Pressure and In-House Efficiency Gaps
A second structural pressure stems from the cost of maintaining compliance capabilities internally. As entity structures become more layered and regulatory expectations intensify, corporations are reassessing whether fully owned secretarial teams provide the most efficient path. The complexity of multi-jurisdiction operations, fluctuating staffing costs, and the need for specialized regulatory knowledge are pushing organizations toward outsourced or hybrid operating models. This shift is not simply about cost reduction; it reflects a strategic decision to redirect internal resources toward core business activities while leveraging external expertise for statutory adherence, governance administration, and risk tracking.
Share Registry Services Market
Technology Integration and Workflow Fragmentation
The third challenge lies in the uneven pace of digital transformation across the sector. While cloud-based entity management platforms and AI-enhanced tracking tools are increasingly referenced in advanced markets, many organizations still operate with fragmented workflows, manual document control, and siloed compliance calendars. The gap between early adopters and laggards creates operational inefficiencies and inconsistent compliance quality. Service providers that can unify statutory tracking, board administration, document automation, and regulatory intelligence into cohesive workflows are gaining traction, while legacy models struggle to justify premium pricing for purely administrative services.
Core Drivers Shaping Market Dynamics
The market's direction is shaped by a combination of technological, regulatory, demand-side, and cost-structure forces. Each driver reinforces the others, creating a cycle where complexity fuels outsourcing, outsourcing accelerates technology adoption, and technology enables stronger governance outcomes.
Worldwide Company Secretary Tool Market
Technology Innovation and Automation
Digital tools and automation are redefining what corporate secretarial services can deliver. Cloud-based entity management systems now support continuous compliance monitoring, automated filing reminders, digital board pack generation, and centralized document repositories. AI-assisted workflows are increasingly used for statutory tracking, contract review support, and regulatory change alerts. These capabilities reduce manual error rates, shorten turnaround times, and enable service providers to manage larger portfolios with greater consistency. In markets where regulatory evolution is rapid, such as advanced Asian financial hubs, cloud-enabled and AI-enhanced tools have accelerated the shift toward real-time governance administration and digital board meetings. The strategic implication is clear: technology is moving from a back-office enabler to a core differentiator that shapes service quality, scalability, and pricing power.
Regulatory and Governance Environment
Regulatory changes continue to be the most influential driver of demand. Amendments affecting audit exemptions, corporate governance enforcement provisions, and registry transparency requirements have expanded the compliance burden for directors and corporate secretaries. In the UK context, for example, recent reforms have created transition periods that require organizations to update governance documentation and strengthen preparedness for directors facing new filing and oversight expectations. These regulatory shifts do more than increase paperwork; they alter the compliance risk profile of companies and elevate the importance of proactive governance administration. Providers that can combine regulatory interpretation, practical implementation support, and ongoing monitoring are better positioned to capture demand from organizations seeking to reduce exposure to compliance failures.
Demand-Side Shifts in Corporate Behavior
Corporate behavior is changing in ways that expand the addressable market. Companies are increasingly viewing corporate secretarial functions not as a static administrative task but as a governance capability that supports board effectiveness, investor confidence, and operational resilience. Large corporations with complex legal entity structures need consistent oversight across jurisdictions, while small and medium enterprises require affordable, reliable compliance support to scale without governance breakdowns. Micro enterprises, meanwhile, often seek streamlined formation and basic compliance services that lower the barrier to formal incorporation. This segmentation of demand encourages providers to design service tiers that balance cost efficiency with depth of support, and it creates opportunities for specialized offerings in entity management, governance advisory, and shareholder administration.
Cost Structure and Outsourcing Economics
Cost dynamics are reinforcing the shift toward managed services. The rising complexity of entity structures and regulatory requirements increases the difficulty of maintaining fully in-house compliance teams, especially for organizations operating across multiple jurisdictions. Outsourced corporate secretarial services offer a pathway to reduce fixed compliance costs, access specialized expertise, and scale service capacity as business needs evolve. This economic logic is particularly compelling for firms that want to avoid the overhead of recruiting, training, and retaining niche compliance talent while still meeting statutory obligations. The result is a growing preference for service models that combine predictable pricing with flexible coverage, especially where compliance failures carry material financial or reputational consequences.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of global professional networks, specialized corporate service providers, and niche players with strong regional or sector focus. The market remains moderately fragmented, with the largest three players holding a combined share near 28 percent and the top five approaching 42 percent. This concentration indicates room for consolidation while also reflecting the practical realities of jurisdiction-specific licensing, regulatory knowledge, and client trust.
Strategic Positioning of Leading Players
PwC and Deloitte leverage broad professional service ecosystems to offer integrated corporate secretarial and entity management capabilities alongside regulatory compliance support across numerous jurisdictions. Their advantage lies in the ability to connect secretarial services with wider governance, tax, audit, and advisory offerings, creating cross-sell opportunities and a unified client experience. KPMG and Mazars pursue similar integration strategies, with strong emphasis on managed services, statutory compliance, and governance support delivered through global networks. These firms benefit from brand recognition, multinational reach, and the credibility that comes from operating across the full spectrum of corporate/advisory services.
Vistra and TMF Group represent the specialized end of the spectrum. Vistra focuses on corporate secretarial services, entity administration, and regulatory compliance for international clients, often serving organizations that require consistent handling across multiple jurisdictions. TMF Group emphasizes corporate secretarial services, trust administration, and compliance solutions for regulated entities, positioning itself around depth in regulated structures and operational execution. Citco narrows the focus further by specializing in corporate secretarial and management services for regulated entities such as hedge funds and private equity, where governance requirements and investor expectations are particularly stringent.
Other players add important dimensions to the competitive field. Ecovis relies on partnerships with local networks to deliver global compliance coverage, which can be an effective model for firms that value local execution combined with international coordination. Axiom Law integrates corporate secretarial services with legal network support, emphasizing board governance and compliance within a broader legal advisory context. Luther Corporate Services builds on entity management focus for Indian and international clients, reflecting the growing importance of India-linked operations in global compliance workflows. Equiniti provides company secretarial and governance administration services with an emphasis on UK and international compliance, and recently expanded its engagement model through new governance insight products designed to help clients track regulatory changes and company secretarial developments. Link Group complements this landscape with corporate secretarial, governance, and shareholder services across multiple markets, reinforcing the trend toward integrated administration and investor-facing support.
Differentiation and Market Evolution
Differentiation in this market is increasingly defined by three factors: jurisdictional coverage, technology-enabled delivery, and service integration. Providers that can demonstrate reliable multi-jurisdiction execution, combined with coherent governance advisory and digital workflow tools, are better positioned to retain multinational clients and command stronger pricing. At the same time, the market is evolving through both consolidation and specialization. Larger platforms may pursue selective acquisitions or partnership models to expand jurisdictional reach, while specialized firms may deepen expertise in regulated sectors, complex entity structures, or particular regional ecosystems. New entrants that offer modern digital interfaces, transparent pricing, and strong compliance quality can win share in segments where traditional providers remain dependent on manual processes.
For corporate buyers, the practical implication is that vendor selection should move beyond reputation alone and evaluate operational reliability, technology maturity, regulatory responsiveness, and the ability to scale as entity structures change. For providers, the strategic priority is to reduce dependency on purely administrative revenue by expanding into governance advisory, risk monitoring, and digital service models that improve margins and client stickiness.
Future Trends and Commercial Opportunities
Looking ahead, three trends are likely to shape the market over the next several years and create actionable opportunities for organizations that prepare early.
Trend 1: Governance-as-a-Service and Integrated Compliance Platforms
Corporate secretarial services are moving toward integrated platforms that combine entity management, statutory filings, board administration, document control, and regulatory intelligence in a single workflow. This shift creates an opportunity for providers to offer governance-as-a-service models that reduce friction for clients and improve consistency across jurisdictions. For corporations, the value lies in fewer handoffs, clearer audit trails, and faster response to regulatory changes. The opportunity is not limited to large enterprises; small and medium enterprises can benefit from tiered digital packages that provide reliable compliance coverage without the cost of building internal capability from scratch. A key risk is that platform complexity may outpace usability if solutions are not designed around practical client workflows, so success will depend on user experience and integration quality as much as feature breadth.
Trend 2: AI-Augmented Compliance Monitoring and Predictive Governance
AI and automation will increasingly support statutory tracking, regulatory change detection, and compliance calendar management. Predictive capabilities may enable earlier identification of filing obligations, potential governance gaps, and jurisdiction-specific requirements that change with little notice. This trend strengthens the case for outsourced and hybrid models, because providers that invest in intelligence layers can offer proactive monitoring rather than reactive filing support. The commercial opportunity lies in converting compliance from a transactional function into a continuously managed service with higher retention and clearer value justification. The uncertainty comes from regulatory acceptance, data governance expectations, and the need to ensure that AI-assisted workflows remain explainable and auditable, especially in sensitive compliance contexts.
Trend 3: Consolidation, Ecosystem Partnerships, and Regional Specialization
The market is likely to see continued consolidation among mid-tier providers seeking scale, alongside ecosystem partnerships that combine global coordination with local execution. At the same time, regional specialization will remain important because regulatory nuance, licensing requirements, and client expectations vary significantly by jurisdiction. This dynamic creates opportunities for firms that can balance global consistency with local depth, either through owned offices, strategic partnerships, or network-based delivery models. Investors and acquirers may find value in platforms with strong jurisdictional coverage, recurring revenue characteristics, and demonstrated technology adoption. The risk is that consolidation can be complicated by integration challenges, differing compliance standards, and client migration costs, so execution discipline will determine whether scale translates into durable advantage.
Actionable Recommendations for Decision Makers
Different stakeholders face distinct priorities in this environment, but all can benefit from a structured approach to corporate secretarial strategy.
For Corporate Executives and Governance Leaders
Evaluate whether internal compliance structures are aligned with current regulatory complexity and future growth plans. If entity structures are expanding or regulatory expectations are increasing, consider hybrid or outsourced models that reduce fixed overhead while improving coverage consistency. Prioritize providers that can demonstrate digital workflow maturity, proactive regulatory monitoring, and clear escalation paths for governance issues. Treat corporate secretarial capability as part of the broader governance and risk framework rather than an isolated administrative function.
For Investors and Strategic Acquirers
Focus on business models with recurring revenue, scalable delivery, and credible technology adoption. Jurisdictional breadth, regulated-sector expertise, and strong client retention are important indicators of resilience. Assess whether target providers rely too heavily on manual administrative work or have moved toward integrated platforms and governance advisory services. In consolidation plays, prioritize cultural and operational compatibility, since integration challenges can erode the value of expanded jurisdictional reach. Monitor regulatory transitions closely, as compliance-driven demand can accelerate engagement but may also shift in response to new filing structures and governance rules.
For Procurement Teams and Service Selection Leaders
Use structured criteria that go beyond price and reputation. Evaluate data security, filing accuracy history, response times during regulatory changes, and the ability to manage multi-jurisdiction portfolios without loss of consistency. Request evidence of digital integration, document control standards, and board administration capabilities rather than assuming these are available by default. Where possible, pilot services in a limited scope to test workflow reliability before expanding to broader entity portfolios. A well-designed procurement process can reduce the risk of service gaps and create a stronger foundation for long-term compliance performance.
For organizations that need detailed segmentation data, jurisdiction-level dynamics, and tailored scenario planning, deeper research can help translate these market-wide trends into specific investment, vendor selection, or operating-model decisions. A more granular view of service-type demand, company-size segmentation, regional growth patterns, and competitive positioning can support more precise go-to-market and procurement strategies. Readers interested in the full analytical framework, including expanded segmentation detail and customized recommendations, can access the complete PW Consulting study for this market.
PW Consulting Information & Electronics Research Center
For detailed analysis of this topic, please visit the official page: Corporate Secretarial Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
TEM Market 2026-2032: Why 4.3% CAGR and $1.25B Valuation Signal a Strategic Turning Point
By pmarketresearch, 2026-09-21
Transmission Electron Microscope Market: Strategic Trends and Commercial Opportunities Through 2032
The global Transmission Electron Microscope (TEM) market has demonstrated resilient expansion over the past five years, with the sector reaching approximately 970.0 million USD in 2025. Projections indicate steady growth through the end of the decade, with the market expected to surpass 1.25 billion USD by 2032 and register a compound annual growth rate of 4.3 percent across the forecast horizon. This trajectory reflects an industry navigating both maturing applications and emerging demand vectors. While the expansion is not explosive, it is structurally sustained by converging technological capabilities, shifting regulatory frameworks, and deepening integration of electron microscopy into high-value research and diagnostic workflows.
The market's evolution cannot be understood through aggregate figures alone. Revenue distribution reveals a landscape where regional maturity, application specialization, and instrument architecture each shape purchasing behavior and competitive positioning. North America and Europe continue to anchor a significant portion of demand, reflecting established research infrastructure and medical device evaluation networks. Asia Pacific has emerged as a faster-growing geographic cluster, driven by expanding semiconductor manufacturing capacity and national investment in materials and life sciences research. At the product level, conventional TEM systems maintain a substantial installed base, while scanning TEM variants and cryo-enabled platforms have gained share as laboratories prioritize resolution, automation, and specimen preservation for delicate biological and advanced material samples. Across applications, academic and industrial laboratories are increasingly channeling procurement toward semiconductor defect analysis, material sciences characterization, and life sciences investigations, each pulling the market in slightly different technical directions.
Structural Challenges and Inflection Points
Despite steady growth, the TEM market faces several structural challenges that will define competitive outcomes over the next cycle. The first is the tension between capital intensity and accessibility. High-resolution electron microscopy remains a significant capital investment, and procurement decisions are increasingly tied to operational efficiency, maintenance costs, and the ability to integrate instruments into high-throughput workflows. Laboratories and industrial buyers are no longer evaluating systems solely on resolution specifications; they are weighing total cost of ownership, staff training demands, and the extent to which automation can reduce bottlenecks in sample preparation and data interpretation.
A second challenge lies in the fragmentation of end-user requirements. The SEMICON-driven demand for precise defect characterization, the structural biology push toward atomic-level molecular imaging, and the broader materials science need for compositional and crystallographic analysis each place distinct pressures on instrument design. Suppliers must balance specialization with platform flexibility, and over-indexing toward one application space can limit reach in adjacent high-growth segments.
A third inflection point comes from regulatory and standards-driven change. As diagnostic and medical-adjacent applications of electron microscopy become more formalized, compliance requirements and procedural coding are reshaping procurement pathways. For manufacturers and service providers, this creates both new demand signals and new operational obligations, particularly where imaging workflows intersect with clinical evaluation, quality management, and evidence generation for therapeutic development.
Key Drivers Reshaping the TEM Market
The current expansion is not a uniform pullback of demand across all segments. It is being pulled by several reinforcing forces that change both how instruments are built and how they are purchased.
Technological Innovation and the Automation Imperative
Instrumentation innovation remains the central growth lever, but the nature of differentiation has shifted. Historically, TEM competition focused heavily on resolution and stability. Today, the frontier includes workflow automation, AI-assisted imaging and interpretation, and improved specimen handling for demanding sample types. Recent product introductions have underscored this shift. In mid-2025, Thermo Fisher Scientific presented systems emphasizing automation and accessibility for life sciences and pathology applications, signaling a broader industry move toward instruments that reduce dependence on highly specialized operator intervention. That same year, Hitachi High-Tech introduced a transmission electron microscope designed around high-quality data acquisition and improved operational efficiency, reinforcing the growing premium on throughput and repeatability rather than resolution alone.
Cryo-enabled instrumentation represents a particularly important innovation vector. The launch of advanced cryo-TEM platforms with enhanced AI-driven automation for molecular structure analysis illustrates how technology is being tailored to structural biology and drug discovery workflows. These systems are not simply higher-resolution instruments; they are designed to support iterative, data-heavy research programs where automation, reproducibility, and integration with downstream analysis pipelines matter as much as raw imaging capability.
Regulatory and Standards-Driven Demand Formation
Regulatory evolution is shaping procurement in ways that are sometimes slower to appear in headline figures but material in practice. The establishment of procedural coding for diagnostic electron microscopy applications has helped formalize a reimbursement and billing pathway for certain surgical pathology evaluations, strengthening the commercial logic for diagnostic-oriented imaging workflows. More broadly, the medical device quality management landscape has moved toward alignment with ISO 13485:2016 standards, a change that influences both product validation expectations and supply chain requirements for manufacturers serving regulated end markets.
These developments matter because they convert informal or research-only uses of electron microscopy into more structured, compliance-aware procurement decisions. For suppliers, this means that documentation, quality systems, and service architectures are increasingly part of the competitive equation. For buyers, particularly in diagnostic-adjacent and medical device contexts, regulatory clarity can reduce uncertainty and accelerate adoption where imaging results directly support decision-making.
Demand-Side Shifts in Semiconductors, Materials, and Life Sciences
Demand is being reshaped by how end users organize their own innovation pipelines. In semiconductors, continuing miniaturization and the complexity of advanced node manufacturing have intensified the need for high-precision defect inspection and materials characterization, reinforcing TEM's role in process development and failure analysis. In materials sciences, the push toward advanced alloys, composites, and functional materials sustains demand for imaging solutions that can resolve structural and compositional detail at fine scales. In life sciences, structural biology and drug discovery continue to expand the addressable market for high-end imaging, especially where molecular structure determination informs therapeutic design.
PW Consulting
A notable feature of this demand environment is the growing importance of partnership-driven deployment. High-value instrumentation is increasingly installed as part of collaborative research and development ecosystems rather than as isolated laboratory purchases. This pattern reinforces the strategic importance of site-specific integration, service responsiveness, and the ability to support recurring high-throughput usage rather than sporadic academic experimentation.
Supply Chain and Cost Structure Dynamics
Cost structures in the TEM market are being influenced by more than component pricing alone. Supply chain resilience, service network coverage, and the economics of advanced subsystem manufacturing all affect both pricing strategy and time-to-deployment. Manufacturers that can standardize high-value subsystems, maintain reliable service coverage, and reduce downtime through predictive maintenance or remote diagnostics are gaining an advantage in markets where instrument uptime directly affects research output or production timelines. At the same time, buyers are increasingly sensitive to installation complexity and the hidden costs of specimen preparation, training, and data management, which expands the relevance of bundled service models and workflow-oriented selling.
Competitive Landscape and Strategic Positioning
The TEM market remains moderately concentrated, with a small group of established manufacturers holding a substantial share of revenue and technology leadership. This concentration does not imply stagnation; rather, it creates a competitive environment in which differentiation increasingly depends on platform breadth, application-specific engineering, service ecosystems, and the ability to navigate regulated demand pathways.
Established Players and Their Strategic Orientation
JEOL Ltd. continues to compete from a position grounded in precision electron optics and a long track record in scientific instrumentation. Its TEM offering emphasizes core imaging performance and the kind of engineering reliability that matters to users who prioritize instrument stability, repeatability, and specialized technical support. In a market where users are balancing performance claims against practical operating costs, JEOL's positioning reflects the enduring value of a focused instrumentation heritage.
Cryo-Electron Microscope Market
Thermo Fisher Scientific has pursued a broader platform and workflow strategy, building offerings that connect imaging hardware with automation, sample handling, and application-specific software. Its recent activity highlights a clear emphasis on making advanced microscopy more accessible and operationally efficient for life sciences, pathology, and structural biology applications. The movement toward AI-driven automation and integrated workflows suggests a strategy centered on reducing friction across the imaging pipeline rather than competing solely on stand-alone instrument specifications.
Scanning Electron Microscopes (SEM) Market
Hitachi High-Tech has continued to refine its TEM/STEM portfolio with an eye toward data quality and operational efficiency. Its product activity in recent periods indicates a focus on improving the practical experience of acquisition and analysis, aligning with the wider industry trend toward instruments that support consistent output in demanding research and industrial settings.
Carl Zeiss AG remains a major force in precision imaging, and its market moves increasingly intersect with regulated application spaces. Regulatory clearance for advanced TEM systems in the United States reflects a broader opening of certain medical and diagnostic-adjacent pathways, enabling deeper engagement with users whose procurement decisions are shaped by compliance, validation, and clinical workflow requirements.
Market Evolution: Consolidation, Differentiation, and Selective New Entry
The competitive structure appears likely to evolve through a combination of consolidation among service and technology providers, deeper differentiation by application, and selective entry by specialists targeting high-value niches. Full-scale disruption by generalist new entrants remains unlikely given the capital intensity, engineering complexity, and service requirements of advanced TEM systems. More plausible is a pattern in which established players strengthen platform ecosystems, while niche specialists compete on cryo workflows, AI-enhanced analysis, or application-specific deployment models. Partnerships with research institutions, pharmaceutical developers, and semiconductor innovators are likely to become more important as win-loss factors, especially where multi-year usage, data continuity, and service reliability influence procurement decisions.
Forward-Looking Trends and Commercial Implications
Trend 1: Workflow Automation as a Primary Purchase Criterion
Over the next three to five years, automation is likely to move from a differentiating feature to a baseline expectation in high-value TEM procurement. AI-assisted acquisition, reduced manual intervention in sample handling, and more integrated data pipelines will matter increasingly to laboratories facing throughput constraints and skilled labor shortages. For manufacturers, this opens opportunities to compete on software, service, and workflow design rather than hardware specifications alone. For buyers, the commercial implication is that total workflow cost and operational reliability may become more decisive than peak performance claims measured in isolation.
Trend 2: Expansion of Regulated and Diagnostic-Adjacent Use Cases
As procedural coding and quality management expectations continue to formalize certain electron microscopy applications, demand in diagnostic-adjacent and regulated environments is likely to become more predictable and more structured. This trend favors suppliers with strong documentation, validated workflows, and service models capable of supporting compliance-conscious buyers. It also creates entry opportunities for organizations that can bundle imaging systems with procedural support, training, and ongoing quality assurance. The risk side of this trend is that regulatory requirements can shift procurement cycles, increase validation costs, and narrow the set of eligible suppliers in certain segments.
Trend 3: Application-Linked Procurement and Ecosystem Deployments
A third trend is the growing alignment between instrument purchases and specific end-use ecosystems. Semiconductor process development, drug discovery partnerships, and advanced materials programs are increasingly deploying TEM not as a standalone research tool but as part of integrated development infrastructure. This shift pushes competitive advantage toward providers who can support long-term usage patterns, multi-site coordination, and reliable data generation across repeated cycles. The opportunity lies in offering solutions that reduce friction between imaging, analysis, and downstream decision-making. The uncertainty lies in the pace at which different application sectors will standardize their workflows and in how quickly procurement models will shift from capital purchase to more service- or outcome-linked arrangements.
Strategic Recommendations for Decision Makers
Different stakeholders face different priorities, but several actions are broadly relevant across the TEM market ecosystem.
For Manufacturers and Technology Providers
- Prioritize automation, workflow integration, and service responsiveness as core elements of product strategy, not supplementary features. Buyers increasingly evaluate instruments based on how they perform in daily operations rather than on specification sheets alone.
- Strengthen quality management and documentation capabilities where regulated or diagnostic-adjacent applications represent a meaningful growth path, since compliance readiness can determine market access as much as technical performance.
- Develop application-specific deployment models that align with semiconductor, life sciences, or materials science workflows, recognizing that each segment rewards different combinations of throughput, resolution, and support.
For Investors and Strategic Partners
- Look beyond aggregate market size and evaluate where automation, cryo workflows, and regulated demand are likely to create durable pockets of growth with stronger margins or longer customer lock-in.
- Assess the value of service, software, and workflow support businesses that complement hardware sales, since recurring revenue and customer retention are likely to become more important as competition intensifies around operational outcomes.
- Monitor partnership-driven deployments as indicators of future demand concentration, particularly where leading research institutions, drug developers, or semiconductor players standardize on specific imaging ecosystems.
For Procurement Leaders and End-User Organizations
- Evaluate total cost of ownership with explicit attention to training burden, maintenance exposure, downtime risk, and data management requirements, since these factors often outweigh headline instrument pricing in long-term operating economics.
- Align instrument selection with the organization's most likely future use cases, balancing platform flexibility against the risk of over-investing in capabilities that will rarely be used.
- Consider deployment models that support service continuity, remote diagnostics, and predictable upgrade paths, especially where imaging results are tied to critical research, process development, or diagnostic workflows.
The TEM market is entering a phase in which growth is increasingly shaped by how well suppliers and buyers manage operational complexity, regulatory alignment, and application-specific value creation. Aggregate expansion is meaningful, but the more important story is the shift toward automation, workflow integration, and structured demand in regulated environments. Organizations that treat TEM procurement and product strategy as part of a broader operational and compliance context are better positioned to capture durable value as the market matures.
For decision makers seeking deeper segmentation detail, company-level benchmarks, regional demand patterns, and scenario-based forecasts across forecast years, PW Consulting's full market research report provides a more granular view of the TEM market. The complete analysis extends beyond the strategic overview presented here to support customized evaluations of entry timing, segment focus, competitive positioning, and procurement planning.
For detailed analysis of this topic, please visit the official page: Transmission Electron Microscope (TEM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com