

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
TEM Market 2026-2032: Why 4.3% CAGR and $1.25B Valuation Signal a Strategic Turning Point

Transmission Electron Microscope Market: Strategic Trends and Commercial Opportunities Through 2032
The global Transmission Electron Microscope (TEM) market has demonstrated resilient expansion over the past five years, with the sector reaching approximately 970.0 million USD in 2025. Projections indicate steady growth through the end of the decade, with the market expected to surpass 1.25 billion USD by 2032 and register a compound annual growth rate of 4.3 percent across the forecast horizon. This trajectory reflects an industry navigating both maturing applications and emerging demand vectors. While the expansion is not explosive, it is structurally sustained by converging technological capabilities, shifting regulatory frameworks, and deepening integration of electron microscopy into high-value research and diagnostic workflows.
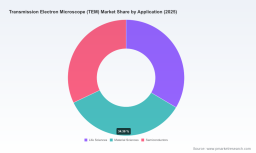
The market's evolution cannot be understood through aggregate figures alone. Revenue distribution reveals a landscape where regional maturity, application specialization, and instrument architecture each shape purchasing behavior and competitive positioning. North America and Europe continue to anchor a significant portion of demand, reflecting established research infrastructure and medical device evaluation networks. Asia Pacific has emerged as a faster-growing geographic cluster, driven by expanding semiconductor manufacturing capacity and national investment in materials and life sciences research. At the product level, conventional TEM systems maintain a substantial installed base, while scanning TEM variants and cryo-enabled platforms have gained share as laboratories prioritize resolution, automation, and specimen preservation for delicate biological and advanced material samples. Across applications, academic and industrial laboratories are increasingly channeling procurement toward semiconductor defect analysis, material sciences characterization, and life sciences investigations, each pulling the market in slightly different technical directions.
Structural Challenges and Inflection Points
Despite steady growth, the TEM market faces several structural challenges that will define competitive outcomes over the next cycle. The first is the tension between capital intensity and accessibility. High-resolution electron microscopy remains a significant capital investment, and procurement decisions are increasingly tied to operational efficiency, maintenance costs, and the ability to integrate instruments into high-throughput workflows. Laboratories and industrial buyers are no longer evaluating systems solely on resolution specifications; they are weighing total cost of ownership, staff training demands, and the extent to which automation can reduce bottlenecks in sample preparation and data interpretation.
A second challenge lies in the fragmentation of end-user requirements. The SEMICON-driven demand for precise defect characterization, the structural biology push toward atomic-level molecular imaging, and the broader materials science need for compositional and crystallographic analysis each place distinct pressures on instrument design. Suppliers must balance specialization with platform flexibility, and over-indexing toward one application space can limit reach in adjacent high-growth segments.
A third inflection point comes from regulatory and standards-driven change. As diagnostic and medical-adjacent applications of electron microscopy become more formalized, compliance requirements and procedural coding are reshaping procurement pathways. For manufacturers and service providers, this creates both new demand signals and new operational obligations, particularly where imaging workflows intersect with clinical evaluation, quality management, and evidence generation for therapeutic development.
Key Drivers Reshaping the TEM Market
The current expansion is not a uniform pullback of demand across all segments. It is being pulled by several reinforcing forces that change both how instruments are built and how they are purchased.
Technological Innovation and the Automation Imperative
Instrumentation innovation remains the central growth lever, but the nature of differentiation has shifted. Historically, TEM competition focused heavily on resolution and stability. Today, the frontier includes workflow automation, AI-assisted imaging and interpretation, and improved specimen handling for demanding sample types. Recent product introductions have underscored this shift. In mid-2025, Thermo Fisher Scientific presented systems emphasizing automation and accessibility for life sciences and pathology applications, signaling a broader industry move toward instruments that reduce dependence on highly specialized operator intervention. That same year, Hitachi High-Tech introduced a transmission electron microscope designed around high-quality data acquisition and improved operational efficiency, reinforcing the growing premium on throughput and repeatability rather than resolution alone.
Cryo-enabled instrumentation represents a particularly important innovation vector. The launch of advanced cryo-TEM platforms with enhanced AI-driven automation for molecular structure analysis illustrates how technology is being tailored to structural biology and drug discovery workflows. These systems are not simply higher-resolution instruments; they are designed to support iterative, data-heavy research programs where automation, reproducibility, and integration with downstream analysis pipelines matter as much as raw imaging capability.
Regulatory and Standards-Driven Demand Formation
Regulatory evolution is shaping procurement in ways that are sometimes slower to appear in headline figures but material in practice. The establishment of procedural coding for diagnostic electron microscopy applications has helped formalize a reimbursement and billing pathway for certain surgical pathology evaluations, strengthening the commercial logic for diagnostic-oriented imaging workflows. More broadly, the medical device quality management landscape has moved toward alignment with ISO 13485:2016 standards, a change that influences both product validation expectations and supply chain requirements for manufacturers serving regulated end markets.
These developments matter because they convert informal or research-only uses of electron microscopy into more structured, compliance-aware procurement decisions. For suppliers, this means that documentation, quality systems, and service architectures are increasingly part of the competitive equation. For buyers, particularly in diagnostic-adjacent and medical device contexts, regulatory clarity can reduce uncertainty and accelerate adoption where imaging results directly support decision-making.
Demand-Side Shifts in Semiconductors, Materials, and Life Sciences
Demand is being reshaped by how end users organize their own innovation pipelines. In semiconductors, continuing miniaturization and the complexity of advanced node manufacturing have intensified the need for high-precision defect inspection and materials characterization, reinforcing TEM's role in process development and failure analysis. In materials sciences, the push toward advanced alloys, composites, and functional materials sustains demand for imaging solutions that can resolve structural and compositional detail at fine scales. In life sciences, structural biology and drug discovery continue to expand the addressable market for high-end imaging, especially where molecular structure determination informs therapeutic design.
PW Consulting
A notable feature of this demand environment is the growing importance of partnership-driven deployment. High-value instrumentation is increasingly installed as part of collaborative research and development ecosystems rather than as isolated laboratory purchases. This pattern reinforces the strategic importance of site-specific integration, service responsiveness, and the ability to support recurring high-throughput usage rather than sporadic academic experimentation.
Supply Chain and Cost Structure Dynamics
Cost structures in the TEM market are being influenced by more than component pricing alone. Supply chain resilience, service network coverage, and the economics of advanced subsystem manufacturing all affect both pricing strategy and time-to-deployment. Manufacturers that can standardize high-value subsystems, maintain reliable service coverage, and reduce downtime through predictive maintenance or remote diagnostics are gaining an advantage in markets where instrument uptime directly affects research output or production timelines. At the same time, buyers are increasingly sensitive to installation complexity and the hidden costs of specimen preparation, training, and data management, which expands the relevance of bundled service models and workflow-oriented selling.
Competitive Landscape and Strategic Positioning
The TEM market remains moderately concentrated, with a small group of established manufacturers holding a substantial share of revenue and technology leadership. This concentration does not imply stagnation; rather, it creates a competitive environment in which differentiation increasingly depends on platform breadth, application-specific engineering, service ecosystems, and the ability to navigate regulated demand pathways.
Established Players and Their Strategic Orientation
JEOL Ltd. continues to compete from a position grounded in precision electron optics and a long track record in scientific instrumentation. Its TEM offering emphasizes core imaging performance and the kind of engineering reliability that matters to users who prioritize instrument stability, repeatability, and specialized technical support. In a market where users are balancing performance claims against practical operating costs, JEOL's positioning reflects the enduring value of a focused instrumentation heritage.
Cryo-Electron Microscope Market
Thermo Fisher Scientific has pursued a broader platform and workflow strategy, building offerings that connect imaging hardware with automation, sample handling, and application-specific software. Its recent activity highlights a clear emphasis on making advanced microscopy more accessible and operationally efficient for life sciences, pathology, and structural biology applications. The movement toward AI-driven automation and integrated workflows suggests a strategy centered on reducing friction across the imaging pipeline rather than competing solely on stand-alone instrument specifications.
Scanning Electron Microscopes (SEM) Market
Hitachi High-Tech has continued to refine its TEM/STEM portfolio with an eye toward data quality and operational efficiency. Its product activity in recent periods indicates a focus on improving the practical experience of acquisition and analysis, aligning with the wider industry trend toward instruments that support consistent output in demanding research and industrial settings.
Carl Zeiss AG remains a major force in precision imaging, and its market moves increasingly intersect with regulated application spaces. Regulatory clearance for advanced TEM systems in the United States reflects a broader opening of certain medical and diagnostic-adjacent pathways, enabling deeper engagement with users whose procurement decisions are shaped by compliance, validation, and clinical workflow requirements.
Market Evolution: Consolidation, Differentiation, and Selective New Entry
The competitive structure appears likely to evolve through a combination of consolidation among service and technology providers, deeper differentiation by application, and selective entry by specialists targeting high-value niches. Full-scale disruption by generalist new entrants remains unlikely given the capital intensity, engineering complexity, and service requirements of advanced TEM systems. More plausible is a pattern in which established players strengthen platform ecosystems, while niche specialists compete on cryo workflows, AI-enhanced analysis, or application-specific deployment models. Partnerships with research institutions, pharmaceutical developers, and semiconductor innovators are likely to become more important as win-loss factors, especially where multi-year usage, data continuity, and service reliability influence procurement decisions.
Forward-Looking Trends and Commercial Implications
Trend 1: Workflow Automation as a Primary Purchase Criterion
Over the next three to five years, automation is likely to move from a differentiating feature to a baseline expectation in high-value TEM procurement. AI-assisted acquisition, reduced manual intervention in sample handling, and more integrated data pipelines will matter increasingly to laboratories facing throughput constraints and skilled labor shortages. For manufacturers, this opens opportunities to compete on software, service, and workflow design rather than hardware specifications alone. For buyers, the commercial implication is that total workflow cost and operational reliability may become more decisive than peak performance claims measured in isolation.
Trend 2: Expansion of Regulated and Diagnostic-Adjacent Use Cases
As procedural coding and quality management expectations continue to formalize certain electron microscopy applications, demand in diagnostic-adjacent and regulated environments is likely to become more predictable and more structured. This trend favors suppliers with strong documentation, validated workflows, and service models capable of supporting compliance-conscious buyers. It also creates entry opportunities for organizations that can bundle imaging systems with procedural support, training, and ongoing quality assurance. The risk side of this trend is that regulatory requirements can shift procurement cycles, increase validation costs, and narrow the set of eligible suppliers in certain segments.
Trend 3: Application-Linked Procurement and Ecosystem Deployments
A third trend is the growing alignment between instrument purchases and specific end-use ecosystems. Semiconductor process development, drug discovery partnerships, and advanced materials programs are increasingly deploying TEM not as a standalone research tool but as part of integrated development infrastructure. This shift pushes competitive advantage toward providers who can support long-term usage patterns, multi-site coordination, and reliable data generation across repeated cycles. The opportunity lies in offering solutions that reduce friction between imaging, analysis, and downstream decision-making. The uncertainty lies in the pace at which different application sectors will standardize their workflows and in how quickly procurement models will shift from capital purchase to more service- or outcome-linked arrangements.
Strategic Recommendations for Decision Makers
Different stakeholders face different priorities, but several actions are broadly relevant across the TEM market ecosystem.
For Manufacturers and Technology Providers
- Prioritize automation, workflow integration, and service responsiveness as core elements of product strategy, not supplementary features. Buyers increasingly evaluate instruments based on how they perform in daily operations rather than on specification sheets alone.
- Strengthen quality management and documentation capabilities where regulated or diagnostic-adjacent applications represent a meaningful growth path, since compliance readiness can determine market access as much as technical performance.
- Develop application-specific deployment models that align with semiconductor, life sciences, or materials science workflows, recognizing that each segment rewards different combinations of throughput, resolution, and support.
For Investors and Strategic Partners
- Look beyond aggregate market size and evaluate where automation, cryo workflows, and regulated demand are likely to create durable pockets of growth with stronger margins or longer customer lock-in.
- Assess the value of service, software, and workflow support businesses that complement hardware sales, since recurring revenue and customer retention are likely to become more important as competition intensifies around operational outcomes.
- Monitor partnership-driven deployments as indicators of future demand concentration, particularly where leading research institutions, drug developers, or semiconductor players standardize on specific imaging ecosystems.
For Procurement Leaders and End-User Organizations
- Evaluate total cost of ownership with explicit attention to training burden, maintenance exposure, downtime risk, and data management requirements, since these factors often outweigh headline instrument pricing in long-term operating economics.
- Align instrument selection with the organization's most likely future use cases, balancing platform flexibility against the risk of over-investing in capabilities that will rarely be used.
- Consider deployment models that support service continuity, remote diagnostics, and predictable upgrade paths, especially where imaging results are tied to critical research, process development, or diagnostic workflows.
The TEM market is entering a phase in which growth is increasingly shaped by how well suppliers and buyers manage operational complexity, regulatory alignment, and application-specific value creation. Aggregate expansion is meaningful, but the more important story is the shift toward automation, workflow integration, and structured demand in regulated environments. Organizations that treat TEM procurement and product strategy as part of a broader operational and compliance context are better positioned to capture durable value as the market matures.
For decision makers seeking deeper segmentation detail, company-level benchmarks, regional demand patterns, and scenario-based forecasts across forecast years, PW Consulting's full market research report provides a more granular view of the TEM market. The complete analysis extends beyond the strategic overview presented here to support customized evaluations of entry timing, segment focus, competitive positioning, and procurement planning.
For detailed analysis of this topic, please visit the official page: Transmission Electron Microscope (TEM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com