

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Air Blowers Market: Mining & Manufacturing Demand Behind 5.5% CAGR to 2032

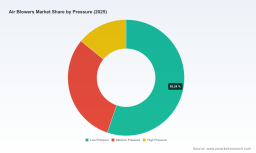
Strategic Shifts in the Global Air Blowers Market: Navigating Growth, Efficiency Mandates, and Competitive Realignment
Market Overview: Steady Expansion Amid Structural Complexity
The global air blowers market has demonstrated consistent growth over the past half-decade, with industry revenue reaching approximately 215 million USD in 2025, up from 163.15 million USD in 2020. The trajectory reflects a compound annual growth rate of 1.4 percent across the forecast window extending to 2032, with projected valuations surpassing 344 million USD by the end of the period. This measured pace masks underlying volatility in demand patterns, regional execution, and technology adoption cycles that shape how companies allocate capital and position their product portfolios.
The market is characterized by moderate concentration, with the top three players capturing roughly 40 percent of total revenue and the top five approaching 60 percent. This structure suggests a competitive arena where established multinational manufacturers maintain scale advantages in distribution, service networks, and compliance capabilities, while regional specialists and emerging entrants compete on customization, speed, and localized engineering support. The presence of both broad-product-line incumbents and application-focused niche providers creates a layered competitive environment where buyers evaluate total cost of ownership, reliability under specific operating conditions, and alignment with evolving efficiency mandates.
Several inflection points are reshaping how value is created and captured. First, regulatory frameworks governing industrial fan and blower efficiency are tightening across major economies, shifting procurement criteria from upfront price toward lifecycle energy consumption and maintainability. Second, supply chain volatility in steel and precision components has pressured cost structures, forcing manufacturers to reconsider sourcing strategies, inventory buffers, and vertical integration decisions. Third, application-side buyers are increasingly integrating air movement equipment into broader automation and process-optimization initiatives, which elevates expectations for connectivity, diagnostics, and repeatable performance. Together, these forces are pulling the market away from commoditized equipment transactions toward solutions that deliver measurable operational savings and regulatory compliance.
Core Growth Drivers: Technology, Policy, Demand, and Supply Chain
Technology Innovation and Performance Breakthroughs
Advancements in blower design are centering on three interrelated objectives: higher aerodynamic efficiency, lower noise and vibration profiles, and improved adaptability to variable operating conditions. Manufacturers are refining impeller geometries, optimizing aerodynamic pathways, and integrating control systems that modulate output to match real-time demand. These developments matter because air blowers frequently run continuously in wastewater treatment, pneumatic conveying, and process aeration, where even modest efficiency gains compound into significant energy savings over equipment lifecycles.
Oil-free configurations have gained particular attention in food processing, pharmaceuticals, and environmental applications, where contamination risk and product integrity drive procurement decisions. Companies offering oil-free rotary lobe, screw, and regenerative designs are positioning these platforms as default choices for sensitive processes, reducing the need for downstream filtration and simplifying maintenance routines. At the same time, high-speed and centrifugal variants continue to serve heavier-duty duties where reliability, pressure stability, and throughput dominate specification criteria.
PW Consulting
The 2026 trade show circuit underscored this technology emphasis. Exhibitors at IFAT 2026 in Munich and IFAT India 2026 in Mumbai highlighted efficient air movement solutions designed for environmental, wastewater, and process-air applications. These appearances signaled not only product momentum but also a strategic focus on sectors where efficiency, compliance, and process reliability converge. For manufacturers, the takeaway is clear: differentiation increasingly depends on demonstrating measurable performance under realistic operating conditions rather than competing solely on catalog breadth.
Policy and Regulatory Environment
Regulatory pressure is becoming a defining force in market dynamics, particularly where motor power ranges intersect with industrial fan and blower usage. In the European Union, the Ecodesign Regulation 2024/1834 for industrial fans and blowers covering 125-500 kW motors introduces stricter performance requirements, repairability provisions, and load and speed testing protocols. The mandatory application date of 24 July 2026 places compliance timelines in sharp focus for manufacturers selling into Europe and for buyers who must justify equipment selections against evolving standards.
In the United States, the Department of Energy finalized new energy conservation standards for fans and blowers with updated efficiency requirements published in January 2024. These standards reinforce NA companies’ expectations that air movement equipment will need to meet formalized efficiency benchmarks, influencing design priorities, product line planning, and the value proposition of retrofitting versus replacing aging installations.
These policy developments create a dual effect. For manufacturers, they raise the bar for engineering and documentation while offering a credible basis for premium positioning when efficiency and serviceability are proven. For buyers, they reduce the ambiguity around what constitutes acceptable performance and increase the strategic importance of selecting equipment that will remain compliant through its service life. In practice, regulatory momentum is accelerating the shift from incremental purchasing decisions to longer-cycle planning where total energy cost, maintenance access, and documentation readiness carry greater weight.
Demand-Side Changes in Buyer Behavior
Demand patterns are shifting as end-users treat air blowers less as standalone components and more as integrated elements of process reliability and cost control. Mining and manufacturing continue to represent substantial application volumes, with air movement supporting ventilation, pneumatic conveying, aeration, and process gas handling. Food processing industries also contribute meaningfully, where hygiene, oil-free operation, and stable pressure delivery align with production quality requirements. Across these sectors, the common thread is an increasing reluctance to accept performance variability, especially in facilities where unplanned downtime carries high financial and operational consequences.
Procurement behavior reflects this mindset. Buyers are requesting more detailed performance data, broader operating envelopes, and clearer documentation of maintenance and serviceability characteristics. They are also more attentive to noise levels, footprint constraints, and integration with existing control architectures. This is particularly visible where automation initiatives are expanding. Labor shortages in manufacturing have driven demand for automated blower production lines to sustain efficiency, and on the end-user side, that same automation push encourages equipment choices that reduce manual intervention and simplify supervision.
Worldwide Hand Held Blower Market
Trade show participation from multiple companies during 2025 and 2026 further illustrates demand-side evolution. Demonstrations at events such as Best Practices 2025 EXPO & Conference and regional automation and plastics exhibitions emphasized on-site utilities, process air, and automation-compatible blower arrangements. These showcases indicate that end-users are exploring bundled or application-tailored solutions that fit into broader facility upgrades rather than purchasing generic equipment in isolation.
Supply Chain and Cost Structure Pressures
Steel remains the primary raw material for industrial blower housings and impellers, and sector analysis from 2025 points to persistent supply chain volatility affecting input costs. This reality places continuous pressure on margin management and pricing strategies, particularly for manufacturers with limited flexibility in sourcing or limited ability to pass through cost changes without eroding competitiveness.
Compounding the material challenge is the labor dimension. Automation labor shortages in manufacturing are prompting higher demand for automated blower production lines to maintain efficiency. For equipment producers, this means investment in production automation is no longer solely an elective productivity improvement; it is increasingly part of the cost-structure response to skilled-labor constraints and throughput expectations. On the buyer side, the same dynamics push demand toward equipment that supports consistent output with reduced manual oversight.
A notable external factor is the continued strength of export activity from China, where industrial blower exports rose 15 percent year-over-year in the first quarter of 2026. This increase reflects strong global demand and highlights the role of export-oriented manufacturers in shaping availability, pricing, and competitive intensity across multiple regions. For market participants, the implication is that cost discipline, design efficiency, and service differentiation will remain central to defending position even as supply expands.
Roots Blower Market
Competitive Landscape and Strategic Positioning
The competitive field spans global manufacturers with broad industrial portfolios and specialized providers with deep application knowledge. This mix creates opportunities for different strategic plays, depending on whether a company competes through scale, application expertise, service proximity, or technology differentiation.
Atlas Copco has built a recognizable position around oil-free industrial and aeration blowers, including ZL Lobe and NEOS variants intended for low-pressure applications in wastewater, food processing, and pneumatic conveying. The emphasis on oil-free solutions in sensitive and regulated environments supports a value proposition anchored in cleanliness, compliance support, and process safety. Aerzen Maschinenfabrik GmbH offers oil-free rotary lobe blowers focused on industrial aeration, wastewater, and process gas handling, aligning closely with applications where contamination avoidance and steady process conditions are paramount.
ebm-papst emphasizes process air, circulation, and drying blowers for industrial HVAC and energy-efficient applications, positioning itself where efficiency and integrated airflow management are central to customer priorities. Twin City Fan Companies provides a full-spectrum range of air moving equipment, including centrifugal and axial blowers for industrial ventilation and process applications, appealing to buyers who value breadth and engineering flexibility across multiple duty cycles. Kaeser Kompressoren contributes oil-free screw blowers and positive displacement offerings for industrial air supply and aeration, reinforcing its broader compressed-air and air-supply ecosystem play.
Ingersoll Rand focuses on industrial blowers for compressed air systems and pneumatic conveying in manufacturing, where reliable throughput and integration with plant air systems are key purchasing criteria. Gardner Denver and Howden both address heavier-duty uses: Gardner Denver through rotary lobe and centrifugal blowers for industrial aeration and process gas applications, and Howden through high-efficiency centrifugal blowers for heavy-duty industrial and energy sectors. A1 Blowers India Pvt. Ltd. and Inovair Blowers represent more regionally or operationally oriented profiles, with A1 emphasizing industrial air blowers, vacuum boosters, and engineered air solutions for manufacturing, and Inovair emphasizing centrifugal and axial blowers with vertical manufacturing to support timely industrial delivery.
Several strategic themes emerge from this landscape. First, product focus is increasingly tied to application outcomes rather than generic specifications. Companies that articulate clear value in wastewater aeration, food-grade processes, pneumatic conveying, or HVAC efficiency are better positioned to command loyalty and pricing power than those competing primarily on hardware parity. Second, service and documentation capability is becoming a competitive differentiator as efficiency standards and repairability expectations rise. Third, regional presence and delivery reliability matter where engineering support, lead-time consistency, and local troubleshooting can outweigh marginal hardware price differences.
Recent event activity reinforces the importance of visible market engagement. A1 Blowers India’s exhibit at IFAT India 2026, Nitto Kohki’s appearance at IFAT 2026 alongside pumps for environmental and energy applications, Elektror Group’s participation with industrial blowers for process air, Sahara Air Products’ demonstration of on-site utilities including blowers for automation, and Air Deviser Industrial’s showcases in automation and plastics exhibitions all point to a market where suppliers are actively targeting application-specific audiences. This pattern suggests continued segmentation by end-use and an emphasis on demonstrating fit within real operating environments rather than relying solely on broad catalog positioning.
The market is likely to see continued evolution along two paths. On one hand, larger multinational players may pursue selective integration, acquiring application-focused capabilities or strengthening service and digital-support functions to widen their value proposition. On the other hand, specialized manufacturers can thrive by deepening expertise in high-priority niches such as oil-free process air, wastewater aeration, and automation-compatible equipment layouts. New entrants and export-oriented producers will continue to test price-sensitive segments, but sustainable advantage will increasingly depend on the ability to prove efficiency, reliability, and compliance readiness in the field.
Future Outlook: Three Strategic Trends for the Next Three to Five Years
Efficiency as a Procurement Default, Not a Differentiator
As efficiency regulations take hold and energy costs remain a persistent concern, high-efficiency performance will transition from a selling point to a baseline expectation. This does not eliminate differentiation, but it shifts the basis of competition toward how clearly a manufacturer can validate performance, support repairability, and document compliance across operating conditions. Companies that invest early in test protocols, transparent performance reporting, and service-friendly designs will be better positioned to navigate purchasing scrutiny and reduce the risk of disqualification during specification reviews. The commercial opportunity lies in helping buyers quantify lifecycle savings and link equipment selection to broader energy and sustainability targets.
Application-Centric Bundling and Process Integration
Demand is moving toward solutions that fit into integrated process and automation plans rather than isolated component purchases. This trend favors suppliers that can combine appropriate blower types with control strategies, installation guidance, and service arrangements tailored to specific duties such as wastewater aeration, pneumatic conveying, food processing airflow, and industrial ventilation. The strategic implication is a shift from product catalogs to application packages, where the value proposition includes performance stability, integration ease, and reduced operational oversight. Manufacturers that build application engineering competence and strengthen field-support capabilities can capture more wallet share by becoming trusted partners in facility upgrades and process optimization projects.
Regional Demand Divergence and Supply-Side Realignment
Regional demand will likely continue to diverge in pace and priorities. Asia Pacific and North America represent substantial market bases, while Europe’s regulatory-driven efficiency focus creates distinct specification requirements. Latin America and the Middle East and Africa remain meaningful but more varied in their application mixes and procurement maturity. At the same time, export strength from Chinese manufacturers and ongoing steel cost volatility will keep pressure on global pricing and availability. Over the next three to five years, companies that can align production footprint, sourcing flexibility, and regional service presence with local demand profiles will be better equipped to manage risk and capture growth. A key uncertainty is how quickly regulatory implementation, energy price trajectories, and raw material conditions will interact, potentially compressing margins for players that cannot adapt product portfolios or cost structures with sufficient speed.
Actionable Guidance for Decision-Makers
For manufacturers and product leaders, the priority is to align engineering roadmaps with emerging compliance and efficiency expectations while reinforcing application-specific value. Invest in verifiable performance data, serviceability features, and control capabilities that support variable-duty operation. Strengthen production automation where labor constraints threaten throughput, and evaluate sourcing strategies for steel and precision components to reduce exposure to volatility. In go-to-market terms, emphasize application outcomes and lifecycle cost rather than catalog breadth alone, and prepare documentation that helps procurement teams justify selections under tighter efficiency scrutiny.
For investors and strategic planners, the market offers opportunities in companies that combine credible efficiency performance with application depth and service readiness. Favor business models that can demonstrate repeatable value in wastewater, food processing, pneumatic conveying, and industrial ventilation, particularly where regulatory momentum and automation trends increase the importance of reliability and documentation. Monitor competitive dynamics carefully: export-led price pressure, raw material swings, and selective consolidation can shift the attractiveness of different subsegments. The most resilient upside typically comes from players that can convert compliance and efficiency requirements into differentiated offerings rather than absorbing them as pure cost burdens.
For procurement and operations leaders, treat blower selection as a lifecycle decision with regulatory, energy, and integration implications. Specify equipment using documented efficiency performance and operating envelopes that match actual process variability, and include serviceability and maintenance access in evaluation criteria. Where facility upgrades or automation initiatives are underway, consider bundled solutions that reduce integration risk and support consistent supervision. Keep close attention to evolving standards and testing requirements, as early alignment can shorten specification cycles and reduce the chance of rework or replacement later in the asset life.
Detailed segmentation data, company-level benchmarks, and region-specific demand patterns can sharpen these decisions further. For executives and planning teams seeking a more granular view of subsegments, application mixes, and competitive positioning, the full PW Consulting market report provides expanded data and tailored analysis to support investment, product, and procurement strategies.
For detailed analysis of this topic, please visit the official page: Air Blowers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com