

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Life Science Reagents Market: Why 4.95% CAGR and Clinical Diagnostics Shifts Reshape Strategy

The Life Science Reagents Market: Strategic Shifts and Commercial Opportunities Through 2032
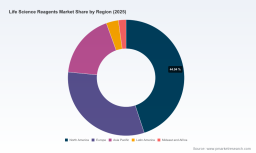
The global life science reagents market reached USD 44.24 billion in 2025, building on a decade of steady expansion from USD 35.0 billion in 2020. Growth is projected to continue through the forecast period, with the market expected to reach USD 61.0 billion by 2032. This trajectory reflects a compound annual growth rate of approximately 4.95 percent, signaling a mature but still expanding sector. The pace of growth, however, masks significant underlying shifts in how reagents are developed, manufactured, regulated, and deployed across research, diagnostics, and bioprocessing workflows.
Market expansion is no longer driven solely by volume increases in traditional laboratory supplies. Instead, value creation is concentrating around precision reagents, integrated diagnostic platforms, and specialized inputs for cell and gene therapy development. Clinical diagnostics remains the largest application segment, while drug discovery and genetic research continue to anchor demand from pharmaceutical and biotechnology sponsors. The geographic distribution of revenue reflects entrenched demand in developed markets, though emerging regions are gradually increasing their share as local research infrastructure and diagnostic capacity expand.
Beneath these aggregate figures, the industry is navigating a period of structural transition. Pricing power is uneven, supply dependencies are being reevaluated, and regulatory harmonization is forcing operational changes that extend well beyond compliance departments. For executives and investors, the opportunity lies in understanding where differentiation is achievable, where consolidation is accelerating, and where emerging demand vectors will outpace supply.
Market Context and Core Challenges
The life science reagents sector operates at the intersection of academic research, clinical testing, and commercial biomanufacturing. Its customer base spans large pharmaceutical companies, contract research and manufacturing organizations, hospital laboratories, and academic institutions. This breadth provides resilience, but it also introduces complexity in product development, quality standards, and go-to-market models.
Several structural challenges are reshaping how companies compete:
- Input dependency and cost volatility. Production of critical enzymes, buffers, and specialty biochemicals remains concentrated among a limited number of upstream suppliers. Disruptions in this layer transmit quickly into reagent pricing and lead times, particularly for companies that rely heavily on imported intermediates.
- Regulatory synchronization and documentation burden. The alignment of quality management requirements with internationally recognized standards is raising the bar for documentation, software validation, and audit readiness. Organizations that viewed compliance as a periodic exercise are now facing continuous operational adjustments.
- Portfolio complexity versus scale. Reagent manufacturers must balance breadth of catalog with depth of performance validation. Broad portfolios attract academic and routine diagnostic buyers, but high-value contracts increasingly demand application-specific validation, lot-to-lot consistency, and regulatory-grade documentation.
These challenges are not independent. Supply concentration amplifies the cost impact of regulatory changes, while portfolio complexity increases the operational load of maintaining compliance across multiple product lines. The companies that navigate this environment effectively are those that treat supply resilience, quality systems, and application support as interconnected capabilities rather than separate functions.
A second layer of tension comes from the shifting endpoint use of reagents. Historically, many reagent categories were optimized for research flexibility. Today, a growing share of demand originates from workflows that feed directly into clinical decisions, bioprocess validation, or regulated product release. That shift changes the value proposition: buyers care less about catalog breadth and more about traceability, reproducibility, and compatibility with standardized platforms.
Key Drivers Reshaping the Market
Technical Innovation and Platform Convergence
Innovation in reagents is increasingly tied to platform-level performance rather than isolated chemical improvements. Digital PCR, advanced immunoassay formats, and enzyme-based workflows are expanding the precision and throughput of both research and diagnostic applications. The commercial impact is visible in product launches that pair reagents with dedicated instrumentation or standardized workflows, creating more integrated value propositions.
Recent platform activity illustrates this direction. One major diagnostics and life science supplier expanded its digital PCR assay portfolio with a broad set of new tests on an existing partitioning platform, reinforcing the link between reagent availability and instrument adoption. In a parallel move, another manufacturer introduced specialized ddPCR kits targeting adeno-associated virus serotypes, reflecting the growing need for precise quantification tools in gene therapy development and quality control. These examples show how reagent innovation is being engineered around specific workflow bottlenecks rather than generic laboratory needs.
For commercial strategy, this trend rewards companies that can combine reagent performance with clear application support, validated protocols, and compatibility with widely used instrumentation. Standalone catalog products face stiffer competition when buyers can obtain equivalent performance inside a supported workflow.
Regulatory Change as a Competitive Filter
Regulatory dynamics are no longer a background condition; they are actively reshaping vendor selection and internal operating models. Harmonization efforts that synchronize quality management expectations with established international standards are compelling companies to upgrade documentation, software controls, and training processes. The effect is twofold. First, compliance costs are rising across the board. Second, the relative burden is heavier for smaller or less organized suppliers, which can tilt purchasing decisions toward vendors with mature quality infrastructure.
Laboratory Chemical Reagents Market
In practice, this means regulatory readiness is becoming a commercial asset. Buyers in clinical and bioprocessing settings increasingly view documented quality systems, validated software, and predictable audit performance as part of the reagent value proposition. Suppliers that treat these capabilities as strategic differentiators can command preference even when pricing is not the lowest.
PW Consulting
Demand-Side Shifts in Therapeutics and Diagnostics
The upstream demand environment is being reshaped by three interrelated forces: continued investment in drug discovery, growth in genetic and proteomic research, and expanding clinical diagnostic throughput. Drug discovery and genetic research remain strong anchors for reagent consumption, but the fastest commercial pressure is emerging where diagnostic workflows scale and where advanced therapies require specialized reagents for process development and release testing.
This demand mix is changing buying behavior. Clinical and bioprocessing buyers are looking for suppliers who can support lot consistency, documentation, and workflow integration. Research buyers still value breadth and flexibility, but they are also increasingly sensitive to supply reliability after several years of volatile availability across life science inputs. The net effect is a market where reliability and application support are becoming as important as unit price.
Supply Chain Reconfiguration and Cost Structure
The cost structure of reagent manufacturing is being reexamined as companies reassess dependency on concentrated upstream sources for enzymes, buffers, and other critical inputs. Reliance on a narrow supplier base in specific geographies creates exposure to logistics disruption, regulatory changes at the source, and price sensitivity when demand spikes. As a result, some manufacturers are diversifying sourcing, building additional buffer inventory for critical components, or investing in closer oversight of upstream quality.
This reconfiguration is not simply a contingency measure. It is increasingly part of commercial positioning. Suppliers that can demonstrate more predictable lead times, transparent sourcing practices, and resilient inventory management gain credibility with customers whose own production or testing schedules cannot tolerate variability. In a market growing at a steady but not explosive pace, reliability can be a stronger differentiator than incremental cost savings.
Competitive Landscape and Leading Strategies
The market is moderately concentrated, with a meaningful share of revenue held by a limited group of large, diversified suppliers. This concentration supports scale advantages in manufacturing, quality systems, and global distribution, but it also leaves room for specialized players to compete on application focus, regional presence, or workflow integration. The competitive dynamics are best understood by looking at how leading companies position themselves across research, diagnostics, and bioprocessing.
Large diversified suppliers such as Thermo Fisher Scientific, Merck KGaA, Danaher Corporation, Becton, Dickinson and Company, Roche Holding AG, Agilent Technologies, bioMérieux, Bio-Rad Laboratories, Promega Corporation, QIAGEN, PerkinElmer, Waters Corporation, and Lonza Group compete on multiple fronts. Their strategic advantages generally include broad product portfolios, established quality and regulatory infrastructure, global reach, and the ability to bundle reagents with instruments, kits, or services. Several of these companies also benefit from portfolio expansion through acquisition, which allows them to enter or deepen specific application areas more quickly than organic development alone would permit.
Specialized or regional-focused players add an important layer of competition. Bio-Techne Corporation and Maravai LifeSciences Holdings, Inc. illustrate a different strategic posture: deep focus on selected reagent categories, nucleic acid and enzyme-based solutions, antibody-related offerings, and support for advanced therapy and diagnostic development. These companies often compete by building strong application expertise, targeted customer relationships, and agile product development in niches where broader suppliers may be less differentiated.
Competitive positioning is increasingly defined by three choices:
- Breadth versus depth. Broad portfolios support cross-selling and reduce customer switching, but depth in high-value applications can create stronger loyalty and pricing resilience.
- Workflow integration versus component supply. Companies that align reagents with instrumentation, kits, or validated protocols can strengthen stickiness, while component suppliers must compete on performance, availability, and support.
- Global scale versus regional responsiveness. Scale Helps with cost and consistency, but regional presence can matter for service speed, regulatory localization, and customer intimacy.
Market evolution is being shaped by both consolidation and selective new entry. Recent activity shows how these forces are playing out. In distribution, partnerships are extending reach for specialized reagent portfolios without requiring full infrastructure build-out. In product strategy, ongoing assay and kit launches are reinforcing platform-based competition. In M&A, portfolio acquisitions are being used to secure intellectual property, enzymes, or antibody-related assets that strengthen a supplier’s position in high-demand workflows. One diversified supplier, for example, expanded its transfection reagent capabilities through acquisition, while another major player strengthened its antibody and reagent supply through a completed acquisition that consolidated presence in a strategically important category.
At the same time, new entrants are appearing where technological or application gaps create opening points. One molecular biology-focused company announced entry into the molecular biology and clinical diagnostic reagents market, signaling that platform expertise and targeted capability can still open doors even in a concentrated landscape. The broader implication is that the market is not static: incumbents retain advantages in scale and infrastructure, but differentiation remains possible through application focus, workflow alignment, and strategic partnerships.
Future Trends and Commercial Implications
Trend 1: Workflow-Embedded Reagents Will Capture Disproportionate Value
Over the next three to five years, reagents that are tightly integrated with validated workflows, dedicated instruments, or standardized kits are likely to command a growing share of commercial value. The reason is straightforward: as applications move toward clinical, bioprocess, and regulated environments, buyers prioritize reproducibility and support over isolated catalog purchases. Companies that can offer reagents as part of a reliable workflow will be better positioned to protect pricing and deepen customer relationships.
The commercial opportunity lies in designing reagent portfolios around specific end-use cases rather than around chemical categories alone. This includes pairing reagents with clear protocols, compatibility information, and application support that reduces integration risk for the buyer. It also includes thinking in terms of instrument-ecosystem alignment, where reagent availability reinforces platform adoption and vice versa.
Trend 2: Quality and Supply Resilience Will Become Purchase Criteria, Not Back-Office Functions
Regulatory harmonization and upstream supply concentration are pushing quality systems and supply reliability into the foreground of purchasing decisions. Buyers are increasingly likely to evaluate suppliers not only on product performance but also on documentation readiness, software validation maturity, and the ability to maintain consistent supply for critical inputs. This shift raises the stakes for suppliers that depend on fragile upstream chains or underdeveloped quality infrastructure.
For manufacturers, the strategic response is to treat quality and supply resilience as market-facing capabilities. That can mean diversifying critical inputs, strengthening inventory planning for high-impact components, and making quality documentation more accessible and transparent to customers. Suppliers that communicate these capabilities clearly may find them becoming part of the commercial rationale for selection.
Trend 3: Targeted Expansion and Partnerships Will Outpace Broad-Based Growth Alone
As market growth settles into a steady trajectory, pure volume expansion will matter less than targeted scaling in high-value segments. The most relevant opportunities are likely to arise in specialized enzyme and nucleic acid solutions, advanced diagnostic assay support, and reagents tied to cell and gene therapy workflows. In this environment, acquisitions, asset purchases, and distribution partnerships can be faster paths to capability than organic build-out, especially when they add intellectual property, validated assays, or regional reach.
At the same time, new entry remains possible where a company can bring a distinct technical angle or an underserved application focus. The presence of recent market-entry announcements and distribution partnerships suggests that the barrier to participation is not uniform across segments. Companies that can identify pockets where workflow needs are growing faster than supplier depth may find commercially meaningful openings.
Risks and Uncertainties
These trends are not without risk. Regulatory timelines can shift the burden of compliance faster than some suppliers can retool documentation and software systems. Upstream dependency may continue to create cost and availability shocks if diversification lags. Workflow integration can also intensify competitive pressure, since platform-based offerings can marginalize standalone reagents that lack clear compatibility or support. Finally, demand concentration in diagnostics and advanced therapies can create pockets of strong growth, but it also introduces exposure to changes in therapeutic pipelines, testing volumes, and reimbursement or procurement dynamics.
The overarching uncertainty is whether growth will remain broad-based or increasingly selective. If buying behavior continues to favor workflow-embedded, quality-ready, and supply-resilient solutions, then differentiation will depend less on catalog size and more on execution in targeted segments. That outcome would reward disciplined portfolio strategy and penalize diffuse expansion.
Strategic Recommendations for Decision-Makers
For Reagent Manufacturers and Suppliers
Focus portfolio strategy on application depth in segments where workflow integration and regulatory-grade support are becoming purchase requirements. Rather than spreading resources evenly across all categories, prioritize the reagent lines that connect to high-value diagnostics, drug discovery support, genetic research tools, and bioprocessing needs. Strengthen upstream visibility for critical enzymes and buffers, and treat supply resilience as a commercial message rather than an internal contingency plan. Where acquisition, asset purchase, or distribution partnership can close a capability gap more quickly than organic development, evaluate those options against the cost of missing a window in a growing segment.
For Investors and Strategic Buyers
Assess exposure to workflow-embedded demand and regulatory readiness when evaluating opportunities in this market. Companies with strong quality systems, instrument-aligned reagent portfolios, and credible supply strategies are better positioned to defend margins and customer relationships than those competing primarily on catalog breadth or price. Pay attention to consolidation patterns, especially where acquisitions add enzymes, antibodies, assay IP, or bioprocessing-relevant capabilities. Equally important, watch for signs of new entry in specialized niches, since targeted competition can reshape pricing and share even in a moderately concentrated market.
For Procurement and Sourcing Leaders
Treat reagent selection as a balance of performance, documentation, and supply predictability. Where workflows support clinical decisions, bioprocess validation, or regulated release, prioritize suppliers that can provide consistent lot performance, clear quality documentation, and stable availability for critical inputs. Diversification of supplier base for high-impact reagent categories can reduce exposure to upstream volatility, while closer alignment with suppliers that offer validated workflows may lower integration risk and operational overhead. In practice, the lowest unit cost is not always the lowest total cost when variability, rework, or supply disruption are included.
Closing Perspective
The life science reagents market is moving from a phase defined by broad demand growth to one shaped by where value is created within specific workflows, regulatory contexts, and supply chains. Aggregate expansion remains healthy, but the more important question for decision-makers is no longer how large the market will become by 2032. It is which capabilities will separate durable suppliers from transactional ones as quality expectations rise, upstream dependencies are scrutinized, and buyers increasingly purchase outcomes rather than isolated components.
Detailed segmentation data, company-level benchmarks, regional demand patterns, and scenario analysis can sharpen these strategic choices further. Additional intelligence is available through PW Consulting’s complete market research report, which provides a more granular view of the segments, competitors, and forward scenarios discussed here.
Life Science Instruments & Reagents Market
For detailed analysis of this topic, please visit the official page: Life Science Reagents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com