

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Corporate Secretarial Services Market 2026: Beyond the 5.2% CAGR Story

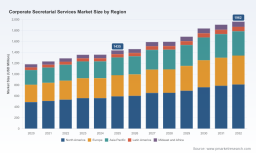
Navigating the Corporate Secretarial Services Market: Strategic Shifts and Emerging Opportunities
The corporate secretarial services landscape is undergoing a structural transformation driven by regulatory complexity, technological adoption, and evolving corporate governance expectations. Global revenue in this space reached approximately USD 1,435 million in 2025, up from USD 1,180 million in 2020, reflecting a compound annual growth rate of 5.2 percent through the 2032 outlook horizon. This growth trajectory is not uniform; it reflects a sector where routine compliance tasks are increasingly automated while high-value governance advisory, cross-border entity management, and risk mitigation services command premium positioning. For executives and investors, the market presents a dual narrative: steady top-line expansion paired with rapid shifts in how services are delivered, priced, and differentiated.
Market Landscape and Core Challenges
The corporate secretarial services market operates at the intersection of legal compliance, administrative governance, and strategic advisory. Over the past five years, revenue growth has consistently outpaced broader professional services benchmarks, yet the expansion masks underlying pressures that demand strategic attention. The sector's value is increasingly concentrated in complex jurisdictions, multinational entity structures, and organizations that cannot sustain in-house compliance teams at scale. This dynamic creates both opportunity and vulnerability for service providers and corporate buyers alike.
Regulatory Velocity and Compliance Gaps
One of the most persistent challenges is the pace of regulatory change. Directors and corporate secretaries must navigate an environment where filing requirements, governance standards, and disclosure obligations evolve faster than internal processes can adapt. Recent amendments to audit exemption frameworks and corporate governance enforcement provisions have introduced immediate compliance implications, altering statutory filing calendars and expanding the scope of director accountability. Simultaneously, broader corporate registry reforms in key markets have imposed transition periods that require updated entity documentation, enhanced beneficial ownership tracking, and revised board oversight procedures. Organizations that rely on reactive compliance workflows face elevated risk of late filings, governance lapses, or reputational exposure.
Cost Pressure and In-House Efficiency Gaps
A second structural pressure stems from the cost of maintaining compliance capabilities internally. As entity structures become more layered and regulatory expectations intensify, corporations are reassessing whether fully owned secretarial teams provide the most efficient path. The complexity of multi-jurisdiction operations, fluctuating staffing costs, and the need for specialized regulatory knowledge are pushing organizations toward outsourced or hybrid operating models. This shift is not simply about cost reduction; it reflects a strategic decision to redirect internal resources toward core business activities while leveraging external expertise for statutory adherence, governance administration, and risk tracking.
Share Registry Services Market
Technology Integration and Workflow Fragmentation
The third challenge lies in the uneven pace of digital transformation across the sector. While cloud-based entity management platforms and AI-enhanced tracking tools are increasingly referenced in advanced markets, many organizations still operate with fragmented workflows, manual document control, and siloed compliance calendars. The gap between early adopters and laggards creates operational inefficiencies and inconsistent compliance quality. Service providers that can unify statutory tracking, board administration, document automation, and regulatory intelligence into cohesive workflows are gaining traction, while legacy models struggle to justify premium pricing for purely administrative services.
Core Drivers Shaping Market Dynamics
The market's direction is shaped by a combination of technological, regulatory, demand-side, and cost-structure forces. Each driver reinforces the others, creating a cycle where complexity fuels outsourcing, outsourcing accelerates technology adoption, and technology enables stronger governance outcomes.
Worldwide Company Secretary Tool Market
Technology Innovation and Automation
Digital tools and automation are redefining what corporate secretarial services can deliver. Cloud-based entity management systems now support continuous compliance monitoring, automated filing reminders, digital board pack generation, and centralized document repositories. AI-assisted workflows are increasingly used for statutory tracking, contract review support, and regulatory change alerts. These capabilities reduce manual error rates, shorten turnaround times, and enable service providers to manage larger portfolios with greater consistency. In markets where regulatory evolution is rapid, such as advanced Asian financial hubs, cloud-enabled and AI-enhanced tools have accelerated the shift toward real-time governance administration and digital board meetings. The strategic implication is clear: technology is moving from a back-office enabler to a core differentiator that shapes service quality, scalability, and pricing power.
Regulatory and Governance Environment
Regulatory changes continue to be the most influential driver of demand. Amendments affecting audit exemptions, corporate governance enforcement provisions, and registry transparency requirements have expanded the compliance burden for directors and corporate secretaries. In the UK context, for example, recent reforms have created transition periods that require organizations to update governance documentation and strengthen preparedness for directors facing new filing and oversight expectations. These regulatory shifts do more than increase paperwork; they alter the compliance risk profile of companies and elevate the importance of proactive governance administration. Providers that can combine regulatory interpretation, practical implementation support, and ongoing monitoring are better positioned to capture demand from organizations seeking to reduce exposure to compliance failures.
Demand-Side Shifts in Corporate Behavior
Corporate behavior is changing in ways that expand the addressable market. Companies are increasingly viewing corporate secretarial functions not as a static administrative task but as a governance capability that supports board effectiveness, investor confidence, and operational resilience. Large corporations with complex legal entity structures need consistent oversight across jurisdictions, while small and medium enterprises require affordable, reliable compliance support to scale without governance breakdowns. Micro enterprises, meanwhile, often seek streamlined formation and basic compliance services that lower the barrier to formal incorporation. This segmentation of demand encourages providers to design service tiers that balance cost efficiency with depth of support, and it creates opportunities for specialized offerings in entity management, governance advisory, and shareholder administration.
Cost Structure and Outsourcing Economics
Cost dynamics are reinforcing the shift toward managed services. The rising complexity of entity structures and regulatory requirements increases the difficulty of maintaining fully in-house compliance teams, especially for organizations operating across multiple jurisdictions. Outsourced corporate secretarial services offer a pathway to reduce fixed compliance costs, access specialized expertise, and scale service capacity as business needs evolve. This economic logic is particularly compelling for firms that want to avoid the overhead of recruiting, training, and retaining niche compliance talent while still meeting statutory obligations. The result is a growing preference for service models that combine predictable pricing with flexible coverage, especially where compliance failures carry material financial or reputational consequences.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of global professional networks, specialized corporate service providers, and niche players with strong regional or sector focus. The market remains moderately fragmented, with the largest three players holding a combined share near 28 percent and the top five approaching 42 percent. This concentration indicates room for consolidation while also reflecting the practical realities of jurisdiction-specific licensing, regulatory knowledge, and client trust.
Strategic Positioning of Leading Players
PwC and Deloitte leverage broad professional service ecosystems to offer integrated corporate secretarial and entity management capabilities alongside regulatory compliance support across numerous jurisdictions. Their advantage lies in the ability to connect secretarial services with wider governance, tax, audit, and advisory offerings, creating cross-sell opportunities and a unified client experience. KPMG and Mazars pursue similar integration strategies, with strong emphasis on managed services, statutory compliance, and governance support delivered through global networks. These firms benefit from brand recognition, multinational reach, and the credibility that comes from operating across the full spectrum of corporate/advisory services.
Vistra and TMF Group represent the specialized end of the spectrum. Vistra focuses on corporate secretarial services, entity administration, and regulatory compliance for international clients, often serving organizations that require consistent handling across multiple jurisdictions. TMF Group emphasizes corporate secretarial services, trust administration, and compliance solutions for regulated entities, positioning itself around depth in regulated structures and operational execution. Citco narrows the focus further by specializing in corporate secretarial and management services for regulated entities such as hedge funds and private equity, where governance requirements and investor expectations are particularly stringent.
Other players add important dimensions to the competitive field. Ecovis relies on partnerships with local networks to deliver global compliance coverage, which can be an effective model for firms that value local execution combined with international coordination. Axiom Law integrates corporate secretarial services with legal network support, emphasizing board governance and compliance within a broader legal advisory context. Luther Corporate Services builds on entity management focus for Indian and international clients, reflecting the growing importance of India-linked operations in global compliance workflows. Equiniti provides company secretarial and governance administration services with an emphasis on UK and international compliance, and recently expanded its engagement model through new governance insight products designed to help clients track regulatory changes and company secretarial developments. Link Group complements this landscape with corporate secretarial, governance, and shareholder services across multiple markets, reinforcing the trend toward integrated administration and investor-facing support.
Differentiation and Market Evolution
Differentiation in this market is increasingly defined by three factors: jurisdictional coverage, technology-enabled delivery, and service integration. Providers that can demonstrate reliable multi-jurisdiction execution, combined with coherent governance advisory and digital workflow tools, are better positioned to retain multinational clients and command stronger pricing. At the same time, the market is evolving through both consolidation and specialization. Larger platforms may pursue selective acquisitions or partnership models to expand jurisdictional reach, while specialized firms may deepen expertise in regulated sectors, complex entity structures, or particular regional ecosystems. New entrants that offer modern digital interfaces, transparent pricing, and strong compliance quality can win share in segments where traditional providers remain dependent on manual processes.
For corporate buyers, the practical implication is that vendor selection should move beyond reputation alone and evaluate operational reliability, technology maturity, regulatory responsiveness, and the ability to scale as entity structures change. For providers, the strategic priority is to reduce dependency on purely administrative revenue by expanding into governance advisory, risk monitoring, and digital service models that improve margins and client stickiness.
Future Trends and Commercial Opportunities
Looking ahead, three trends are likely to shape the market over the next several years and create actionable opportunities for organizations that prepare early.
Trend 1: Governance-as-a-Service and Integrated Compliance Platforms
Corporate secretarial services are moving toward integrated platforms that combine entity management, statutory filings, board administration, document control, and regulatory intelligence in a single workflow. This shift creates an opportunity for providers to offer governance-as-a-service models that reduce friction for clients and improve consistency across jurisdictions. For corporations, the value lies in fewer handoffs, clearer audit trails, and faster response to regulatory changes. The opportunity is not limited to large enterprises; small and medium enterprises can benefit from tiered digital packages that provide reliable compliance coverage without the cost of building internal capability from scratch. A key risk is that platform complexity may outpace usability if solutions are not designed around practical client workflows, so success will depend on user experience and integration quality as much as feature breadth.
Trend 2: AI-Augmented Compliance Monitoring and Predictive Governance
AI and automation will increasingly support statutory tracking, regulatory change detection, and compliance calendar management. Predictive capabilities may enable earlier identification of filing obligations, potential governance gaps, and jurisdiction-specific requirements that change with little notice. This trend strengthens the case for outsourced and hybrid models, because providers that invest in intelligence layers can offer proactive monitoring rather than reactive filing support. The commercial opportunity lies in converting compliance from a transactional function into a continuously managed service with higher retention and clearer value justification. The uncertainty comes from regulatory acceptance, data governance expectations, and the need to ensure that AI-assisted workflows remain explainable and auditable, especially in sensitive compliance contexts.
Trend 3: Consolidation, Ecosystem Partnerships, and Regional Specialization
The market is likely to see continued consolidation among mid-tier providers seeking scale, alongside ecosystem partnerships that combine global coordination with local execution. At the same time, regional specialization will remain important because regulatory nuance, licensing requirements, and client expectations vary significantly by jurisdiction. This dynamic creates opportunities for firms that can balance global consistency with local depth, either through owned offices, strategic partnerships, or network-based delivery models. Investors and acquirers may find value in platforms with strong jurisdictional coverage, recurring revenue characteristics, and demonstrated technology adoption. The risk is that consolidation can be complicated by integration challenges, differing compliance standards, and client migration costs, so execution discipline will determine whether scale translates into durable advantage.
Actionable Recommendations for Decision Makers
Different stakeholders face distinct priorities in this environment, but all can benefit from a structured approach to corporate secretarial strategy.
For Corporate Executives and Governance Leaders
Evaluate whether internal compliance structures are aligned with current regulatory complexity and future growth plans. If entity structures are expanding or regulatory expectations are increasing, consider hybrid or outsourced models that reduce fixed overhead while improving coverage consistency. Prioritize providers that can demonstrate digital workflow maturity, proactive regulatory monitoring, and clear escalation paths for governance issues. Treat corporate secretarial capability as part of the broader governance and risk framework rather than an isolated administrative function.
For Investors and Strategic Acquirers
Focus on business models with recurring revenue, scalable delivery, and credible technology adoption. Jurisdictional breadth, regulated-sector expertise, and strong client retention are important indicators of resilience. Assess whether target providers rely too heavily on manual administrative work or have moved toward integrated platforms and governance advisory services. In consolidation plays, prioritize cultural and operational compatibility, since integration challenges can erode the value of expanded jurisdictional reach. Monitor regulatory transitions closely, as compliance-driven demand can accelerate engagement but may also shift in response to new filing structures and governance rules.
For Procurement Teams and Service Selection Leaders
Use structured criteria that go beyond price and reputation. Evaluate data security, filing accuracy history, response times during regulatory changes, and the ability to manage multi-jurisdiction portfolios without loss of consistency. Request evidence of digital integration, document control standards, and board administration capabilities rather than assuming these are available by default. Where possible, pilot services in a limited scope to test workflow reliability before expanding to broader entity portfolios. A well-designed procurement process can reduce the risk of service gaps and create a stronger foundation for long-term compliance performance.
For organizations that need detailed segmentation data, jurisdiction-level dynamics, and tailored scenario planning, deeper research can help translate these market-wide trends into specific investment, vendor selection, or operating-model decisions. A more granular view of service-type demand, company-size segmentation, regional growth patterns, and competitive positioning can support more precise go-to-market and procurement strategies. Readers interested in the full analytical framework, including expanded segmentation detail and customized recommendations, can access the complete PW Consulting study for this market.
PW Consulting Information & Electronics Research Center
For detailed analysis of this topic, please visit the official page: Corporate Secretarial Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com