

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Welding Equipment Market: 6.5% CAGR Growth and Strategic Shifts Redefining Revenue Trajectories to 2032

Welding Equipment Market: Strategic Trends and Commercial Opportunities Through 2032
The welding equipment market stands at a convergence of structural growth, technological disruption, and regulatory recalibration. Valued at approximately $22.5 billion in 2025, the sector has expanded from $15.5 billion in 2020, reflecting a compound annual growth rate of 6.5 percent across the 2026–2032 forecast horizon. This trajectory is not merely incremental; it signals a fundamental shift in how welding is deployed, automated, and regulated across industrial ecosystems. For executives, investors, and procurement leaders, the market presents a dual narrative: steady macroeconomic demand anchored in infrastructure and manufacturing, juxtaposed against acute labor constraints, compliance complexity, and rapid technological substitution. Understanding where value is migrating—and why—requires moving beyond headline revenue figures to examine the operational, technological, and policy forces reshaping the competitive landscape.
PW Consulting
Market Context and Structural Challenges
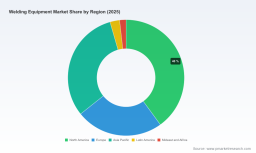
The broader market trajectory demonstrates consistent expansion, but the composition of that growth reveals underlying tensions. Arc welding continues to dominate revenue contribution, while emerging processes such as laser beam welding and precision resistance systems are gaining share in specialized fabrication and high-throughput environments. The geographic distribution of demand reflects divergent industrial priorities: mature economies are prioritizing equipment upgrades and automation retrofits, while high-growth regions are driven by capacity expansion in heavy engineering, infrastructure, and mobile manufacturing. Meanwhile, the application landscape remains anchored by automotive, building and construction, and heavy engineering, though railway, shipbuilding, and niche fabrication segments are accelerating as fleet modernization and energy transition projects enter execution phases.
Three structural challenges define the current inflection point.
- Workforce displacement and skill scarcity. The industry faces a projected shortfall of hundreds of thousands of qualified welders by the end of the decade. This gap is not cyclical; it reflects demographic attrition, training bottlenecks, and the increasing technical complexity of modern welding processes. The consequence is a structural push toward collaborative robotics, semi-automated cells, and process digitization, but adoption remains uneven across small and mid-sized fabricators.
- Regulatory fragmentation and compliance recalibration. Welding equipment and processes are subject to an expanding matrix of product safety standards, calibration and verification requirements, and sector-specific qualification rules. Harmonization is advancing in some jurisdictions, yet divergent national implementations and proposed rule changes in critical infrastructure segments are creating compliance uncertainty. Manufacturers and end users must navigate overlapping standards that affect certification timelines, equipment selection, and operational auditability.
- Procurement economics and capital deployment cycles. End-user budgets are increasingly constrained by inflation in component costs, energy volatility, and financing conditions. Fabricators and contractors are forced to weigh upfront equipment investment against long-term total cost of ownership, particularly as automation, consumables efficiency, and predictive maintenance become meaningful differentiators. This dynamic is reshaping purchasing behavior, with greater emphasis on multi-process flexibility, lifecycle service agreements, and demonstrable productivity gains rather than unit-price competition alone.
Core Demand Drivers
Technological Innovation and Process Substitution
The most consequential driver is the ongoing redefinition of welding capability through automation, advanced power electronics, and hybrid process integration. Collaborative welding robots and adaptive handheld systems are moving from pilot deployments to routine fabrication floor usage, particularly in environments where skilled labor is scarce or where mixed-model production demands rapid changeover. Laser beam and hybrid laser-arc solutions are expanding the envelope of applicability in high-precision joining, thin-gauge materials, and heat-sensitive alloys. At the same time, equipment manufacturers are embedding software layers that enable parameter control, data capture, and process verification, shifting welding from a craft-dominant operation to a more standardized, repeatable manufacturing process. These advances are not replacing welding; they are compressing skill dependency, improving consistency, and expanding the range of projects that can be executed profitably.
Policy, Standards, and Infrastructure Mandates
Regulatory and standards activity is functioning as both a constraint and a catalyst. Updated harmonized standards for welding equipment and revised calibration and verification requirements are increasing the emphasis on traceability, process control, and documented qualification. In parallel, proposed changes to qualification and inspection practices in certain pipeline and compressor station segments are tightening the criteria under which welders and processes are deemed acceptable. For capital-intensive sectors such as heavy engineering, energy infrastructure, and defense-related fabrication, these developments raise the bar for equipment selection and operator certification. The market response is twofold: manufacturers are engineering for compliance-driven features and documentation support, while end users are accelerating the adoption of automated and semi-automated solutions that reduce variability and simplify audit readiness.
Demand-Side Shifts in End-Use Sectors
Demand is being reshaped by investment cycles in transportation, construction, and heavy industrial modernization. Automotive production continues to require high-volume joining across mixed material portfolios, including lightweight alloys and mixed-material assemblies that demand precise heat input control. Building and construction activity sustains steady equipment utilization, particularly for structural fabrication, field welding, and on-site assembly where portability and durability matter. Heavy engineering and railway and shipbuilding segments are driven by fleet renewal, component replacement, and specialized fabrication where weld integrity, metallurgical control, and throughput are paramount. The common thread across these sectors is a growing preference for equipment that can operate across multiple process modes, integrate with data systems, and support consistent output under variable conditions.
Supply Chain and Cost Structure Evolution
The cost equation for welding operations is being recalibrated by component availability, energy considerations, and the economics of automation. Fabricators are increasingly evaluating total cost of ownership rather than purchase price, factoring in consumables efficiency, downtime risk, service availability, and the labor productivity impact of automation. Supply chain pressures have heightened the value of equipment robustness, service networks, and flexible financing options. At the same time, the economics of collaborative welding cells and modular automation are improving as hardware costs decline and deployment complexity is reduced through preconfigured solutions. This is altering the investment calculus for mid-tier fabricators that previously viewed automation as out of reach, creating a broader base of potential adopters and a wider competitive field for equipment providers.
Competitive Landscape and Strategic Positioning
The market remains moderately concentrated, with leading players commanding meaningful share while retaining room for differentiation through application specialization, automation integration, and regional service depth. The competitive architecture is defined less by uniform product breadth and more by targeted capability, ecosystem positioning, and speed in translating new process capabilities into field-ready solutions.
Leading Players and Differentiation Paths
Lincoln Electric has built its positioning around advanced arc welding systems, collaborative cobots, aluminum MIG capabilities, and fabrication automation. Recent product introductions have extended this footprint into aluminum-focused MIG systems and adaptive collaborative welding platforms, signaling a focus on material-specific process needs and labor-augmentation solutions. Miller Electric Mfg. LLC continues to emphasize multiprocess flexibility, engine-driven portability for field and heavy-duty use, and collaborative robotic systems that support mixed-production environments. Its portfolio orientation reflects an emphasis on versatility across job shop, field, and production settings.
ESAB has advanced its presence in heavy industrial and pipeline applications through equipment, automation, and cutting solutions, with product lines designed for demanding service conditions and high-throughput fabrication. A major acquisition move in the sector has reinforced the industry’s direction toward consolidation around automation and advanced process control capabilities. Fronius International GmbH has concentrated on precision MIG/MAG and TIG equipment, collaborative welding cells, and automation for fabrication environments where repeatability and process control are critical. EWM GmbH has built a profile around TIG/MIG/MMA machines, automation solutions, and software-enabled process management, aligning equipment capability with digital integration for industrial users. Hobart Welding Products remains focused on construction and general fabrication through MIG platforms, engine-driven models, and a broad accessory ecosystem, emphasizing practicality, durability, and field readiness.
Engine-Driven Welders Market
Market Structure Evolution
The competitive map is evolving along three vectors. First, consolidation is accelerating around automation, software, and process verification capabilities, as larger players absorb specialized competencies to strengthen end-to-end offerings. Second, differentiation is increasingly driven by application-specific engineering—aluminum welding, field portability, precision fabrication, heavy industrial throughput—rather than generic product breadth. Third, new entrants and technology-focused suppliers are gaining traction in handheld laser welding, collaborative cells, and digital process tools, particularly where they can address labor scarcity and changeover intensity. The net effect is a market in which scale, service networks, and application expertise intersect with technology adoption cycles, creating both opportunities for incumbents to deepen moats and openings for focused innovators to capture niche advantage.
Strategic Outlook: Trends and Commercial Signaling
Automation as a Standard Operating Layer
Over the next three to five years, collaborative welding, modular automation cells, and adaptive process control are likely to transition from selective adoption to baseline capability in a broadening range of fabrication environments. The driver is structural: labor constraints, consistency requirements, and the economics of mixed-model production are aligning to make automation a practical response rather than a premium option. Commercial opportunity lies in solutions that reduce deployment friction, support rapid changeover, and integrate with existing shop-floor workflows. The risk is that automation value is overstated where change management, training, and process redesign are underinvested, leading to underperformance and stalled adoption cycles.
Process Diversification in High-Value Joining
Laser-based and hybrid joining methods are expected to gain incremental share in applications that demand precision, reduced heat input, and compatibility with advanced materials. These processes will not displace conventional arc welding broadly, but they will expand the toolkit for sectors where joint quality, material sensitivity, and throughput are decisive. The commercial implication is a growing need for equipment portfolios that can span conventional and advanced processes, along with consumables, parameter support, and training that match the chosen process. Uncertainty remains around equipment cost, operator skill requirements, and the pace of qualification acceptance across industries and regions.
Compliance-Linked Purchasing and Service Intensity
As standards and qualification expectations tighten, procurement decisions are increasingly influenced by documentation support, calibration alignment, and service reliability. Equipment that facilitates traceability, parameter consistency, and audit-ready operation will carry a growing premium in regulated and mission-critical segments. The related opportunity is in service models, lifecycle support, and software-enabled maintenance that reduce compliance burden and operational risk. A key uncertainty is the speed and uniformity of regulatory implementation, which can shift demand patterns regionally and create uneven adoption timelines.
Actionable Guidance for Decision Makers
For Equipment Manufacturers and Solution Providers
- Strengthen application-specific engineering and validation support, particularly for aluminum welding, field- portable heavy-duty use, and precision fabrication, where process expertise can differentiate beyond hardware specifications.
- Accelerate integration of collaborative automation and process data capabilities into mainstream product lines, targeting deployment simplicity and changeover agility rather than only high-end automation niches.
- Build service, training, and compliance-documentation support as core commercial elements, since lifecycle value and audit readiness are increasingly part of the purchasing equation.
For Investors and Strategic Capital Allocators
- Evaluate exposure to automation adoption curves, handheld and hybrid process technologies, and software-enabled process control, where value creation is tied to labor economics and consistency gains rather than unit volume alone.
- Monitor consolidation activity and capability transfers in automation, precision welding, and digital process management, as these moves can reshape competitive positioning and margin profiles.
- Assess regional demand drivers and regulatory trajectories separately, since market growth and compliance-linked purchasing can diverge significantly across geographies and end-use sectors.
For Procurement Leaders and End Users
- Shift evaluation criteria toward total cost of ownership, incorporating consumables efficiency, downtime risk, service proximity, and the productivity impact of automation or multi-process flexibility.
- Prioritize equipment and partner capabilities that reduce variability and support qualification or audit readiness, especially in infrastructure, heavy engineering, and regulated fabrication contexts.
- Plan for workforce adaptation alongside equipment investment, ensuring training, change management, and process documentation are funded and sequenced with deployment to realize projected gains.
The welding equipment market is moving toward a more technology-dense, compliance-aware, and labor-constrained operating environment. For decision makers, the strategic task is to align equipment choices, automation roadmaps, and service models with the specific demands of their application mix and regional context. Detailed segment-level sizing, competitive benchmarking, and scenario analysis can sharpen those decisions, and the full research report provides the deeper data architecture and customized guidance needed to translate these market-level insights into operational strategy.
Welding Helmets Market
For detailed analysis of this topic, please visit the official page: Welding Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com