

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
XLPE Foam Market 2026: Why 6.8% CAGR Alone Misses the Real Growth Drivers

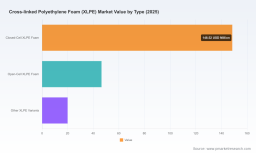
The Cross-linked Polyethylene Foam Market: Navigating Growth, Pressure, and Strategic Positioning
Market Context and Core Challenges
The cross-linked polyethylene (XLPE) foam sector has matured into a structurally important materials segment, with global revenue expanding from approximately $163 million in 2020 to a projected $342 million by 2032. The trajectory reflects sustained demand across multiple downstream industries, with a compound annual growth rate of 6.8 percent over the 2026–2032 horizon. This baseline trajectory masks a more nuanced reality: growth is uneven across applications, value capture is shifting, and manufacturers are operating in an environment where technical differentiation must be paired with cost discipline and compliance agility.
Several structural inflection points are reshaping how incumbents and new entrants think about XLPE foam. First, energy-code tightening in major construction jurisdictions is elevating performance expectations for insulation products. Specifications for below-grade and crawlspace assemblies now routinely require higher R-value retention and moisture resistance, favoring closed-cell formulations that hold dimensional stability under prolonged exposure. This shifts demand toward grades that were previously treated as premium or specialized options, compressing the gap between standard commodity SKUs and engineered variants. Second, the cost base for custom fabrication has become a visible strategic variable. Die-cutting, molding, and one-off tooling for industrial and automotive components elevate labor and setup costs, forcing fabricators to decide whether to absorb complexity internally or move toward standardized, high-runner geometries that preserve margin. Third, regulatory clarity around recycled content and food-contact documentation is accelerating procurement screening in Europe and select North American supply chains. High-purity traceability requirements are no longer a niche concern; they are becoming a prerequisite for entering certain packaging and healthcare-adjacent applications. Together, these pressures are converting XLPE foam from a generally interchangeable cushioning material into a performance-classified input where formulation, documentation, and fabrication capability all influence win rates.
Key Drivers Shaping the Market
Technology and process innovation are redefining what XLPE foam can deliver. Irradiation and electron-beam crosslinking have expanded the range of achievable cell structures, improving balance between flexibility, shock absorption, and thermal behavior. In parallel, thermoforming-grade developments are extending the material into higher-volume forming workflows, where manufacturers seek recyclable formats that still preserve protective performance. These advances are not simply product features; they change end-use economics by enabling lighter assemblies, fewer secondary components, and more predictable tolerances in precision gaskets and composite interfaces. Where these grades are adopted, they tend to unlock value not only through material substitution but through downstream assembly savings that buyers increasingly factor into specification decisions.
Policy and regulatory signals are acting as both gatekeeper and growth catalyst. In construction, updated energy codes and moisture-resistance expectations are reinforcing the case for closed-cell XLPE in assemblies where durability and thermal continuity matter. In packaging, EU requirements around high-purity documentation for recycled-content materials in food-contact contexts are raising the bar for traceability and lot control. These rules do not uniformly slow adoption; instead, they reward operators with disciplined quality systems and penalize those that treat compliance as an afterthought. The practical effect is a two-speed market: applications with stringent documentation and performance demands consolidate around suppliers that can deliver repeatable certifications, while price-sensitive commodity uses remain more exposed to substitution and margin erosion.
Demand-side behavior is shifting as well. Lightweight construction in renewable-energy nacelles and high-speed rail composite panels is driving interest in low-density, high-integrity foam cores and interlayers. Automotive programs continue to prioritize weight reduction and acoustic comfort, pushing XLPE into interiors, gaskets, and component protection where form, fit, and long-term resilience are critical. At the same time, brand owners and industrial purchasers are increasingly weighing total installed cost rather than unit price alone, which benefits suppliers that can demonstrate reliability, short lead times, and consistent lot-to-lot performance. One-day availability in select North American operations, for example, is becoming a competitive lever in prototypes and short-run programs where schedule risk outweighs minor material savings.
Supply chain and cost structure changes reinforce the need for portfolio discipline. Raw resin volatility, energy costs, and labor intensity in custom fabrication all pressure margins, especially for specialized die-cut or molded parts. In response, some operators are expanding extrusion capacity to improve throughput and reduce per-unit processing risk, while others are diversifying into grades that support higher-value fabrication rather than competing solely on roll, bun, and sheet volume. The market is therefore rewarding companies that align capacity investments with application mix: insulation and packaging volumes support scale, while automotive, healthcare, and precision industrial uses justify tighter process control and faster customization.
Competitive Landscape and Strategic Positioning
The competitive set spans global material developers, regional extrusion specialists, and custom fabricators, each competing on a different combination of formulation ownership, fabrication capability, and service model. Zotefoams operates from a global platform with a portfolio of closed-cell crosslinked polyolefin foams, including XLPE grades designed for packaging, industrial gaskets, and thermal insulation. Its strategic advantage lies in brand continuity across applications, which supports specifier trust in programs that value material consistency across geographies and product families. Armacell positions itself around closed-cell XLPE foam lines and custom fabrication pathways for insulation, packaging, and automotive use, emphasizing application engineering and flexibility in converted solutions. Sekisui Chemical contributes a distinct irradiation-crosslinked portfolio through Volara and Minicel, with relevance in automotive, healthcare, and protective packaging, where controlled cell structure and cleanliness are important. Toray Plastics complements the field with electron-beam crosslinked XLPE foam sheets targeted at gaskets, composites, automotive interiors, and high-precision applications, reflecting a strategy oriented toward engineered sheet formats and tight tolerance work.
Regional and fabrication-focused players add a different layer of value. Worldwide Foam illustrates the capacity-driven route, with a second extruder moving into trial runs to expand throughput for XLPE foam and reduce delivery risk in North American markets. Atlas Foam Products, AM Foam, Merryweather Foam, and Flextech Foam demonstrate the importance of custom fabrication, die-cutting, and contract manufacturing in translating rolls and buns into specification-ready components. CYG TEFA represents the scale manufacturing option from China, serving insulation, packaging, and building materials with a volume-oriented model. Across these profiles, the differentiating axis is not simply who produces the most foam, but who can reliably convert a base material into a finished, certified, application-specific outcome with acceptable lead time and documentation rigor.
Phenolic Foam Board Market
The landscape is evolving along two complementary lines. In one direction, integration is increasing between raw foam production and conversion capability, because customers in automotive, construction, and healthcare increasingly prefer fewer handoffs, clearer accountability, and better control over dimensional consistency and surface quality. In the other direction, specialization is intensifying around grade families and end-use performance, especially where recyclable thermoforming formats, high-shock-absorption variants, and moisture-resistant insulation grades create more defensible positioning. New entrants are most likely to succeed where they can address a visible gap: faster short-run availability, more disciplined documentation for regulated applications, or a particular grade optimized for lightweight composite assemblies. At the same time, differentiation based purely on volume pricing is becoming riskier, as buyers in performance-sensitive segments place greater weight on reliability, traceability, and total delivered value.
Forward-Looking Trends and Commercial Opportunities
One clear direction for the next three to five years is the continued migration of XLPE foam from generic cushioning toward performance-classified roles in construction, mobility, and renewable-energy assemblies. As energy codes and lightweighting objectives become more prescriptive, insulation and composite-foam applications should benefit from stronger specification pull. The commercial opportunity here is not simply more volume, but a shift toward engineered grades that command higher margins, repeat orders, and longer program lifecycles. Manufacturers that can offer consistent thermal and moisture behavior, along with reliable documentation, are better positioned to capture these programs than those competing primarily on commodity price.
High Density Microcellular Polyurethane Foam Market
A second trend is the growing emphasis on recyclability and formability without sacrificing protective performance. Thermoforming-grade developments and shock-absorption innovations are expanding the material’s reach into higher-value packaging and forming workflows, where brands want lighter, more sustainable structures but cannot compromise on impact protection or dimensional stability. The opportunity lies in pairing material innovation with process compatibility: if a grade can be formed efficiently, recycled or reprocessed responsibly, and still meet performance thresholds, it becomes a preferred option in programs that face both sustainability targets and engineering constraints. This is especially relevant where buyers are balancing regulatory documentation requirements with the need for repeatable production outcomes.
A third trajectory is the increasing importance of supply reliability and customization economics. Capacity expansions, one-day availability models, and tighter fabricated part pipelines matter more as programs shorten, prototypes move faster, and procurement teams evaluate lead-time risk alongside unit cost. For fabricators, the commercial question is whether to standardize common geometries, invest in tooling that supports higher volumes, or retain custom flexibility at a premium. The most resilient operators tend to blend both approaches: share standardized platforms to absorb volume consistently, while reserving custom capability for applications where performance or regulation justifies the added complexity. Potential risks include raw-material price swings, regional energy-cost divergence, and the chance that overly ambitious recycled-content claims outpace documentation readiness or downstream acceptance. Companies that move too slowly on compliance systems, or too aggressively into grades without clear end-use validation, may find themselves squeezed between better-documented competitors and buyers who reduce specification risk by consolidating suppliers.
PW Consulting
Strategic Actions for Decision Makers
For material producers and fabricators, the priority is to align grade portfolios and capacity investments with the applications where performance differentiation is most valued. If construction insulation and moisture-resistant assemblies are expanding under tighter codes, ensure that closed-cell grades and conversion options support those specifications reliably. If automotive and lightweight composite demand is rising, prioritize sheet formats, tolerance control, and documentation that reduce integration risk for design engineers. Where custom fabrication drives margin, evaluate whether standardizing high-runner geometries can lower labor intensity while preserving bespoke capability for premium programs. The practical lesson is to treat specification security and delivery reliability as margin enablers, not just service features.
For investors evaluating exposure to the XLPE foam space, the most durable value creation is likely to come from operators that combine scale with application discipline. Volume growth alone is not a sufficient thesis, because commodity applications remain exposed to substitution and price pressure. A more robust view focuses on whether a target can defend margins through formulation ownership, conversion capability, documentation readiness for regulated uses, and a mix that includes construction, automotive, and renewable-energy-driven demand rather than relying heavily on a single volume category. Capacity expansion can be positive, but only if it is matched to demand mix and supported by the operational controls needed to protect yield and lead-time performance.
For procurement teams and specification engineers, the strategic move is to evaluate XLPE foam selections through a broader lens than unit cost. Consider total installed performance, moisture and thermal behavior in the intended assembly, documentation availability for regulated or food-contact-adjacent uses, and the supplier’s ability to support prototypes and short runs without excessive schedule risk. Where possible, reduce fragmentation by qualifying suppliers that can cover both base material and converted components, or by structuring relationships that give reliable access to performance grades while maintaining competitive tension on commodity SKUs. In practice, the strongest purchasing strategies balance cost control with specification certainty, because program delays and rework often outweigh marginal savings on material price alone.
Closing Perspective
The XLPE foam market is moving from broad availability to more selective value creation. Growth is real, but it is increasingly concentrated in applications where performance, compliance, and delivery reliability matter enough to justify engineered grades and tighter fabrication models. That shift gives manufacturers an opportunity to defend margins through specification relevance and service consistency, gives investors a framework for separating scale plays from durable application-focused operators, and gives buyers a stronger reason to evaluate total value rather than headline price. For organizations seeking a more granular view of regional demand patterns, type-level splits, application sizing, competitive benchmarks, and customized strategic scenarios, a full market study can provide the segmentation detail and structured analysis needed to support investment, sourcing, and product-portfolio decisions.
For detailed analysis of this topic, please visit the official page: Cross-linked Polyethylene Foam (XLPE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com