
Blogs
The LED Glass Market: Strategic Trends and Commercial Opportunities in a High-Growth Segment
Market Landscape and Core Challenges
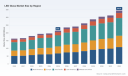
The LED glass market has transitioned from a niche architectural curiosity to a structurally significant component of modern display and facade systems. Over the historical period from 2020 to 2025, the sector expanded steadily, moving from a base of roughly $163 million to approximately $215 million. This trajectory reflects more than cyclical demand; it signals a foundational shift in how lighting, transparency, and digital content are integrated into built environments. Looking ahead through the forecast period extending to 2032, the market is projected to reach approximately $345 million, supported by a compound annual growth rate of 9.58 percent. The growth profile suggests a segment that is maturing in capability while still expanding in addressable use cases.
Beneath the headline numbers, the market is defined by a relatively fragmented structure. The top three players hold a combined share of roughly 24.6 percent, while the top five account for approximately 26.2 percent. This concentration pattern indicates that leadership is earned through application-specific expertise, integration capability, and regional distribution strength rather than through unchecked scale. For decision-makers, the implication is clear: market share is contested at the edges, and competitive advantage increasingly depends on engineering reliability, certification readiness, and the ability to pair glass solutions with compelling content ecosystems.
Despite the favorable growth outlook, the industry is navigating a set of challenges that will determine which participants capture disproportionate value over the next several years. Two to three structural friction points stand out. First, safety and compliance requirements continue to complicate thin-glass adoption, particularly in the United States, where glazing systems must satisfy rigorous testing protocols such as ANSI Z97.1 for lites used in building applications. This regulatory layer creates a barrier to entry for lightweight, high-transparency solutions and raises the cost of validation for new product lines. Second, the supply chain for raw materials remains sensitive to commodity dynamics, which directly affects unit economics and margin stability. Third, the market is undergoing a qualitative shift in how transparency and display performance are balanced, forcing manufacturers to reconcile aesthetic expectations with technical constraints. These challenges are not merely operational; they shape the pace of adoption, the viability of new form factors, and the strategic positioning of leading firms.
LED Lighting Market
Key Growth Drivers: Technology, Policy, Demand, and Cost Structure
The expansion of LED glass is being propelled by a convergence of forces that reinforce one another. Understanding these drivers is essential because they define where investment, product development, and commercial partnerships are likely to yield the highest returns.
Technology innovation remains the most visible catalyst. The integration of high-resolution LEDs directly into architectural-grade safety glass has progressed from experimental prototypes to commercially viable configurations, including laminated, surface-applied, and ceiling-hung solutions. This evolution is not just about embedding light sources; it is about engineering transparent digital displays that maintain clarity, durability, and visual fidelity in real-world environments. Recent industry activity underscores this shift. In early 2026, Ganglustr, a transparent glass LED specialist, published a piece highlighting switchable glass innovations and positioned transparent LED glass as a defining trend for modern retail and commercial facades. The emphasis on facade applications reflects a broader move toward using glass not only as a display surface but as a dynamic architectural element that communicates brand identity and adapts to context. Meanwhile, multi-year partnerships are emerging that extend LED glass beyond traditional screen installations. A notable example is the collaboration between the Big 12 Conference and ASB GlassFloor, which designated LED glass floors as official tournament courts for men’s and women’s basketball events. This move validates the durability and performance requirements of LED glass in high-traffic, high-visibility settings and signals a pathway for sports and entertainment venues to become early adopters of specialized glass-based surfaces.
Policy and regulatory environments are shaping adoption curves in both constraining and enabling ways. On one hand, safety glazing certification remains a practical hurdle. The need to demonstrate compliance with recognized testing standards introduces time and cost into product development, particularly for thin glass formats that must still meet structural and safety expectations. On the other hand, standardization efforts are beginning to reduce friction. The global harmonization of smart glass standards and the refinement of thin-film specifications for building applications are creating a more predictable compliance landscape. When standards converge across regions, manufacturers can scale with greater confidence, and specifiers can evaluate solutions against consistent criteria. Over time, this should lower the barrier to wider deployment and improve the comparability of competing offerings.
Demand-side behavior is changing as well. Commercial building owners, retailers, and event operators are increasingly seeking surfaces that do more than enclose or illuminate a space; they want architecture that communicates, adapts, and engages. Transparent LED glass meets this expectation by allowing displays to coexist with daylight, views, and spatial openness. In retail and commercial facades, the value proposition extends beyond signage: it encompasses brand presence, wayfinding, and the ability to refresh content without replacing physical infrastructure. In decorative contexts, the appeal lies in the combination of lighting quality and transparency, enabling designers to create immersive interior environments that feel both modern and integrated. The demand pattern is therefore not limited to a single application; it spans decorative, informational, and experiential uses, each with its own performance requirements and procurement rhythms.
Cost structure and supply chain dynamics also play a decisive role. The raw material environment has shown meaningful movement. Soda ash prices declined during 2025 due to oversupply and softer demand from key industries, and by mid-2026 the commodity was trading flat with declines measured over both the month and the year. For LED glass producers, commodity movements matter because they influence input costs, pricing flexibility, and the economics of scaling production. When material costs ease, there is more room to invest in process improvements, certification, and application development. Conversely, sustained volatility can compress margins and sharpen the focus on yield, material efficiency, and supplier relationships. The current environment suggests a favorable but not guaranteed window for cost optimization, making disciplined sourcing and transparent cost modeling important strategic priorities.
Competitive Landscape and Leadership Strategies
The competitive map in LED glass is shaped by firms that have chosen distinct paths to differentiation. Rather than competing solely on price, leading participants are building advantage through configuration expertise, application focus, and the ability to deliver transparent digital displays that perform reliably in architectural settings.
Clear Motion Glass, based in York, Pennsylvania, has positioned itself around cvLED transparent LED glass solutions that integrate high-resolution LEDs directly into architectural-grade safety glass. Its portfolio spans laminated, surface-applied, and ceiling-hung configurations, which indicates a strategy centered on flexibility of installation and adaptability to different project constraints. By emphasizing transparent digital displays that maintain architectural integrity, the company addresses a core specifier concern: how to introduce digital content without sacrificing the visual and structural qualities of glass. This approach suggests a focus on integration quality, safety compliance, and the ability to work within existing building systems rather than requiring wholesale redesigns.
Glasstronn, headquartered in Bangalore, India, has built its identity around transparent glass LED solutions that combine glass with LED technology for vibrant, ultra-transparent digital displays. Its emphasis on retail, commercial, and architectural applications points to a strategy oriented toward high-visibility environments where display quality and transparency are equally important. By focusing on the intersection of aesthetics and performance, the company aligns itself with the growing demand for facades and interior surfaces that serve both functional and brand-communication roles. The publication of industry-facing content on switchable glass innovations further signals a commitment to thought leadership and to shaping specifier expectations around transparent LED glass as a mainstream architectural choice.
The market structure suggests a landscape that is neither fully consolidated nor purely fragmented. With the top three and top five players holding modest combined shares, there is room for specialization, regional expansion, and application-led growth. At the same time, the presence of recognizable players with clear configuration strategies indicates that differentiation is achievable through engineering depth and application expertise. The evolution of the competitive field is likely to follow one of two complementary paths. First, integration and partnership models may become more important as LED glass moves into complex environments such as sports venues, retail facades, and decorative interiors. In these settings, success depends not only on the glass itself but on the ability to coordinate with media networks, installation teams, and building systems. Second, new entrants may target specific niches where transparency, form factor, or cost profiles create openings that broader players do not fully address. The result could be a market that remains diverse at the product level while consolidating around a smaller set of trusted integration partners in high-value applications.
For buyers and competitors alike, the strategic lesson is that leadership is increasingly defined by reliability in real-world deployments, the ability to navigate safety and certification requirements, and the capacity to pair hardware with content and installation expertise. Price competition exists, but it is unlikely to be the primary separator over the forecast horizon. Instead, the firms that stand out will be those that can demonstrate repeatable performance across configurations, maintain compliance readiness, and align their product roadmaps with where demand is moving, particularly in facade, decorative, and specialized venue applications.
Future Trends and Commercial Implications (2026–2032)
Looking forward, several trends are likely to shape the LED glass market over the next three to five years. These trends are not abstract; they carry direct implications for product strategy, partnership choices, and investment timing.
One important trend is the deeper integration of LED glass into architectural and venue systems as a standard option rather than a special-occasion solution. The extension of LED glass into tournament courts and the growing attention to retail and commercial facades indicate that the technology is moving toward repeatable deployment models. As more projects demonstrate durability and maintenance feasibility, specifiers will become more comfortable specifying transparent LED glass in new builds and retrofits. The commercial opportunity here lies in building application-ready portfolios that address installation logistics, content integration, and post-installation support, rather than selling glass as a standalone component.
A second trend is the continued push toward thinner, more transparent, and more seamlessly integrated forms. Standardization activity and certification pathways are gradually reducing uncertainty, which should encourage experimentation with lighter configurations and new integration methods. Thinner glass can improve aesthetics and reduce perceived visual weight, but it must still satisfy safety expectations and performance requirements. The firms that can balance these priorities through material science, lamination expertise, and testing discipline will be well positioned to capture demand from designers and architects who want digital functionality without compromising spatial quality. The risk is that thin-glass adoption may progress unevenly across regions, especially where safety glazing certification remains a practical hurdle.
A third trend is cost and supply chain normalization influencing product economics and pricing strategies. Commodity movements in inputs such as soda ash have the potential to improve unit economics when they move favorably, and the recent easing in prices has created a more supportive backdrop. However, commodity markets are cyclical, and reliance on temporary cost relief can be risky. The more durable advantage will come from process efficiency, yield improvement, and supplier diversification. Companies that treat cost structure as a strategic variable, rather than a passive outcome, will be better equipped to maintain margins through market cycles and to invest in the application development that drives long-term growth.
These trends connect to tangible commercial opportunities. For product developers, the opportunity is to build configurable platforms that can be adapted across decorative, facade, and venue applications without compromising safety or transparency. For integration and systems players, the opportunity is to offer end-to-end solutions that reduce specification risk and accelerate project timelines. For investors, the opportunity lies in identifying participants with credible certification readiness, application traction, and disciplined cost management, rather than those relying on short-term commodity tailwinds. The principal risks include regulatory variability across jurisdictions, the possibility that thin-glass adoption slows if certification costs remain high, and exposure to raw material volatility that could compress margins if not managed proactively.
Actionable Guidance for Decision-Makers
The strategic choices facing manufacturers, investors, and buyers are distinct, but they share a common need: clarity on where value is being created and where risk is concentrated. The following guidance is intended to support decision-making in the near term while keeping longer-term positioning in view.
PW Consulting
For manufacturers and product developers, the priority is to align product roadmaps with the applications that are demonstrating the strongest momentum while maintaining rigorous attention to safety, transparency, and installation practicality. Building a portfolio that spans laminated, surface-applied, and ceiling-hung configurations can broaden market access, but differentiation will come from proving repeatable performance in the environments that matter most to specifiers. It is equally important to treat certification and compliance not as a final hurdle but as a design constraint from the outset. Early alignment with recognized testing requirements reduces rework, shortens time to market, and strengthens credibility with building professionals. Finally, disciplined sourcing and cost modeling should be treated as core capabilities, not administrative functions, so that material cost fluctuations do not derail margin plans or investment in application development.
For investors and strategic partners, due diligence should focus on evidence of application traction, integration capability, and regulatory readiness rather than on headline technology claims alone. The market’s moderate concentration suggests that value can be captured by participants with clear differentiation, but it also means that not every player is positioned for sustained advantage. Evaluating a company’s ability to navigate safety glazing requirements, its track record in real-world installations, and its relationships with content, installation, and building-system partners can provide a more reliable view of durability than product narratives in isolation. Timing matters as well: the current environment offers a window in which cost structures are relatively supportive, but that window is not permanent, so investment theses should account for both near-term economics and the longer trajectory of standardization and adoption.
For buyers and procurement teams, the emphasis should be on reducing total project risk rather than minimizing unit price. Transparent LED glass is most valuable when it is specified as part of a coherent system that includes content strategy, installation planning, and maintenance considerations. Evaluating suppliers on configuration flexibility, compliance documentation, and post-installation support can prevent costly mismatches between expectation and performance. It is also prudent to assess how a supplier handles variability across regions and applications, since the same glass solution may face different certification expectations and performance demands depending on whether it is used in an interior decorative setting, a commercial facade, or a high-traffic venue. Procurement decisions that account for lifecycle cost and specification confidence are more likely to deliver durable value than those focused narrowly on initial price.
Optical Glass Market
Across all of these perspectives, the recurring theme is that detailed, current intelligence is a strategic asset. Market structure, regulatory dynamics, raw material conditions, and application momentum are all evolving, and the companies that act on the most accurate picture of these changes are best positioned to allocate capital, prioritize product development, and negotiate from strength. A complete, segmented view of the market—covering regional patterns, type and application splits, competitive positioning, and forward indicators—can sharpen these decisions and reduce the uncertainty that comes from relying on partial information. For those seeking a deeper dive with granular segmentation and tailored scenarios, the broader research resource that supports this analysis provides a more detailed foundation for planning and execution.
For detailed analysis of this topic, please visit the official page: LED Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dust Sensors Market: Why 5.4% CAGR Growth Is Reshaping Strategic Competition
By pmarketresearch, 2026-09-21
Navigating the Dust Sensors Market: Strategic Trends and Commercial Opportunities in a Tightening Air Quality Landscape
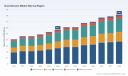
The dust sensors market stands at the intersection of environmental regulation, industrial automation, and consumer health awareness. Valuation reached an estimated $0.57 billion in 2025, expanding from $0.42 billion in 2020 at a compound annual growth rate of 5.4 percent. The trajectory points toward $0.82 billion by 2032, with the most pronounced acceleration concentrated in the 2026–2032 forecast window. This expansion is not merely a function of unit volume growth; it reflects a structural recalibration of how particulate matter is measured, monitored, and managed across commercial, industrial, and domestic environments. For executives and investors, the opportunity lies in recognizing where measurement precision, regulatory pressure, and cost discipline converge to create defensible positioning.
Beneath the headline growth figure, the market reveals a clear maturity curve. Historical expansion from 2020 through 2025 was supported by early-stage adoption in air quality monitoring and incremental industrial compliance upgrades. The next phase demands a shift from broad deployment to targeted, high-value applications where sensor data directly drives operational decisions or regulatory reporting. Market concentration remains moderate, with the top three participants holding approximately 28.5 percent of revenue and the top five reaching 38.2 percent. This fragmentation signals room for specialized players to capture niche leadership, but it also underscores the importance of differentiation in a space where commoditization pressure is building at the lower end of the performance spectrum.
Several structural challenges now shape the market's near-term evolution. The first is the tension between measurement fidelity and cost at scale. As deployment moves into dense urban networks and distributed industrial sites, the operational burden of installation, calibration, and maintenance becomes a meaningful constraint on total cost of ownership. The second challenge is regulatory fragmentation. Differing enforcement timelines, reporting formats, and particulate thresholds across jurisdictions create compliance complexity for manufacturers and end-users alike, requiring sensor solutions that can adapt to varying validation standards without sacrificing accuracy. The third is the performance ceiling of lower-cost optical technologies in harsh or high-particulate environments. Industrial dust, powder handling, and bulk solids operations expose sensors to contamination, humidity, and particle size distributions that can degrade readings if the underlying optical architecture and self-cleaning mechanisms are not engineered for those conditions. These pressures are not bottlenecks so much as filters: they determine which offerings translate into durable market share.
Key Drivers Reshaping Demand and Value Capture
Technology innovation continues to redefine what dust sensors can deliver in real time. Advances in optical detection architectures, laser-based particle sizing, and integrated signal processing are enabling tighter correlation between sensor output and reference-grade measurements. For environmental and indoor air quality applications, this translates into actionable data that can trigger filtration adjustments, ventilation control, or compliance documentation without relying on sporadic manual sampling. In industrial contexts, the shift toward continuous emissions and leak detection monitoring is reducing dependence on periodic checks, allowing operators to identify filter degradation or fugitive dust events sooner. The commercial value of these capabilities lies in their ability to convert raw particulate readings into operational signals that reduce downtime, protect equipment, and support audit-ready reporting.
Policy and regulatory pressure is reinforcing demand from the top down. In the European Union, the revised Ambient Air Quality Directive sets stricter limit values for PM2.5, reducing the annual limit value by more than half to align with WHO guidelines and streamlining provisions for twelve air pollutants. This creates a direct compliance pull for more granular, auditable monitoring across industrial sites, urban environments, and managed indoor spaces. In parallel, U.S. EPA monitoring priorities for 2025–2026 emphasize the deployment of next-generation low-cost sensors for PM2.5 in urban networks, reflecting a broader shift toward distributed measurement architectures that supplement reference stations. These regulatory signals expand the addressable demand base, but they also raise the bar for sensor validation, data credibility, and documentation traceability.
Demand-side behavior is changing on both the enterprise and consumer fronts. Organizations are increasingly treating air quality as an operational and reputational variable rather than a compliance checkbox. In healthcare, cleanroom-adjacent environments, and facilities with vulnerable occupants, particulate monitoring is being integrated into broader environmental management and ventilation strategies. In automotive and aerospace contexts, cabin air quality and sensitive component protection are driving interest in compact, reliable monitoring modules. On the consumer side, family-use applications continue to expand, supported by greater awareness of indoor air quality and the availability of smaller, lower-power devices. The strategic implication is that demand is becoming more application-specific, which rewards providers that can frame sensor performance in terms of the end-use outcome rather than raw specifications alone.
Supply chain and cost dynamics add another layer of complexity. Laser-based dust sensors depend on high-precision optical components and laser sources that require advanced polymer injection molding processes, tying performance to specialized manufacturing capabilities and materials availability. At the same time, labor costs associated with installing and calibrating low-cost sensors in dense urban networks remain a key operational constraint, particularly where large-scale deployments are contemplated. These factors push the market toward solutions that balance upfront hardware cost with ease of deployment, modularity, and maintenance efficiency. For suppliers, the winners are increasingly those who can reduce the hidden costs of integration and ongoing calibration rather than compete solely on unit price.
Competitive Landscape and the Logic of Differentiation
The competitive field is shaped by a mix of specialist sensor manufacturers and broader measurement-player portfolios, each pursuing a distinct value proposition. ENVEA, based in France, has focused its offering on real-time industrial emissions and filter leak detection through its ProSens and Dusty dust monitors. Its positioning reflects an emphasis on continuous industrial monitoring where measurement continuity and operational reliability matter more than consumer-facing form factors. In April 2025, the company launched a next-generation Optical Aerosol Spectrometer for real-time particulate matter monitoring, a move that signals an intent to extend high-resolution measurement capabilities into broader environmental and compliance contexts. The strategic takeaway is that advanced optical architectures can be used to bridge industrial emissions monitoring and ambient air quality requirements, provided the instrumentation is validated for the intended deployment environment.
Air Quality Sensor Market
Chinese manufacturers illustrate a different competitive logic, centered on laser and infrared dust sensors for air quality monitoring and industrial leak detection. Chengdu Pulse Optics-tech and Zhengzhou Winsen Electronics both emphasize laser and infrared-based sensing for air quality applications, with product families such as the ZH10 laser dust sensor and supporting infrared variants. Their trajectory suggests scale-oriented development aimed at cost-sensitive monitoring segments, where integration flexibility and price competitiveness can accelerate adoption. Cubic Sensor and Instrument takes a more application-specific approach, focusing on industrial dust sensors for powder and bulk solids leak detection. This specialization matters because it aligns sensor design with the particle types, loading conditions, and contamination risks encountered in material handling environments, rather than treating all particulate monitoring as a single category. The broader implication is that regional manufacturing depth and application-specific calibration can create defensible positions even in a market with many participants.
Western suppliers in automotive and HVAC-adjacent segments are pursuing integration-led differentiation. Amphenol Advanced Sensors, through its Telaire SMART Dust Sensor and DSF series, targets automotive and air quality applications, indicating a focus on embedding particulate sensing into vehicle and built-environment platforms where size, reliability, and system compatibility are critical. Sensirion, based in Switzerland, offers the SPS30 PM2.5 sensor for HVAC and air quality applications, an approach that connects particulate measurement to air circulation and filtration control in building systems. Shinyei Corporation, from Japan, continues to develop optical dust sensors such as the PPD series for air quality monitoring, reinforcing a long-standing emphasis on compact optical detection suitable for distributed monitoring. Collectively, these profiles show that competitive advantage is increasingly defined by where the sensor is integrated and what control or reporting function it enables, rather than by detection method alone.
The market structure is evolving along three trajectories. First, consolidation pressure is building at the lower-performance end, where generic optical sensors face margin compression and replacement risk from better-integrated alternatives. Second, specialization is intensifying in higher-value industrial and compliance-grade segments, where validation, durability, and data usability justifypremium positioning. Third, new entrants are likely to emerge at the intersection of sensor hardware and data services, particularly where low-cost networks can be combined with calibration support, remote diagnostics, and software layers that make readings operationally useful. For buyers and partners, this means supplier selection should weigh not only detection performance but also the ecosystem around calibration, maintenance, integration support, and data-handling practices.
Forward Outlook: Trends That Will Shape the Next Three to Five Years
The first major trend is the convergence of distributed sensing with regulatory-grade data expectations. As urban and industrial monitoring networks expand, the market will increasingly reward sensor platforms that can operate at scale while maintaining enough measurement consistency to support reporting, trend analysis, and operational decision-making. The commercial opportunity here lies in enabling large-scale deployments without surrendering data credibility, which requires thoughtful calibration strategies, robust optical designs, and software that can contextualize readings across sites and time periods. Companies that can reduce the hidden burden of installation and calibration will be better positioned to serve dense network scenarios.
A second trend is the migration of dust sensing from standalone measurement toward embedded control and predictive maintenance. In HVAC, industrial filtration, and material handling environments, particulate data is becoming part of a feedback loop that adjusts airflow, flags filter status, or alerts operators to leak conditions before they escalate. This creates a shift in value capture from device sales alone to solutions that contribute to energy efficiency, equipment protection, and compliance readiness. The opportunity is strongest for suppliers that can articulate how sensor data integrates with existing control systems and what operational outcomes it supports, rather than positioning the sensor purely as an information source.
PW Consulting Automotive & Machinery Research Center
A third trend is the widening performance gap between generic low-cost sensors and application-hardened solutions. As deployment scales, users are becoming more discerning about where lower-cost units are appropriate and where contamination, humidity, particle size range, or compliance documentation make ruggedized designs necessary. This does not mean the low-cost segment will disappear; it means its role will become more clearly defined. The strategic risk is for suppliers that overgeneralize their offering and get pulled into price competition in applications where performance and maintainability matter more. The corresponding opportunity is to segment the market deliberately and align product architecture, validation claims, and service support with the requirements of each segment.
Underpinning these trends are uncertainties that decision-makers should monitor. Regulatory timelines and enforcement intensity can vary by region, affecting demand pacing and validation requirements. Supply chain dependencies for precision optics and laser sources may influence cost and availability, particularly if manufacturing bottlenecks emerge around advanced polymer injection molding or specialized components. Labor and installation constraints may continue to shape the economics of large-scale urban networks, making modular, field-serviceable designs more valuable. Finally, data credibility remains a persistent question in distributed sensing, especially where readings inform compliance or public-facing reporting. Suppliers and end-users alike will need to manage expectations around uncertainty, calibration intervals, and the role of reference correlation in networked deployments.
Actionable Guidance for Manufacturers, Investors, and Procurement Leaders
For manufacturers, the priority is to define product strategy around use-case outcomes rather than detection method alone. That means mapping sensor architectures to the environments they will face, clarifying where calibration support, self-cleaning, or modular replacement add real value, and positioning data outputs in terms of operational or compliance utility. Companies that can demonstrate repeatability across installation conditions, simplify integration with ventilation or filtration control, and provide clear documentation for audit contexts will be better equipped to hold pricing power as the market matures. Equally important is deciding where not to compete: undifferentiated low-cost segments may generate volume, but margins and longevity will depend on whether the offering is tied to a defensible application fit or service model.
For investors, the most instructive question is where value will concentrate as the market evolves from broad adoption to more demanding applications. Segments tied to industrial leak detection, continuous emissions monitoring, HVAC integration, and compliance-aligned urban networks are likely to support more resilient economics than generic consumer-facing devices, provided the supplier can meet validation and maintainability expectations. Investment thesis-building should therefore emphasize differentiation in optical design, calibration and service strategy, integration readiness, and the ability to support data credibility at scale. It should also account for regional regulatory momentum, since policy-driven demand can create near-term pull but may shift in emphasis as standards harmonize or enforcement patterns change.
For procurement and operations leaders, sensor selection should be evaluated as a total-cost and risk decision, not just a hardware comparison. The relevant considerations include calibration and maintenance burden, expected service life under local particulate and humidity conditions, compatibility with existing control or reporting infrastructure, and the supplier's ability to support validation or documentation requirements where compliance is involved. In dense urban or multi-site deployments, installation labor and ongoing calibration constraints should be priced into the decision, because they can dominate lifecycle cost. Procurement teams also benefit from aligning sensor specifications with the actual decisions the data will inform: if readings drive filter changes, ventilation adjustments, or compliance reporting, then measurement stability and traceability become more important than marginal sensitivity gains in benign conditions.
As the market moves from early adoption to more disciplined, application-specific deployment, the ability to separate durable opportunity from transient hype will depend on detailed segmentation, validation expectations, and regional regulatory pacing. The broader market direction is clear, but the commercial winners will be those who can match sensor capabilities to the operational and compliance realities of each segment. For decision-makers seeking granular breakdowns of regional demand patterns, application-level sizing, company-level positioning, and scenario-based forecasts, a full market study provides the additional structure needed to translate these trends into a concrete investment, product, or procurement roadmap.
UV Sensors Market
For detailed analysis of this topic, please visit the official page: Dust Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Enterprise Resource Planning Software Market: Strategic Trends and Commercial Opportunities in a Transforming Landscape
Market Snapshot: Scale, Trajectory, and Structural Pressure Points
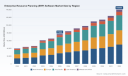
The enterprise resource planning (ERP) software market has transitioned from a mature, incremental-growth category into a structurally expanding ecosystem. Total revenue crossed the 77 billion-dollar threshold in 2025, building on a decade-long expansion that saw the market scale from roughly 40 billion in 2020. The forward trajectory is notably steep, with projected revenue reaching 140 billion by 2032. A compound annual growth rate of 9.5 percent over the 2026 to 2032 period signals that ERP is no longer a back-office utility but a central operating platform where finance, supply chain, human capital, and customer operations converge. The pace of expansion reflects a market that is simultaneously consolidating around cloud delivery, broadening its functional scope, and absorbing new demand from mid-market and cross-industry adopters who previously viewed integrated suites as out of reach.
Beneath the headline growth, three structural challenges are reshaping how buyers evaluate ERP investments and how vendors compete for wallet share. The first is the tension between speed-to-value and implementation complexity. Cloud deployments have lowered the initial capital barrier by removing hardware procurement and shifting costs into subscription and hosting models, but the long-term cost curve depends heavily on configuration discipline, integration maturity, and change management. For smaller enterprises, customization concerns, training requirements, and upgrade costs remain recurring friction points that can erode the promised efficiency gains of a modern platform. The second challenge is regulatory and compliance fluidity. Cloud ERP systems must continuously align with data protection, industry-specific, and financial reporting obligations, while built-in automatic updates create a moving target for internal audit and control teams. Regulatory signals in 2025, including deregulatory proposals aimed at reducing compliance burdens for data and AI obligations in cloud environments, introduce both relief and uncertainty, as the exact scope and timing of obligations continue to evolve. The third challenge is organizational readiness for AI-infused workflows. ERP vendors are embedding intelligent automation, predictive insights, and agent-based capabilities across finance, procurement, and supply chain functions, yet enterprises often lack the data governance, process standardization, and skills infrastructure required to extract measurable value. Without that foundation, AI features risk becoming superficial differentiators rather than operational levers.
For executives and planners, the strategic implication is clear: ERP is becoming a multi-year operating decision rather than a one-time software purchase. The winners will be organizations that treat platform selection as a capabilities investment, align deployment scope with process maturity, and build the governance needed to sustain compliance and continuous improvement.
Core Drivers Reshaping Demand and Vendor Behavior
Several interlocking forces explain why the ERP market is expanding at a pace that outstrips many traditional enterprise software categories. These drivers are not isolated; they reinforce each other and create distinct opportunities for organizations that can position ERP as an enabler of operational resilience and decision velocity.
Technology Innovation and Platform Convergence
The most visible driver is the convergence of cloud architecture, embedded analytics, and AI-enabled automation into a single operational fabric. Cloud ERP has moved from a deployment preference to the dominant delivery model, supported by subscription economics that reduce upfront infrastructure costs while enabling continuous updates. More importantly, the platform layer is increasingly intelligent. Recent product movements show vendors moving beyond dashboards and alerts toward agent-based tooling that can build, connect, and verify AI agents across HR, finance, and IT environments. This shift matters because it reframes ERP from a record-keeping system to an orchestration layer that can coordinate transactions, reconciliations, approvals, and exception handling with less manual intervention.
Accounting Software Market
The commercial impact is twofold. First, buyers can justify ERP investments on the basis of operational agility and reduced cycle times rather than pure cost displacement. Second, vendors are competing on ecosystem breadth, integration depth, and the ability to extend functionality through low-code or partner-built extensions. The practical takeaway is that organizations should evaluate platforms not only on core ledger and reporting strength, but also on how readily the system can absorb new workflows, connect to specialized applications, and support governed automation without creating brittle custom code.
Regulatory and Compliance Dynamics
Policy and regulatory environments are becoming both a constraint and a catalyst. Cloud ERP systems must navigate overlapping obligations related to data protection, financial reporting standards, and industry-specific controls. At the same time, vendors are consolidating compliance capabilities into the platform itself, with automatic updates and configuration controls designed to keep organizations aligned as rules change. This is particularly relevant for multinational enterprises and regulated industries, where manual remediation and fragmented systems can turn compliance into a recurring cost center.
Recent regulatory developments illustrate the direction of travel. In late 2025, European regulators signaled a deregulatory push intended to reduce compliance burdens associated with data and AI obligations in cloud ERP contexts. The implication is nuanced: reducing friction can accelerate adoption and lower the cost of governance, but the exact boundaries of reduced obligations and the timing of implementation remain important variables for procurement and risk teams. For decision-makers, the strategic lesson is to treat compliance not as a static checkbox but as a platform selection criterion, weighing how much regulatory upkeep can be absorbed by the vendor versus how much must remain inside the enterprise.
Demand-Side Shifts in Enterprise Behavior
Buyer behavior is changing as operational complexity rises and expectations for real-time visibility increase. Finance and accounting remain a foundational application area, but demand is broadening across human resources, supply chain management, customer relationship management, and inventory management. This expansion reflects a broader shift in how enterprises organize work: functional silos are increasingly undesirable because they slow decision-making, duplicate data entry, and weaken cross-functional accountability. Integrated suites are therefore attractive not because they eliminate specialized tools, but because they reduce fragmentation and create a shared data backbone for planning, execution, and control.
At the same time, the mid-market is a critical demand engine. Smaller organizations are adopting ERP at increasing rates, yet they encounter familiar implementation concerns around customization, training, and upgrade exposure. That dynamic is reshaping the vendor landscape, with some platforms emphasizing simplicity, rapid deployment, and modular adoption, while others continue to target complex, multi-entity, multi-currency environments. The commercial opportunity lies in matching platform scope to organizational maturity: enterprises that over-customize prematurely or underestimate change management often pay for it later in upgrade costs and adoption friction, while those that standardize first and extend later tend to realize value faster.
Cost Structure and Supply-Side Realities
Cost structure is evolving in ways that influence both adoption timing and vendor strategy. Cloud ERP implementations reduce upfront hardware expenditure, which lowers the barrier to entry and enables faster initial deployment. However, subscription and hosting fees persist over time, and total cost of ownership increasingly depends on integration work, data migration quality, user adoption, and the need for ongoing configuration support. In effect, the cost conversation has shifted from capital avoidance to lifecycle efficiency.
This shift is particularly important for procurement teams and finance leaders. The cheapest entry point is not always the lowest-risk path if the platform requires heavy customization or if internal teams lack the bandwidth to manage upgrades and extensions. Conversely, a platform with stronger out-of-the-box functionality and clearer upgrade paths may deliver better long-term economics, even if initial subscription pricing appears higher. The broader supply-side implication is that vendors are competing on implementation velocity, partner ecosystems, and the predictability of ongoing costs, not merely on feature count.
Competitive Positioning and the Evolving Vendor Landscape
The ERP market remains concentrated, with a relatively small group of large providers commanding a substantial share of total revenue. This concentration reflects the scale required to maintain broad functional coverage, global compliance support, and a mature partner ecosystem. At the same time, the landscape is not static. Consolidation, product divergence, and targeted specialization are all visible at once, creating a more nuanced competitive map than the traditional flagship-versus challenger framing suggests.
Large platform vendors have pursued strategies that emphasize ecosystem integration and cloud-native architectures. SAP continues to anchor its positioning around its S/4HANA and business one offerings, with modules spanning finance, supply chain, and manufacturing. Oracle has reinforced its Fusion Cloud ERP and NetSuite footprint, emphasizing finance, operations, and global supply chain capabilities. Microsoft has leaned into Dynamics 365 with AI-driven integrations across finance and supply chain, while also serving a broad base through Business Central. Workday has expanded its ERP scope around finance, HCM, and enterprise operations, increasingly highlighting AI agent capabilities as part of its differentiation. These players share a common strategic theme: they are positioning ERP as an integrated operating platform rather than a set of isolated modules, and they are investing heavily in cloud delivery, data continuity, and intelligent automation.
Alongside the large platforms, specialized and mid-market vendors continue to compete on industry fit, deployment flexibility, and total cost predictability. Infor focuses on cloud suites for manufacturing, distribution, and industry-specific scenarios. QAD and Epicor target manufacturing, distribution, and service-oriented environments with adaptive or kinetic-oriented ERP formulations. Sage maintains a strong presence in finance, accounting, and small-to-medium enterprise contexts, while Acumatica emphasizes flexible cloud ERP with AI-capable financial and operational management. Odoo offers an approach built around CRM, finance, inventory, and manufacturing with open-source options that appeal to organizations seeking modularity and extensibility. The diversity of these offerings matters because ERP value is highly context-dependent: a platform that excels in a complex multinational manufacturing environment may be overkill for a growing services firm, while a streamlined system may struggle in a heavily regulated multi-entity operation.
Recent market moves underscore how quickly the landscape can shift. In mid-2025, Acumatica reached a definitive agreement to be acquired by Vista Equity Partners, a transaction that signals the continued investor appetite for scalable cloud ERP platforms with clear mid-market positioning and growth potential. In mid-2026, Workday expanded its agent-related tooling with developer agents, agent-ready tools, and agent passport capabilities designed to support building, connecting, and verifying AI agents across HR, finance, and IT environments. These developments are not isolated events; they reflect two broader dynamics. First, capital and M&A activity continues to reshape ownership and go-to-market intensity in the sector. Second, product roadmaps are increasingly oriented around governed AI and orchestration, with vendors racing to make ERP environments more programmable and agent-compatible without sacrificing control.
PW Consulting
The competitive trend that follows from this mix is a market that is simultaneously consolidating at the top and fragmenting by use case. Large platforms are broadening their ecosystems and embedding intelligence, while specialized vendors compete on vertical depth, deployment simplicity, or open extensibility. New entrants and partner-built solutions are also shaping the edges of the market, particularly where organizations want best-of-breed integration around a core ERP backbone. For buyers, the practical implication is that vendor selection should be treated as a fit-and-evolution question: which platform aligns with current process needs, which one can grow with the organization, and which one offers a credible path through compliance, integration, and AI adoption without forcing excessive customization.
Supplier Relationship Management System Market
Forward Outlook: Three Trends to Watch Over the Next Three to Five Years
Looking ahead, the ERP market is likely to be defined by a small number of high-impact trends that will shape both vendor strategies and enterprise buying behavior. These trends are not speculative; they are already visible in product roadmaps, implementation patterns, and regulatory signals, but their full commercial implications will unfold gradually.
Intelligence as a Core ERP Capability, Not a Add-On
The next phase of ERP competition will center on how reliably platforms can support governed automation and agent-based workflows. The move toward developer tools, agent-ready environments, and verification mechanisms indicates that AI will increasingly be treated as an operational layer inside ERP rather than a separate analytics overlay. For enterprises, this creates an opportunity to reduce manual reconciliation, improve exception handling, and accelerate cycle times in finance and supply chain processes. The risk is that organizations adopt agent-enabled features before they have standardized data, cleaned master records, and defined control boundaries. In that scenario, intelligence can amplify process noise rather than reduce it. The strategic opportunity, then, is to pair platform-level intelligence with disciplined data governance and clearly scoped automation use cases.
Compliance and Regulatory Agility Becoming a Buying Criterion
As cloud ERP systems continue to absorb more regulatory upkeep through automatic updates and built-in controls, enterprises will increasingly evaluate vendors on their ability to help them stay aligned without excessive manual intervention. At the same time, regulatory environments will remain fluid, with deregulatory signals and evolving obligations creating periods of both opportunity and uncertainty. Organizations that treat compliance as an ongoing platform capability are better positioned to reduce audit friction and avoid reactive remediation costs. The commercial opportunity is to select platforms and implementation models that make regulatory adaptation part of the operating rhythm rather than a periodic project.
Deployment Economics and Implementation Discipline Driving TCO Outcomes
Cloud adoption will continue to lower upfront barriers, but leadership teams will become more sophisticated about lifecycle economics. Over the next several years, buyers are likely to compare solutions less on initial price and more on implementation risk, upgrade exposure, training burden, and the cost of maintaining custom extensions. This should favor platforms and partners that can deliver predictable deployment timelines, modular adoption, and cleaner upgrade paths. For vendors, the implication is that implementation quality and partner ecosystems will become more important competitive levers, not just product features. For enterprises, it means that the best ERP decision is often the one that balances ambition with implementation realism, especially for organizations that have limited internal bandwidth.
What Decision-Makers Should Do Next
ERP strategy is no longer a procurement exercise; it is an operating model decision. The most effective responses will differ by role, but several priorities apply across the board.
- For manufacturers and operationally complex enterprises, prioritize platforms that can connect finance, supply chain, inventory, and manufacturing workflows without forcing excessive customization. Standardization first, extension second, is usually the most durable path to value, especially when supply chain volatility and compliance demands are high.
- For investors and market observers, focus on the signals that indicate durable competitive advantage: cloud delivery maturity, ecosystem extensibility, agent-ready tooling, and evidence that implementation and upgrade economics are improving rather than worsening. Ownership changes and product launches matter, but they should be evaluated against whether they strengthen or weaken a vendor’s ability to serve complex enterprise needs over time.
- For procurement and finance leaders evaluating ERP purchases, treat total cost of ownership as a lifecycle question. Compare not only subscription pricing, but also implementation complexity, training demands, customization exposure, and the operational burden of maintaining compliance and upgrades. A lower entry cost can be attractive, but it should not come at the expense of long-term maintainability.
Each of these priorities benefits from deeper, segment-level intelligence. Market-wide figures provide direction, but the real decisions happen in the details: which deployment model fits a given operating profile, which functional areas are expanding fastest in a specific industry, how vendor strategies differ by enterprise size, and where implementation risk is most likely to undermine projected value. The ERP market is large, fast-moving, and increasingly defined by platform intelligence, regulatory agility, and deployment discipline. Organizations that make decisions with that context in mind are better positioned to convert ERP from a cost center into a strategic operating asset.
For detailed analysis of this topic, please visit the official page: Enterprise Resource Planning (ERP) Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cationic Conditioning Polymers Market: How 6.98% CAGR and Hair Care Demand Reshape Growth Beyond 2032
By pmarketresearch, 2026-09-21
The Cationic Conditioning Polymers Market: Strategic Trends and Commercial Opportunities
The global market for cationic conditioning polymers has entered a phase of disciplined expansion, driven by fundamental shifts in personal care formulation philosophies and regulatory redefinition of what constitutes acceptable ingredient architecture. Valued at approximately 502.7 million USD in 2025, the market has grown from 358.22 million USD in 2020, reflecting a compound annual growth rate of 6.98 percent through the forecast horizon to 2032. This trajectory signals more than incremental volume growth; it points to a structural transformation in how conditioners, shampoos, and related personal care matrices are engineered for performance, sensorial appeal, and environmental compliance. For executives and investors navigating specialty chemicals and beauty care supply chains, the market presents a landscape where formulation science, regulatory foresight, and supply chain agility now determine competitive positioning more than scale alone.
Market Status and Defining Challenges
From Volume Recovery to Formulation Redesign
The historical 2020–2025 period illustrates a recovery curve that accelerated sharply after the initial disruption of the early 2020s, with market size rising to 419.89 million USD in 2022 and continuing upward to 428.24 million USD in 2023 and 480.94 million USD in 2024. The 2025 valuation of 502.7 million USD represents a market that has absorbed post-pandemic demand normalization, resumed salon and retail channel activity, and begun confronting a more stringent regulatory environment. The forecast period extends this momentum, projecting a climb toward 540.47 million USD in 2026, continuing through 608.61 million USD in 2028, and reaching 802.8 million USD by 2032. This growth path is not uniform across all formulation segments or geographies, and the uneven pace itself reveals where investment logic must be sharpened.
Three structural challenges currently define the operating environment for manufacturers, formulators, and brand owners. First, the regulatory redefinition of polymer-based microplastics in rinse-off personal care products has forced widespread reformulation. Industry tracking shows that more than 28 percent of rinse-off personal care products in 2023 required reformulation across EU nations due to polymer-based microplastic content restrictions, and EU enforcement continues to shape global formulation strategy even beyond European borders. Second, feedstock volatility has introduced margin pressure and supply uncertainty into the production of key intermediates, particularly where CHPTAC pricing fluctuates in response to global supply shocks in epichlorohydrin and trimethylamine. Third, the competitive field remains comparatively fragmented, with a CR3 of 24.6 percent and a CR5 of 26.2 percent, indicating that no small group of players dominates the market and that differentiation depends on technical capability and regulatory navigation rather than scale alone.
These challenges interact in ways that reshape sourcing, R&D prioritization, and portfolio strategy. The market is not simply expanding; it is being redesigned.
PW Consulting
Key Drivers of Market Evolution
Innovation at the Chemistry-Performance Intersection
Technical innovation is propelling the market forward by expanding the performance envelope of cationic conditioning systems. Advanced polymer architectures now deliver stronger substantivity, improved wet and dry hair manageability, and more efficient deposition at lower usage levels. Recent product introductions illustrate this direction. In February 2026, Lubrizol introduced advanced cationic conditioning polymers engineered for enhanced hair manageability, moisture retention, and compatibility in shampoos and conditioners, signaling continued investment in next-generationpersonal care active systems. In December 2025, Inolex highlighted Kerazyne MB polyesteramine as an advanced multifunctional conditioning polymer for hair and skin care, emphasizing multifunctional performance within a single ingredient platform. These developments reflect a broader shift from commodity-style conditioning agents toward actives that solve multiple formulation pain points simultaneously, such as sensory softness, rinsability, and stability in complex surfactant systems.
For formulators and procurement leaders, this shift means that ingredient selection increasingly hinges on functionality breadth and compatibility rather than cost-per-kilogram alone. Polymers that can perform under sulfate-free, mild-surfactant, or low-pH conditions carry disproportionate value in premium and claims-driven product segments, where sensory outcomes and clean-label narratives must coexist with technical reliability.
Regulatory Pressure as a Catalyst for Sustainable Design
Regulatory change is accelerating reformulation cycles and creating a market premium for biodegradable and sulfate-free cationic systems. Between 2022 and 2024, industry data indicates that 38 percent of leading firms launched sulfate-free and biodegradable cationic polymers to address eco-conscious demand, a response that aligns with both consumer sentiment and regulatory tightening. At the same time, EU enforcement of polymer-based microplastic restrictions in rinse-off products continues to influence ingredient choices globally, while China’s REACH MEE Order 12 requires regular or simplified registration for cationic polymers expected to become cationic in natural water environments, adding a compliance layer for manufacturers supplying into or through the Asia-Pacific region.
These regulatory dynamics do not merely constrain; they redirect innovation toward genuinely sustainable chemistries. Companies that can demonstrate environmental compatibility without sacrificing conditioning performance are gaining formulation preference in markets where sustainability claims must be substantiated and where downstream customers face their own compliance obligations.
Consumer and Retailer Demand Reshaping Application Priorities
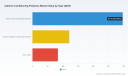
Demand-side behavior continues to favor hair care segments where conditioning performance is both visible and emotionally salient. Hair conditioners remain the largest application area, embodying the highest share of market value among end-use categories, while shampoos represent a significant secondary application, and other applications account for a smaller but strategically important portion of demand. The broad application footprint means that cationic conditioning polymers are embedded across a range of product formats, from rinse-off masks and treatments to daily-use shampoos and color-protecting systems. Consumer expectations around softness, shine, detangling, and heat protection are intensifying, particularly in premium and salon-grade offerings, pushing manufacturers to adopt actives that can deliver multi-attribute benefits without complicating formulation architecture.
The practical implication is that demand is increasingly performance-specific and claim-sensitive. Ingredients that enable simplified ingredient lists, support sulfate-free positioning, and deliver durable conditioning after rinsing are gaining share in segments where formulation transparency and sensorial consistency directly influence repurchase behavior.
Feedstock Volatility and Supply Chain Realignment
Cost structure and supply chain resilience have emerged as critical strategic variables. The CHPTAC market price volatility driven by global supply shocks in epichlorohydrin and trimethylamine has introduced uncertainty into the cost base for cationic polymer production, compelling manufacturers to revisit sourcing strategies, inventory planning, and pricing architectures. Capacity expansions and production increases are underway to address supply constraints and regional demand growth. In December 2025, Solenis expanded production capabilities for specialty cationic polymers used in personal care and industrial conditioning applications. In January 2026, Nippon Shokubai increased specialty polymer production to meet rising demand from Asia-Pacific personal care and salon-grade segments. These moves reflect a market-wide effort to secure supply, reduce lead-time risk, and align capacity with regional demand intensity.
For buyers and manufacturers, the lesson is that agility in sourcing and the ability to qualify alternative chemistries or regional suppliers are now part of core operational strategy. Reliance on single-source feedstock pathways or rigid formulation routines is becoming a liability in an environment where cost and compliance risks can shift rapidly.
Competitive Landscape and Winning Strategies
Leader Profiles and Differentiation Pathways
The competitive field includes players with distinct technical identities and regional strengths. SKW Quab Chemicals Inc., based in Saddle Brook, New Jersey, focuses on QUAB cationizing reagents and resulting cationic polymers, including cationic guar derivatives, for high-strength conditioning in personal care shampoos and conditioners. This reagent-centric approach positions the company around enabling chemistry that supports strong conditioning performance and formulation flexibility. Samyang KCI Corporation, headquartered in Seoul, South Korea, emphasizes specialty conditioning agents and cationic polymers for premium shampoos, conditioners, and hair care formulations, aligning closely with the Asia-Pacific premium and salon-grade demand trajectory. SNF, based in Andrézieux, France, focuses on water-soluble cationic polymers and film formers for hair care and conditioning in personal care applications, leveraging a broad polymer platform that spans performance and application versatility.
Solenis, headquartered in Charlotte, North Carolina, concentrates on specialty cationic polymers for personal care conditioning applications, and its December 2025 capacity expansion underscores a strategy of scaling specialty supply to meet demand while maintaining application-specific technical support. Inolex, based in Philadelphia, Pennsylvania, focuses on sustainable bio-based cationic conditioning agents and polymers for plant-based hair care and conditioning systems, distinguishing itself through a sustainability narrative anchored in bio-based chemistry and multifunctional performance, as highlighted by its December 2025 Kerazyne MB polyesteramine introduction.
Cationic Starch Market
Strategic Positioning and Differentiation Levers
Across these players, three differentiation levers are becoming decisive. First, application-specific technical support is increasingly valued, particularly where formulators require help optimizing deposition, rinse-off behavior, and compatibility with mild surfactant systems. Second, sustainable sourcing and bio-based or biodegradable positioning create claims advantage in premium and eco-conscious segments, where performance and environmental compatibility must be demonstrated together. Third, supply resilience and regional capacity alignment reduce risk for customers who are sensitive to lead times, feedstock volatility, and regulatory registration requirements across jurisdictions.
The market concentration data, with a CR3 of 24.6 percent and CR5 of 26.2 percent, indicates that scale dominance is not the primary competitive dynamic. Instead, differentiation through chemistry, application expertise, and compliance readiness determines which suppliers gain formulation preference and long-term inclusion in brand owner pipelines.
Market Structure Evolution: Consolidation Pressures and Entry Opportunities
The landscape is likely to evolve through a combination of selective consolidation and continued entry by specialized players. Scale players can capture value by integrating capacity, broadening regional coverage, and offering application breadth that reduces the number of supplier relationships for large brand owners. At the same time, new and niche entrants can compete by solving specific formulation problems, offering sustainable chemistries with verifiable claims, or serving fast-growing regional demand with localized technical support and supply. The regulatory environment also creates entry barriers where registration and compliance costs raise the threshold for new supply, but it simultaneously creates opportunities for suppliers that have already navigated these requirements and can offer ready-to-formulate, compliant solutions.
For incumbents, the strategic priority is to convert technical and compliance capabilities into stickier customer relationships. For new entrants, the entry point is not generic volume but targeted performance, sustainability substantiation, or regional supply advantage.
Forward Outlook: Trends Shaping the Next Three to Five Years
Trend One: Sustainability-Linked Performance as a Default Requirement
Over the next three to five years, sustainability-linked performance is likely to become a default expectation rather than a premium differentiator in many priority segments. As regulatory frameworks continue to tighten around polymer-based microplastics and environmental fate, and as consumer and retailer expectations around biodegradability and reduced environmental burden intensify, formulations will increasingly be judged on both function and footprint. This trend creates commercial opportunity for suppliers that can deliver conditioning performance with verifiable environmental compatibility and for brand owners that can translate those attributes into credible claims. The risk is that uncertified or poorly substantiated sustainability narratives face growing scrutiny, making technical validation and documentation essential.
Trend Two: Regional Demand Divergence and Localized Supply Strategies
Regional demand patterns are expected to diverge further, with Asia-Pacific personal care and salon-grade segments continuing to drive volume and premiumization, while North America and Europe remain centers of formulation innovation and regulatory influence. Industry developments already reflect this divergence, with Nippon Shokubai increasing specialty polymer production to meet rising Asia-Pacific demand and Solenis expanding capacity to support both personal care and industrial conditioning applications. The opportunity lies in aligning supply and technical support with regional demand intensity, reducing lead times, and building local formulation partnerships. The risk is that global supply strategies that ignore regional regulatory and demand nuances may face cost, compliance, or service-level disadvantages.
Trend Three: Ingredient Simplification and Multifunctional Actives
Formulation simplification is likely to accelerate as brand owners seek to reduce ingredient counts, improve label clarity, and streamline compliance management while preserving sensory and performance outcomes. Multifunctional conditioning polymers that combine deposition, softness, moisture retention, and compatibility in a single platform are well positioned for this environment. Recent introductions, such as Lubrizol’s advanced cationic conditioning polymers and Inolex’s Kerazyne MB polyesteramine, illustrate the direction of travel toward actives that reduce formulation complexity while expanding benefit sets. The commercial opportunity is for suppliers that can prove multifunctional performance with robust data and for brand owners that can leverage simplified systems to support claims and cost efficiency. The risk is overpromising on multifunctionality without sufficient application-specific validation, which can erode trust in a market where performance is immediately felt by consumers.
Strategic Actions for Decision Makers
For Manufacturers and Formulators
Prioritize application-specific validation of cationic systems under the conditions most relevant to your portfolio, including mild surfactant systems, sulfate-free bases, and rinse-off formats where deposition and substantivity must be balanced with clarity and feel. Build regulatory readiness into ingredient qualification processes, particularly for markets with registration or microplastic-related constraints, so that compliant options are available without last-minute reformulation pressure. Diversify feedstock and supplier pathways where feasible to mitigate CHPTAC-related volatility and reduce exposure to single-source disruptions.
Worldwide Cationic Reagent Market
For Investors and Strategic Buyers
Evaluate suppliers on the basis of technical differentiation, sustainability substantiation, and regional supply resilience rather than price alone. Companies that combine application expertise with verifiable environmental compatibility and the ability to support reformulation under evolving regulatory conditions are likely to capture higher-value positions in the value chain. Pay attention to capacity expansions and regional production moves as indicators of where demand is being served and where supply reliability is improving, since these shifts can alter competitive dynamics and customer loyalty over time.
For Procurement and Product Development Leaders
Treat cationic conditioning polymers as strategic inputs whose selection affects claims, compliance, and consumer perception, not just cost and viscosity. Qualify ingredients that support sulfate-free, biodegradable, or bio-based narratives with documented performance data, and align sourcing decisions with the regulatory and demand profile of your priority markets. Establish early engagement with suppliers that offer technical support for formulation optimization, since collaboration at the development stage can reduce time-to-market and improve the robustness of end-product performance.
The strategic value of this market lies in the intersection of performance, compliance, and supply agility. Detailed segmentation data, regional demand analysis, and tailored sourcing or portfolio recommendations can clarify where to commit resources and how to structure partnerships for the next growth cycle. Access to granular market sizing, application-level demand breakdowns, and company-level competitive assessment enables more precise decision making than aggregate trends alone can provide. For teams seeking to translate these dynamics into product roadmaps, sourcing strategies, or investment theses, comprehensive market intelligence remains a critical input to confident execution.
For detailed analysis of this topic, please visit the official page: Cationic Conditioning Polymers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Laser Drilling Machine for Aerospace: Why 6.98% CAGR Reshapes the $344.8M Market
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Laser Drilling Machine for Aerospace Market
The aerospace manufacturing sector is undergoing a fundamental transformation in how precision components are produced, and laser drilling technology sits at the center of this shift. As the 2025 market reaches an estimated 215.0 Million, with growth tracked from 2020 through the current year, the sector has demonstrated consistent expansion across the historical period. Looking ahead to 2032, the trajectory points toward a 6.98% compound annual growth rate, positioning this technology as a critical enabler for next-generation aerospace production. For executives, investors, and strategic planners, understanding the underlying dynamics of this market requires more than surface-level sizing. It demands a clear view of the technological, regulatory, and competitive forces shaping where capital and capability will flow over the next several years.
Worldwide Laser Drilling Device Market
The expansion from 2020 to 2025 reflects a steady accumulation of adoption across engine component manufacturing, airframe assemblies, and specialized aerospace applications. By 2032, revenues are projected to reach 344.8 Million, signaling a market that has moved well beyond niche adoption and is becoming embedded in standard aerospace manufacturing workflows. This growth is not uniform across all categories. Energy-based machining technologies show clear differentiation, with fiber-based systems capturing the largest share of revenue, followed by solid-state laser approaches and carbon dioxide-based configurations. Similarly, the demand landscape shows commercial aviation driving the majority of activity, while military aviation and other specialized applications contribute meaningful but smaller volumes. Regionally, established aerospace hubs continue to anchor the largest revenue pools, while emerging industrial centers are gradually expanding their footprint.
Core Challenges and Inflection Points
Despite the positive growth trajectory, the market faces structural challenges that will determine which participants capture value and which struggle to compete. Three critical dynamics deserve attention.
First, certification and qualification remain formidable barriers. Laser drilling for aerospace components must align with stringent aviation quality standards and non-conventional machining certifications. Systems designed for turbine disc cooling holes, jet engine components, and high-temperature alloy processing require documented process control, traceable quality assurance, and often original equipment manufacturer approvals. These requirements create a high bar for entry and raise the cost of scaling new offerings, but they also protect incumbents who have invested in certified workflows and established relationships with engine and airframe manufacturers.
Second, the shift in laser technology modalities is reshaping buyer expectations. Fiber-based systems have gained prominence because they offer compact form factors, high beam quality, and strong compatibility with multi-axis CNC integration. Solid-state and carbon dioxide approaches still serve specific use cases, but the momentum is clearly tilted toward platforms that can deliver micro-hole precision with minimal heat-affected zones and predictable cycle times. Manufacturers that continue to rely on legacy process chains without adapting to fiber and hybrid architectures risk being outcompeted on throughput and repeatability.
Third, the demand environment is evolving as aerospace production scales and aircraft architectures become more complex. Cooling hole density, micro-hole accuracy, and surface integrity requirements are intensifying, especially for turbine blades, vanes, and high-performance structural parts. At the same time, the industry is looking for automation, monitoring, and software integration that can reduce variability across high-mix production runs. This places pressure on equipment suppliers and service providers to deliver not just hardware, but integrated process solutions that include control software, inspection feedback, and application engineering support.
Key Drivers Shaping Market Direction
The market is being pulled forward by a combination of technology advancement, regulatory frameworks, demand-side transformation, and cost structure evolution. Each driver reinforces the others, creating a coherent case for continued investment in laser drilling capabilities.
Worldwide Solar Laser Drilling Market
Technology Innovation and Breakthroughs
Precision and speed are becoming defining competitive dimensions. Advanced multi-axis systems now support positioning accuracy on the order of micrometers while enabling drilling rates that can reach hundreds of bores per second in optimized configurations. These capabilities are particularly relevant for effusion cooling holes in turbine discs and engine components, where geometry, diameter consistency, and surface quality directly affect performance and lifecycle cost. Fiber laser integration with 5-axis and 7-axis CNC architectures has expanded the feasible design space for drilling in complex contours and 3D aerospace alloys. In parallel, software and monitoring layers are improving process stability, allowing operators to manage trepanning, micro-hole patterns, and specialized flow or optical products with greater control and repeatability.
Policy and Regulatory Environment
Aviation quality standards and non-conventional machining certification requirements create both a barrier and a catalyst. Regulatory regimes and OEM quality expectations push manufacturers toward documented process control, validated machine performance, and certified service practices. This environment favors suppliers that can demonstrate compliance with recognized aerospace standards and provide the audit trail that engine and airframe producers require. At the same time, the standardization of laser drilling for critical cooling and precision hole applications reinforces its role as a preferred process in high-temperature alloy manufacturing, supporting long-term demand stability beyond cyclical production fluctuations.
Demand-Side Changes
Commercial aviation continues to be the dominant application driver, reflecting the scale of production, aftermarket demand, and the ongoing need for precision cooling and micro-hole features across engine and airframe components. Military aviation adds a distinct set of requirements, where performance margins, material behavior under extreme conditions, and component reliability place a premium on advanced drilling technology. Beyond these core segments, specialized applications in flow control, optical products, and calibrated micro-leak features are creating pockets of high-value demand. The broader trend is toward more demanding geometries and tighter tolerances, which increases the appeal of laser processes that can maintain precision across difficult-to-machine materials and composite structures.
Supply Chain and Cost Structure Evolution
The economics of laser drilling are shifting as equipment becomes more integrated, automation more accessible, and service models more flexible. Multi-axis platforms with fiber lasers can reduce rework and improve throughput by minimizing heat-affected zones and improving hole quality consistency. For high-mix production, the ability to switch between configurations, control processes through software, and integrate monitoring reduces the cost of changeovers and improves asset utilization. At the same time, certified service providers and system integrators are expanding their geographic reach, allowing manufacturers to access specialized drilling capability without always investing in full in-house capacity. This combination of capital efficiency and capability access is changing how aerospace manufacturers evaluate their sourcing and production strategies.
Competitive Landscape and Leading Strategies
The market features a mix of established machine builders, specialized service providers, and technology integrators, each pursuing a distinct route to value. The competitive field is not dominated by a single model, and concentration remains moderate, indicating that differentiation and application expertise still matter greatly. This environment rewards companies that can combine hardware performance with certification readiness, software-enabled process control, and strong OEM relationships.
Strategic Positioning Among Leading Participants
DMG MORI has built its positioning around high-end multi-axis laser machining with fiber laser integration for precision drilling of turbine blades, vanes, and aerospace components. Its 5-axis LASERTEC PowerDrill series emphasizes precision, process software, and shape-control technology, targeting high-value engine and IGT component manufacturing where accuracy and repeatability are central. The appeal lies in combining machine rigidity, laser performance, and application software into a single platform that can be qualified for demanding aerospace workflows.
Prima Power offers a different angle through multi-axis laser systems focused on high-precision micro-hole drilling with low heat-affected zones and CNC monitoring. Its LASERDYNE series is oriented toward aerospace components where micro-hole integrity and process control are critical. By emphasizing specialized processing and 3D laser drilling capabilities, Prima Power positions itself for customers who need tight control over hole quality in complex geometries, while also expanding into broader laser processing solutions that include cutting and hybrid workflows.
EBTEC Corporation has developed a strong identity around certified laser drilling services and systems for aerospace alloys and composites, supported by AS9100 and NADCAP credentials as well as OEM approvals. Its multi-axis machines, spanning Nd:YAG and fiber laser configurations across a broad power range, are designed for precision holes in demanding materials. This service-plus-equipment model gives the company a clear route to customers who value qualification readiness, OEM acceptance, and full-process support rather than hardware alone.
Corry Laser Technology focuses on high-degree-of-freedom moving beam systems for trepanning and micro-hole drilling in 3D aerospace alloys. Its emphasis on multiple industry certifications and approvals from major aerospace players signals a strategy centered on trust, qualification, and capability validation. By aligning its systems with recognized aerospace standards, the company creates a defensible position in an environment where certification is often as important as raw machining performance.
Lenox Laser and Accumet Engineering illustrate the service-oriented side of the market. Lenox Laser specializes in precision laser drilling services and systems for small-hole technology, with particular attention to calibrated micro-leaks and flow or optical products. Accumet Engineering provides precision laser drilling services for metals and ceramics, with broad regional coverage and secondary processing capability. These participants show that for many aerospace manufacturers, the decision is not only about buying equipment but also about accessing specialized process expertise, quality assurance, and capacity flexibility.
Market Evolution and Structural Trends
The competitive landscape is evolving along several axes. One is the gradual convergence of laser drilling with broader laser processing platforms, as seen in recent industry showcases where drilling capabilities are presented alongside cutting and automated modules. This convergence reduces the friction of integrating drilling into larger production cells and can improve overall facility efficiency. Another is the continued importance of certification and OEM acceptance as filters for serious competition. Participants that can demonstrate NADCAP-aligned processes and approvals from major engine and component manufacturers are better positioned to win demanding contracts and retain long-term relationships.
At the same time, the market is open enough that new entrants and specialist service providers can build niches around application expertise, material-specific process development, and regional service coverage. The moderate concentration in the market suggests that scale alone is not the only winning strategy. Differentiation through software, monitoring, process qualification, and customer support remains a viable path, especially for companies serving high-mix, high-precision production environments. Recent industry activity also indicates that the sector is actively converging around aerospace-focused demonstrations and discussions, signaling that both suppliers and end users are paying close attention to laser drilling as a strategic process rather than a peripheral capability.
Future Trends and Commercial Opportunities
Looking forward across the next three to five years, several trends are likely to shape where value is created and how participants should position themselves.
PW Consulting Automotive & Machinery Research Center
Integration of Drilling with Automated Laser Processing Cells
The direction of travel points toward more tightly integrated systems that combine drilling, cutting, and automation within unified machine concepts. This trend is already visible in recent product announcements that pair drilling modules with laser cutting workflows and smart automation. For manufacturers, the commercial opportunity lies in reducing handling, improving throughput, and standardizing process control across multiple operations. For equipment suppliers, the opportunity is to offer platforms that can serve multiple process steps without forcing customers to manage fragmented equipment portfolios. The risk is that integration raises technical complexity and can increase the importance of application engineering, service responsiveness, and customer training.
Continued Emphasis on Certification, Quality Documentation, and OEM Alignment
Aviation standards and OEM approvals will continue to act as both a constraint and a competitive moat. Systems and services that can demonstrate NADCAP-aligned machining practices and maintain the approvals required for engine and airframe components will be better positioned to access the most demanding segments. This creates a commercial opportunity for participants to invest in qualified process documentation, audit readiness, and customer-facing quality systems. It also implies that short-term pricing pressure is less important than long-term qualification credibility in high-value aerospace segments. The uncertainty is that certification requirements can evolve, and qualifying new materials or new hole geometries may require additional validation effort.
Growth in High-Precision Micro-Hole and Complex Geometry Demand
As turbine components, cooling structures, and specialized aerospace parts become more geometry-intensive, demand for precise micro-hole drilling and complex trepanning will likely remain strong. Fiber laser systems with multi-axis capability are well suited to this demand because they can address difficult materials and 3D contours while maintaining tight tolerances. The commercial opportunity here is for suppliers and service providers that can demonstrate repeatable performance on challenging alloys and composites, including low heat-affected zones and stable hole quality. The downside risk is that materials and cooling requirements can change as engine architectures evolve, which means process flexibility and continued application development will be essential.
Strategic Recommendations for Decision Makers
Different stakeholders should prioritize different actions based on their role in the value chain. The common theme is that competitive advantage will come from combining technical capability with qualification readiness, process integration, and responsive service models.
For manufacturers and production leaders, the priority is to assess where laser drilling can replace or enhance existing process chains in ways that improve quality, reduce rework, and support tighter tolerances. Before expanding capacity, it is worth evaluating whether integrating drilling with adjacent laser processes or automated modules can increase asset utilization and simplify workflow. Equally important is ensuring that selected systems or services can meet the certification and approval requirements of target applications, because those requirements often determine whether a solution is viable for production use in the first place.
For investors and technology acquirers, the most relevant signal is that the market is expanding steadily, but value capture will depend on differentiation rather than volume alone. Platforms that combine fiber laser performance with multi-axis flexibility, software-enabled process control, and strong aerospace certification readiness are better aligned with long-term demand. Service-oriented providers with OEM approvals and specialized application expertise also represent an attractive way to participate in demand without needing to compete purely on equipment commoditization. At the same time, investors should monitor integration trends and watch for consolidation among specialists, since those dynamics can reshape regional coverage and service availability.
For procurement and sourcing leaders, the focus should be on total process reliability rather than unit price alone. Laser drilling for aerospace parts often implicates quality, certification, and downstream performance, so supplier selection should weigh documented process control, traceability, approval status, and the ability to support new materials or new hole geometries. Engaging suppliers early in the qualification process can reduce later delays, particularly when component designs require micro-hole precision or complex contours. Where in-house capacity is limited, partnering with certified service providers can offer flexibility while preserving access to specialized process expertise.
For organizations navigating this market, the most practical next step is to obtain a detailed view of segment-level demand, regional dynamics, and company-specific capability maps before making major investment or sourcing decisions. The broader trends are clear, but the specifics of where demand is strongest, which certifications matter most for a given application, and how competing platforms differ on precision, integration, and service support can materially change the outcome of a strategic choice. More granular data and tailored assessments can help translate market direction into concrete capital, procurement, and partnership decisions.
The laser drilling market for aerospace is moving from steady expansion toward a more integrated, qualification-intensive, and application-driven phase. That shift creates opportunities for equipment suppliers, service providers, and manufacturers that can combine precision technology with certified processes and flexible delivery models. It also raises the stakes for participants that underestimate the importance of software, monitoring, automation, and OEM acceptance. In a market projected to grow to 344.8 Million by 2032, the winners are likely to be those who treat laser drilling not as an isolated machine purchase, but as a strategic process capability embedded in high-performance aerospace production.
For detailed analysis of this topic, please visit the official page: Laser Drilling Machine for Aerospace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Water Pump Market: Why 5.3% CAGR and Asia Pacific Resonance Redefine Growth
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Automotive Water Pump Market
The automotive water pump market has evolved from a commoditized mechanical component into a strategically critical subsystem within broader vehicle thermal management architectures. Valued at approximately $2.085 billion in 2025 and projected to reach nearly $3 billion by 2032, the segment is expanding at a compound annual growth rate of 5.3 percent over the 2026–2032 forecast horizon. This trajectory reflects more than steady replacement demand; it signals a structural shift driven by powertrain electrification, tighter emissions and thermal efficiency mandates, and the growing complexity of cooling circuits that now serve internal combustion engines, hybrid drivetrains, battery packs, and power electronics simultaneously. For executives and investors evaluating near-term industrial exposure, the water pump market offers a tractable lens into how legacy component suppliers are repositioning for electrified thermal management, how aftermarket channels are adapting to new testing and certification requirements, and where margin pools are migrating as product specifications become more application-specific.
Automotive Vacuum Pump Market
Market Structure and Core Operational Challenges
The market’s scale and growth profile mask a moderately concentrated competitive environment. The top three players collectively command roughly 38 percent of global revenue, while the top five account for just under half, leaving meaningful room for regional specialists, Tier 2 suppliers, and well-capitalized aftermarket brands to compete on coverage, service speed, and application-specific engineering. This fragmentation is particularly visible across powertrain types and vehicle classes, where mechanical circulation pumps still dominate volume but electric and vacuum-assisted variants are expanding their share in hybrid, EV-adjacent, and specialized commercial applications. The structural tension is that growth is not evenly distributed; it is concentrated in configurations that demand higher reliability, tighter integration with electronic control units, and more rigorous validation protocols.
Three challenges are currently shaping how manufacturers, distributors, and service networks operate in this space.
- Testing and quality assurance intensity is rising. Modern water pumps, particularly those built with premium alloy materials for high-temperature engine environments, now require 100 percent functional and leakage testing to satisfy OEM and aftermarket safety expectations. This standard elevates fixed costs and compresses the economics of low-mix, high-volume production unless offset by automation, process control, and yield optimization.
- Certification and installer competency requirements are tightening. Updated qualification pathways for personnel handling cooling system repairs and replacements are reshaping labor readiness in the service channel. As safety standards evolve, professional installers increasingly need refreshed certifications, which affects turnaround times, warranty exposure, and the practical adoption of new pump variants in the field.
- Thermal management complexity is fragmenting demand. Vehicles no longer rely on a single cooling loop with a single pump duty cycle. Hybrid and electric architectures require coolant flow control that responds to engine load, battery temperature, and power electronics needs, often with speed variation and ECU activation. This shifts purchasing behavior from generic replacement toward application-matched components and elevates the importance of diagnostic compatibility.
The commercial implication is straightforward: competitive advantage is increasingly defined by the ability to deliver validated performance at scale, support evolving service certifications, and align product portfolios with the thermal architectures that dominate new vehicle production and high-value replacement segments.
Key Demand Drivers Reshaping the Segment
Several interlocking forces are accelerating change in the automotive water pump market. None of these drivers operates in isolation; together, they are redefining both the technical specification of pumps and the economic structure of the supply base.
Technology Innovation and Thermal Integration
The most decisive technological shift is the migration from purely mechanical circulation toward electronically controlled and application-specific pumping solutions. In legacy internal combustion platforms, water pumps remain fundamental to engine cooling, but their design tolerances, sealing architectures, and bearing durability are increasingly judged against higher operating temperatures and longer service intervals. In electrified and hybrid applications, pumps must coordinate with control units to modulate flow, reduce parasitic load, and optimize thermal management across multiple subsystems. This creates a dual opportunity set: suppliers that can offer cost-effective standalone repair variants for the aftermarket while also delivering integrated, control-ready hardware for OEM thermal loops are positioned to capture demand across the vehicle lifecycle. Recent product visibility at industry exhibitions, including augmented-reality demonstrations of water pump innovations, suggests that leading suppliers are investing in visualization, training, and integration messaging to help customers understand how next-generation pumps function within complex cooling circuits.
Water Pumps Market
Regulatory and Standards Pressure
Policy and standardization activity is raising the bar for both production and service. On the manufacturing side, the expectation that automotive water pumps undergo complete leakage and functional testing is no longer an optional quality flourish; it is a baseline requirement for OEM and aftermarket acceptance. On the service side, evolving safety qualifications are changing who can handle cooling system repairs and what credentials are required, which indirectly affects the competitiveness of aftermarket suppliers that depend on broad installer adoption. At the same time, material expectations are shifting: premium alloy constructions are increasingly tied to durability assurance in high-temperature environments, which raises performance credibility but also pressures cost structures. The net effect is a market where compliance and validation are becoming strategic differentiators rather than administrative overhead.
Demand-Side Shifts Across Vehicle segments
Vehicle mix is changing the shape of demand. Passenger cars continue to represent the largest application pool, but the composition of that demand is being reshaped by hybrid penetration, extended maintenance cycles, and higher expectations for cooling reliability across a wider range of operating conditions. Commercial vehicle applications remain significant, and their cooling requirements are intensifying as heavy-duty platforms adopt more sophisticated engine families and operate under demanding duty cycles. Off-highway vehicles constitute a smaller but technically demanding niche, where robustness and application-specific fitment often outweigh pure price competition. Across these segments, the strongest growth is not simply in unit volume but in specification complexity: customers increasingly want components that can be installed with confidence, tested to recognized standards, and matched to the thermal load characteristics of the target vehicle.
Supply Chain and Cost Structure Reconfiguration
Materials, testing throughput, and geographic manufacturing footprints are recalibrating cost dynamics. The emphasis on premium alloys and full-functional testing increases the importance of supplier process capability and yield discipline. At the same time, the broader component ecosystem is adapting to higher content per vehicle in thermal management, which can support pricing power for suppliers that bring validated performance and application breadth. Geography also plays a role: different regions reflect distinct vehicle production patterns, service channel maturity, and regulatory expectations, meaning that suppliers with flexible manufacturing and strong regional coverage can better absorb localized cost shocks and respond to application-specific demand.
Competitive Landscape and Leading Strategies
The competitive field combines established global suppliers, regional specialists, and aftermarket-focused manufacturers, each pursuing a distinct route to relevance. The strategic puzzle is not who is largest in absolute terms, but who is best positioned to convert technical change into defensible share.
Global OEM-oriented suppliers such as Aisin and Continental are leaning into thermal management breadth and manufacturing credibility. Aisin’s position as a leading aluminum die-cast engine cooling water pump supplier to Japanese manufacturers, with expanding reach into European and American production, reflects the value of scale, casting expertise, and long-standing OEM relationships. Its recent demonstration of augmented-reality product innovations at a major industry event underscores a broader playbook: using visible technology demonstrations to signal engineering depth and to educate partners on new pump behaviors in electrified and hybrid cooling loops. Continental’s focus on standalone water pumps and kits for thermal management, including cost-effective variants without control units, highlights a complementary strategy: serving the repair and replacement market with practical, lower-integration options while still participating in higher-specification thermal management solutions.
In the aftermarket and engineered replacement space, brands such as Gates, Carter, and SKF are competing on performance assurance, coverage, and testing credibility. Gates emphasizes premium alloy automotive water pumps for late-model, hybrid, and vintage vehicles, paired with 100 percent functional and leakage testing, a positioning that directly addresses the rising quality expectations discussed earlier. Carter positions engineered water pumps for engine cooling with OEM-level performance and broad vehicle coverage, appealing to customers who want dependable replacement without sacrificing fitment confidence. SKF’s emphasis on precision pumps and high reliability for engine cooling reinforces the broader theme that durability and fit are increasingly valuable in a market where warranty exposure and installer trust matter.
Heavy-duty and commercial vehicle specialists illustrate a different competitive angle. US Motor Works, for example, maintains a professional-series heavy-duty water pump lineup covering platforms such as PACCAR and Detroit Diesel applications, supported by ISO 9001:2015 certified manufacturing. Its recent catalog updates and new part numbers for specific commercial engine families demonstrate how application-specific coverage and timely part expansion can defend share in commercial channels where downtime costs are high and specification accuracy is non-negotiable. Setco Automotive, based in India, has been expanding its water pump offerings within a broader thermal management and clutch component portfolio targeting passenger cars and light commercial vehicles, an example of how regional manufacturers can scale by aligning component portfolios with local vehicle mix and growing service demand.
Electric and thermal-management-focused entrants are also shaping the field. VALEO’s integration of electric and mechanical water pumps into vehicle cooling systems for passenger and commercial vehicles reflects the broader shift toward electrified thermal architectures. Bosch’s portfolio of water pumps, including switchable and control-unit variants for modern engine systems with expanded aftermarket part numbers, illustrates how established technology suppliers can bridge OEM content and aftermarket availability. Padmini VNA Mechatronics has been developing electric water pumps for EV and passenger vehicle thermal management, working with Indian OEMs such as Mahindra and Tata, which shows how regional suppliers can enter higher-value thermal content through partnerships and application-specific electrification support.
Taken together, these positions reveal three prevailing strategic orientations. First, some leaders are consolidating advantage through OEM content, casting and precision manufacturing, and thermal integration messaging. Second, others are differentiating through testing credibility, alloy and durability claims, and broad aftermarket coverage. Third, a third group is pursuing application-specific expansion in heavy-duty, commercial, or EV-adjacent segments where specification accuracy and regional vehicle mix create defensible niches. The likely trajectory over the next several years is continued differentiation rather than wholesale consolidation, because the value pool is splitting across high-specification OEM content, service-friendly repair kits, and specialized heavy-duty or electrified thermal applications.
Forward-Looking Trends and What They Mean for Commercial Strategy
Looking ahead three to five years, several trends are likely to define how the market matures and where commercial opportunities concentrate.
Trend One: Electronic Control and Thermal Management Will Become the Primary Margin Driver
As cooling loops grow more complex, the economic center of gravity will shift toward pumps and related hardware that integrate effectively with electronic control, support variable flow, and reduce thermal management load. This does not mean mechanical pumps will disappear; it means the highest-value work will increasingly involve coordination with control logic, coolant flow optimization, and application-specific validation. Suppliers that can offer both control-integrated solutions for new platforms and accessible repair options for the aftermarket will be better placed to capture value across the vehicle lifecycle. The commercial opportunity lies in packaging hardware with the technical support, diagnostics compatibility, and installer education that reduce friction in adoption.
Trend Two: Quality Assurance and Certification Will Separate Competitors
The expectations around 100 percent functional and leakage testing, premium material durability, and installer certification are not temporary frictions; they are becoming structural entry conditions. Companies that invest in testing throughput, process control, and clear quality communication will be able to command stronger positioning with OEMs and demanding aftermarket buyers. Conversely, suppliers that cannot demonstrate consistent validation or support the evolving competency requirements of the service channel will face growing disadvantages in warranty exposure, brand trust, and repeat procurement. For commercial strategy, this creates an opportunity to treat quality systems and certification readiness as market-facing assets rather than internal compliance tasks.
Trend Three: Regional Vehicle Mix Will Drive Asymmetric Growth Paths
Growth will not be uniform across regions because vehicle production, electrification pace, and service channel maturity differ. Asia Pacific’s scale in vehicle production and expanding local OEM ecosystems make it a central arena for both content and aftermarket development. North America and Europe will continue to reward suppliers that can combine broad coverage with strong application fit and service readiness, especially as hybrid and complex cooling architectures become more common in faster-turning replacement cycles. Latin America and the Middle East and Africa will remain important but likely more price-sensitive and infrastructure-dependent, where coverage, availability, and installer support can be as influential as technical differentiation. The strategic takeaway is that portfolios, manufacturing flexibility, and service networks must be calibrated to regional vehicle mixes rather than treated as homogeneous global demand.
These trends carry risks. Electrification timelines can shift, which changes the pace at which electric and hybrid thermal content scales. Testing and certification requirements may evolve further, raising compliance costs for suppliers that are slow to adapt. Material and manufacturing cost pressures can compress margins if yield and automation do not keep pace. And in the aftermarket, the success of cost-effective standalone repair variants depends on installer acceptance and diagnostic compatibility, which can be slower to develop than OEM adoption. Companies that monitor these signals closely will be better positioned to time portfolio investments and avoid overcommitting to a single trajectory.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align product architecture with the dual reality of rising thermal complexity and persistent aftermarket demand for reliable, installable replacements. That means investing in testing capability, process control, and alloy or sealing architectures that support durability claims, while also building a portfolio that spans control-integrated hardware for OEM loops and cost-effective variants for repair markets. Equally important is application coverage: deep fitment support for high-value commercial engine families, hybrid platforms, and passenger-car segments where replacement frequency and warranty sensitivity justify stronger engineering and service content.
For investors, the most relevant question is where margin pools are expanding as the market shifts from commodity replacement toward validated performance and thermal integration. Opportunities are likely to be strongest in suppliers that combine application breadth with credible quality systems, in regional players that can scale with local OEM and service demand, and in companies that can bridge electric and mechanical cooling requirements without over-concentration in a single architecture. Due diligence should pay close attention to testing infrastructure, certification readiness, coverage depth in commercial and hybrid applications, and the ability to support installer education and service adoption.
PW Consulting Automotive & Machinery Research Center
For procurement and fleet service organizations, the practical focus should be on reducing installation risk and warranty exposure while maintaining coverage across evolving vehicle populations. That argues for sourcing strategies that prioritize validated performance, clear documentation, and compatibility with existing service competencies, especially as certification expectations for cooling system repairs continue to tighten. In this environment, the value of detailed segment-level intelligence increases: knowing which applications are growing fastest, which specifications are becoming standard, and where testing or certification requirements are changing can materially improve sourcing decisions and inventory planning.
Detailed segmentation data, regional breakouts, application-level revenue estimates, and company-specific competitive benchmarks can sharpen these decisions further. For teams that need granular visibility into market splits, growth dispersion across vehicle types, and the strategic positioning of individual suppliers, the full research report provides the additional detail required to translate these trends into procurement roadmaps, portfolio priorities, and investment theses.
For detailed analysis of this topic, please visit the official page: Automotive Water Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Embolization Particle Market: Why 9.8% CAGR and the Oncology Shift Redefine Growth to 2032
By pmarketresearch, 2026-09-21
The Embolization Particle Market: Strategic Trends and Commercial Opportunities Through 2032
The embolization particle market has entered a phase of sustained expansion, transitioning from a niche interventional toolkit component to a core growth vector within the broader medical device economy. Between 2020 and 2025, global revenue climbed from approximately 1.83 billion USD to 2.88 billion USD, reflecting consistent year-over-year gains driven by procedural volume growth, product refinement, and expanding clinical indications. The trajectory is expected to continue through 2032, with the market projected to reach roughly 5.51 billion USD. This growth path translates to a compound annual growth rate of 9.8 percent across the 2026–2032 forecast window. Such momentum is not accidental; it reflects converging forces in oncology procedural adoption, interventional radiology workflow optimization, and gradual geographic penetration beyond mature markets. For decision makers evaluating capital allocation, product strategy, or procurement roadmaps, the market now rewards those who understand where innovation is compounding, which segments are maturing, and where regulatory and reimbursement dynamics are shifting the competitive edge.
Behind the headline numbers lies a market with notable structural complexity. Revenue distribution is not uniform across procedures or geographies. Oncology applications command the largest share of demand, supported by the increasing use of embolotherapy as a bridge to surgery, a primary treatment in unresectable cases, and a complementary modality in combination regimens. Uterine fibroid embolization and peripheral vascular disease applications continue to anchor steady procedural volumes, while newer indications remain in earlier stages of clinical and commercial validation. Regionally, established markets with mature interventional infrastructure and favorable reimbursement pathways account for the largest revenue pools, while faster-growing regions are expanding capacity through training programs, device localization, and increasing procedural throughput. The overall market concentration also signals that scale, clinical evidence, and regulatory execution remain decisive advantages for leading players, even as specialized entrants find room to compete in differentiated niches.
Key Structural Challenges and Inflection Points
Despite strong growth momentum, the market faces several challenges that can reshape competitive advantage over the next few years. First, clinical evidence requirements are intensifying. Purchasing committees and hospital formulary teams increasingly expect durable outcomes data, not just procedural feasibility. This shifts the basis of competition from device availability alone toward therapeutic performance, reproducibility, and post-market evidence accumulation. Manufacturers that can generate and communicate robust real-world outcomes are better positioned to defend pricing and expand share, while those relying on generic claims face growing scrutiny.
Second, regulatory and reimbursement alignment remains uneven across regions. A product that secures clearance or approval in one jurisdiction may still encounter prolonged adoption timelines elsewhere if reimbursement coding, coverage policy, or procurement rules do not keep pace. The gap between regulatory authorization and economic access can weaken commercial velocity, particularly for products entering smaller or cost-sensitive markets. For this reason, the most effective product strategies now integrate reimbursement planning early, rather than treating it as a downstream activity.
Third, the industry is seeing a shift in supply chain expectations around sterilization, biocompatibility, and consistency. Embolization particles must meet rigorous standards for safe delivery, predictable behavior, and reliable manufacturing quality. Because these products are used in high-stakes vascular procedures, even small inconsistencies can affect procedural confidence and hospital adoption. This elevates the importance of process control, documentation discipline, and regulatory readiness across the manufacturing footprint. Companies that treat these as strategic capabilities rather than operational overhead gain resilience in a market where trust is a core purchasing factor.
A further inflection point lies in the expanding role of embolotherapy in combination treatment pathways. As interventional and oncology teams coordinate care more closely, embolization particles are increasingly evaluated not only as standalone embolic tools but as components within broader treatment strategies. This creates both opportunity and complexity: product selection becomes more procedure- and patient-specific, and competitive differentiation increasingly depends on how well a device supports clinical workflow, imaging compatibility, and procedural flexibility.
Key Growth Drivers Reshaping the Market
Technology Innovation and Product Differentiation
Technology development continues to be one of the most visible drivers of market change. Embolization particles are evolving along several directions at once, including material composition, size distribution precision, delivery characteristics, and functional added value. Spherical embolic microspheres have gained prominence because their consistency can support more predictable occlusion and procedural control compared with irregular particle formats. At the same time, non-spherical polyvinyl alcohol-based options remain relevant where specific embolic behaviors are desired, particularly in arteriovenous malformations and certain hypervascular tumor applications. This diversity of product architecture means the market is not converging on a single format; instead, it is becoming more application-defined.
A second layer of innovation lies in drug-eluting and functionalized platforms. These systems are designed to combine local embolic effect with sustained therapeutic delivery, broadening their relevance in oncology and other targeted indications. Their adoption depends not only on device performance but also on the availability of supporting clinical evidence and procedural protocols. As clinicians gain more experience with these platforms, products that demonstrate reliable delivery, manageable handling, and consistent outcomes are likely to earn stronger preference in complex cases.
Worldwide Intracranial Embolization Coil Market
The third technology trend is the continuous refinement of resorbable and hydrogel-based materials. Fast-resorbable gelatin-based hydrophilic microspheres, for example, reflect an interest in temporary embolic effects for specific procedures such as musculoskeletal pain embolization. Such products illustrate a broader move toward matching material behavior to clinical intent rather than applying one embolic solution across all use cases. For manufacturers, this means product roadmaps increasingly need to balance material science, clinical use cases, and procedural ergonomics.
Policy and Regulatory Dynamics
Regulatory developments are acting as both gatekeepers and enablers. Approvals and clearances can unlock large demand pools quickly when they address high-impact indications. For example, recent authorization activity around Y-90 resin microspheres for unresectable hepatocellular carcinoma has highlighted the commercial importance of strong trial-supported indications in oncology. Similarly, 510(k) clearances for polyvinyl alcohol embolization microspheres used in arteriovenous malformations and hypervascular tumors demonstrate that incremental regulatory progress in conventional embolic categories still matters, particularly when it reinforces procedural versatility and hospital purchasing confidence.
At the same time, compliance expectations around sterilization, packaging, and labeling are increasingly scrutinized across jurisdictions. Products that are packaged dry and designed to meet recognized sterilization standards benefit from manufacturing predictability and regulatory clarity. This may appear technical, but it matters commercially because regulators, procurement teams, and hospital quality departments all rely on consistent documentation when evaluating suppliers for long-term use. In practice, regulatory readiness is becoming a differentiator that affects speed to market, cross-border expansion, and institutional trust.
Reimbursement and market access policies further shape adoption. Even when a device is clinically appropriate, hospitals and interventional centers move faster when reimbursement pathways are clear and aligned with the product’s intended use. Support resources tied to specific product applications can help shorten education and implementation cycles, especially for centers scaling up embolization procedures. As a result, companies that integrate reimbursement support, clinical education, and procedural training into their commercial model tend to achieve more dependable uptake than those that rely on product features alone.
Demand-Side Shifts in Clinical and Institutional Behavior
Demand is being reshaped by changes in how hospitals and procedural teams think about intervention. Interventional radiology and endovascular practices are increasingly focused on minimizing procedural variability, improving turnover, and maintaining consistent outcomes across operators. In that environment, products that provide predictable handling and repeatable performance become more valuable. The emphasis is moving from availability toward reliability and fit-for-purpose performance in specific procedures.
Procurement behavior is also evolving. Hospitals are paying closer attention to total procedural cost, not just device unit price. This includes factors such as preparation time, compatibility with existing delivery systems, waste reduction, and the breadth of procedures a product can support. Where a single product family can serve multiple use cases without compromising performance, it can simplify inventory management and reduce training burden. These operational considerations increasingly influence purchasing decisions alongside clinical factors.
Oncology demand remains a dominant driver, but it is changing in character. Embolization particles are being incorporated into more nuanced treatment pathways, including scenarios where local control is essential and where patient eligibility for surgery or systemic therapy is limited. That shift supports sustained growth in oncology volumes, but it also raises expectations for evidence, safety, and procedural integration. Similarly, uterine fibroid embolization and peripheral vascular disease applications continue to benefit from growing recognition of minimally invasive options, though growth in those areas depends on local clinical adoption patterns and reimbursement conditions.
Supply Chain and Cost Structure Pressures
Cost structure and supply chain resilience are increasingly important as the market expands. Manufacturing consistency, raw material availability, and sterilization logistics directly affect product reliability and commercial continuity. In a market where clinical trust depends on uniformity and quality, supply disruptions can have outsized consequences. This has raised interest in supply models that reduce risk through stable production processes, clear documentation, and well-managed distribution pathways.
Pricing dynamics are also shifting. In mature markets, hospitals are more likely to challenge recurring device spend, especially when multiple products appear clinically similar. In response, manufacturers can defend positions through clinical differentiation, service quality, and procedural support rather than broad price competition. In faster-growing regions, the pricing conversation may be more about access and scalability than about marginal cost reduction. Companies that manage both ends of this spectrum effectively are better positioned to capture regional growth without compromising margin integrity.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Key Players
The competitive field is anchored by a group of established manufacturers with strong product portfolios, regulatory assets, and procedural credibility. These companies compete on more than product features; they compete on evidence base, indication coverage, delivery system compatibility, and commercial support. Their strategies tend to emphasize one or more of the following: breadth across embolic formats, depth in a specialized indication, or capability in drug-eluting and functionalized platforms.
Merit Medical Systems, Inc. maintains a diversified embolization particle portfolio spanning irregularly shaped non-resorbable polyvinyl alcohol particles, sodium acrylate alcohol copolymer microspheres, spherical embolic microspheres positioned as a market leader in that category, and resorbable porcine gelatin for hypervascular tumors and bleeding control. This breadth allows the company to serve a wide procedural range, from arteriovenous malformations to hypervascular tumors, with multiple material options. Their profile suggests a strategy built on format flexibility and cross-application coverage, which can be attractive to centers seeking to standardize on fewer suppliers while still matching products to specific clinical scenarios.
Boston Scientific Corporation competes with a portfolio that includes polyvinyl alcohol embolization particles, hydrogel-based microspheres with Polyzene-F, and Y-90 resin microspheres for radioembolization. This combination supports both conventional embolic applications and specialized oncology radioembolization use cases. A notable advantage lies in combining procedural product lines with reimbursement-related educational resources that can support adoption in peripheral hepatic vascular tumor and uterine fibroid applications. For competitors and customers alike, this illustrates how commercial execution can hinge on pairing device capability with access support and procedural education.
Terumo Corporation emphasizes microspheres and drug-eluting platforms, with offerings that include PEG drug-eluting microspheres and hydrogel-based microspheres cleared in certain regions for hypervascular tumors and uterine fibroids. The strategic logic here is clear: by covering both standard embolic microspheres and drug-eluting options, the company can position for current procedural demand while participating in higher-complexity applications. In markets where clinicians are expanding indications and refining treatment pathways, such product alignment can translate into stronger institutional relationships and repeat usage.
Sirtex Medical Limited focuses strongly on radioembolization, particularly with Y-90 resin microspheres used in unresectable hepatocellular carcinoma. The company’s recent regulatory milestones illustrate the commercial power of indication-specific leadership. A recent FDA approval for unresectable HCC, supported by trial results showing high local tumor control and durable response duration, reinforces the value of evidence-led positioning in oncology. Alongside EU medical device regulation certification for delivery systems, this shows a strategy centered on regulatory and clinical credibility in a high-value therapeutic niche rather than broad product spread.
BTG plc, now integrated with the Boston Scientific portfolio, contributes legacy relevance through sulphonate-modified hydrogel microspheres. The broader trajectory here suggests that portfolio consolidation can strengthen commercialization while preserving specialized technology lines. Integration can streamline distribution, expand customer access, and reinforce clinical messaging, though it also requires careful management of brand continuity and procedural familiarity.
NextBioMedical Co., Ltd. represents a newer competitive presence with fast-resorbable gelatin-based hydrophilic microspheres. Recent Health Canada approval for musculoskeletal pain embolization shows how targeted regulatory success can open commercial entry in specific applications. For smaller or regionally focused players, the strategic play is often to compete where a well-defined clinical niche, clear regulatory pathway, and strong procedural alignment can outweigh the advantages of larger global portfolios.
Market Structure Evolution: Consolidation, Fragmentation, and New Entrants
The market is simultaneously experiencing consolidation benefits and niche fragmentation. Larger portfolios and integrated commercial models can reduce complexity for hospital buyers and improve access to broader procedural support. That favors incumbents with scale and established relationships. At the same time, fragmentation persists because embolization is not a single-use category with one optimal solution. Different applications, anatomical targets, and procedural preferences sustain demand for multiple embolic formats and material types. This creates openings for specialized entrants that can solve a specific clinical problem exceptionally well.
PW Consulting
New entrants are most likely to succeed when they pursue disciplined differentiation rather than broad me-too coverage. The recent approvals and clearances in both conventional PVA microspheres and Y-90 resin microspheres show that incremental innovation can still unlock commercial momentum if it addresses an unmet procedural need or strengthens evidence in a valuable indication. For the overall market, this means competitive intensity will likely remain high, but the winners will be those who combine product performance with regulatory clarity, reimbursement readiness, and credible procedural support.
Forward-Looking Trends and Commercial Implications (2026–2032)
Trend 1: Broader Oncology Integration and Evidence-Led Adoption
Oncology applications are expected to remain the largest demand anchor, but their commercial character will continue to shift. As embolotherapy becomes more embedded in combination treatment pathways, products will be evaluated more closely for local control capability, procedural compatibility, and durability of outcome. This trend favors companies that can support clinicians with evidence, training, and procedural guidance, not just device supply. For investors and manufacturers, it means that oncology growth will increasingly reward those who can translate trial strength and real-world performance into confident purchasing decisions. A risk here is that adoption may advance unevenly across regions if evidence expectations or reimbursement alignment lag.
Trend 2: Expanded Indications in Interventional Pain and Peripheral Applications
Beyond oncology, growth is likely to come from incremental indication expansion in areas such as uterine fibroid embolization, peripheral vascular disease, and musculoskeletal pain embolization. These applications can broaden addressable volume without requiring a complete overhaul of procedural infrastructure. The commercial opportunity lies in product-line extensions and application-specific positioning that match material behavior to clinical intent. For companies, the key is to avoid overextending into indications where clinical evidence or reimbursement support is premature. A realistic expansion strategy should prioritize indications with clear procedural fit and existing institutional demand. The uncertainty is that some newer applications may develop more slowly than anticipated if clinical adoption or payment pathways remain limited.
Trend 3: Regional Expansion with Increasingly Localized Competition
Revenue growth will continue to be supported by regional expansion, especially in markets where interventional capacity is increasing and procedural training is strengthening. However, the pattern of growth is expected to become more localized. As regional players secure approvals, build manufacturing and distribution capability, and tailor commercial support to local procurement realities, competition in emerging markets may intensify beyond the global incumbents. This suggests a future where global portfolio strength and local execution both matter. Manufacturers that can adapt reimbursement engagement, education, and supply strategy to regional conditions will have an advantage. The principal risk is that regional adoption curves may be slower or more policy-dependent than top-line growth projections imply, particularly where purchasing systems prioritize cost containment.
Commercial Opportunity Summary
- Products that align material behavior with clearly defined clinical use cases are likely to gain preference in complex or high-stakes procedures.
- Evidence generation and procedural education will increasingly influence share gains, especially in oncology.
- Reimbursement support and market access readiness will shape commercial velocity as much as regulatory clearance.
- Regional expansion will favor players who can combine global product credibility with localized commercial execution.
- Portfolio breadth can be valuable, but differentiation by application is becoming more important than undifferentiated coverage.
Strategic Actions for Decision Makers
For Manufacturers and Product Leaders
Manufacturers should prioritize product strategy that connects material performance to procedural outcomes. Rather than expanding purely for breadth, companies should evaluate which indications offer the strongest combination of clinical demand, reimbursement feasibility, and differentiation potential. Investment in evidence generation, sterilization and quality documentation, and procedural training can strengthen competitive positions in ways that last longer than short-term promotional activity. For portfolios already spanning multiple embolic formats, the opportunity is to make each product’s clinical rationale explicit and defensible. For newer or narrower portfolios, the opportunity is to win in a specific application with clear regulatory and reimbursement alignment.
For Investors and Corporate Development Teams
Investors should assess both market momentum and competitive defensibility. The projected trajectory suggests continued value creation, but share will likely accrue to businesses that can sustain regulatory confidence, clinical credibility, and commercial support in high-value applications. M&A and partnership opportunities may emerge around specialized technology lines, regional access capabilities, or complementary product formats. Due diligence should focus on indication-level adoption dynamics, evidence readiness, supply resilience, and the extent to which a company’s strategy relies on broad coverage versus focused differentiation. Valuation scenarios should also account for the possibility that regional growth and reimbursement timelines are more variable than aggregate market growth implies.
For Procurement and Clinical Program Leaders
Procurement and clinical leaders should evaluate embolization products through a total-procedure lens. This includes not only unit cost but also consistency of performance, handling characteristics, compatibility with existing delivery workflows, and the breadth of procedures a product can reliably support. Supplier selection should weigh clinical evidence, regulatory status, sterilization and quality documentation, and the availability of procedural support resources. In programs where embolization volume is growing, standardization on products that reduce variability and training burden can improve operational efficiency. At the same time, maintaining flexibility for application-specific needs may be prudent where procedural diversity is high.
Why Detailed Intelligence Matters Now
The embolization particle market is expanding, but the forces shaping that expansion differ significantly by application, region, and product format. Aggregate growth figures provide direction, yet the operational and commercial decisions that determine success depend on more granular insight: which indications are gaining procedural traction fastest, where reimbursement alignment is accelerating adoption, how regulatory milestones are changing competitive positioning, and which product formats are becoming more or less differentiated over time. Decision makers who operate with detailed segmentation data, company-level competitive mapping, and indication-specific outlooks are better equipped to time investments, prioritize portfolios, and manage procurement risk.
Expandable Microspheres Market
For those seeking a more complete view, the full research report provides deeper segmentation detail, company-level competitive profiles, regional and application-level revenue estimates, and tailored strategic scenarios. The additional depth is especially useful for teams that need to evaluate entry timing, portfolio fit, pricing strategy, or regional expansion with more precision than a market overview can support.
For detailed analysis of this topic, please visit the official page: Embolization Particle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
MRAM Market Reaches $45B by 2032: The 38.97% CAGR Trajectory Explained
By pmarketresearch, 2026-09-21
Magneto Resistive RAM (MRAM) Market: Strategic Trends and Commercial Opportunities
The global memory landscape is entering a decisive inflection point. Magnetic Resistive Random Access Memory (MRAM) has moved beyond niche experimentation to become a strategically critical non-volatile memory technology for applications demanding speed, endurance, and retention under harsh conditions. Revenue trajectories over the past half-decade tell a story of accelerating adoption: the market expanded from under one billion dollars in 2020 to approximately 4.49 billion dollars in 2025, and forward projections indicate sustained double-digit expansion through the end of the decade. The compound annual growth rate across the forecast horizon stands at roughly 38.97 percent, a pace that reflects both genuine technological maturation and broadening demand across mission-critical sectors. By 2032, market value is expected to approach 45 billion dollars, signaling a structural shift in how system architects balance performance, power, and reliability.
PW Consulting
Such growth is not merely a function of semiconductor cycle dynamics. MRAM occupies a unique position in the memory hierarchy, bridging gaps left by traditional flash, DRAM, and SRAM in specific use cases. The technology's ability to deliver non-volatility with near-SRAM speeds, combined with exceptional write endurance and temperature tolerance, has made it increasingly attractive for environments where data integrity cannot be compromised. Yet the path from rapid revenue expansion to sustained commercial dominance is neither linear nor guaranteed. Understanding the forces shaping this trajectory requires looking past headline numbers to the underlying technological, regulatory, and competitive dynamics that will determine which players capture value and which segments scale profitably.
Market Context and Structural Challenges
The current market environment reflects a technology transitioning from specialized deployment to broader architectural integration. Historically, MRAM found footholds in industrial, aerospace, and defense applications where radiation hardness, extreme temperature operation, and long-term data retention justified higher unit costs. That foundation remains intact, but the growth profile now reflects incremental penetration into adjacent markets where system designers are re-evaluating memory choices amid increasing performance and power constraints. The revenue curve's steepening over recent years indicates that design wins are compounding, manufacturing yields are improving, and integration pathways with existing semiconductor process flows are becoming more defined.
This momentum coexists with several structural challenges that will shape competitive outcomes over the next five years. First, the tension between density scaling and manufacturing complexity remains acute. MRAM fabrication relies on specialized magnetic materials, additional deposition and patterning steps, and tighter process tolerances than many conventional memory technologies. As manufacturers push toward higher-density arrays, maintaining uniform magnetic tunnel junction characteristics across large wafers becomes increasingly difficult, creating trade-offs between capacity, yield, and cost that cannot be solved through process optimization alone.
Second, qualification and reliability requirements continue to act as both a market enabler and a barrier. High-reliability applications demand documented performance under extreme thermal cycling, long-term retention guarantees, and adherence to automotive-grade qualification frameworks. These standards protect end customers but extend development timelines and raise the cost of market entry. The result is a market where incumbents with established qualification portfolios and application-specific reference designs hold meaningful advantages, while new entrants must navigate a multi-year pathway to prove suitability for safety-critical deployments.
Third, the market's current structure reflects a moderately consolidated landscape. A relatively small group of firms accounts for a substantial share of revenue, while the remainder is distributed across specialized players and emerging participants. This concentration creates both stability and friction: established players benefit from ongoing design wins and customer relationships, but the same dynamic can slow the diffusion of disruptive process innovations if incumbent architectures are optimized for existing product families rather than next-generation scaling pathways.
Key Drivers Shaping the Market Trajectory
The acceleration observed in recent years is not the product of a single catalyst. It emerges from the convergence of technological breakthroughs, evolving demand-side requirements, and shifting supply-side economics that together expand the addressable opportunity for MRAM.
Technical Innovation and Process Maturation form the foundation of current growth. Advances in magnetic tunnel junction design, particularly the transition toward perpendicular MTJ configurations and improvements in spin-transfer torque efficiency, have increased the feasibility of higher-density arrays while preserving the retention and endurance characteristics that define MRAM's value proposition. Incremental improvements in integration compatibility with standard CMOS flows reduce the friction of adoption for system manufacturers who cannot absorb highly customized fabrication requirements. Recent technical milestones illustrate this trajectory: one leading manufacturer achieved a Phase One milestone under a U.S. government-funded program by scaling magnetic cell geometry to enable higher-density space-grade MRAM, demonstrating that process innovation is increasingly oriented toward expanding density envelopes without abandoning reliability requirements.
Policy and Regulatory Environments are reshaping demand patterns in ways that directly favor non-volatile memory technologies with proven reliability profiles. National security priorities, industrial base resilience initiatives, and export control frameworks have heightened interest in domestic or allied supply chains for specialized semiconductor technologies. MRAM's relevance to defense, aerospace, and mission-critical infrastructure aligns with policy directions that emphasize secure, high-reliability components. This is visible in recent contract activity: a major MRAM developer secured a substantial subcontract with a U.S. prime contractor to support Toggle MRAM process technology and engineering services for Defense Industrial Base customers, reflecting how national security initiatives are translating into concrete demand signals for specialized memory capabilities.
Demand-Side Shifts in Application Architecture are expanding the contexts in which MRAM competes. In automotive systems, increasing electrification, advanced driver-assistance functionality, and connectivity requirements are pushing designers toward memory solutions that can operate reliably across wide temperature ranges while maintaining fast read/write performance. Validation activity underscores this momentum: MRAM products have been validated across multiple FPGA families for high-reliability configuration memory in industrial, aerospace, military, and automotive contexts, indicating that MRAM is being positioned not only as a standalone memory component but as an enabling element within broader system architectures. In aerospace and defense, the combination of radiation tolerance, extreme environment performance, and long data retention continues to drive adoption where alternative technologies struggle to meet qualification thresholds.
Supply Chain and Cost Structure Evolution remains a critical shaping force. The specialized materials and additional fabrication steps inherent to MRAM create cost structures that differ from mainstream memory categories. At lower volumes, these costs can limit price competitiveness in cost-sensitive markets. However, as process recipes mature, design wins accumulate, and manufacturing scale improves, the economic balance shifts. The challenge for manufacturers is to manage the intersection of yield, density, and qualification requirements in a way that preserves margin while expanding addressable volume. For customers, the decision increasingly comes down to total cost of ownership over the product lifecycle: MRAM's endurance, reduced risk of data loss, and suitability for harsh environments can offset higher upfront component costs in applications where failure is expensive or dangerous.
Static Random Access Memory (SRAM) Market
Competitive Landscape and Strategic Positioning
The MRAM market's competitive architecture reflects a blend of specialized incumbents, application-focused players, and selective government-driven demand that rewards proven reliability. Rather than competing solely on density or price, leading firms have built differentiation around process expertise, qualification track records, and deep integration with specific end-market requirements.
Everspin Technologies has established a prominent position as a developer and manufacturer of both discrete and embedded MRAM products, with a portfolio spanning Toggle MRAM, STT-MRAM, and advanced perpendicular MTJ-based variants. Its strategic emphasis on industrial IoT, data centers, automotive, aerospace, and mission-critical applications reflects a deliberate focus on markets where reliability and endurance justify the technology's adoption. The company's recent validation of its MRAM across FPGA families for high-reliability configuration memory, alongside a significant subcontract supporting U.S. Defense Industrial Base customers, illustrates how incumbents translate technical capability into commercial and programmatic momentum. The combination of design-in relationships, qualification documentation, and alignment with defense and industrial priorities gives such players a defensible position in segments where certification and trust matter as much as raw performance.
NVE Corporation occupies a more specialized niche, developing and licensing MRAM technology with emphasis on anti-tamper applications and spintronics-based solutions for low-bit-density, tamper-prevention use cases. This positioning reflects a different competitive logic: rather than competing in high-volume mainstream memory, the company focuses on specialized security-oriented applications where its technology's characteristics align with narrow but valuable requirements. In a market where many players chase density and volume, specialized security applications represent a reminder that differentiation can arise from application specificity as much as from process scale.
Avalanche Technology has focused on high-density STT-MRAM with spin-programmable perpendicular MTJ technology, targeting space-grade and industrial products for aerospace and defense. Its recent achievement of a Phase One milestone in a government-funded program, scaling magnetic cell geometry for higher-density space-grade MRAM, highlights a strategy centered on expanding density capability within stringent reliability envelopes. For customers in aerospace and defense, this type of progress signals a pathway toward more capacious memory solutions that still meet the qualification and environmental demands of mission-critical deployment.
The broader competitive trajectory is likely to be shaped by three overlapping dynamics. Integration will continue as system manufacturers seek memory solutions that reduce architectural complexity, particularly where non-volatility, speed, and endurance can be combined in a single element. At the same time, differentiation will persist: the market is not uniform, and the requirements of automotive, aerospace, industrial, and enterprise applications differ enough that specialized expertise, qualification portfolios, and application-specific reference designs will remain valuable. New entry will be selective rather than broad-based, given the barriers posed by fabrication complexity, qualification timelines, and the need for customer trust in high-reliability contexts. Incumbents with established design wins and process knowledge will have an advantage, but targeted entrants addressing narrow, high-value niches may find room to build sustainable positions.
Future Trends and Commercial Implications
Looking ahead across the next three to five years, the MRAM market's evolution will be defined by how effectively the industry resolves the tension between scaling ambition and manufacturing reality, how broadly qualification frameworks expand beyond traditional high-reliability niches, and how policy and supply chain dynamics shape demand concentration.
One clear trend is the continued push toward higher-density MRAM within reliability-constrained environments. As magnetic cell geometry and MTJ stack designs advance, the feasibility of denser arrays for aerospace, defense, and industrial applications improves. The commercial implication is straightforward: customers in these segments will gain access to memory solutions with greater capacity without sacrificing the environmental and retention characteristics that drove initial adoption. This creates opportunities for system architects to consolidate memory functions, reduce component count, and simplify designs in contexts where reliability is non-negotiable. The associated risk is that density gains may lag expectations if process uniformity challenges prove harder to overcome at scale, creating uneven product ramps and potential disappointment in roadmaps that assume linear scaling.
Giant Magneto Resistive (GMR) Sensors Market
A second trend is the broadening of qualification and integration pathways beyond the most demanding defense and aerospace niches. Validation activity across FPGA ecosystems and growing attention to automotive-grade qualification indicate that MRAM is being positioned for design wins in adjacent markets where reliability requirements are significant but not necessarily at the extreme end of the spectrum. The commercial opportunity lies in capturing design-in momentum early in product lifecycles, building reference architectures, and establishing supply confidence before competitors lock in alternative memory choices. The uncertainty here is regulatory and standards-driven: qualification frameworks are rigorous by design, and any shift in requirement interpretation, testing expectations, or supply chain scrutiny can alter timing and cost for both manufacturers and end customers.
A third trend is the growing intersection of memory technology strategy with national security and supply chain resilience priorities. Demand signals tied to defense industrial base initiatives, secure component sourcing, and allied supply chain preferences are likely to remain relevant, particularly for manufacturers positioned to support government and prime-contractor programs. For commercial players, this creates opportunities to align product roadmaps with policy-relevant applications and to build relationships that extend beyond traditional commercial cycles. The risk is concentration: reliance on policy-driven demand can be rewarding but also exposes manufacturers to shifts in program funding, procurement priorities, and export control environments. Diversification across industrial, automotive, and commercial high-reliability segments remains a prudent hedge.
Strategic Considerations for Decision-Makers
For manufacturers and technology developers, the near-term priority is to manage the density-versus-yield tension with explicit roadmaps that account for qualification requirements and customer qualification timelines. Investments in process control, magnetic material optimization, and integration compatibility with standard CMOS flows will determine whether higher-density products can reach volume without eroding margins. Equally important is the development of application-specific reference designs and qualification documentation that shorten customer evaluation cycles. In markets where reliability is paramount, the ability to demonstrate tested performance under representative conditions often matters more than headline specifications. Manufacturers should also consider how to balance defense-adjacent demand with broader industrial and automotive opportunities, ensuring that roadmaps are not overly dependent on any single demand stream.
For investors, the market presents a profile of high growth potential paired with technology execution risk and qualification-driven adoption timelines. The headline growth rate and forward market size trajectory reflect genuine expansion, but returns will depend on which companies can translate technical milestones into volume production, secure recurring design wins, and maintain cost discipline as densities increase. Evaluation should focus on process maturity indicators, qualification progress in target end markets, the durability of customer relationships in high-reliability segments, and the extent to which revenue is tied to policy-sensitive programs versus commercially diversified demand. The specialized nature of MRAM means that leadership in a narrow application area can be more valuable than broad but shallow market presence.
For procurement teams and system architects, MRAM should be evaluated as part of a total cost of ownership framework rather than solely on unit price. In applications where data retention, endurance, temperature tolerance, and fast non-volatile operation reduce downstream risk, MRAM's value can outweigh higher initial component costs. Early engagement with suppliers during the design-in phase, clear alignment on qualification expectations, and review of validation evidence across relevant FPGA or system ecosystems can reduce integration risk. Procurement strategies should also account for supply continuity in high-reliability contexts, where qualification lead times and specialized manufacturing requirements make supply chain resilience a meaningful consideration.
The strategic picture is clear: MRAM is moving from a specialized memory technology to a more broadly relevant element in system architectures where reliability, endurance, and non-volatility intersect with performance requirements. The growth trajectory is strong, but the market's future shape will be determined by how effectively participants navigate manufacturing complexity, qualification rigor, and the selective but meaningful influence of policy-driven demand. Detailed segmentation data, company-level competitive positioning, and application-specific adoption pathways can sharpen these strategic choices further. For decision-makers seeking a fuller picture of market size by segment, regional dynamics, and forward scenario analysis, the complete PW Consulting market report provides the granular intelligence needed to translate high-level trends into concrete commercial action.
For detailed analysis of this topic, please visit the official page: Magneto Resistive RAM (MRAM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Quick Service Restaurant IT Market: Strategic Shifts and Commercial Opportunities in a High-Growth Landscape
The Quick Service Restaurant (QSR) IT market has evolved from a back-office support function into a central growth engine. Between 2020 and 2025, the segment expanded from a 25.94 billion valuation to approximately 39.91 billion, reflecting a compound annual growth rate of 9.0 percent through the 2026–2032 forecast horizon. By 2032, the market is projected to surpass 72.96 billion, signaling sustained momentum rather than a cyclical peak. This trajectory is not driven by uniform expansion across all players. Instead, it reflects a structural realignment where technology, operational efficiency, and consumer expectations converge to redefine how QSR brands operate, compete, and scale.
At its core, the market sits at a transition point. Legacy point-of-sale systems are giving way to cloud-native architectures, fragmented toolchains are being consolidated into integrated platforms, and data is shifting from a reporting artifact to a real-time decision utility. The growth rate itself tells a story: it is fast enough to attract serious capital and competitor attention, but nuanced enough that success depends on execution quality, not merely market timing. For executives and investors, the imperative is to understand where the value is being created, who is capturing it, and what forces will shape the next phase of expansion.
The current landscape is characterized by a relatively open competitive field. Concentration metrics indicate that the top three players account for roughly 20.0 percent of total revenue, while the top five represent approximately 25.0 percent. This suggests a market that is still diversifying rather than ossified around a few dominant incumbents. The implication is straightforward: scale advantages exist, but they are not insurmountable. Companies that can deliver differentiated functionality, reliable integration, and clear total cost of ownership are finding room to grow. The question for decision-makers is no longer whether to invest in QSR IT, but how to align investments with the operational realities of high-volume, speed-driven environments.
Market Snapshot: Scale, Trajectory, and What the Numbers Mean
Macro Growth and Structural Momentum
The market’s expansion from 2020 through 2025 was not a straight line. Growth accelerated during periods of digital adoption pressure and moderated when operational budgets tightened. The 9.0 percent compound annual growth rate projected through 2032 reflects a market that has internalized technology adoption as a baseline expectation rather than a discretionary upgrade. This pace is meaningful because it compresses planning cycles. Manufacturers, software vendors, and service providers must anticipate demand shifts faster, while operators face shorter windows to evaluate, deploy, and derive value from new systems before the next wave of innovation arrives.
Revenue composition across hardware, software, and services indicates that no single component dominates the value pool. Hardware remains a substantial portion of the market, reflecting the continued need for terminals, kiosks, and display infrastructure. Software represents a comparably large share, underscoring the shift toward licensing, analytics, and integrated management capabilities. Services, while smaller in relative terms, play a critical role in implementation, customization, and ongoing optimization. The balance among these categories matters because it signals where margin profiles, renewal dynamics, and customer retention pressures differ. Hardware deployments often anchor long-term relationships, software introduces recurring revenue and upgrade cycles, and services tie value to operational outcomes rather than transactional sales.
Fast-casual Dining Market
Application-level demand also reveals a bifurcated but balanced base. Large-scale consumers represent a significant share of market activity, reflecting the needs of multi-unit brands that prioritize standardization, centralized reporting, and cross-location scalability. Smaller consumers account for a substantial portion as well, driven by independent operators and emerging chains that seek affordable, modular solutions without sacrificing core functionality. This split is strategically important. It means the market is not a single use case waiting for a uniform solution. Instead, it demands flexible architectures that can serve enterprise standardization and small-operator agility without forcing either segment into an ill-fitting model.
Core Challenges and Inflection Points
Integration Complexity and Operational Friction
One of the most persistent challenges in the QSR IT market is integration complexity. Many operators still rely on a patchwork of systems for ordering, payments, kitchen display, inventory, labor scheduling, and analytics. The promise of a unified platform is compelling, but the reality of deployment often introduces friction: data reconciliation between legacy and new systems, workflow redesign for staff, and change management across locations with varying levels of digital maturity. The operational risk is not just technical downtime. It is degraded throughput during transition periods, inconsistent customer experiences, and uncertainty about whether new tools will actually reduce labor intensity or simply add administrative overhead.
This challenge creates a clear inflection point. Vendors that can reduce deployment risk, provide proven migration paths, and demonstrate measurable improvements in throughput and error rates are positioned to win more decisive adoption. Conversely, solutions that overpromise on seamless unification without accounting for real-world operational variability face higher resistance from operators who cannot afford prolonged disruption. For decision-makers, the practical question is how to balance ambition with execution certainty: which capabilities can be standardized immediately, which require phased rollout, and how to measure success beyond go-live dates.
Cost Pressure and Margin Discipline
Operational cost pressure is another defining constraint. Labor availability, wage dynamics, and throughput expectations continue to shape how QSR brands think about technology investments. At the same time, upstream cost dynamics can affect suppliers and ultimately influence menu pricing and margin structures. Industry commentary has highlighted that tariff exposure on imported goods could raise input costs for QSR suppliers, prompting supply-chain adaptations and, in some cases, potential price adjustments passed through to customers. These pressures do not diminish the case for technology. They sharpen it. When margins are tight, the value of technology shifts from convenience to efficiency: reducing waste, improving order accuracy, optimizing labor allocation, and enabling faster decision cycles.
The inflection here is subtle but important. Technology is increasingly evaluated not as a separate line item but as a lever within a broader cost and throughput strategy. Solutions that can tie directly to labor productivity, inventory accuracy, or order velocity are more defensible in budget conversations than abstract digital transformation narratives. For investors and operators alike, this means the most durable demand is likely to come from tools that demonstrate measurable operational impact rather than incremental feature enhancement.
Skill Gaps and Change Management
A third challenge is the human dimension of technology adoption. Even well-designed systems depend on staff proficiency, manager oversight, and consistent usage patterns. QSR environments are high-pressure, turnover-prone, and operationally intense. Systems that require extensive training, complex manual steps, or frequent troubleshooting can underperform in practice regardless of their technical sophistication. This reality places a premium on usability, role-based design, and support models that extend beyond initial installation.
The strategic implication is that vendors and operators must treat change management as part of the product experience. Deployment success increasingly depends on how well a solution fits frontline workflows, how quickly staff can reach competence, and how effectively managers can interpret system outputs without adding administrative burden. In this sense, the market is rewarding solutions that reduce cognitive load and operational ambiguity, not just those that add capability.
Key Drivers Shaping the Market
Technological Innovation and AI-Enabled Operations
Technology innovation remains the most visible driver of market growth, with artificial intelligence emerging as a central theme. AI adoption in the QSR segment is expected to accelerate, driven by needs around order accuracy, voice-based ordering, demand forecasting, and operational automation. The appeal is straightforward: in high-volume environments, small improvements in order handling and throughput compound quickly into meaningful gains in revenue protection and labor efficiency. AI voice ordering, for example, can help manage demand spikes, reduce missed or misheard orders, and free staff to focus on fulfillment and service quality. Analytics and operational intelligence can improve inventory planning, labor scheduling, and menu performance tracking, giving managers more precise inputs for day-to-day decisions.
A concrete example of this trajectory is the recent launch by Toast of a unified enterprise drive-thru platform that integrates POS, kitchen display, digital menu boards, and AI voice ordering with the aim of optimizing QSR throughput. This type of release matters because it reflects a shift from isolated tools to coordinated workflows. The strategic value is not simply the presence of AI. It is the integration of AI into a system where order capture, kitchen execution, and customer-facing display operate as one flow. For operators, this reduces handoff friction. For vendors, it raises the bar on platform coherence and real-world performance.
Demand-Side Changes and Consumer Expectations
Consumer expectations continue to reshape QSR operations. Speed, convenience, and consistency are baseline demands, but they are increasingly supplemented by expectations around personalization, mobile engagement, and frictionless payment. Digital ordering, curbside pickup, and self-service options are no longer niche offerings. They are part of the service architecture that determines perceived value and repeat behavior. As these channels expand, the IT stack must support order routing, inventory visibility, payment flexibility, and loyalty integration without creating inconsistency across channels.
This demand-side shift also influences how brands think about data. When ordering happens across multiple touchpoints, the opportunity is not just to process transactions but to connect them into a coherent view of customer behavior and operational performance. That connection enables better promotion targeting, more accurate demand signals, and tighter alignment between sales channels and kitchen capacity. The commercial implication is that QSR IT is becoming a differentiation layer, not just a transaction layer. Brands that can orchestrate channels efficiently while maintaining speed and consistency are better positioned to defend share in competitive corridors.
Supply Chain, Cost Structure, and Regulatory Context
Supply chain and cost structure dynamics are increasingly intertwined with technology decisions. Tariff-related pressures on imported goods have been noted as a factor that could increase operational costs for QSR suppliers and contribute to broader input cost challenges. While the direct impact varies by supplier and product category, the broader signal is that cost volatility is a persistent consideration. In that environment, technology investments are evaluated for their ability to offset pressure through efficiency, waste reduction, and more precise inventory and labor management.
Regulatory and industry context also contributes to the pace of change. Expert commentary from the restaurant sector indicates that AI adoption in QSR is expected to accelerate, reflecting both competitive pressure and operational necessity. At the same time, the environment is not static. Cost inputs, labor conditions, and consumer behavior all create uncertainty that makes flexibility and scalability important purchase criteria. This reinforces a broader trend: the market is rewarding solutions that are adaptable across locations and resilient to changing cost and demand conditions, rather than solutions optimized for a single idealized operating model.
Competitive Landscape and Leading Strategies
Positioning Among Core Participants
The competitive field includes a mix of platform-focused vendors, hardware specialists, and enterprise-oriented providers. Toast stands out for its all-in-one cloud-based POS and restaurant management orientation, with capabilities that span drive-thru, AI voice ordering, and analytics tailored to high-volume QSR operations. Its recent enterprise drive-thru launch highlights a strategy centered on throughput optimization and integrated order flow. Square approaches the market with a cloud-native restaurant POS built around mobile ordering, inventory management, and curbside solutions, emphasizing speed and multi-location scalability. This positions Square around flexibility and growth-oriented deployment, particularly for operators that value rapid expansion and modular functionality.
Elo Touch Solutions takes a hardware-focused angle, offering customizable QSR POS systems, kiosks, and digital menu boards that connect order processing with inventory integration. Its relevance lies in the physical interaction layer: terminals, kiosks, and displays remain essential in many QSR environments, and hardware differentiation can influence throughput, durability, and customer experience. PAR Technology Corporation operates with an enterprise hospitality orientation, bringing together POS, scheduling, and operational intelligence for multi-unit QSR brands. Its value proposition centers on unification across locations and operational oversight, which appeals to brands managing complex field operations. Oracle brings a broader hospitality and food-and-beverage footprint, with POS capabilities that include mobile order and pay, analytics, and back-office integration. Its positioning reflects the ability to serve QSR and wider hospitality needs within a more extensive technology ecosystem. NCR Voyix focuses on unified-commerce POS for restaurants, including self-checkout and payments, with an emphasis on QSR efficiency and growth. Its strategy aligns with the broader movement toward combined ordering, payment, and service flows that reduce friction at the point of interaction.
Differentiation and Strategic Themes
Across these participants, several strategic themes emerge. One is integration depth. The most compelling offerings are those that reduce the number of disconnected systems an operator must manage and make data flow more naturally between front-of-house, back-of-house, and management functions. Another is scalability. Multi-unit brands need solutions that can standardize operations without eliminating local flexibility, and they need reporting and control mechanisms that work across locations without excessive customization. A third theme is operational intelligence. Analytics and management insights are increasingly expected to be part of the platform rather than a separate add-on, because they connect technology investment to measurable performance outcomes.
Differentiation also comes from deployment and support models. In a market where integration complexity and change management are real risks, vendors that provide smoother onboarding, clearer operational fit, and reliable ongoing support can create meaningful distance from competitors with similar feature sets. This is especially true for high-volume QSR environments, where even small usability issues can affect throughput and staff adoption. The strategic lesson is that functionality alone does not determine winner status. Execution quality, integration reliability, and total cost of ownership often matter more in sustained adoption.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market structure suggests continued evolution rather than early consolidation. With top-three and top-five concentration levels still moderate, there is room for both consolidation and specialization. Larger platforms may pursue breadth by adding capabilities across ordering, payments, kitchen operations, and analytics. Smaller or niche players may pursue depth in specific workflows, hardware categories, or regional deployment models. New entrants can still gain traction by addressing underserved needs, such as particular hardware configurations, vertical-specific workflows, or more affordable entry points for smaller operators.
At the same time, the risk of fragmentation is real. If operators accumulate overlapping tools in pursuit of best-of-breed functionality, they may face higher integration costs and weaker data coherence. This creates pressure for platforms that can balance breadth with usability. The likely outcome is a competitive environment where success depends on the ability to deliver a coherent experience across the stack, while still allowing flexibility for local operational needs. For executives evaluating vendors, the key is to assess not only what a platform can do in isolation, but how well it reduces complexity across the broader system of operations.
Future Outlook: Trends and Commercial Implications
Trend One: Unified, Throughput-Oriented Platforms
Over the next three to five years, one of the clearest trends is likely to be the continued shift toward unified platforms designed around throughput and order flow. In QSR, speed and accuracy are not marginal improvements; they are core to revenue protection and customer satisfaction. Platforms that coordinate ordering, kitchen execution, display, payments, and basic analytics within a connected workflow will have a structural advantage because they reduce handoffs and operational ambiguity. The commercial opportunity here is for vendors that can prove end-to-end impact rather than isolated feature value, and for operators that can standardize high-impact workflows without over-customizing to the point of fragility.
PW Consulting
The associated risk is over-engineering. Not every location needs the same level of automation or the same integration depth. If platforms become too rigid, they may struggle with diverse store formats, varying labor models, and local market differences. The winners will likely be those that offer strong core workflows while allowing controlled adaptation at the edges.
Trend Two: AI and Operational Intelligence as Standard Capabilities
AI and operational intelligence are likely to become standard expectations rather than differentiators in every category. Voice ordering, demand forecasting, labor optimization, and anomaly detection can improve throughput and reduce costly errors when applied well. As adoption accelerates, the differentiator will shift from whether a system includes AI to how reliably it performs in live conditions and how usable its outputs are for managers and staff. The commercial implication is that vendors will need to demonstrate robustness, transparency, and practical value, while operators will need to build internal capability to act on system-generated insights.
A key uncertainty is the pace and shape of AI value realization. Adoption may outpace the ability to integrate AI outputs into daily workflows, leading to underutilization or skepticism if results are inconsistent. In that scenario, the market may reward pragmatic deployments that solve specific operational problems over broad promises of intelligence. Decision-makers should therefore treat AI as an operational tool with measurable endpoints, not as a blanket upgrade.
Trend Three: Cost-Efficiency-Led Adoption and Flexible Architectures
Cost pressure and input volatility are likely to reinforce efficiency-led adoption. Technology purchases will increasingly be justified through labor productivity, waste reduction, order accuracy, and inventory control. This trend favors flexible architectures that can be deployed in phases, scaled across locations, and aligned with operational priorities instead of requiring full transformation upfront. The commercial opportunity is for solutions that can show a clear path from installation to measurable efficiency gains, and for buyers who structure deployments around high-return workflows first.
The related risk is that cost pressure may also delay adoption if returns are unclear or if implementation disruption is perceived as too high. In that environment, vendor credibility, referenceable outcomes, and low-friction rollout become critical. The market may divided between players who can evidence value quickly and those who rely on longer, less certain transformation narratives.
Strategic Implications for Decision-Makers
For Manufacturers and Technology Providers
Focus on workflow coherence and deployment confidence. In a market where integration complexity and change management are persistent barriers, the most defensible position is a solution that fits frontline operations, supports smooth migration, and delivers measurable throughput or efficiency gains. Product roadmaps should prioritize integration depth, role-based usability, and support models that reduce post-deployment friction. Where AI is involved, emphasize reliability, clear use cases, and manager-friendly outputs rather than broad claims of intelligence. Pricing and packaging should reflect the reality that operators evaluate total cost of ownership, not just upfront capability.
Worldwide Information Technology Market
For Investors
Evaluate market positions through the lens of scale, repeatability, and operational proof. The moderate concentration structure suggests room for differentiation, but durable advantage will likely come from platforms that can standardize across locations while maintaining flexibility, and from vendors that can evidence efficiency outcomes in high-volume environments. Pay attention to recurring revenue quality, renewal dynamics, and the ability to expand within existing accounts through additional modules or locations. Also consider exposure to cost and supply-chain volatility, since margin pressure can influence both adoption timing and vendor selection. The strongest investment theses are likely to be tied to platforms that reduce operational risk and demonstrate clear payback paths.
For Procurement and Operator Decision-Makers
Prioritize solutions that align with the highest-impact operational constraints in your environment. Start with workflows where technology can directly improve speed, accuracy, labor utilization, or inventory control, and sequence rollouts to limit disruption. Evaluate vendors on integration reliability, support responsiveness, and the usability of their systems for frontline staff and managers, not just on feature count. Where possible, structure deployments to generate visible operational improvements early, because early wins build internal confidence and support broader adoption. Given the pace of change and the range of vendor strategies, timely access to detailed segmentation data, vendor comparisons, and deployment benchmarks can materially improve decision quality. Detailed research that breaks down sub-segment dynamics and tailored implementation considerations can help ensure that procurement choices match both immediate operational needs and longer-term scalability goals.
The QSR IT market is expanding at a pace that rewards focused strategy. The winners in the next phase will likely be those who treat technology as an integrated operating capability, align investments with measurable efficiency outcomes, and build for flexibility in a cost-conscious, speed-driven environment. For organizations navigating this landscape, the most valuable next step is to ground decisions in detailed, segment-specific intelligence that connects market dynamics to concrete operational choices.
For detailed analysis of this topic, please visit the official page: Quick Service Restaurant (QSR) IT Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Power Liftgate Market: Why 7.6% CAGR Reshapes Competition by 2032
By pmarketresearch, 2026-09-21
Strategic Trends & Commercial Opportunities in the Automotive Power Liftgate Market
Market Trajectory: Growth, Structure, and Inflection Points
The automotive power liftgate market has entered a sustained expansion phase, transitioning from a premium convenience feature to a mainstream closure solution across multiple vehicle segments. Between 2020 and 2025, global market revenue climbed from approximately $163.15 million to $215.0 million, reflecting a compound annual growth rate (CAGR) of 7.6% projected through 2032. By the end of the forecast window, revenue is expected to surpass $344.8 million, signaling that power liftgate adoption is no longer confined to high-end SUV or crossover trims. The growth trajectory underscores a structural shift in how automakers approach rear and tailgate closure architectures: electrification of actuation, tighter integration with body electronics, and a growing emphasis on weight reduction and packaging efficiency.
Despite the positive trajectory, the market faces several critical challenges that will shape competitive outcomes over the next three to five years. First, supply chain volatility for critical raw materials introduces cost and production risk. Rare-earth magnet supply concentration in China affects permanent-magnet motor production used in power liftgate actuators, while copper price volatility directly impacts motor winding costs in brushless DC motor-driven spindle actuators. These input cost pressures compress margins for suppliers who lack multi-source strategies or material substitution capabilities. Second, regulatory and safety expectations are tightening. Safety regulations for power liftgate systems emphasize anti-pinch protection and integrated sensors for reliable operation across temperature ranges, and EU and global vehicle safety standards drive demand for energy-efficient electric actuation compatible with 48V/12V platforms. Compliance is no longer a baseline checkbox; it is becoming a differentiator that influences OEM platform decisions. Third, the market remains moderately fragmented, with a CR3 of 24.6% and CR5 of 26.2%, indicating that scale alone does not guarantee leadership. Suppliers that win are those offering validated system-level integration, not just discrete components.
PW Consulting
Key Drivers Reshaping the Power Liftgate Market
Electrification and actuator efficiency. The shift toward electrified closure systems is a primary growth engine. Brushless DC motor designs with high torque-density and position-controlled architectures are replacing simpler DC solutions in premium and high-volume applications. These designs improve reliability, reduce noise, and enable finer control over closing speed and pinch mitigation. At the same time, the market is seeing a move toward lightweight thermoplastic and composite solutions that reduce mass relative to conventional metal architectures. For EV programs, even modest weight savings at the rear closure contribute to range and packaging objectives, making liftgate design part of a broader vehicle efficiency equation rather than an isolated convenience feature.
Automotive Power Window Motor Market
Safety regulation and functional integration. Regulatory pressure is accelerating the convergence of actuation, sensing, and body electronics. Anti-pinch protection, occupant detection, and reliable operation across temperature extremes are increasingly expected as standard capabilities. This creates a demand pull for suppliers that can deliver integrated control electronics, proximity sensing, and fail-safe motor control within a single validated module. The practical effect is a move away from decentralized, component-level sourcing toward system-level partnerships where the supplier takes greater responsibility for functional safety, diagnostics, and calibration.
Consumer expectations and commercial use cases. On the demand side, power liftgates have become a decisive purchase attribute for passenger cars, particularly in segments where cargo utility and hands-free operation matter. In commercial vehicles, the value proposition shifts toward durability, repeated cycle reliability, and integration with fleet telematics or access control. The combined effect is broader demand across both passenger cars and commercial vehicles, with passenger car applications driving volume growth and commercial applications reinforcing the need for ruggedized designs and higher duty-cycle validation.
Supply chain reconfiguration and cost structure. Cost and resilience are increasingly intertwined. Suppliers are responding to raw material exposure by diversifying magnet sourcing, optimizing winding designs, and increasing the share of applications using composite or thermoplastic structures that reduce reliance on heavier metal stampings. At the same time, regional manufacturing footprints and local content expectations are reshaping sourcing strategies. The companies best positioned to protect margins are those that combine design flexibility with disciplined procurement and the ability to offer platform-sharing architectures across multiple OEM programs.
Competitive Landscape: Differentiation, Positioning, and Evolution
The competitive environment is defined by specialists and system integrators operating at different levels of the value chain. Brose Fahrzeugteile SE & Co. KG has reinforced its system-level positioning through concepts that combine ultra-wideband positioning and radar for automatic tailgate activation and occupant detection, illustrating a move toward contactless, context-aware closure experiences. Aisin Corporation continues to emphasize actuator and control electronics optimized for body closure in Asian OEM programs, where proximity sensors and integrated control strategies support high-volume, cost-sensitive applications. Magna International Inc. is advancing lightweight thermoplastic liftgate solutions that are materially lighter than conventional steel components, directly addressing EV efficiency and packaging constraints while offering a broader system module including electric actuators, hands-free detection, and integrated ECU.
Continental AG focuses on power closure systems, actuators, and anti-pinch motor control integrated with body electronics, aligning with the regulatory and functional safety trend. Huf Hulsbeck & Fürst GmbH & Co. KG brings strength in tailgate latches, actuators, and strikers with integrated closing functions and external actuator variants for reliable operation, which is especially relevant where latch integrity and serviceability are priorities. Stabilus GmbH differentiates through electric liftgate drive systems that combine gas-spring assistance with electromechanical actuation and position control, a hybrid approach that can balance force, stroke, and packaging demands. HI-LEX Corporation contributes power liftgate actuators and related electromechanical components for vehicle tailgates, often supporting suppliers and OEMs that require component-level flexibility. Strattec Security Corporation extends into power access systems including actuators, latches, and security modules integrated with vehicle access, opening adjacency opportunities where closure and access control converge. Johnson Electric Holdings Limited offers brushless DC motor and actuator assemblies with high torque-density and position-controlled designs, reinforcing the broader industry shift toward efficient, controllable actuation.
The market is evolving along two simultaneous paths: consolidation at the system level and specialization at the component level. Larger suppliers are expanding from actuation into full closure modules that span mechanics, electronics, sensing, and software integration. At the same time, smaller entrants and component specialists remain relevant where OEMs seek cost-optimized elements, regional supply support, or alternative architectural approaches. The strategic implication is that positioning matters more than scale alone. Suppliers that can articulate a clear system architecture, demonstrate validation rigor, and reduce integration risk for OEMs are gaining disproportionate influence in platform decisions.
Forward-Looking Trends and Commercial Implications
Trend 1: From liftgate actuation to intelligent closure experiences. Over the next three to five years, power liftgates will increasingly be evaluated as part of a broader closure and access experience rather than as a standalone motorized mechanism. Contactless activation, occupant detection, adaptive closing behavior, and integration with vehicle access ecosystems will move from premium niches toward broader deployment. The commercial opportunity lies in suppliers and OEMs that can bundle actuation with sensing, control software, and validation support, reducing the integration burden for vehicle programs. The main risk is that feature creep raises cost and complexity faster than consumers are willing to pay, especially in price-sensitive segments.
Trend 2: Lightweighting as a strategic necessity, not an option. Weight reduction will continue to gain priority as EV range, packaging, and platform sharing become more central to vehicle economics. Thermoplastic and composite liftgate solutions, along with refined metal architectures, will compete on a program-by-program basis. Suppliers that can deliver repeatable weight savings without compromising durability, safety, or repairability will find expanded relevance across both passenger and commercial platforms. The uncertainty here is material cost and long-term durability validation, particularly where novel structures interact with crash, latch, and environmental requirements.
Trend 3: Supply resilience and material strategy as competitive levers. Input cost exposure will remain a central management challenge. Rare-earth magnet concentration and copper volatility will continue to influence actuator cost structures, making material strategy, multi-source procurement, and design flexibility critical capabilities. Companies that can offer design variants, alternative magnet strategies, or architectures that reduce sensitivity to a single commodity will enjoy stronger negotiating position and more stable margin profiles. The risk is that supply disruptions or trade dynamics compress available options and lengthen qualification cycles for alternative materials.
Strategic Implications for Decision Makers
For component and system suppliers. Positioning should emphasize validated integration rather than discrete component performance alone. The most defensible value proposition combines actuator efficiency, anti-pinch and sensor integration, lightweight material options, and platform-sharing architectures that reduce OEM engineering burden. Suppliers should also treat raw material exposure as a design problem, not only a procurement problem, by developing actuator and latch variants that can adapt to magnet and copper cost dynamics without sacrificing functional performance.
Electric Tailgate Radar Market
For investors. The market’s 7.6% CAGR through 2032 suggests durable growth, but returns will likely accrue to companies with differentiated system capabilities, cost-resilient supply chains, and exposure to both passenger and commercial demand. Investment theses should weigh not only revenue momentum but also the ability to capture value from lightweighting, functional integration, and access-control adjacencies. Companies that remain dependent on a single commodity-intensive actuator architecture or a narrow OEM base carry higher sensitivity to input costs and program concentration.
For procurement and OEM strategy teams. Sourcing decisions should balance short-term cost against integration risk and compliance readiness. As safety expectations around anti-pinch protection, sensor reliability across temperature ranges, and energy-efficient actuation increase, qualification speed and documentation rigor become as important as unit pricing. Multi-source strategies, where feasible, and clear material substitution pathways can reduce exposure to magnet and copper volatility while preserving program timing.
The broader opportunity is to treat the power liftgate not as a late-stage convenience add-on, but as an integrated closure system that contributes to vehicle efficiency, safety compliance, and user experience. Achieving that shift requires timely insight into where material strategies, regulatory expectations, and OEM platform priorities are converging. For leaders who need deeper segment-level data, regional demand patterns, and customized scenario planning, PW Consulting’s full Automotive Power Liftgate Market research report provides the granular breakdowns and strategic frameworks needed to translate market momentum into concrete program and investment decisions.
For detailed analysis of this topic, please visit the official page: Automotive Power Liftgate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com