

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Laser Drilling Machine for Aerospace: Why 6.98% CAGR Reshapes the $344.8M Market

Strategic Trends and Commercial Opportunities in the Laser Drilling Machine for Aerospace Market
The aerospace manufacturing sector is undergoing a fundamental transformation in how precision components are produced, and laser drilling technology sits at the center of this shift. As the 2025 market reaches an estimated 215.0 Million, with growth tracked from 2020 through the current year, the sector has demonstrated consistent expansion across the historical period. Looking ahead to 2032, the trajectory points toward a 6.98% compound annual growth rate, positioning this technology as a critical enabler for next-generation aerospace production. For executives, investors, and strategic planners, understanding the underlying dynamics of this market requires more than surface-level sizing. It demands a clear view of the technological, regulatory, and competitive forces shaping where capital and capability will flow over the next several years.
Worldwide Laser Drilling Device Market
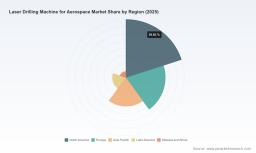
The expansion from 2020 to 2025 reflects a steady accumulation of adoption across engine component manufacturing, airframe assemblies, and specialized aerospace applications. By 2032, revenues are projected to reach 344.8 Million, signaling a market that has moved well beyond niche adoption and is becoming embedded in standard aerospace manufacturing workflows. This growth is not uniform across all categories. Energy-based machining technologies show clear differentiation, with fiber-based systems capturing the largest share of revenue, followed by solid-state laser approaches and carbon dioxide-based configurations. Similarly, the demand landscape shows commercial aviation driving the majority of activity, while military aviation and other specialized applications contribute meaningful but smaller volumes. Regionally, established aerospace hubs continue to anchor the largest revenue pools, while emerging industrial centers are gradually expanding their footprint.
Core Challenges and Inflection Points
Despite the positive growth trajectory, the market faces structural challenges that will determine which participants capture value and which struggle to compete. Three critical dynamics deserve attention.
First, certification and qualification remain formidable barriers. Laser drilling for aerospace components must align with stringent aviation quality standards and non-conventional machining certifications. Systems designed for turbine disc cooling holes, jet engine components, and high-temperature alloy processing require documented process control, traceable quality assurance, and often original equipment manufacturer approvals. These requirements create a high bar for entry and raise the cost of scaling new offerings, but they also protect incumbents who have invested in certified workflows and established relationships with engine and airframe manufacturers.
Second, the shift in laser technology modalities is reshaping buyer expectations. Fiber-based systems have gained prominence because they offer compact form factors, high beam quality, and strong compatibility with multi-axis CNC integration. Solid-state and carbon dioxide approaches still serve specific use cases, but the momentum is clearly tilted toward platforms that can deliver micro-hole precision with minimal heat-affected zones and predictable cycle times. Manufacturers that continue to rely on legacy process chains without adapting to fiber and hybrid architectures risk being outcompeted on throughput and repeatability.
Third, the demand environment is evolving as aerospace production scales and aircraft architectures become more complex. Cooling hole density, micro-hole accuracy, and surface integrity requirements are intensifying, especially for turbine blades, vanes, and high-performance structural parts. At the same time, the industry is looking for automation, monitoring, and software integration that can reduce variability across high-mix production runs. This places pressure on equipment suppliers and service providers to deliver not just hardware, but integrated process solutions that include control software, inspection feedback, and application engineering support.
Key Drivers Shaping Market Direction
The market is being pulled forward by a combination of technology advancement, regulatory frameworks, demand-side transformation, and cost structure evolution. Each driver reinforces the others, creating a coherent case for continued investment in laser drilling capabilities.
Worldwide Solar Laser Drilling Market
Technology Innovation and Breakthroughs
Precision and speed are becoming defining competitive dimensions. Advanced multi-axis systems now support positioning accuracy on the order of micrometers while enabling drilling rates that can reach hundreds of bores per second in optimized configurations. These capabilities are particularly relevant for effusion cooling holes in turbine discs and engine components, where geometry, diameter consistency, and surface quality directly affect performance and lifecycle cost. Fiber laser integration with 5-axis and 7-axis CNC architectures has expanded the feasible design space for drilling in complex contours and 3D aerospace alloys. In parallel, software and monitoring layers are improving process stability, allowing operators to manage trepanning, micro-hole patterns, and specialized flow or optical products with greater control and repeatability.
Policy and Regulatory Environment
Aviation quality standards and non-conventional machining certification requirements create both a barrier and a catalyst. Regulatory regimes and OEM quality expectations push manufacturers toward documented process control, validated machine performance, and certified service practices. This environment favors suppliers that can demonstrate compliance with recognized aerospace standards and provide the audit trail that engine and airframe producers require. At the same time, the standardization of laser drilling for critical cooling and precision hole applications reinforces its role as a preferred process in high-temperature alloy manufacturing, supporting long-term demand stability beyond cyclical production fluctuations.
Demand-Side Changes
Commercial aviation continues to be the dominant application driver, reflecting the scale of production, aftermarket demand, and the ongoing need for precision cooling and micro-hole features across engine and airframe components. Military aviation adds a distinct set of requirements, where performance margins, material behavior under extreme conditions, and component reliability place a premium on advanced drilling technology. Beyond these core segments, specialized applications in flow control, optical products, and calibrated micro-leak features are creating pockets of high-value demand. The broader trend is toward more demanding geometries and tighter tolerances, which increases the appeal of laser processes that can maintain precision across difficult-to-machine materials and composite structures.
Supply Chain and Cost Structure Evolution
The economics of laser drilling are shifting as equipment becomes more integrated, automation more accessible, and service models more flexible. Multi-axis platforms with fiber lasers can reduce rework and improve throughput by minimizing heat-affected zones and improving hole quality consistency. For high-mix production, the ability to switch between configurations, control processes through software, and integrate monitoring reduces the cost of changeovers and improves asset utilization. At the same time, certified service providers and system integrators are expanding their geographic reach, allowing manufacturers to access specialized drilling capability without always investing in full in-house capacity. This combination of capital efficiency and capability access is changing how aerospace manufacturers evaluate their sourcing and production strategies.
Competitive Landscape and Leading Strategies
The market features a mix of established machine builders, specialized service providers, and technology integrators, each pursuing a distinct route to value. The competitive field is not dominated by a single model, and concentration remains moderate, indicating that differentiation and application expertise still matter greatly. This environment rewards companies that can combine hardware performance with certification readiness, software-enabled process control, and strong OEM relationships.
Strategic Positioning Among Leading Participants
DMG MORI has built its positioning around high-end multi-axis laser machining with fiber laser integration for precision drilling of turbine blades, vanes, and aerospace components. Its 5-axis LASERTEC PowerDrill series emphasizes precision, process software, and shape-control technology, targeting high-value engine and IGT component manufacturing where accuracy and repeatability are central. The appeal lies in combining machine rigidity, laser performance, and application software into a single platform that can be qualified for demanding aerospace workflows.
Prima Power offers a different angle through multi-axis laser systems focused on high-precision micro-hole drilling with low heat-affected zones and CNC monitoring. Its LASERDYNE series is oriented toward aerospace components where micro-hole integrity and process control are critical. By emphasizing specialized processing and 3D laser drilling capabilities, Prima Power positions itself for customers who need tight control over hole quality in complex geometries, while also expanding into broader laser processing solutions that include cutting and hybrid workflows.
EBTEC Corporation has developed a strong identity around certified laser drilling services and systems for aerospace alloys and composites, supported by AS9100 and NADCAP credentials as well as OEM approvals. Its multi-axis machines, spanning Nd:YAG and fiber laser configurations across a broad power range, are designed for precision holes in demanding materials. This service-plus-equipment model gives the company a clear route to customers who value qualification readiness, OEM acceptance, and full-process support rather than hardware alone.
Corry Laser Technology focuses on high-degree-of-freedom moving beam systems for trepanning and micro-hole drilling in 3D aerospace alloys. Its emphasis on multiple industry certifications and approvals from major aerospace players signals a strategy centered on trust, qualification, and capability validation. By aligning its systems with recognized aerospace standards, the company creates a defensible position in an environment where certification is often as important as raw machining performance.
Lenox Laser and Accumet Engineering illustrate the service-oriented side of the market. Lenox Laser specializes in precision laser drilling services and systems for small-hole technology, with particular attention to calibrated micro-leaks and flow or optical products. Accumet Engineering provides precision laser drilling services for metals and ceramics, with broad regional coverage and secondary processing capability. These participants show that for many aerospace manufacturers, the decision is not only about buying equipment but also about accessing specialized process expertise, quality assurance, and capacity flexibility.
Market Evolution and Structural Trends
The competitive landscape is evolving along several axes. One is the gradual convergence of laser drilling with broader laser processing platforms, as seen in recent industry showcases where drilling capabilities are presented alongside cutting and automated modules. This convergence reduces the friction of integrating drilling into larger production cells and can improve overall facility efficiency. Another is the continued importance of certification and OEM acceptance as filters for serious competition. Participants that can demonstrate NADCAP-aligned processes and approvals from major engine and component manufacturers are better positioned to win demanding contracts and retain long-term relationships.
At the same time, the market is open enough that new entrants and specialist service providers can build niches around application expertise, material-specific process development, and regional service coverage. The moderate concentration in the market suggests that scale alone is not the only winning strategy. Differentiation through software, monitoring, process qualification, and customer support remains a viable path, especially for companies serving high-mix, high-precision production environments. Recent industry activity also indicates that the sector is actively converging around aerospace-focused demonstrations and discussions, signaling that both suppliers and end users are paying close attention to laser drilling as a strategic process rather than a peripheral capability.
Future Trends and Commercial Opportunities
Looking forward across the next three to five years, several trends are likely to shape where value is created and how participants should position themselves.
PW Consulting Automotive & Machinery Research Center
Integration of Drilling with Automated Laser Processing Cells
The direction of travel points toward more tightly integrated systems that combine drilling, cutting, and automation within unified machine concepts. This trend is already visible in recent product announcements that pair drilling modules with laser cutting workflows and smart automation. For manufacturers, the commercial opportunity lies in reducing handling, improving throughput, and standardizing process control across multiple operations. For equipment suppliers, the opportunity is to offer platforms that can serve multiple process steps without forcing customers to manage fragmented equipment portfolios. The risk is that integration raises technical complexity and can increase the importance of application engineering, service responsiveness, and customer training.
Continued Emphasis on Certification, Quality Documentation, and OEM Alignment
Aviation standards and OEM approvals will continue to act as both a constraint and a competitive moat. Systems and services that can demonstrate NADCAP-aligned machining practices and maintain the approvals required for engine and airframe components will be better positioned to access the most demanding segments. This creates a commercial opportunity for participants to invest in qualified process documentation, audit readiness, and customer-facing quality systems. It also implies that short-term pricing pressure is less important than long-term qualification credibility in high-value aerospace segments. The uncertainty is that certification requirements can evolve, and qualifying new materials or new hole geometries may require additional validation effort.
Growth in High-Precision Micro-Hole and Complex Geometry Demand
As turbine components, cooling structures, and specialized aerospace parts become more geometry-intensive, demand for precise micro-hole drilling and complex trepanning will likely remain strong. Fiber laser systems with multi-axis capability are well suited to this demand because they can address difficult materials and 3D contours while maintaining tight tolerances. The commercial opportunity here is for suppliers and service providers that can demonstrate repeatable performance on challenging alloys and composites, including low heat-affected zones and stable hole quality. The downside risk is that materials and cooling requirements can change as engine architectures evolve, which means process flexibility and continued application development will be essential.
Strategic Recommendations for Decision Makers
Different stakeholders should prioritize different actions based on their role in the value chain. The common theme is that competitive advantage will come from combining technical capability with qualification readiness, process integration, and responsive service models.
For manufacturers and production leaders, the priority is to assess where laser drilling can replace or enhance existing process chains in ways that improve quality, reduce rework, and support tighter tolerances. Before expanding capacity, it is worth evaluating whether integrating drilling with adjacent laser processes or automated modules can increase asset utilization and simplify workflow. Equally important is ensuring that selected systems or services can meet the certification and approval requirements of target applications, because those requirements often determine whether a solution is viable for production use in the first place.
For investors and technology acquirers, the most relevant signal is that the market is expanding steadily, but value capture will depend on differentiation rather than volume alone. Platforms that combine fiber laser performance with multi-axis flexibility, software-enabled process control, and strong aerospace certification readiness are better aligned with long-term demand. Service-oriented providers with OEM approvals and specialized application expertise also represent an attractive way to participate in demand without needing to compete purely on equipment commoditization. At the same time, investors should monitor integration trends and watch for consolidation among specialists, since those dynamics can reshape regional coverage and service availability.
For procurement and sourcing leaders, the focus should be on total process reliability rather than unit price alone. Laser drilling for aerospace parts often implicates quality, certification, and downstream performance, so supplier selection should weigh documented process control, traceability, approval status, and the ability to support new materials or new hole geometries. Engaging suppliers early in the qualification process can reduce later delays, particularly when component designs require micro-hole precision or complex contours. Where in-house capacity is limited, partnering with certified service providers can offer flexibility while preserving access to specialized process expertise.
For organizations navigating this market, the most practical next step is to obtain a detailed view of segment-level demand, regional dynamics, and company-specific capability maps before making major investment or sourcing decisions. The broader trends are clear, but the specifics of where demand is strongest, which certifications matter most for a given application, and how competing platforms differ on precision, integration, and service support can materially change the outcome of a strategic choice. More granular data and tailored assessments can help translate market direction into concrete capital, procurement, and partnership decisions.
The laser drilling market for aerospace is moving from steady expansion toward a more integrated, qualification-intensive, and application-driven phase. That shift creates opportunities for equipment suppliers, service providers, and manufacturers that can combine precision technology with certified processes and flexible delivery models. It also raises the stakes for participants that underestimate the importance of software, monitoring, automation, and OEM acceptance. In a market projected to grow to 344.8 Million by 2032, the winners are likely to be those who treat laser drilling not as an isolated machine purchase, but as a strategic process capability embedded in high-performance aerospace production.
For detailed analysis of this topic, please visit the official page: Laser Drilling Machine for Aerospace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com