

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Automotive Water Pump Market: Why 5.3% CAGR and Asia Pacific Resonance Redefine Growth

Strategic Trends and Commercial Opportunities in the Automotive Water Pump Market
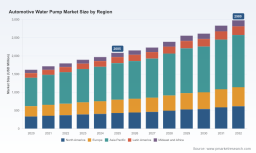
The automotive water pump market has evolved from a commoditized mechanical component into a strategically critical subsystem within broader vehicle thermal management architectures. Valued at approximately $2.085 billion in 2025 and projected to reach nearly $3 billion by 2032, the segment is expanding at a compound annual growth rate of 5.3 percent over the 2026–2032 forecast horizon. This trajectory reflects more than steady replacement demand; it signals a structural shift driven by powertrain electrification, tighter emissions and thermal efficiency mandates, and the growing complexity of cooling circuits that now serve internal combustion engines, hybrid drivetrains, battery packs, and power electronics simultaneously. For executives and investors evaluating near-term industrial exposure, the water pump market offers a tractable lens into how legacy component suppliers are repositioning for electrified thermal management, how aftermarket channels are adapting to new testing and certification requirements, and where margin pools are migrating as product specifications become more application-specific.
Automotive Vacuum Pump Market
Market Structure and Core Operational Challenges
The market’s scale and growth profile mask a moderately concentrated competitive environment. The top three players collectively command roughly 38 percent of global revenue, while the top five account for just under half, leaving meaningful room for regional specialists, Tier 2 suppliers, and well-capitalized aftermarket brands to compete on coverage, service speed, and application-specific engineering. This fragmentation is particularly visible across powertrain types and vehicle classes, where mechanical circulation pumps still dominate volume but electric and vacuum-assisted variants are expanding their share in hybrid, EV-adjacent, and specialized commercial applications. The structural tension is that growth is not evenly distributed; it is concentrated in configurations that demand higher reliability, tighter integration with electronic control units, and more rigorous validation protocols.
Three challenges are currently shaping how manufacturers, distributors, and service networks operate in this space.
- Testing and quality assurance intensity is rising. Modern water pumps, particularly those built with premium alloy materials for high-temperature engine environments, now require 100 percent functional and leakage testing to satisfy OEM and aftermarket safety expectations. This standard elevates fixed costs and compresses the economics of low-mix, high-volume production unless offset by automation, process control, and yield optimization.
- Certification and installer competency requirements are tightening. Updated qualification pathways for personnel handling cooling system repairs and replacements are reshaping labor readiness in the service channel. As safety standards evolve, professional installers increasingly need refreshed certifications, which affects turnaround times, warranty exposure, and the practical adoption of new pump variants in the field.
- Thermal management complexity is fragmenting demand. Vehicles no longer rely on a single cooling loop with a single pump duty cycle. Hybrid and electric architectures require coolant flow control that responds to engine load, battery temperature, and power electronics needs, often with speed variation and ECU activation. This shifts purchasing behavior from generic replacement toward application-matched components and elevates the importance of diagnostic compatibility.
The commercial implication is straightforward: competitive advantage is increasingly defined by the ability to deliver validated performance at scale, support evolving service certifications, and align product portfolios with the thermal architectures that dominate new vehicle production and high-value replacement segments.
Key Demand Drivers Reshaping the Segment
Several interlocking forces are accelerating change in the automotive water pump market. None of these drivers operates in isolation; together, they are redefining both the technical specification of pumps and the economic structure of the supply base.
Technology Innovation and Thermal Integration
The most decisive technological shift is the migration from purely mechanical circulation toward electronically controlled and application-specific pumping solutions. In legacy internal combustion platforms, water pumps remain fundamental to engine cooling, but their design tolerances, sealing architectures, and bearing durability are increasingly judged against higher operating temperatures and longer service intervals. In electrified and hybrid applications, pumps must coordinate with control units to modulate flow, reduce parasitic load, and optimize thermal management across multiple subsystems. This creates a dual opportunity set: suppliers that can offer cost-effective standalone repair variants for the aftermarket while also delivering integrated, control-ready hardware for OEM thermal loops are positioned to capture demand across the vehicle lifecycle. Recent product visibility at industry exhibitions, including augmented-reality demonstrations of water pump innovations, suggests that leading suppliers are investing in visualization, training, and integration messaging to help customers understand how next-generation pumps function within complex cooling circuits.
Water Pumps Market
Regulatory and Standards Pressure
Policy and standardization activity is raising the bar for both production and service. On the manufacturing side, the expectation that automotive water pumps undergo complete leakage and functional testing is no longer an optional quality flourish; it is a baseline requirement for OEM and aftermarket acceptance. On the service side, evolving safety qualifications are changing who can handle cooling system repairs and what credentials are required, which indirectly affects the competitiveness of aftermarket suppliers that depend on broad installer adoption. At the same time, material expectations are shifting: premium alloy constructions are increasingly tied to durability assurance in high-temperature environments, which raises performance credibility but also pressures cost structures. The net effect is a market where compliance and validation are becoming strategic differentiators rather than administrative overhead.
Demand-Side Shifts Across Vehicle segments
Vehicle mix is changing the shape of demand. Passenger cars continue to represent the largest application pool, but the composition of that demand is being reshaped by hybrid penetration, extended maintenance cycles, and higher expectations for cooling reliability across a wider range of operating conditions. Commercial vehicle applications remain significant, and their cooling requirements are intensifying as heavy-duty platforms adopt more sophisticated engine families and operate under demanding duty cycles. Off-highway vehicles constitute a smaller but technically demanding niche, where robustness and application-specific fitment often outweigh pure price competition. Across these segments, the strongest growth is not simply in unit volume but in specification complexity: customers increasingly want components that can be installed with confidence, tested to recognized standards, and matched to the thermal load characteristics of the target vehicle.
Supply Chain and Cost Structure Reconfiguration
Materials, testing throughput, and geographic manufacturing footprints are recalibrating cost dynamics. The emphasis on premium alloys and full-functional testing increases the importance of supplier process capability and yield discipline. At the same time, the broader component ecosystem is adapting to higher content per vehicle in thermal management, which can support pricing power for suppliers that bring validated performance and application breadth. Geography also plays a role: different regions reflect distinct vehicle production patterns, service channel maturity, and regulatory expectations, meaning that suppliers with flexible manufacturing and strong regional coverage can better absorb localized cost shocks and respond to application-specific demand.
Competitive Landscape and Leading Strategies
The competitive field combines established global suppliers, regional specialists, and aftermarket-focused manufacturers, each pursuing a distinct route to relevance. The strategic puzzle is not who is largest in absolute terms, but who is best positioned to convert technical change into defensible share.
Global OEM-oriented suppliers such as Aisin and Continental are leaning into thermal management breadth and manufacturing credibility. Aisin’s position as a leading aluminum die-cast engine cooling water pump supplier to Japanese manufacturers, with expanding reach into European and American production, reflects the value of scale, casting expertise, and long-standing OEM relationships. Its recent demonstration of augmented-reality product innovations at a major industry event underscores a broader playbook: using visible technology demonstrations to signal engineering depth and to educate partners on new pump behaviors in electrified and hybrid cooling loops. Continental’s focus on standalone water pumps and kits for thermal management, including cost-effective variants without control units, highlights a complementary strategy: serving the repair and replacement market with practical, lower-integration options while still participating in higher-specification thermal management solutions.
In the aftermarket and engineered replacement space, brands such as Gates, Carter, and SKF are competing on performance assurance, coverage, and testing credibility. Gates emphasizes premium alloy automotive water pumps for late-model, hybrid, and vintage vehicles, paired with 100 percent functional and leakage testing, a positioning that directly addresses the rising quality expectations discussed earlier. Carter positions engineered water pumps for engine cooling with OEM-level performance and broad vehicle coverage, appealing to customers who want dependable replacement without sacrificing fitment confidence. SKF’s emphasis on precision pumps and high reliability for engine cooling reinforces the broader theme that durability and fit are increasingly valuable in a market where warranty exposure and installer trust matter.
Heavy-duty and commercial vehicle specialists illustrate a different competitive angle. US Motor Works, for example, maintains a professional-series heavy-duty water pump lineup covering platforms such as PACCAR and Detroit Diesel applications, supported by ISO 9001:2015 certified manufacturing. Its recent catalog updates and new part numbers for specific commercial engine families demonstrate how application-specific coverage and timely part expansion can defend share in commercial channels where downtime costs are high and specification accuracy is non-negotiable. Setco Automotive, based in India, has been expanding its water pump offerings within a broader thermal management and clutch component portfolio targeting passenger cars and light commercial vehicles, an example of how regional manufacturers can scale by aligning component portfolios with local vehicle mix and growing service demand.
Electric and thermal-management-focused entrants are also shaping the field. VALEO’s integration of electric and mechanical water pumps into vehicle cooling systems for passenger and commercial vehicles reflects the broader shift toward electrified thermal architectures. Bosch’s portfolio of water pumps, including switchable and control-unit variants for modern engine systems with expanded aftermarket part numbers, illustrates how established technology suppliers can bridge OEM content and aftermarket availability. Padmini VNA Mechatronics has been developing electric water pumps for EV and passenger vehicle thermal management, working with Indian OEMs such as Mahindra and Tata, which shows how regional suppliers can enter higher-value thermal content through partnerships and application-specific electrification support.
Taken together, these positions reveal three prevailing strategic orientations. First, some leaders are consolidating advantage through OEM content, casting and precision manufacturing, and thermal integration messaging. Second, others are differentiating through testing credibility, alloy and durability claims, and broad aftermarket coverage. Third, a third group is pursuing application-specific expansion in heavy-duty, commercial, or EV-adjacent segments where specification accuracy and regional vehicle mix create defensible niches. The likely trajectory over the next several years is continued differentiation rather than wholesale consolidation, because the value pool is splitting across high-specification OEM content, service-friendly repair kits, and specialized heavy-duty or electrified thermal applications.
Forward-Looking Trends and What They Mean for Commercial Strategy
Looking ahead three to five years, several trends are likely to define how the market matures and where commercial opportunities concentrate.
Trend One: Electronic Control and Thermal Management Will Become the Primary Margin Driver
As cooling loops grow more complex, the economic center of gravity will shift toward pumps and related hardware that integrate effectively with electronic control, support variable flow, and reduce thermal management load. This does not mean mechanical pumps will disappear; it means the highest-value work will increasingly involve coordination with control logic, coolant flow optimization, and application-specific validation. Suppliers that can offer both control-integrated solutions for new platforms and accessible repair options for the aftermarket will be better placed to capture value across the vehicle lifecycle. The commercial opportunity lies in packaging hardware with the technical support, diagnostics compatibility, and installer education that reduce friction in adoption.
Trend Two: Quality Assurance and Certification Will Separate Competitors
The expectations around 100 percent functional and leakage testing, premium material durability, and installer certification are not temporary frictions; they are becoming structural entry conditions. Companies that invest in testing throughput, process control, and clear quality communication will be able to command stronger positioning with OEMs and demanding aftermarket buyers. Conversely, suppliers that cannot demonstrate consistent validation or support the evolving competency requirements of the service channel will face growing disadvantages in warranty exposure, brand trust, and repeat procurement. For commercial strategy, this creates an opportunity to treat quality systems and certification readiness as market-facing assets rather than internal compliance tasks.
Trend Three: Regional Vehicle Mix Will Drive Asymmetric Growth Paths
Growth will not be uniform across regions because vehicle production, electrification pace, and service channel maturity differ. Asia Pacific’s scale in vehicle production and expanding local OEM ecosystems make it a central arena for both content and aftermarket development. North America and Europe will continue to reward suppliers that can combine broad coverage with strong application fit and service readiness, especially as hybrid and complex cooling architectures become more common in faster-turning replacement cycles. Latin America and the Middle East and Africa will remain important but likely more price-sensitive and infrastructure-dependent, where coverage, availability, and installer support can be as influential as technical differentiation. The strategic takeaway is that portfolios, manufacturing flexibility, and service networks must be calibrated to regional vehicle mixes rather than treated as homogeneous global demand.
These trends carry risks. Electrification timelines can shift, which changes the pace at which electric and hybrid thermal content scales. Testing and certification requirements may evolve further, raising compliance costs for suppliers that are slow to adapt. Material and manufacturing cost pressures can compress margins if yield and automation do not keep pace. And in the aftermarket, the success of cost-effective standalone repair variants depends on installer acceptance and diagnostic compatibility, which can be slower to develop than OEM adoption. Companies that monitor these signals closely will be better positioned to time portfolio investments and avoid overcommitting to a single trajectory.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align product architecture with the dual reality of rising thermal complexity and persistent aftermarket demand for reliable, installable replacements. That means investing in testing capability, process control, and alloy or sealing architectures that support durability claims, while also building a portfolio that spans control-integrated hardware for OEM loops and cost-effective variants for repair markets. Equally important is application coverage: deep fitment support for high-value commercial engine families, hybrid platforms, and passenger-car segments where replacement frequency and warranty sensitivity justify stronger engineering and service content.
For investors, the most relevant question is where margin pools are expanding as the market shifts from commodity replacement toward validated performance and thermal integration. Opportunities are likely to be strongest in suppliers that combine application breadth with credible quality systems, in regional players that can scale with local OEM and service demand, and in companies that can bridge electric and mechanical cooling requirements without over-concentration in a single architecture. Due diligence should pay close attention to testing infrastructure, certification readiness, coverage depth in commercial and hybrid applications, and the ability to support installer education and service adoption.
PW Consulting Automotive & Machinery Research Center
For procurement and fleet service organizations, the practical focus should be on reducing installation risk and warranty exposure while maintaining coverage across evolving vehicle populations. That argues for sourcing strategies that prioritize validated performance, clear documentation, and compatibility with existing service competencies, especially as certification expectations for cooling system repairs continue to tighten. In this environment, the value of detailed segment-level intelligence increases: knowing which applications are growing fastest, which specifications are becoming standard, and where testing or certification requirements are changing can materially improve sourcing decisions and inventory planning.
Detailed segmentation data, regional breakouts, application-level revenue estimates, and company-specific competitive benchmarks can sharpen these decisions further. For teams that need granular visibility into market splits, growth dispersion across vehicle types, and the strategic positioning of individual suppliers, the full research report provides the additional detail required to translate these trends into procurement roadmaps, portfolio priorities, and investment theses.
For detailed analysis of this topic, please visit the official page: Automotive Water Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com