

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Dust Sensors Market: Why 5.4% CAGR Growth Is Reshaping Strategic Competition

Navigating the Dust Sensors Market: Strategic Trends and Commercial Opportunities in a Tightening Air Quality Landscape
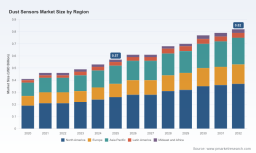
The dust sensors market stands at the intersection of environmental regulation, industrial automation, and consumer health awareness. Valuation reached an estimated $0.57 billion in 2025, expanding from $0.42 billion in 2020 at a compound annual growth rate of 5.4 percent. The trajectory points toward $0.82 billion by 2032, with the most pronounced acceleration concentrated in the 2026–2032 forecast window. This expansion is not merely a function of unit volume growth; it reflects a structural recalibration of how particulate matter is measured, monitored, and managed across commercial, industrial, and domestic environments. For executives and investors, the opportunity lies in recognizing where measurement precision, regulatory pressure, and cost discipline converge to create defensible positioning.
Beneath the headline growth figure, the market reveals a clear maturity curve. Historical expansion from 2020 through 2025 was supported by early-stage adoption in air quality monitoring and incremental industrial compliance upgrades. The next phase demands a shift from broad deployment to targeted, high-value applications where sensor data directly drives operational decisions or regulatory reporting. Market concentration remains moderate, with the top three participants holding approximately 28.5 percent of revenue and the top five reaching 38.2 percent. This fragmentation signals room for specialized players to capture niche leadership, but it also underscores the importance of differentiation in a space where commoditization pressure is building at the lower end of the performance spectrum.
Several structural challenges now shape the market's near-term evolution. The first is the tension between measurement fidelity and cost at scale. As deployment moves into dense urban networks and distributed industrial sites, the operational burden of installation, calibration, and maintenance becomes a meaningful constraint on total cost of ownership. The second challenge is regulatory fragmentation. Differing enforcement timelines, reporting formats, and particulate thresholds across jurisdictions create compliance complexity for manufacturers and end-users alike, requiring sensor solutions that can adapt to varying validation standards without sacrificing accuracy. The third is the performance ceiling of lower-cost optical technologies in harsh or high-particulate environments. Industrial dust, powder handling, and bulk solids operations expose sensors to contamination, humidity, and particle size distributions that can degrade readings if the underlying optical architecture and self-cleaning mechanisms are not engineered for those conditions. These pressures are not bottlenecks so much as filters: they determine which offerings translate into durable market share.
Key Drivers Reshaping Demand and Value Capture
Technology innovation continues to redefine what dust sensors can deliver in real time. Advances in optical detection architectures, laser-based particle sizing, and integrated signal processing are enabling tighter correlation between sensor output and reference-grade measurements. For environmental and indoor air quality applications, this translates into actionable data that can trigger filtration adjustments, ventilation control, or compliance documentation without relying on sporadic manual sampling. In industrial contexts, the shift toward continuous emissions and leak detection monitoring is reducing dependence on periodic checks, allowing operators to identify filter degradation or fugitive dust events sooner. The commercial value of these capabilities lies in their ability to convert raw particulate readings into operational signals that reduce downtime, protect equipment, and support audit-ready reporting.
Policy and regulatory pressure is reinforcing demand from the top down. In the European Union, the revised Ambient Air Quality Directive sets stricter limit values for PM2.5, reducing the annual limit value by more than half to align with WHO guidelines and streamlining provisions for twelve air pollutants. This creates a direct compliance pull for more granular, auditable monitoring across industrial sites, urban environments, and managed indoor spaces. In parallel, U.S. EPA monitoring priorities for 2025–2026 emphasize the deployment of next-generation low-cost sensors for PM2.5 in urban networks, reflecting a broader shift toward distributed measurement architectures that supplement reference stations. These regulatory signals expand the addressable demand base, but they also raise the bar for sensor validation, data credibility, and documentation traceability.
Demand-side behavior is changing on both the enterprise and consumer fronts. Organizations are increasingly treating air quality as an operational and reputational variable rather than a compliance checkbox. In healthcare, cleanroom-adjacent environments, and facilities with vulnerable occupants, particulate monitoring is being integrated into broader environmental management and ventilation strategies. In automotive and aerospace contexts, cabin air quality and sensitive component protection are driving interest in compact, reliable monitoring modules. On the consumer side, family-use applications continue to expand, supported by greater awareness of indoor air quality and the availability of smaller, lower-power devices. The strategic implication is that demand is becoming more application-specific, which rewards providers that can frame sensor performance in terms of the end-use outcome rather than raw specifications alone.
Supply chain and cost dynamics add another layer of complexity. Laser-based dust sensors depend on high-precision optical components and laser sources that require advanced polymer injection molding processes, tying performance to specialized manufacturing capabilities and materials availability. At the same time, labor costs associated with installing and calibrating low-cost sensors in dense urban networks remain a key operational constraint, particularly where large-scale deployments are contemplated. These factors push the market toward solutions that balance upfront hardware cost with ease of deployment, modularity, and maintenance efficiency. For suppliers, the winners are increasingly those who can reduce the hidden costs of integration and ongoing calibration rather than compete solely on unit price.
Competitive Landscape and the Logic of Differentiation
The competitive field is shaped by a mix of specialist sensor manufacturers and broader measurement-player portfolios, each pursuing a distinct value proposition. ENVEA, based in France, has focused its offering on real-time industrial emissions and filter leak detection through its ProSens and Dusty dust monitors. Its positioning reflects an emphasis on continuous industrial monitoring where measurement continuity and operational reliability matter more than consumer-facing form factors. In April 2025, the company launched a next-generation Optical Aerosol Spectrometer for real-time particulate matter monitoring, a move that signals an intent to extend high-resolution measurement capabilities into broader environmental and compliance contexts. The strategic takeaway is that advanced optical architectures can be used to bridge industrial emissions monitoring and ambient air quality requirements, provided the instrumentation is validated for the intended deployment environment.
Air Quality Sensor Market
Chinese manufacturers illustrate a different competitive logic, centered on laser and infrared dust sensors for air quality monitoring and industrial leak detection. Chengdu Pulse Optics-tech and Zhengzhou Winsen Electronics both emphasize laser and infrared-based sensing for air quality applications, with product families such as the ZH10 laser dust sensor and supporting infrared variants. Their trajectory suggests scale-oriented development aimed at cost-sensitive monitoring segments, where integration flexibility and price competitiveness can accelerate adoption. Cubic Sensor and Instrument takes a more application-specific approach, focusing on industrial dust sensors for powder and bulk solids leak detection. This specialization matters because it aligns sensor design with the particle types, loading conditions, and contamination risks encountered in material handling environments, rather than treating all particulate monitoring as a single category. The broader implication is that regional manufacturing depth and application-specific calibration can create defensible positions even in a market with many participants.
Western suppliers in automotive and HVAC-adjacent segments are pursuing integration-led differentiation. Amphenol Advanced Sensors, through its Telaire SMART Dust Sensor and DSF series, targets automotive and air quality applications, indicating a focus on embedding particulate sensing into vehicle and built-environment platforms where size, reliability, and system compatibility are critical. Sensirion, based in Switzerland, offers the SPS30 PM2.5 sensor for HVAC and air quality applications, an approach that connects particulate measurement to air circulation and filtration control in building systems. Shinyei Corporation, from Japan, continues to develop optical dust sensors such as the PPD series for air quality monitoring, reinforcing a long-standing emphasis on compact optical detection suitable for distributed monitoring. Collectively, these profiles show that competitive advantage is increasingly defined by where the sensor is integrated and what control or reporting function it enables, rather than by detection method alone.
The market structure is evolving along three trajectories. First, consolidation pressure is building at the lower-performance end, where generic optical sensors face margin compression and replacement risk from better-integrated alternatives. Second, specialization is intensifying in higher-value industrial and compliance-grade segments, where validation, durability, and data usability justifypremium positioning. Third, new entrants are likely to emerge at the intersection of sensor hardware and data services, particularly where low-cost networks can be combined with calibration support, remote diagnostics, and software layers that make readings operationally useful. For buyers and partners, this means supplier selection should weigh not only detection performance but also the ecosystem around calibration, maintenance, integration support, and data-handling practices.
Forward Outlook: Trends That Will Shape the Next Three to Five Years
The first major trend is the convergence of distributed sensing with regulatory-grade data expectations. As urban and industrial monitoring networks expand, the market will increasingly reward sensor platforms that can operate at scale while maintaining enough measurement consistency to support reporting, trend analysis, and operational decision-making. The commercial opportunity here lies in enabling large-scale deployments without surrendering data credibility, which requires thoughtful calibration strategies, robust optical designs, and software that can contextualize readings across sites and time periods. Companies that can reduce the hidden burden of installation and calibration will be better positioned to serve dense network scenarios.
A second trend is the migration of dust sensing from standalone measurement toward embedded control and predictive maintenance. In HVAC, industrial filtration, and material handling environments, particulate data is becoming part of a feedback loop that adjusts airflow, flags filter status, or alerts operators to leak conditions before they escalate. This creates a shift in value capture from device sales alone to solutions that contribute to energy efficiency, equipment protection, and compliance readiness. The opportunity is strongest for suppliers that can articulate how sensor data integrates with existing control systems and what operational outcomes it supports, rather than positioning the sensor purely as an information source.
PW Consulting Automotive & Machinery Research Center
A third trend is the widening performance gap between generic low-cost sensors and application-hardened solutions. As deployment scales, users are becoming more discerning about where lower-cost units are appropriate and where contamination, humidity, particle size range, or compliance documentation make ruggedized designs necessary. This does not mean the low-cost segment will disappear; it means its role will become more clearly defined. The strategic risk is for suppliers that overgeneralize their offering and get pulled into price competition in applications where performance and maintainability matter more. The corresponding opportunity is to segment the market deliberately and align product architecture, validation claims, and service support with the requirements of each segment.
Underpinning these trends are uncertainties that decision-makers should monitor. Regulatory timelines and enforcement intensity can vary by region, affecting demand pacing and validation requirements. Supply chain dependencies for precision optics and laser sources may influence cost and availability, particularly if manufacturing bottlenecks emerge around advanced polymer injection molding or specialized components. Labor and installation constraints may continue to shape the economics of large-scale urban networks, making modular, field-serviceable designs more valuable. Finally, data credibility remains a persistent question in distributed sensing, especially where readings inform compliance or public-facing reporting. Suppliers and end-users alike will need to manage expectations around uncertainty, calibration intervals, and the role of reference correlation in networked deployments.
Actionable Guidance for Manufacturers, Investors, and Procurement Leaders
For manufacturers, the priority is to define product strategy around use-case outcomes rather than detection method alone. That means mapping sensor architectures to the environments they will face, clarifying where calibration support, self-cleaning, or modular replacement add real value, and positioning data outputs in terms of operational or compliance utility. Companies that can demonstrate repeatability across installation conditions, simplify integration with ventilation or filtration control, and provide clear documentation for audit contexts will be better equipped to hold pricing power as the market matures. Equally important is deciding where not to compete: undifferentiated low-cost segments may generate volume, but margins and longevity will depend on whether the offering is tied to a defensible application fit or service model.
For investors, the most instructive question is where value will concentrate as the market evolves from broad adoption to more demanding applications. Segments tied to industrial leak detection, continuous emissions monitoring, HVAC integration, and compliance-aligned urban networks are likely to support more resilient economics than generic consumer-facing devices, provided the supplier can meet validation and maintainability expectations. Investment thesis-building should therefore emphasize differentiation in optical design, calibration and service strategy, integration readiness, and the ability to support data credibility at scale. It should also account for regional regulatory momentum, since policy-driven demand can create near-term pull but may shift in emphasis as standards harmonize or enforcement patterns change.
For procurement and operations leaders, sensor selection should be evaluated as a total-cost and risk decision, not just a hardware comparison. The relevant considerations include calibration and maintenance burden, expected service life under local particulate and humidity conditions, compatibility with existing control or reporting infrastructure, and the supplier's ability to support validation or documentation requirements where compliance is involved. In dense urban or multi-site deployments, installation labor and ongoing calibration constraints should be priced into the decision, because they can dominate lifecycle cost. Procurement teams also benefit from aligning sensor specifications with the actual decisions the data will inform: if readings drive filter changes, ventilation adjustments, or compliance reporting, then measurement stability and traceability become more important than marginal sensitivity gains in benign conditions.
As the market moves from early adoption to more disciplined, application-specific deployment, the ability to separate durable opportunity from transient hype will depend on detailed segmentation, validation expectations, and regional regulatory pacing. The broader market direction is clear, but the commercial winners will be those who can match sensor capabilities to the operational and compliance realities of each segment. For decision-makers seeking granular breakdowns of regional demand patterns, application-level sizing, company-level positioning, and scenario-based forecasts, a full market study provides the additional structure needed to translate these trends into a concrete investment, product, or procurement roadmap.
UV Sensors Market
For detailed analysis of this topic, please visit the official page: Dust Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com