

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Hydrochar Market Hits $285.5M in 2025, Projected 8.5% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Horizons in the Global Hydrochar Market: Navigating the 2032 Outlook
The global transition toward circular carbon economies is no longer a theoretical ambition. It is a measurable industrial shift, and nowhere is this more evident than in the rapidly maturing hydrochar sector. Hydrothermal carbonization has evolved from a niche laboratory process into a commercially viable pathway for converting wet organic residues into stable, energy-dense carbon materials. For executives, investors, and policy strategists operating in 2026, the question is no longer whether hydrochar will scale, but how market participants will position themselves within a rapidly fragmenting and capital-intensive landscape. This analysis draws from PW Consulting's latest worldwide hydrochar market research, offering a strategic preview of the macroeconomic trajectory, competitive architecture, and operational levers that will define the next seven years.
Market Trajectory: From Acceleration to Structural Scaling
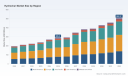
The hydrochar market is entering a phase of compounding structural growth rather than cyclical fluctuation. Historical revenue data from 2020 through 2025 demonstrates a consistent upward arc, reflecting the gradual commercialization of hydrothermal carbonization (HTC) and related conversion technologies across municipal waste management, industrial biomass processing, and agricultural valorization networks. From an analytical perspective, the transition into the 2026–2032 forecast window marks a critical inflection point, as scaling effects, regulatory alignment, and feedstock logistics begin to converge.
The market size trajectory underscores this momentum. Starting at approximately 195.4 million USD in 2020, revenue climbed steadily to 285.5 million USD by the base year of 2025. This historical run-rate establishes a firm foundation for the forecast period, with projected revenue expanding to 292.49 million USD in 2026 and accelerating toward 345.9 million USD by 2027. The trajectory continues upward through the decade, culminating in a projected market valuation of 505.37 million USD by 2032. When annualized, this pathway translates to a compound annual growth rate of 8.5 percent, a figure that places hydrochar among the more resilient subsegments within the broader bioenergy and carbon management ecosystem. For corporate strategists, an 8.5 percent CAGR is not merely a growth indicator; it is a signal that supply chain investments, technology partnerships, and capacity planning must be calibrated against a compounding demand environment rather than a static market structure.
Regulatory Catalysts and Feedstock Dynamics
Market expansion in the hydrochar space is being reinforced by a convergence of regulatory mandates and structural feedstock advantages. In Europe, the revised Waste Framework Directive (2008/98/EC) has established binding timelines for the separate collection of biowaste, fundamentally altering municipal waste management economics. This policy shift is expected to accelerate the deployment of HTC-based pathways, as municipalities and industrial processors seek compliant, high-value utilization routes for wet organic streams that would otherwise incur high transportation and disposal costs.
The raw material landscape further amplifies this trajectory. IEA Bioenergy Task 40 has identified roughly 200 million metric tons per year of available wet biomass residues across Europe alone, a volume that provides substantial feedstock headroom for hydrothermal conversion. This availability is critical because hydrochar production inherently favors wet biomass, circumventing the energy-intensive drying requirements that constrain conventional pyrolysis operations. From a technical standpoint, hydrothermal processing achieves a carbon yield in the range of 70 to 80 percent from initial biomass, while simultaneously densifying the energy content to approximately 25 MJ/kg, positioning the output as both a soil amendment and a drop-in solid fuel.
Carbon pricing mechanisms are adding commercial momentum. Under current European Union Emissions Trading System guidelines, the co-firing of hydrochar in industrial and power generation settings can qualify for carbon credit recognition, given that the process can reduce CO2 emissions by up to 90 percent relative to conventional coal combustion. This reimbursement dynamic transforms hydrochar from a waste-management solution into a monetizable decarbonization asset, enabling power generators and heavy industry operators to integrate hydrochar into existing combustion infrastructure with measurable compliance benefits. In parallel, macroeconomic planning in Asia is creating import and scaling pathways. China's 14th Five-Year Plan explicitly targets a 20 percent share for biomass energy, establishing a policy environment that supports both domestic development and cross-border procurement of hydrochar products and technology partnerships.
Segmentation and Application Architecture
The revenue architecture of the hydrochar market reflects a diversified application base, with material valorization and energy recovery operating as parallel growth engines. Rather than relying on a single end-use vertical, the market distributes demand across soil and fertilizer applications, solid fuel and energy generation, and activated carbon or adsorbent production. This tripartite composition provides structural resilience, as fluctuations in one application segment can be partially offset by demand in another. Soil amendment and fertilizer utilization remains a foundational demand channel, particularly as agricultural sectors seek organic carbon-based soil conditioners that improve water retention, nutrient availability, and long-term carbon sequestration.
Simultaneously, the solid fuel and energy generation pathway has emerged as the largest demand driver in the current market structure. Hydrochar's compatibility with existing combustion systems, combined with its elevated energy density and low moisture content after processing, enables industrial boilers, co-firing facilities, and dedicated bioenergy plants to substitute a portion of their fossil fuel inputs with a renewable carbon carrier. The activated carbon and adsorbents segment represents a higher-value, performance-driven market, where hydrochar serves as a precursor for filtration media, contaminant capture, and industrial purification applications. This segment's growth is tightly coupled with tightening environmental standards across water treatment, air quality management, and industrial process control.
Feedstock type segmentation further illustrates the market's adaptability. Sewage sludge, agricultural waste, and food waste each contribute meaningful volumes, with the relative attractiveness of each stream varying by regional waste management infrastructure, local regulatory frameworks, and downstream end-use requirements. Sewage sludge conversion benefits from established municipal collection systems and high moisture content that aligns well with hydrothermal processing. Agricultural residues provide a geographically distributed feedstock base with strong seasonal availability, while food waste streams offer concentrated organic content suitable for localized conversion facilities. The optimal feedstock mix is rarely static; it is shaped by logistics costs, subsidy structures, and the proximity of conversion capacity to both waste generation points and end-use markets.
Competitive Landscape: Technology Positioning and Corporate Strategy
The competitive structure of the hydrochar market remains moderately fragmented, with the top three participants collectively capturing approximately 28.5 percent of market revenue and the top five firms extending that share to roughly 35.2 percent. This concentration pattern indicates that while scale advantages are materializing, the market has not yet consolidated around a small number of dominant incumbents. The current competitive environment is instead defined by differentiated technology pathways, geographic specialization, and application-specific product positioning.
Ingelia, headquartered in Barcelona, Spain, has established itself as a reference point for commercial HTC deployment, particularly in the conversion of sewage sludge and biowaste into fertilizer and fuel-grade hydrochar. The company's operational footprint advanced significantly in November 2022, when it initiated operations at a 7,000 ton-per-year hydrochar plant in Italy, demonstrating the feasibility of medium-scale, continuous conversion infrastructure processing municipal sewage streams. This milestone highlights the commercial viability of integrating HTC into existing wastewater and waste-to-resource networks.
TerraNova Energy GmbH, based in Münster, Germany, has pursued an industrial-scale strategy through its HTCycle technology, targeting wet biomass residues for both energy and soil applications. The company reinforced its market trajectory in June 2023 by securing a contract for a HTCycle plant in Germany designed to produce approximately 20,000 tons per year of hydrochar from biowaste. This contract reflects a strategic emphasis on large-capacity facilities that leverage European biowaste collection mandates and industrial decarbonization requirements.
BlackCarbon GmbH, operating from St. Pölten, Austria, has carved out a premium positioning by manufacturing hydrochar from wood waste and agricultural residues, specifically designed as a drop-in coal replacement for industrial boilers. In March 2023, the company expanded its facility to a 10,000 ton-per-year capacity, signaling commitment to scaling a product line that prioritizes combustion compatibility and energy substitution in industrial heat applications.
Arbaflame A/S, headquartered in Aarhus, Denmark, has pursued a standardized pellet product strategy with its Arbacore hydrochar pellets, targeting co-firing applications in power plants as a sustainable coal alternative. This approach aligns with the broader energy transition demand for standardized, transportable biomass-derived fuels that can be integrated into existing power generation logistics without extensive boiler modifications.
Haffner Energy, based in Vitry-le-François, France, focuses on its ERC technology for generating SynChar hydrochar from wet organic waste, targeting energy production and carbon storage applications. The company achieved an important validation milestone in September 2022 with the certification of its ERC pilot plant for 1 ton-per-day SynChar production from agricultural waste, a step that supports its pathway toward commercial scaling and process refinement.
Worldwide Hydrochar Market
Hydrocracker Market
Antaco, operating from Santiago, Chile, illustrates the geographic diversification of the market by producing hydrochar from forestry residues and sewage sludge for soil amendment and biofuel markets across South America. The company's business model reflects the applicability of hydrochar technologies beyond European and North American regulatory contexts, demonstrating that feedstock availability, agricultural soil needs, and bioenergy demand can jointly support commercial deployment in emerging regional markets.
Strategic Decision Points for 2026 Leadership
For corporate leaders and investment decision-makers, the hydrochar market presents a set of interlocking strategic choices. The first is feedstock positioning. Given the diversity of viable input streams and the strong dependence on local logistics, companies must assess whether to align with municipal waste management contracts, agricultural residue supply networks, or industrial organic waste partnerships. Feedstock security is not merely an operational concern; it is a determinant of capacity utilization, revenue predictability, and margin stability.
The second decision point is application-market alignment. Facilities and technologies optimized for solid fuel substitution may require different product specifications, quality controls, and commercial partnerships than those targeting soil amendment or activated carbon production. The market does not reward generic product strategies. Instead, it increasingly favors architectures in which conversion capacity, downstream offtake agreements, and quality certification are integrated around a clearly defined end-use pathway.
The third strategic dimension is geographic and regulatory exposure. European biowaste mandates, carbon credit eligibility under emissions trading frameworks, and Asia's biomass energy targets create differentiated opportunity sets across regions. Market participants need to evaluate where regulatory tailwinds will most rapidly convert into contracted demand, and where infrastructure gaps, feedstock competition, or certification requirements may slow commercialization. The presence of a market concentration level in the high twenties to mid-thirties percent range further suggests that early positioning in underserved regional demand centers or specialized application niches can yield meaningful competitive insulation before later-stage consolidation pressures intensify.
Finally, capital allocation and partnership strategy will play a decisive role. The recent expansion and contracting activity observed among leading firms demonstrates that capacity scaling is being undertaken in phases, often anchored by specific feedstock contracts or downstream offtake arrangements. Market entrants and existing players alike are likely to benefit from structured collaborations that distribute technology risk, align feedstock sourcing with conversion capacity, and secure revenue visibility through multi-year offtake or joint operating models.
Conclusion: Why Comprehensive Market Intelligence Matters in 2026
The worldwide hydrochar market is entering a decade in which growth will be defined less by macroeconomic cyclicity than by regulatory momentum, feedstock logistics, and application-specific commercialization. The macro trajectory points toward sustained expansion, with the market advancing from approximately 285.5 million USD in 2025 to a projected 505.37 million USD by 2032 at a compound annual growth rate of 8.5 percent. Yet macroeconomic direction alone is insufficient for rigorous corporate planning. Effective strategy demands segmentation clarity, regional demand mapping, feedstock cost modeling, technology benchmarking, and competitive intelligence that links corporate developments to broader market shifts.
PW Consulting's Worldwide Hydrochar Market research is designed to provide that operational depth. The study integrates baseline and forecast revenue structures, segmentation analysis across regions, feedstock types, and application channels, and a detailed competitive assessment of the companies actively shaping the commercial landscape. It examines the regulatory, raw material, carbon pricing, and macroeconomic developments that are altering demand formation, while offering practical context for capacity planning, partnership evaluation, and market-entry decisions.
Full segmentation figures, regional revenue distributions, detailed company positioning, and forecast scenarios are available within the complete study. Readers seeking to translate the market's directional momentum into actionable 2026 strategy are encouraged to access the full report for comprehensive data, granular segmentation breakdowns, and the competitive intelligence required to benchmark opportunities against current industry dynamics.
For detailed analysis of this topic, please visit the official page: Worldwide Hydrochar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Heavy Truck Battery Swap Market Hits $1.25B in 2025, Projects 21% CAGR to 2032
By pmarketresearch, 2026-09-16
The 2026 Inflection Point: Strategic Intelligence for the Worldwide Heavy Truck Battery Swap Stations Market
The commercial transportation sector stands at a definitive crossroads. As decarbonization mandates harden and total cost of ownership models shift, battery-electric heavy trucks are transitioning from pilot programs to scaled deployment. Yet the charging bottleneck remains the single greatest barrier to fleet electrification at scale. Battery swap technology has emerged as the structural solution to this challenge, and 2026 marks the year the industry moves from proof-of-concept to commercial reality. Our newly released Worldwide Heavy Truck Battery Swap Stations Market research delivers the granular intelligence executives need to allocate capital, design infrastructure strategies, and secure competitive positioning in a market projected to surge from USD 1,250.0 million in 2025 to USD 4,746.9 million by 2032, reflecting a compound annual growth rate of 21.0 percent across the 2026–2032 forecast window.
This research is engineered not as a passive data repository but as a decision architecture tool. Every section is calibrated to answer the strategic questions that will define boardroom conversations in 2026: Where does capital flow most efficiently? Which operational models will dominate early-adopter corridors? How do regulatory interventions reshape unit economics? And which players are building defensible moats versus those riding temporary policy tailwinds? The following analysis outlines the strategic architecture of this intelligence, demonstrating how it translates market complexity into actionable executive roadmap components.
A Market Trajectory Defined by Acceleration and Structural Rebalancing
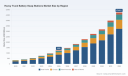
The growth curve tells a story of accelerating commercial validation. Revenue expanded from USD 350.0 million in 2020 to USD 427.88 million in 2021, then accelerated through USD 543.2 million in 2022 and USD 750.94 million in 2023 as infrastructure rollouts moved beyond demonstration phases. The trajectory crossed the one-billion threshold at USD 968.97 million in 2024, reached USD 1,250.0 million in 2025, and is projected to climb to USD 1,474.17 million in 2026 before scaling to USD 1,839.2 million in 2027, USD 2,279.85 million in 2028, USD 2,768.68 million in 2029, USD 3,189.24 million in 2030, USD 3,995.27 million in 2031, and ultimately USD 4,746.9 million in 2032. This expansion is not linear; it reflects compounding effects of standardized hardware deployment, fleet-scale procurement cycles, and localized incentive architectures aligning with route-specific utilization patterns.
For executives, the critical insight lies in recognizing that 2026–2028 represents a positioning window where early infrastructure commitments secure operational corridors, while delayed entry forces negotiation from a disadvantaged position as asset utilization rates climb and site availability contracts. The research maps these inflection dynamics across multiple commercial variables, enabling scenario modeling that accounts for deployment pacing, regulatory timeline shifts, and capital expenditure phasing.
Decoding the Commercial Architecture: Segmentation Logic and Deployment Realities
The market does not grow uniformly across geographies or operational configurations. Regional deployment patterns reveal distinct maturity curves, with Asia Pacific commanding the largest revenue share at USD 852.66 million, followed by Europe at USD 218.48 million, North America at USD 128.21 million, and Rest of World at USD 50.65 million. These distributions reflect differences in freight corridor density, policy sequencing, grid integration timelines, and the progression of truck manufacturing ecosystems. The research dissects the underlying drivers behind each regional trajectory, examining how corridor-specific freight volumes, municipal permitting structures, and cross-border trade routes influence station siting economics and utilization forecasts.
Station architecture introduces another strategic dimension. Automated swap stations, representing USD 954.28 million of the segmentation landscape, deliver throughput advantages critical for high-utilization fleet corridors, while semi-automated configurations at USD 295.72 million offer capital flexibility for phased rollouts and lower-density routes. Operation models further diversify strategic considerations: fleet-dedicated stations at USD 699.11 million align with captive logistics networks seeking predictable turnaround cycles, whereas public access stations at USD 550.89 million address multi-operator utilization and emerging commercial ecosystems. Each segment carries distinct capex profiles, utilization thresholds, and margin trajectories, all of which are mapped in detail within the full report to support deployment sequencing decisions.
The competitive structure adds another layer of strategic complexity. Market concentration metrics show a CR3 of 65.2 percent and a CR5 of 78.4 percent, indicating that early-mover positioning and standardized ecosystem control are consolidating rapidly. This concentration underscores the urgency of strategic timing: as leading operators scale standardized networks and secure preferential site access, late entrants face increasing structural friction in building comparable throughput economics.
Operational Economics, Grid Integration, and the Policy Multiplier
Infrastructure deployment cannot be evaluated in isolation from the operational and regulatory environment that shapes unit economics. Station construction requires substantial upfront investment, with costs typically ranging from RMB 15 million to RMB 25 million per site when accounting for civil works, battery procurement, and grid upgrades. Grid integration demands are equally consequential, as stations require minimum 2MVA connection capacity to support simultaneous swap operations involving multiple heavy battery packs. These technical thresholds directly influence site selection logic, permitting timelines, and the economic viability of high-throughput configurations.
Battery economics form the core variable in total cost calculations. Heavy truck swap batteries in the 500–700kWh LFP range trade in bulk at approximately RMB 800 to RMB 1,200 per kWh, making procurement scale, cycle-life management, and second-life utilization pathways critical margin determinants. The research models these cost structures alongside utilization scenarios to identify the throughput thresholds at which station economics transition from marginal to accretive, providing executives with clear deployment pacing benchmarks.
Policy architecture functions as a strategic accelerator. Chinese local governments have structured subsidy frameworks offering up to RMB 10 million per heavy truck battery swap station under new infrastructure initiatives, materially improving early-stage payback profiles. Simultaneously, standardization efforts have gained formal traction. The MIIT group standard T/CAMPEV 115-2023, released in October 2023, specifies battery voltage compatibility up to 1000V and mandates swap completion times under six minutes for heavy trucks. This standard establishes the technical baseline for interoperability and reduces the fragmentation risk that historically plagued early swap ecosystems. The report maps how these regulatory instruments interact with corporate capital deployment cycles, enabling executives to anticipate subsidy utilization windows, compliance timelines, and interoperability requirements across different jurisdictions.
Competitor Positioning: Who Is Building Scale and Who Is Building Standards
The competitive landscape is defined by a concentrated group of infrastructure and vehicle ecosystem players advancing parallel but increasingly intersecting strategies. CATL, headquartered in Ningde, China, operates the Tianfu Battery Swap Network, deploying standardized heavy-duty truck battery swap stations engineered for 5-minute swap cycles on 500kWh+ battery packs. Its November 2023 commissioning of the world's first standardized heavy-duty truck battery swap station in Yibin, Sichuan, supporting Sinotruk vehicles, signals a shift from component supply to integrated infrastructure ownership, positioning the company at the intersection of battery standardization and station-level throughput optimization.
Worldwide Heavy Truck Battery Swap Stations Market
Farizon Auto, based in Hangzhou, China, has advanced its V5 SuperSwap station network to support Geely's electric logistics vehicles through modular battery swapping architectures. The September 2023 launch of its first heavy truck swap station in Hangzhou marked an early operational footprint for a vehicle manufacturer building parallel infrastructure capability, a model that ties station economics directly to captive fleet deployment and reduces interoperability uncertainty in early corridor rollouts.
TGOOD, headquartered in Shenzhen, China, delivers integrated battery swap solutions spanning heavy-duty trucks and logistics applications, with commercial stations already operational across multiple Chinese provinces. Its multi-provincial footprint illustrates the importance of geographic diversification and operational learning curves in refining station throughput, maintenance cycles, and localized grid coordination strategies.
Aulton New Energy, based in Wuxi, China, extends its bus swap technology heritage into heavy truck applications, offering turnkey swap stations featuring automated battery handling systems. Its cross-segment technology transfer highlights a strategic pathway where standardized mechanical handling, control software, and safety protocols developed in higher-volume transit applications are adapted to the heavier payload and higher voltage requirements of commercial truck corridors.
The recent development timeline confirms that 2023 represented an acceleration point. Between September and November 2023, the ecosystem advanced on multiple fronts: a flagship station commissioning, a formal interchangeability standard from the Ministry of Industry and Information Technology, and the launch of a manufacturer-led network node. These milestones collectively illustrate how standardization, hardware deployment, and vehicle ecosystem alignment are converging to reduce the fragmentation risk that previously constrained commercial scalability.
What the 2026–2032 Forecasting Framework Delivers
Executive decision-making under capital allocation pressure requires more than directional market sizing. The research is structured to support scenario-driven planning across multiple decision dimensions. It combines historical performance tracking from 2020 through 2025 with forward-looking forecasting across the 2026–2032 window, enabling readers to test deployment pacing assumptions against revenue trajectories, utilization thresholds, and capitalization timing.
The report examines station type economics in operational context, contrasting the throughput advantages and capex intensity of fully automated configurations against the flexibility and phased deployment logic of semi-automated sites. It evaluates operation model divergence between fleet-dedicated deployments, which prioritize turnaround predictability and captive utilization, and public access models, which pursue multi-operator aggregation and broader corridor coverage. Regional deployment logic is analyzed through the lens of corridor density, policy sequencing, and infrastructure readiness, rather than through static market share tables, ensuring that executives understand the underlying conditions that shape where and when station networks achieve economic viability.
Competitive intelligence goes beyond corporate profiling to map strategic posture, technology positioning, and deployment sequencing. The analysis identifies which players are prioritizing standardized interchangeability, which are aligning station rollout with captive vehicle procurement, and how recent standardization milestones alter the barrier profile for new entrants. This competitive mapping is integrated with market concentration dynamics to clarify the window during which partnership, site acquisition, and standardization adoption decisions carry the highest strategic leverage.
From Intelligence to Execution: Why 2026 Demands Precision Planning
The growth trajectory, regulatory architecture, and competitive consolidation visible in the current market phase create a narrow planning horizon. Capital deployment decisions made in 2026 will determine whether organizations secure high-utilization corridors or enter as followers competing for constrained site availability and secondary freight routes. The research equips executives to navigate this window by translating market scale projections into deployment sequencing logic, regulatory timing into capital phasing strategies, and competitor movement into partnership and positioning options.
For fleet operators, the intelligence clarifies the throughput and utilization thresholds at which swap station access transitions from operational experiment to structural advantage. For infrastructure developers and equipment suppliers, it identifies the site economics, grid integration requirements, and standardization trajectories that shape bankability and scale potential. For investors and strategic advisors, the concentration dynamics and regional deployment sequencing provide a framework for evaluating where value capture is most likely to accrue as the market matures from early infrastructure buildout toward broader corridor integration.
The full report expands every dimension outlined here into a comprehensive strategic architecture. It integrates detailed segmentation analysis, operational cost modeling, regulatory impact mapping, competitive positioning frameworks, and forward-looking scenario structures designed specifically for 2026 capital allocation and infrastructure planning cycles. The macro trajectory, the standardization milestones, the site economics, and the competitor deployment patterns documented within provide the evidence base required to move from market awareness to execution readiness.
Worldwide Substation Battery Market
Access the complete Worldwide Heavy Truck Battery Swap Stations Market research to secure the full segmentation breakdowns, competitor strategy maps, regional deployment logic, and scenario-planning frameworks that transform market intelligence into boardroom-ready strategy. In a market advancing at a 21.0 percent compound growth rate toward a 2032 revenue milestone above USD 4.7 billion, the organizations that move with precision in 2026 will define the infrastructure corridors and standardization standards that shape the next decade of heavy truck electrification.
For detailed analysis of this topic, please visit the official page: Worldwide Heavy Truck Battery Swap Stations Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Die Cutting Market Hits $6.55 Billion in 2025, Forecasted to Reach $9.12 Billion by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for a Transforming Market: Introducing the Worldwide Die Cutting Service Market Research
The global die cutting service industry stands at a critical inflection point. With the market projected to reach approximately $9.12 billion by 2032 and a compound annual growth rate of 4.85 percent across the forecast horizon, the sector is no longer defined solely by mechanical precision or steady manufacturing demand. It is being reshaped by material cost volatility, sustainability mandates, accelerated technology adoption, and an increasingly fragmented competitive landscape. For executives navigating procurement strategy, capacity planning, or market entry decisions in 2026, superficial summaries are no longer sufficient. This article previews the strategic architecture of our latest Worldwide Die Cutting Service Market research and outlines why this intelligence is essential for decisive, future-ready corporate action.
A Data-Backed View of Market Momentum: 2020 Through 2032
Our analysis tracks a clear upward trajectory across the historical and forecast periods. From 2020 through 2025, the market expanded from roughly $5.12 billion to $6.55 billion, reflecting resilience despite macroeconomic pressures, supply chain realignment, and raw material price fluctuations. The forecast period from 2026 to 2032 extends that momentum, with revenue climbing through 2028 before a notable acceleration drives the market toward its 2032 endpoint. The overall trajectory underscores a structurally growing demand environment rather than a cyclical spike, but growth is not uniform. It is being pulled forward by specific process innovations, regional production shifts, and end-use industries that demand tighter tolerances, faster turnaround, and increasingly sustainable material formats.
Worldwide Die Cutting Service Market
For corporate strategists, this pattern matters because it reveals where investment and differentiation are likely to compound. The forecast period does not simply show higher aggregate revenue; it highlights a market in which operational capability, technological readiness, and regulatory compliance will increasingly separate winners from commoditized service providers. Decision-makers who understand the underlying drivers early can align capacity, vendor selection, and product-development roadmaps accordingly, rather than reacting after cost structures or customer expectations have already shifted.
Why This Research Is Designed for 2026 Decision-Makers
The Worldwide Die Cutting Service Market research is built around actionable clarity, not abstract market description. It is structured to support board-level planning, operations leadership, procurement strategy, and competitive positioning. The report integrates market sizing, segmentation, competitive profiling, and recent industry developments into a single decision-oriented framework. Readers will find a detailed mapping of process types, end-use applications, and regional demand patterns, alongside practical insights on how technology adoption and regulatory change are altering cost dynamics and service expectations.
Beyond descriptive market structure, the study examines the strategic implications of recent capital investments, equipment launches, and corporate transactions that are reshaping service capabilities. It also contextualizes raw material pricing trends and policy developments that directly affect conversion economics and compliance planning. The goal is to give executives a defensible basis for evaluating supplier partnerships, assessing technology upgrade priorities, and anticipating where service requirements will tighten over the next several years. Rather than delivering a static snapshot, the research is designed to support scenario planning in an environment where pricing, capacity, and sustainability expectations are all moving at once.
Segmentation and Demand Drivers: Where Value Is Concentrating
The market is shaped by three structural dimensions: process type, end-use industry, and regional demand. Each dimension carries distinct implications for service providers and buyers.
Process Landscape and Capability Shifts
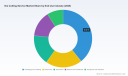
Die cutting services are delivered through multiple conversion methods, each with different throughput characteristics, precision profiles, and capital requirements. Rotary die cutting remains a dominant pathway for high-volume production, particularly where speed, repeatability, and integrated printing or converting capabilities are essential. Flatbed die cutting continues to serve applications that demand flexibility, precision geometry, and lower setup friction for shorter runs or more complex layouts. Laser die cutting adds a further dimension by enabling intricate cuts and reducing tooling dependency in specialized use cases. Alongside these established approaches, additional process variants support niche requirements and hybrid converting workflows.
From a strategic standpoint, the relevant question is not which process is largest in isolation, but where demand is migrating as customers balance volume efficiency against customization, waste reduction, and compliance-driven material changes. The report evaluates how service providers are positioning themselves across these process categories and where equipment investment is likely to widen competitive gaps.
End-Use Industries as Demand Anchors
Demand for die cutting services is distributed across a diversified set of end-use industries, each with different performance requirements and procurement cycles. Packaging and labeling continues to be a central demand driver, reflecting the ongoing need for precise blanks, inserts, protective structures, and labeled components across consumer goods, e-commerce, and industrial supply chains. Electronics represents another significant demand pool, where tight tolerances, clean processing, and specialized material handling are increasingly important. Automotive applications add further volume and complexity, particularly as component specification and lightweighting requirements tighten. Medical and healthcare demand introduces strict quality, traceability, and material-compatibility expectations. Aerospace and industrial applications complete the picture with specialized performance thresholds and lower-volume but higher-value part requirements.
Importantly, these end-use segments do not grow in lockstep. Their relative influence on market expansion depends on production localization, regulatory pressure on materials, and the pace of product innovation. The research dissects how each vertical shapes service expectations and where suppliers can capture differentiation through process control, material expertise, or integrated converting capabilities.
Regional Demand and the Geography of Service Delivery
Regional demand patterns reflect broader manufacturing footprints, packaging consumption habits, and local regulatory environments. North America and Europe remain major demand centers with mature service ecosystems, while Asia Pacific stands out for its scale and ongoing production-network expansion. Latin America and the Middle East and Africa contribute additional regional demand, though from smaller bases, and are influenced by import dynamics, localized manufacturing strategies, and evolving logistics patterns.
Because regional markets differ in cost structures, supplier density, and compliance obligations, a single global strategy rarely fits all operating contexts. The report maps these regional differences in a way that helps organizations assess where to consolidate sourcing, where to diversify supply, and where regional capability gaps may create strategic risk or opportunity.
Competitive Landscape and Strategic Positioning
The competitive environment in die cutting services is characterized by a wide mix of specialized converters, packaging-focused service providers, and broader industrial material suppliers. Market concentration remains relatively modest at the top tier, with the top three firms holding a combined share in the low double digits and the top five firms still occupying a limited portion of total market revenue. This fragmentation suggests that scale alone is not the only route to advantage. Service quality, material versatility, process flexibility, and customer-specific engineering capability continue to matter deeply, especially in applications where precision, turnaround speed, and compliance are decisive.
Several U.S.-based specialists illustrate the depth of capability across the market. Colvin-Friedman Company has built a long-standing reputation for precision custom die cutting across more than twelve industries, emphasizing material versatility and decades of converting experience. Mills Industries focuses on precision die cutting for custom plastic corrugated packaging, including inserts, dividers, dunnage, bins, and protective solutions. LMI Packaging concentrates on precision die-cutting for lids and labels in packaging applications, with an emphasis on quality and strict specification requirements. Janco, Inc. delivers custom die cutting services for foam, plastic, and related materials across packaging, industrial, and medical sectors using rotary, flatbed, and steel rule methods. MCL Industries Inc. operates as a leading provider of rotary and flatbed die cutting services for plastics, foams, and related materials, offering turnkey converting for high-volume packaging production. Best Cutting Die supplies custom dies and die cutting solutions designed specifically for packaging processes, aiming to minimize downtime and support efficient production. The Strouse Corporation, American Industrial Company, and Gardico Inc each bring additional depth in custom parts, precision components, and long-standing service orientation across packaging and industrial applications.
At the same time, larger international players are shaping the broader market through scale, capital investment, and sustainability-focused innovation. DS Smith has moved aggressively into advanced rotary die-cutting capacity, including recent investment in high-precision corrugated board conversion. Mondi emphasizes die-cut carton and board solutions tied to sustainable packaging applications, while Smurfit Westrock continues to compete as a leading provider of die-cut boxes and cartons in corrugated and folding carton markets. Equipment and converting-technology suppliers also influence service capabilities indirectly by setting performance standards and enabling faster, more precise production. BOBST supports converting services and supplies advanced flatbed and rotary die-cutting equipment for folding carton and corrugated board packaging. MM Packaging specializes in die-cutting and creasing processes for cartonboard packaging to produce precise blanks for efficient forming.
The strategic takeaway is that competitive advantage in this market is increasingly multidimensional. Providers are competing not only on price, but on process reliability, material breadth, sustainability alignment, and the ability to integrate die cutting into broader converting and packaging workflows.
Recent Developments Reshaping Market Dynamics
Recent corporate and technology developments underscore how quickly the operational baseline is changing. In March 2026, DS Smith invested DKK 100 million to install an advanced rotary die-cutting line with flexographic printing at its Grenaa facility in Denmark, increasing corrugated board capacity by up to 15 million square meters annually while improving precision on complex die cuts and reducing waste. This kind of investment signals the market's direction: higher throughput, better precision, and stronger emphasis on material efficiency.
In May 2025, Winkler+Dünnebier completed the acquisition of Sysco Machinery Corporation, adding advanced rotary die-cutting, slitting, and rewinding technologies for converting and packaging applications. The transaction illustrates how equipment and converting capability are being consolidated to strengthen integrated service offerings. In March 2025, BOBST launched the MASTERCUT 106 PER flatbed die-cutter at drupa 2025, showcasing 8,000 sheets per hour speed, quick-change capabilities, and a digital performance platform for folding carton and packaging production. Product launches like this expand the practical ceiling for conversion speed and flexibility, raising expectations for service providers who rely on or partner with equipment suppliers.
These developments matter because they affect more than individual companies. They shift customer expectations around lead times, precision, waste reduction, and integrated capability. They also influence the cost and risk profile of maintaining competitive service quality, especially for organizations that must meet increasingly demanding specifications without sacrificing throughput.
Raw Material Pressure and Regulatory Disruption
Market dynamics are not driven only by equipment and competition. Cost volatility and regulatory change are reshaping the operating environment at the same time. Recent pricing data shows continued pressure in corrugated and solid fiber box manufacturing inputs. The U.S. Producer Price Index for corrugated and solid fiber box manufacturing, specifically corrugated paperboard in sheets and rolls, reached 390.002 in March 2026. At the same time, corrugated paper prices in Northeast Asia were reported at 0.41 USD per kilogram in March 2026, compared with around 0.30 USD per kilogram in North America. These differences matter for sourcing strategy, margin planning, and regional service economics, especially for organizations exposed to cross-border supply chains or multi-site procurement.
On the regulatory side, packaging and paper product responsibility is advancing rapidly in the United States. Seven states, including California, Colorado, Maryland, Maine, Minnesota, Oregon, and Washington, have enacted Extended Producer Responsibility laws for packaging and paper products, with ongoing implementation through 2026. In early 2026, Wisconsin and New Hampshire introduced EPR bills covering packaging, paper products, and beverage containers. Minnesota's packaging EPR framework requires producers to participate through a producer responsibility organization, with a needs assessment due by December 2026.
For die cutting service buyers and providers, these policies are not background noise. They influence material selection, waste-reduction priorities, reporting obligations, and the relative attractiveness of sustainable packaging formats. In practical terms, they can alter demand patterns for certain substrates, affect the cost of compliance, and reward service partners that can support material reduction, recyclability, or responsible sourcing claims with credible operational execution.
What the Full Report Delivers
The Worldwide Die Cutting Service Market research is designed to turn these forces into usable strategy. It combines market sizing and forecast context with segmentation analysis across process types, end-use industries, and regions. It profiles the competitive landscape and recent developments that are actively reshaping service capabilities. It also embeds the cost and regulatory environment into the analysis so that executives can evaluate not only where the market is heading, but what it will take to compete effectively within it.
Personal Electronic Die Cutting Market
Because this is a fast-moving market, the report is intended to support concrete decisions: how to structure supplier relationships, where to invest in process flexibility, how to anticipate compliance-driven material shifts, and how to position offerings in a fragmented but increasingly capability-sensitive market. The full dataset, segmentation detail, company profiles, and forward-looking scenario framing are available in the complete study.
Next Steps for Strategic Readers
If your organization is evaluating market entry, supplier consolidation, capacity expansion, or packaging and converting strategy for the 2026 to 2032 period, this research is built to inform those choices with rigor and commercial relevance. The executive summary and full market framework provide the level of detail required to move from general awareness to actionable intelligence. Readers seeking a complete view of segmentation splits, competitive positioning, regional dynamics, and the latest market developments are encouraged to access the full report through the source page, where the underlying data, profiles, and scenario context are presented in full.
For detailed analysis of this topic, please visit the official page: Worldwide Die Cutting Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Civil Engineering Shape Memory Alloys Hit $245.5M in 2025, Growing 8.5% to $434.58M by 2032
By pmarketresearch, 2026-09-16
Unlocking the Future of Structural Resilience: A Strategic Overview of the Shape Memory Alloys in Civil Engineering Market 2026-2032
The global civil infrastructure landscape is undergoing a fundamental transformation. Driven by aging assets, increasing seismic risks, and the urgent demand for sustainable construction methodologies, engineers and investors are turning toward advanced material sciences to redefine structural integrity. At the forefront of this technological shift is the Shape Memory Alloys (SMA) sector. As we move further into 2026, the convergence of material innovation and structural engineering necessity presents a compelling investment thesis.
PW Consulting has released our comprehensive Worldwide Shape Memory Alloys for Civil Engineering Market research to provide stakeholders with the granular intelligence required to navigate this evolving terrain. This article serves as a strategic preview of the findings, highlighting the macro-economic trajectory, competitive dynamics, and technological catalysts that will define the market through 2032.
The Macro-Economic Trajectory: Growth Amidst Complexity
The expansion of the SMA civil engineering market is not merely incremental; it represents a structural recalibration of how infrastructure is built and maintained. Our analysis tracks revenue developments from 2020 through the forecast period ending in 2032. The historical data indicates a steady climb in market valuation, reflecting early adoption phases transitioning into broader commercial viability. Starting from a baseline in the mid-2020s, the market has demonstrated resilience despite global supply chain volatility.
Looking forward, the growth curve is projected to accelerate. The overall market size trajectory suggests a significant uplift in capital allocation toward SMA-integrated projects over the next decade. This growth is underpinned by a compound annual growth rate (CAGR) that signals robust demand penetration across multiple civil engineering verticals. For decision-makers, this implies that timing is critical. Entering the market or expanding existing portfolios now allows organizations to capture share during the steep ascent of the adoption curve. The revenue figures forecast for the late 2020s and early 2030s indicate a mature market phase where early movers will likely consolidate their technological lead.
However, growth is not uniform. It is mediated by material costs, regulatory frameworks, and geographical readiness. Understanding the interplay between these macro drivers and the specific revenue streams is essential for accurate budgeting and strategic planning.
Key Drivers Shaping the 2026 Landscape
Several converging factors are catalyzing demand for shape memory technologies in infrastructure. First, the imperative for seismic resilience is paramount. Traditional reinforcement methods are often heavy, labor-intensive, and reactive. SMAs offer superelastic properties that dissipate energy during seismic events, potentially reducing structural damage and lifecycle costs. This capability is shifting SMAs from experimental novelties to viable components in high-risk zones.
Shape Memory Alloys Market
Second, the focus on structural retrofitting and rehabilitation is intensifying. With vast networks of bridges and buildings reaching the end of their design lives, the industry requires solutions that can be deployed with minimal disruption to ongoing operations. SMA-based strengthening methods, particularly those involving iron-based alloys, offer advantages in terms of weight and corrosion resistance compared to traditional steel, facilitating easier installation and long-term durability.
Third, sustainability and efficiency are driving material innovation. The construction industry is under pressure to reduce carbon footprints. SMAs can contribute to lighter structures, reduced material usage, and extended service life. Furthermore, recent developments in digital fabrication and smart infrastructure integration are creating new use cases. For instance, the integration of SMA actuators in building technology for ventilation, shading, and fire protection systems represents an adjacent growth vector that complements core structural applications.
Finally, standardization is reducing market friction. The establishment of ASTM standards, including F2516 for shape memory alloys and related test methods, provides a framework for quality evaluation. This regulatory clarity supports procurement confidence and accelerates adoption among conservative engineering firms and government entities.
Competitive Dynamics and Vendor Landscape
The market structure is characterized by a mix of specialized material manufacturers and diversified engineering solution providers. Our research indicates a consolidated competitive environment where a core group of players holds a significant share of the revenue. The concentration ratio among the top firms highlights the technical barriers to entry and the importance of established supply chains and intellectual property.
Leading entities are not merely suppliers of raw materials; they are evolving into solution partners. Companies with vertically integrated operations, capable of managing the process from melting to component fabrication, are positioned to control quality and cost more effectively. For example, manufacturers specializing in nickel-titanium based alloys leverage high-performance properties for actuator and damping systems. Simultaneously, firms focusing on iron-based shape memory alloys are gaining traction for large-scale civil infrastructure elements due to advantages in mass production using conventional metallurgical equipment. This dual-track development suggests that the market will segment based on specific application requirements, with nickel-titanium dominating high-precision actuation and iron-based variants scaling for heavy structural strengthening.
Regional presence and application specialization further differentiate competitors. Some players have established strong footholds in structural strengthening and repair of concrete and masonry structures, including bridges, buildings, and silos. Others are integrating SMAs into building technology systems, offering full value chains from specification to assembly. Recent real-world applications demonstrate the transition from pilot projects to commercial deployment. Demonstrations of heat-activated strengthening methods for aging bridge decks and the use of memory-alloy steel in digitally fabricated concrete structures highlight the practical viability of these technologies.
Furthermore, collaborative research efforts are expanding the horizon. Upcoming international symposia focused on shape memory alloys in infrastructure are bringing together researchers and practitioners to discuss future directions. These knowledge exchanges are critical for aligning academic innovation with industrial application, ensuring that emerging technologies meet the rigorous demands of civil engineering practice.
For investors and procurement leaders, the key takeaway is that vendor selection must align with project-specific technical requirements. The optimal partner depends on whether the priority is high-performance actuation, cost-effective mass production for large elements, or integrated system solutions. The market offers diverse capabilities, but due diligence regarding supply chain stability and technical support is essential.
Strategic Implications for Stakeholders
The findings of this report have direct implications for various stakeholders in the construction and infrastructure ecosystem.
- Infrastructure Owners and Operators: Understanding the lifecycle cost benefits of SMA integration is crucial. While initial material costs may be higher, the potential for reduced maintenance, enhanced seismic performance, and extended service life can yield favorable total cost of ownership outcomes. Strategic planning should consider pilot projects in critical assets where performance gains justify material premiums.
- Engineering Firms: Incorporating SMA technologies into design capabilities can differentiate service offerings. Firms that master the specification, detailing, and construction methods for SMA applications will be well-positioned to lead projects that demand advanced resilience features. Continuous training and knowledge acquisition regarding standards and best practices are recommended.
- Material Suppliers and Manufacturers: The projected growth trajectory supports capacity expansion and R&D investment. However, attention to raw material volatility is necessary. Feedstocks such as nickel and titanium are subject to price fluctuations influenced by mining restrictions and geopolitical factors. Developing robust supply chain strategies and exploring alternative alloy formulations, such as iron-based variants, can mitigate exposure.
- Investors: The market shows promise, but due diligence is required. Focusing on companies with proven application records, vertical integration, and strong IP positions offers a pathway to capturing value. Monitoring the evolution of regional demand and regulatory support can provide leading indicators of market shifts.
The Value of PW Consulting's Deep Dive
While the trends outlined above provide the strategic context, execution requires precision. Market growth rates, competitive positioning, and application-specific revenue streams vary significantly across regions and segments. Generalizations can obscure the specific opportunities and risks relevant to your organization.
PW Consulting's Worldwide Shape Memory Alloys for Civil Engineering Market report offers the depth required to move from strategy to action. The report provides a detailed segmentation analysis, examining the market through lenses such as alloy type, application focus, and geography. It includes granular data on demand drivers, restraints, and opportunities that enable accurate forecasting and scenario planning.
Moreover, the competitive analysis goes beyond company profiles. It evaluates market share dynamics, strategic moves, and the implications of recent developments, such as new strengthening methods and symposia that shape industry consensus. The report also contextualizes regulatory environments, including the impact of standards and material availability, helping stakeholders anticipate compliance costs and supply constraints.
Worldwide Shape Memory Alloys for Civil Engineering Market
Readers interested in leveraging this intelligence for their 2026 decision-making are encouraged to access the full report. The detailed data tables, segmentation splits, and competitive assessments contained within the document provide the granularity necessary to refine market entry strategies, optimize procurement negotiations, and identify high-potential niches. Access to the complete analysis ensures that your strategic initiatives are built on a foundation of verified, up-to-date market intelligence.
Conclusion
The intersection of advanced materials and civil engineering is creating a new paradigm for infrastructure resilience. Shape memory alloys are moving from the laboratory to the construction site, driven by seismic needs, aging infrastructure, and the pursuit of efficiency. The market outlook through 2032 indicates substantial growth, supported by technological maturation and increasing standardization.
As the industry navigates this transition, informed decision-making will be the differentiator between leaders and laggards. PW Consulting remains committed to providing the analytical rigor and strategic insight necessary to thrive in this dynamic environment. The full market study offers the detailed roadmap required to capitalize on the opportunities presented by the evolving shape memory alloys landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Shape Memory Alloys for Civil Engineering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide MLCC Dielectric Materials Market Hits $1.86 Billion in 2025, Growing at 7.05% CAGR Through 2032
By pmarketresearch, 2026-09-16
Navigating the Future of Electronic Performance: The Strategic Imperative of the Global MLCC Dielectric Materials Market
For procurement leaders, R&D directors, and corporate strategists operating in the electronics value chain, the materials that enable miniaturization and reliability are no longer a back-office concern. They are a front-line competitive differentiator. As multilayer ceramic capacitors (MLCCs) continue to anchor everything from 5G infrastructure and electric vehicles to medical implants and aerospace systems, the underlying dielectric materials that dictate capacitance density, stability, and thermal resilience have become the nucleus of supply chain resilience and product differentiation. Our newly released Worldwide MLCC Dielectric Materials Market research delivers a comprehensive, data-backed roadmap for organizations that must align material sourcing, product roadmaps, and capacity investments with the trajectory of a rapidly evolving landscape.
The global market for MLCC dielectric materials has demonstrated remarkable resilience and structural growth over the past half-decade. Valued at approximately 1,856.40 million USD in the base year of 2025, the sector has navigated cyclical demand fluctuations, raw material volatility, and shifting end-market appetites to sustain a robust compound annual growth rate of 7.05 percent through the forecast horizon extending to 2032. This trajectory underscores a fundamental reality: the demand for advanced dielectric formulations is not merely cyclical but structurally embedded in the electrification of transportation, the densification of consumer electronics, and the proliferation of high-frequency communication networks. For decision-makers, understanding where this growth concentrates, which material architectures are gaining share, and how legacy supply chains are adapting is the difference between reacting to market shifts and shaping them.
Why This Research Matters for 2026 Strategic Planning
The 2026 planning cycle arrives at a critical inflection point. Supply chain architects are recalibrating tier-two and tier-three supplier dependencies in the wake of geopolitical realignment and regional manufacturing incentives. Simultaneously, product developers are pushing capacitance targets higher while shrinking form factors to the limits of ceramic processing science. The dielectric material layer sits precisely at the intersection of these pressures.
Our forecast model maps a clear acceleration pathway for the sector, with revenue projections climbing from 1,923.77 million USD in 2026 toward 2,980.98 million USD by 2032. More importantly, the analysis isolates the inflection triggers that will separate transient demand spikes from durable structural shifts. By synthesizing historical pricing behavior, capacity commissioning timelines, and application-driven material specification trends, the report equips strategists with a decision framework that extends well beyond headline growth figures. Whether you are evaluating vertical integration opportunities, assessing supplier qualification pipelines, or modeling the cost implications of next-generation dielectric formulations, this research converts macro trends into actionable intelligence.
Market Architecture: Materials, Classes, and the Forces Shaping Demand
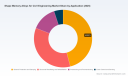
The composition of the MLCC dielectric market reflects decades of materials engineering evolution, yet its present structure is being rewritten by application requirements that demand simultaneously higher performance and lower environmental impact. Barium titanate remains the foundational dielectric compound for both Class I and Class II capacitors, enabling high capacitance density within ultra-thin ceramic layers. However, the market segmentation reveals a nuanced hierarchy of material technologies, each serving distinct performance envelopes and end-use priorities.
- High Purity Barium Titanate continues to dominate as the primary dielectric material, driven by its proven balance of permittivity, manufacturability, and compatibility with high-volume multilayer processing. Japanese suppliers in particular have advanced hydrothermal synthesis routes to deliver grades optimized for precision capacitance stability and ultra-fine grain structures.
- Zirconates and Stannates occupy a strategic niche, offering tailored electrical and mechanical properties that complement barium titanate-based systems in specialized high-reliability and high-voltage applications.
- Rare Earth Doping Oxides represent a more specialized formulation pathway, supporting capacitance tuning and temperature stability for applications where marginal gains in dielectric performance translate into meaningful system-level advantages.
Equally important is the division between dielectric classes, which directly informs material selection and supplier strategy:
- Class II formulations, encompassing X7R, X5R, and Y5V characteristics, command the largest share of material demand due to their prevalence in consumer electronics, automotive electronics, and power management circuits where high volumetric efficiency is paramount.
- Class I materials, including C0G and NP0 types, serve applications demanding exceptional temperature stability, low loss, and long-term reliability, making them indispensable for RF front-ends, precision timing circuits, medical devices, and defense-grade systems.
The market is also defined by notable concentration dynamics. With the top three players commanding 62.45 percent of market share and the top five reaching 78.9 percent, the competitive landscape reflects a mature, technology-intensive ecosystem where formulation expertise, process control, and customer qualification cycles create formidable barriers to entry. For buyers and investors alike, this concentration signals both supply assurance risks and the strategic value of locking in qualified supplier relationships before capacity tightens.
Competitive Landscape: Incumbents, Integrators, and Enabling Material Specialists
The companies profiled in this research illustrate the full spectrum of the dielectric value chain, from powder synthesis and formulated material supply to finished capacitor manufacturing and high-reliability application specialization. Understanding who competes where, and how their material capabilities differentiate their product portfolios, is essential for mapping partnership opportunities and evaluating substitution threats.
Among the leading integrated capacitor manufacturers, Murata Manufacturing Co., Ltd. continues to leverage advanced in-house dielectric material formulations, with recent emphasis on high-capacitance X7R architectures and ultra-miniature dielectric layers that support consumer electronics, automotive, and high-reliability applications. Murata’s July 2025 commencement of mass production for 0402-inch high-capacitance MLCCs at 47 µF, enabled by upgraded dielectric layering technology, exemplifies the pace at which formulation and process innovation are compressing performance boundaries.
Samsung Electro-Mechanics Co., Ltd. maintains a prominent position through proprietary dielectric materials optimized for high capacitance, automotive-grade reliability, and miniaturized components deployed across smartphones, electric vehicles, and 5G infrastructure. TDK Corporation remains a defining force in advanced fine-particle dielectric technologies, with recent moves including the expansion of its CN series to deliver low-resistance soft-termination MLCCs in the 3225 case size, offering 22 nF capacitance and C0G characteristics at 1000 V. TDK’s September 2024 automotive lineup expansion further underscored its focus on industry-leading capacitance at 100 V in 2012 and 3216 sizes, alongside new low-resistance soft termination types built on advanced dielectric formulations.
Yageo Corporation, through its broader portfolio including KEMET and AVX, supplies MLCCs anchored in barium titanate-based dielectrics with emphasis on high-voltage, automotive, and high-reliability segments. Taiyo Yuden Co., Ltd. specializes in high-performance MLCCs with customized dielectric materials spanning automotive, industrial, and consumer electronics use cases. Kyocera Corporation, including its AVX subsidiary, continues to manufacture high-reliability MLCCs using advanced ceramic dielectric formulations targeted at automotive, medical, and aerospace sectors, while Walsin Technology Corporation provides MLCCs incorporating dielectric materials tailored for both general-purpose and specialized electronic applications.
Worldwide MLCC Dielectric Materials Market
On the materials supply side, the competitive dynamics shift toward companies whose core competency lies in dielectric powder engineering and formulation technology. Knowles Precision Devices focuses on high-reliability and high-performance MLCCs with specialized dielectric formulations for medical, military, and 5G markets. Prosperity Dielectrics Co., Ltd. supplies ceramic dielectric powders and formulations across PME and BME series for NP0, X7R, and Y5V applications, directly feeding MLCC production pipelines. Vibrantz Technologies provides engineered dielectric powders and formulated materials for multilayer ceramic components, including both Class I C0G-type and Class 2 X7R-type materials. Sakai Chemical Industry Co., Ltd. has established itself as a key supplier of high-purity barium titanate dielectric powders produced via hydrothermal synthesis for premium MLCC applications, while Nippon Chemical Industrial Co., Ltd., Fuji Titanium Industry Co., Ltd., and Toho Titanium Co., Ltd. round out a robust Japanese supply base producing barium titanate and titanium-based materials critical to electronic dielectric applications.
This interplay between integrated capacitor makers and specialized dielectric material suppliers creates a layered competitive field. For strategists, the implication is clear: material sourcing decisions cannot be made in isolation from the product architecture strategies of the companies that consume them, and vice versa.
Multilayer Ceramic Capacitors (MLCCs) Market
Technology, Regulation, and Supply Chain Dynamics Reshaping the Market
The trajectory of the MLCC dielectric materials market is being shaped not only by performance demands but also by environmental compliance and raw material processing strategies. Manufacturers across the value chain continue to advance lead-free and RoHS-compliant dielectric formulations to meet global environmental standards. This regulatory momentum is not merely a compliance exercise; it is reshaping formulation roadmaps, supplier qualification timelines, and long-term cost structures. Organizations that treat regulatory adaptation as a strategic variable rather than a procedural checkbox will secure advantages in time-to-market and supply continuity.
Raw material dynamics further reinforce the need for strategic foresight. Barium titanate remains the workhorse dielectric for both Class I and Class II capacitors, and the availability of high-purity grades produced through controlled synthesis routes directly influences capacitance consistency, mechanical integrity, and yield performance. Suppliers that have invested in advanced powder processing and particle size control are positioning themselves to serve the most demanding applications, while downstream manufacturers increasingly prioritize qualification partnerships that guarantee batch-to-batch reproducibility. As electrification, connectivity, and miniaturization drive demand toward tighter tolerances, the quality of the dielectric material input becomes a direct determinant of end-product performance and warranty risk.
What the Research Delivers: An Operational Blueprint for Decision-Makers
This report is designed to move beyond descriptive market summaries and into the operational detail that strategic teams require. It integrates historical analysis from 2020 through 2025 with a forward-looking forecast spanning 2026 to 2032, enabling readers to benchmark current positioning against projected growth corridors and identify where capacity, formulation, and qualification investments will yield the greatest returns.
Within the analysis, readers will find:
- A structured assessment of material type segmentation, clarifying how barium titanate-based systems, zirconates and stannates, and rare earth doping oxides each contribute to revenue composition and where application pull is accelerating adoption.
- A detailed evaluation of dielectric class dynamics between Class II and Class I materials, including the performance-driven demand patterns that influence formulation priorities and supplier selection.
- A competitive profiling framework covering leading integrated manufacturers and specialized dielectric material suppliers, with attention to geographic footprints, technological positioning, and recent product and capacity developments.
- Contextual analysis of industry dynamics, including raw material sourcing considerations, formulation trends, and regulatory drivers that influence cost structures and supply chain design.
- Forecast scenarios and market sizing that translate top-line growth into interpretable guidance for capacity planning, sourcing strategy, and investment prioritization.
Crucially, the full report provides the granular segmentation detail, regional revenue distributions, and application-level breakdowns that executive summaries cannot accommodate. These deeper layers enable teams to model localized supply-demand balance, evaluate supplier concentration risk within specific material categories, and align product roadmap milestones with realistic material availability timelines.
Strategic Takeaways for 2026 and Beyond
The Worldwide MLCC Dielectric Materials Market research is built for leaders who need to convert complex material science trends into executable strategy. It frames the market not as a static size estimate but as a dynamic system in which formulation capability, regulatory adaptation, regional manufacturing footprints, and application-driven performance requirements continuously reshape competitive advantage.
In practical terms, the insights contained in this study support several priority actions for 2026 planning:
- Evaluate supplier qualification pipelines against material class requirements, distinguishing between high-volume Class II needs and stability-critical Class I demands.
- Assess the strategic implications of market concentration, particularly where top-tier suppliers hold disproportionate influence over qualified material supply and lead times.
- Integrate environmental compliance and lead-free formulation roadmaps into sourcing decisions, recognizing that regulatory momentum will affect cost, availability, and qualification cycles.
- Align internal R&D and procurement roadmaps with the material technologies most likely to support next-generation capacitance density, miniaturization, and high-reliability performance targets.
The full intelligence behind these recommendations, including the segment-level data, regional breakdowns, and detailed company assessments that enable precise planning, is available in the complete report. For organizations ready to move from general market awareness to targeted, evidence-based decision-making, the complete Worldwide MLCC Dielectric Materials Market research provides the depth required to act with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide MLCC Dielectric Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Wood Briquettes Hit $925.4M in 2025, Projected to Surge to $1,520M by 2032
By pmarketresearch, 2026-09-16
Global Wood Briquettes Market: Strategic Intelligence for 2026 Investment and Operational Planning
Executive Overview of Market Trajectory
The Worldwide Wood Briquettes Market represents a critical intersection of renewable energy policy, industrial decarbonization, and residential heating demand. As organizations navigate the complex energy transition landscape, understanding the quantitative and qualitative dimensions of this sector is paramount for strategic positioning. This market research study provides a comprehensive analysis of market size, growth trajectories, and competitive forces shaping the industry through the forecast period ending in 2032.
Having attained a valuation of approximately 925 million USD in the base year of 2025, the market has demonstrated consistent resilience. Historical data from 2020 through 2025 illustrates a steady accumulation of value, reflecting both organic growth and increased adoption rates across diverse geographical zones. Looking forward, the market is projected to reach 997.6 million USD in 2026, marking a significant step in its expansion curve. This growth is not merely linear but compounds over time, driven by entrenched policy frameworks and shifting consumer preferences toward sustainable biomass solutions. The compound annual growth rate is estimated at 7.35 percent during the forecast period, indicating a robust opportunity for stakeholders who can align their operations with emerging demand patterns.
To fully capitalize on this momentum, decision-makers require more than aggregate figures. They need granular intelligence on segment performance, regional divergences, and the specific regulatory headwinds or tailwinds that will define profitability in the coming years. This report is designed to bridge that gap, offering an evidence-based roadmap for navigating the wood briquettes value chain.
Core Segmentation and Structural Dynamics
Product Type and Material Inputs
The market structure is defined by distinct product categories that cater to varying combustion requirements and feedstock availability. Analysis within this study differentiates between sawdust-based formulations, agro-waste derivatives, and wood residue or chip-based briquettes. Each type possesses unique characteristics regarding energy density, ash content, and production economics. Sawdust briquettes often dominate in terms of volume due to their prevalence in processing streams, while agro-waste variants present opportunities in regions where agricultural biomass is abundant. Wood residue and chips briquettes serve specialized industrial applications where specific burning characteristics are required.
Understanding the cost implications of raw material sourcing is critical. For instance, sawmill residues and wood chips for briquette production have shown price volatility in key markets, with averages in the EU reaching specific levels during late 2023. These input costs directly affect margin structures and pricing strategies. The report delves into how manufacturers mitigate these fluctuations through supply chain optimization and long-term contracting, ensuring that production remains viable even when feedstock prices fluctuate.
Application Segments and Demand Centers
Demand is distributed across several key application verticals, each with distinct growth drivers. Industrial boilers represent a significant portion of consumption, driven by large-scale manufacturing entities seeking cost-effective and compliant heating solutions. Residential heating remains a cornerstone of the market, fueled by consumer desire for carbon-neutral heating options and the aesthetic value of wood-burning stoves. Power generation applications are gaining traction as utilities seek to diversify energy portfolios with biomass feedstocks. Commercial and other applications round out the demand landscape, encompassing hospitality, education, and municipal heating projects.
The interaction between these application segments and regional policies creates a complex web of opportunity. In some jurisdictions, subsidies for biomass boilers significantly enhance residential adoption rates, while in others, industrial regulations mandate specific emission savings that favor high-quality briquettes over raw wood. This study dissects these application-led demand vectors to identify where volume growth is most concentrated and where margin profiles are most favorable.
Regional Market Architecture
Geographically, the market exhibits pronounced differences in maturity, demand volume, and growth speed. Europe currently holds a substantial share of the global market, supported by stringent carbon reduction targets and established biomass infrastructure. Asia Pacific follows as a significant region, characterized by rapid industrialization and increasing awareness of renewable energy alternatives. North America maintains a steady presence, driven by residential heating trends and industrial usage. Latin America and the Middle East and Africa represent emerging territories where market penetration is still developing but holds latent potential.
Regional analysis in this report goes beyond simple revenue allocation. It examines the regulatory environments, logistical constraints, and competitive intensities specific to each zone. For example, the European landscape is heavily influenced by directives such as RED III, which requires solid biomass to meet minimum greenhouse gas emission savings compared to fossil fuels. Such regulations shape not only demand but also the types of products that can be legally sold and subsidized. Similarly, the UK Boiler Upgrade Scheme provides financial incentives for biomass boiler installations, directly stimulating downstream demand in that region. Understanding these regional nuances is essential for any firm planning cross-border expansion or supply chain adjustments.
Competitive Landscape and Strategic Positioning
Key Enterprise Profiles and Operational Focus
The competitive arena is populated by a mix of established manufacturers and specialized producers, each carving out niches based on product quality, geographic reach, and operational scale. Prominent players include Lignetics International, headquartered in Louisville, Colorado, which manufactures premium wood briquettes and compressed logs for residential heating, BBQ, and commercial fireplaces. Their focus on consumer-facing quality highlights one end of the market spectrum.
In Europe, Binderholz GmbH, based in Sankt Johann in Tirol, Austria, produces high-quality wood briquettes from sawmill residues for sustainable heating solutions. Their operations are closely tied to regional milling capacity and EU demand trends. Pfeifer Group, located in Imst, Austria, offers RUF-type wood briquettes as part of its broader range of renewable wood energy products for industrial and residential use, demonstrating the integration of briquette production within larger timber and energy portfolios.
German manufacturers also play a pivotal role. Holzindustrie Torgau GmbH & Co. KG, based in Torgau, specializes in manufacturing pressed wood briquettes certified under DINplus for efficient biomass heating. Südruss Holz GmbH, situated in Unterkirnach, produces natural wood briquettes without additives for export and domestic heating markets, emphasizing purity and export capability. In North America, Bear Mountain Forest Products, located in Eagle River, Wisconsin, supplies dense hardwood briquettes designed for long-burning residential stoves and fireplaces, catering to the premium residential segment.
On the global export front, Jay Khodiyar Industries, headquartered in Rajkot, Gujarat, India, exports 100 percent wood briquettes and biomass variants to global markets for industrial boilers and heating. This company exemplifies the growing role of Asian producers in supplying international markets, leveraging cost advantages and robust manufacturing capabilities.
Strategic Developments and Market Moves
Recent developments among these key entities reveal the strategic priorities shaping the industry. In June 2024, Binderholz GmbH announced an expansion of wood briquette production capacity at its Austrian facilities to meet rising EU demand. This move underscores the confidence major players have in the growth trajectory of the European market and their willingness to invest in capacity when regulatory and demand signals are positive.
Earlier, in November 2023, Holzindustrie Torgau achieved updated DINplus certification for a new briquette product line. Certifications such as DINplus are critical in the wood briquettes market, as they signal compliance with rigorous standards regarding ash content, fines, and overall combustion performance. DIN 51731, for instance, mandates a maximum of 10 percent ash content and 0.5 percent fines for premium wood briquettes. Achieving and maintaining such certifications is a barrier to entry and a competitive differentiator, allowing firms to command premium pricing, such as the levels observed in Central Europe during the 2024 heating season where ENplus A1 wood briquettes retailed at specific price points per tonne.
The market concentration remains relatively fragmented, with top three players holding approximately 18.45 percent of revenue and the top five holding about 26.32 percent. This fragmentation suggests that while leading brands have strong positions, there is ample room for consolidation, niche specialization, or regional dominance strategies.
Regulatory, Standardization, and Economic Drivers
Policy Frameworks and Emission Requirements
Regulatory environments are among the most powerful drivers in the wood briquettes market. In the European Union, the RED III directive requires solid biomass like wood briquettes to meet greenhouse gas emission savings of at least 70 percent versus fossil fuels. This mandate forces both producers and consumers to ensure that biomass products are sourced and processed in ways that demonstrably reduce carbon footprints. It influences everything from feedstock selection to logistics and end-use verification.
Beyond emission targets, subsidy Schemes play a direct role in stimulating demand. The UK Boiler Upgrade Scheme, for instance, provides up to £7,500 grants for biomass boilers compatible with wood briquettes. Such financial mechanisms lower the capital barrier for end-users, accelerating the transition from fossil-fuel heating to biomass systems. The interplay between subsidies, certification standards, and carbon targets creates a multi-layered incentive structure that the report analyzes in detail to help stakeholders predict policy-driven demand shifts.
Quality Standards and Pricing Dynamics
Product quality is not merely a marketing claim; it is a regulatory and commercial necessity. Standards like DIN 51731 set benchmarks that protect consumers and ensure efficient combustion, reducing maintenance issues and emissions. Market data indicates that premium certified briquettes command specific price premiums in key markets. For example, during the 2024 heating season, ENplus A1 wood briquettes achieved retail prices in a defined range per tonne in Central Europe. These pricing dynamics reflect the value that consumers and industrial buyers place on reliability, consistency, and compliance.
Manufacturers must navigate the tension between production costs, which are sensitive to raw material prices and energy inputs, and the price ceilings imposed by market acceptance and competitive pressure. The report provides a framework for analyzing how shifts in input costs, such as the average European price for sawmill residues and wood chips, translate into margin impacts and pricing strategies across different product types and application segments.
Strategic Value of This Market Research Study
Comprehensive Data Coverage and Forecasting Rigor
This study is constructed to provide actionable intelligence for strategic planning. It covers historical data from 2020 through 2025, offering a robust baseline for trend analysis, and extends forecasts through 2032. The projection period allows organizations to stress-test their strategies against multiple growth scenarios and to align capital expenditure cycles with anticipated market expansion.
The report integrates quantitative forecasts with qualitative assessments of the factors driving those numbers. Rather than presenting isolated figures, the analysis contextualizes market size and growth rates within the broader ecosystem of feedstock availability, regulatory requirements, technological advancements in briquetting, and shifting consumer preferences. This holistic approach ensures that the data is interpretable and applicable to real-world decision-making.
Briquette Market
Segmentation Analysis for Targeted Strategy
One of the core strengths of this research is its detailed segmentation framework. By breaking down the market by region, type, and application, the study enables stakeholders to identify their most relevant growth pockets. A manufacturer focused on premium residential products can assess the health and growth potential of the residential heating segment across key regions. An industrial supplier can evaluate the demand outlook for industrial boilers and power generation applications. This granularity supports targeted marketing, production planning, and distribution strategies.
It is important to note that while this article highlights the breadth and depth of the analysis available, the full report contains the precise quantitative allocations and detailed forecasts for each segment and region. These specifics are essential for building financial models, setting sales targets, and evaluating investment returns with precision. Readers seeking the complete segment-level data, including exact historical and projected revenue breakdowns, are encouraged to access the full report through the source webpage.
Competitive Intelligence and Strategic Benchmarking
Understanding the competitive landscape is vital for positioning. This study profiles key companies, analyzing their strategic moves, product focus, geographic presence, and recent developments. By examining events such as capacity expansions, certification achievements, and export initiatives, the report helps firms benchmark their own strategies against industry leaders. It also sheds light on the nature of competition in a fragmented market, highlighting where consolidation is likely and where niche players can thrive.
The inclusion of recent developments, such as the capacity expansion by Binderholz and the certification update by Holzindustrie Torgau, provides timely insights into the operational priorities of major actors. These case examples, combined with broader competitive metrics, offer a practical view of how firms are responding to market opportunities and regulatory demands. For organizations evaluating partnership opportunities, acquisition targets, or competitive threats, this intelligence is invaluable.
Operational and Investment Decision Support
Ultimately, the purpose of this market research is to reduce uncertainty and improve the quality of strategic decisions. For investors, the report provides the data needed to assess market attractiveness, growth sustainability, and risk factors. For manufacturers and suppliers, it offers insights into demand trends, pricing environments, and competitive pressures that inform production planning, capacity investment, and product development. For policymakers and industry associations, it contributes to a clearer understanding of market dynamics and the impact of regulatory measures.
Worldwide Wood Briquettes Market
The study is designed to be a living reference that supports ongoing strategic dialogue. As the market evolves, with changes in feedstock markets, regulatory updates, and technological innovations, the framework provided by this research helps stakeholders adapt and respond proactively. The forecast period through 2032 offers a long enough horizon to plan for structural shifts while remaining specific enough to guide near-term actions in 2026 and beyond.
Detailed data tables, segment-specific growth rates, regional revenue projections, and comprehensive company profiles are available in the full downloadable report. Accessing these resources will enable your organization to conduct a thorough internal analysis and develop strategies that are precisely calibrated to the opportunities and challenges of the Worldwide Wood Briquettes Market.
For detailed analysis of this topic, please visit the official page: Worldwide Wood Briquettes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Global DC Power Supplies Market to Hit $5.9B by 2032, 6.42% CAGR Through 2032
By pmarketresearch, 2026-09-16
Global DC Power Supply and Electronic Load Markets: Strategic Intelligence for 2026 Corporate Decision-Making
The worldwide DC power supply and electronic power load industry stands at a critical inflection point. Between 2020 and 2032, global market revenue is projected to expand from approximately USD 2,780 million to nearly USD 5,945 million, representing a compound annual growth rate of 6.42 percent across the forecast horizon. This structural upward trajectory is not merely a function of incremental demand recovery; it reflects a fundamental realignment in how enterprises design, validate, and manufacture power electronics across automotive, semiconductor, industrial automation, aerospace, and renewable energy verticals. The Worldwide DC Power Supplies and Electronic Power Loads Market research publication arrives precisely when executive leadership teams require defensible, scenario-ready intelligence to navigate supply chain reconfiguration, component cost volatility, and accelerating technology substitution cycles.
For corporate strategists, procurement directors, product planners, and venture investors, this report functions as a decision architecture rather than a static sizing exercise. It maps historical revenue behavior from 2020 through 2025, establishes a rigorous baseline for 2025, and projects forward through 2032 with transparent methodological scaffolding. By deliberately separating macro trajectory from segment-level granularity, the study equips leadership teams to calibrate capital allocation, capacity expansion, vendor partnerships, and technology roadmaps without prematurely exposing sensitive forecasting assumptions.
Macro Trajectory and the Mechanics of Growth Through 2032
The revenue arc captured in this study demonstrates a pattern of recovery, consolidation, and renewed acceleration. After modest contraction in 2023, the market rebounded decisively, with 2024 and 2025 reflecting strong demand pull across multiple end-user ecosystems. The forecast window extending to 2032 positions cumulative growth above historical baselines, driven by electrification mandates, data infrastructure expansion, advanced manufacturing test requirements, and sustained defense modernization programs. The reported CAGR of 6.42 percent consolidates these dynamics into a disciplined growth framework that balances demand-side momentum with practical constraints on component availability, pricing pressure, and regional manufacturing shifts.
Importantly, the study does not treat growth as a uniform linear progression. Revenue expansion is shaped by divergent adoption curves across programmable versus non-programmable architectures, the expanding role of electronic power loads in automated test and validation environments, and the intensifying interplay between semiconductor content, thermal management requirements, and system-level power density targets. Corporate readers will find value in understanding how these structural forces interact to influence market velocity without relying on superficial headline figures that obscure execution risk.
Report Architecture and Actionable Intelligence for Planning Teams
The publication is structured to support multi-function decision-making. Executive summaries convert complex modeling outputs into strategic narratives suitable for board-level review and capital committee discussions. Detailed market sizing sections establish historical baselines, validate demand drivers, and explain the forward-looking assumptions that underpin the forecast period. Rather than presenting aggregate numbers in isolation, the analysis contextualizes revenue evolution within product architecture shifts, application-specific testing requirements, and end-user procurement behavior across industrial, commercial, and government domains.
Beyond sizing, the report delivers operational intelligence that directly informs product strategy and supply chain planning. Coverage includes technology transition pathways, regional manufacturing dynamics, competitive positioning logic, and the practical implications of component cost escalation on product economics. Procurement and engineering leaders will gain clarity on where sourcing vulnerabilities are likely to concentrate, how test equipment requirements are reshaping load and supply specifications, and which application segments are generating the strongest pull for high-reliability, high-density power solutions. Product managers can use these insights to prioritize feature investments, platform consolidation, and portfolio alignment with emerging validation standards.
The study also addresses ecosystem interdependencies that typical market summaries overlook. Coverage of supplier behavior, testing workflow evolution, and application-specific power quality requirements helps organizations translate market momentum into concrete planning assumptions. For enterprises navigating multi-year development cycles or long-term vendor agreements, this level of contextual depth reduces the probability of strategic misalignment and supports more resilient operating models.
Worldwide DC Power Supplies and Electronic Power Loads Market
Competitive Landscape: Positioning, Specialization, and Strategic Implications
The competitive environment is characterized by a mix of broad-platform manufacturers, technology specialists, and application-focused innovators. Market concentration metrics indicate that leading incumbents hold meaningful share, but the landscape remains sufficiently fragmented and dynamic to reward differentiated positioning. The report evaluates core participants across multiple strategic dimensions, including product breadth, precision and programmability capabilities, thermal and power density engineering, and vertical-specific validation expertise.
DC Electronic Load Market
Firms such as TDK-Lambda, Keysight Technologies, Chroma ATE Inc., XP Power, Mean Well Enterprises, EA Elektro-Automatik, Advanced Energy Industries, Magna-Power Electronics, B&K Precision Corporation, Vicor Corporation, Delta Electronics, Murata Manufacturing, and Acopian Power Supplies each occupy distinct strategic coordinates within the market. Several organizations emphasize high-efficiency, compact architectures leveraging advanced semiconductor materials and topologies. Others differentiate through precision programmable platforms designed for R&D validation, production test, battery simulation, and power supply characterization. A further cohort competes on reliability, rapid fulfillment, broad voltage and current ranges, and cost-effective industrial deployment.
Recent vendor activity underscores how aggressively companies are reshaping their portfolios to capture emerging demand. In early 2026, Magna-Power Electronics introduced new high-voltage 1U DC power supply models reaching up to 3000 Vdc, signaling continued investment in high-voltage test and industrial applications. North Atlantic Industries released a 600W DC/DC supply for SOSA-aligned VPX systems, directly targeting aerospace and defense modernization requirements. P-DUKE launched a 150W high-efficiency industrial AC/DC unit for demanding environments, while Jetronl Instruments introduced next-generation programmable solutions aimed at high-end electronics manufacturing across automotive, new energy, and communications testing. ActionPower expanded its automated test equipment portfolio with PCL-series DC electronic loads, reinforcing the growing integration of load instrumentation into validation workflows.
These developments illustrate a broader pattern: competitors are not merely expanding product counts, they are repositioning around application specificity, test integration, power density, and reliability assurance. For enterprise buyers and investors, the strategic question is no longer which supplier is largest, but which portfolio logic best matches an organization's validation needs, procurement constraints, and long-term technology roadmap.
Supply Chain Pressures, Material Constraints, and Component Cost Dynamics
Market growth does not unfold in a vacuum. External shocks and structural material constraints are reshaping cost assumptions, lead-time expectations, and sourcing strategies across the power electronics value chain. In 2025, export controls on rare earth elements and related magnet technologies expanded, with downstream implications for components used in DC power supplies and electronic loads. Around the same period, U.S. actions under Section 232 highlighted national security concerns tied to processed critical minerals and derivative products, reinforcing the strategic importance of supply diversification and regional sourcing resilience.
Component-level pricing pressures have compounded these sourcing complexities. In the first quarter of 2026, tantalum capacitors and MLCCs experienced price increases in the range of 15 to 30 percent, influenced in part by demand associated with AI server power regulation. Power MOSFET and IGBT producers also raised prices by 10 to 20 percent in early 2026 as copper and silicon input costs escalated, while high-voltage MOSFET lead times lengthened meaningfully. These dynamics create a dual challenge for product planners: managing unit cost inflation while maintaining performance and reliability targets in increasingly density-sensitive applications.
At the same time, technology substitution trends are accelerating. Industry analysis points to sustained momentum behind higher efficiency and higher power density designs in electric vehicles and data center infrastructure, with advanced wide-bandgap devices expected to play a growing role in traction inverters and DC-DC converters. This technological trajectory reinforces demand for power supplies and electronic loads that can validate, simulate, and stress next-generation architectures under realistic operating conditions. For organizations operating in this environment, resilience depends on anticipating cost transmission mechanisms, qualifying alternative component sources, and aligning product specifications with the longer-term direction of semiconductor and magnet supply chains.
Strategic Value for 2026 Decision-Making
The 2026 market environment rewards organizations that combine forward-looking demand intelligence with disciplined supply chain and technology planning. This study is designed to support exactly that posture. For strategic planning teams, it provides a structured basis for evaluating revenue opportunity, prioritizing market entry or expansion, and aligning product roadmaps with verifiable demand signals. For procurement and supply chain leaders, it highlights where material constraints, pricing momentum, and regulatory actions are most likely to affect sourcing strategy and total cost of ownership. For technology and engineering leadership, it clarifies how test, validation, and simulation requirements are evolving as power architectures grow more complex and performance expectations intensify.
The analysis also helps organizations separate cyclical noise from durable structural shifts. Not every price increase or product launch signals long-term opportunity; some reflect temporary supply tightness, regional policy reactions, or short-term customer urgency. By grounding interpretation in macro trajectory, segmentation logic, and competitive behavior patterns, the report enables decision-makers to allocate attention and capital more efficiently, avoiding overreaction to isolated events while remaining responsive to genuine demand transformation.
Why Executive Teams Should Access the Full Study
While this preview outlines the strategic contours of the market and the reasoning behind the forecast, the full Worldwide DC Power Supplies and Electronic Power Loads Market research delivers the deeper intelligence required for precise execution. Complete segmentation coverage, detailed regional and application-level breakdowns, competitive positioning maps, and scenario-ready forecast structures are essential for organizations making investment commitments, vendor selections, capacity decisions, or product launch plans. Aggregate market direction establishes confidence; segment-level evidence enables precision.
For leadership teams preparing for 2026 and beyond, the study offers more than market size and growth rates. It provides a coherent framework for interpreting material constraints, competitive responses, and application-driven demand evolution in a market where performance, reliability, and supply resilience increasingly determine competitive outcomes. Readers seeking the full analytical backbone behind these conclusions are encouraged to access the complete report through the source page, where detailed segmentation, company profiles, and forward forecasts are available for immediate strategic application.
For detailed analysis of this topic, please visit the official page: Worldwide DC Power Supplies and Electronic Power Loads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Smart Zero Gravity Bed Market Size Hits $1.8B in 2025, projected 11.85% CAGR to $3.9B by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Frontier: Inside the Worldwide Smart Zero Gravity Bed Market
The convergence of sleep technology, wellness economics, and clinical care delivery is reshaping how households, healthcare providers, and hospitality operators approach rest and recovery. At the center of this transformation lies the smart zero gravity bed category—a segment where ergonomic positioning, connected firmware, and therapeutic functionality intersect to deliver measurable outcomes in circulation, pressure distribution, and sleep quality. Understanding this landscape requires more than product familiarization; it demands a structured view of adoption velocity, regional intensity, competitive positioning, and the regulatory and reimbursement frameworks that shape purchasing behavior.
PW Consulting's latest Worldwide Smart Zero Gravity Bed Market study has been engineered to serve precisely that need. Designed for executives, product leaders, distribution strategists, and investment teams navigating the 2026–2032 planning horizon, the report translates historical momentum and forward-looking indicators into decision-ready intelligence. Rather than presenting a static snapshot, the analysis maps how value is being created, contested, and captured across a rapidly maturing ecosystem of manufacturers, retailers, care facilities, and end users.
Why 2026 Is a Decisive Baseline for Strategic Planning
Market dynamics entering 2026 reflect a phase of consolidation and acceleration. After a period of adoption driven by pilot programs, premium consumer experimentation, and targeted healthcare procurement, the category is transitioning into a more structured growth trajectory. Reported market revenue expanded from 1,452.4 million USD in 2023 to 1,623.78 million USD in 2024, and reached 1,815.39 million USD in 2025. The trajectory continues upward, with 2026 positioned at 2,030.51 million USD and a projected climb toward 3,975.76 million USD by 2032.
Worldwide Infrared Massage Therapy Bed Market
This expansion is supported by a forecast CAGR of 11.85 percent across the 2026–2032 period, a rate that signals durable demand rather than short-cycle enthusiasm. For leadership teams, that trajectory has direct consequences. It informs capacity planning, guides channel investment, shapes partnership prioritization, and clarifies where incremental innovation can yield disproportionate returns. The report uses this macroeconomic arc as the structural backbone for deeper examinations of segment behavior, competitive intensity, and regional demand patterns, ensuring that every tactical recommendation is anchored in measurable momentum.
What the Research Delivers: Operational Depth Over Surface-Level Summaries
A market study earns its place in the executive workflow when it answers not only what is happening, but how to act on it. This publication is organized to support cross-functional decision-making, combining quantitative foundations with qualitative context that explains the forces behind the numbers. The analysis is built around several practical dimensions:
- Macro market sizing and growth mapping across the 2020–2025 historical window and the 2026–2032 forecast period, with a consistent USD million framework that supports scenario modeling and investment prioritization.
- Category and application perspectives that distinguish how demand differs across product configurations and end-use environments, helping teams align product portfolios, messaging, and channel strategy with the most relevant buying drivers.
- Regional demand intensity that reveals where adoption is most concentrated and where latent opportunity remains, enabling smarter prioritization of sales coverage, logistics footprint, and localized product adaptation.
- Competitive profiling of leading manufacturers and technology suppliers, examining positioning, product architecture, commercial reach, and recent strategic moves that signal where the market is heading.
- Regulatory and reimbursement context that clarifies how coverage policy, medical necessity criteria, and procurement rules influence accessibility, pricing tolerance, and channel behavior in healthcare-adjacent demand.
Importantly, the report does not stop at description. It is structured to help teams pressure-test assumptions: which product sizes command the strongest uptake, which applications are expanding fastest, where regional saturation is emerging, and how major players are differentiating through firmware, positioning presets, and integration features. That combination of breadth and specificity is what allows the study to support both strategic visioning and near-term execution.
Competitive Landscape: Differentiation as the New Battleground
The smart zero gravity bed market is shaped by a diverse set of participants, each bringing a distinct route to market and a different emphasis in product design. The leader group reflects a blend of specialized home-care manufacturers, adjustable-base technology suppliers, consumer sleep brands, and regional medical equipment producers. Their collective activity defines the pace of innovation and the standards buyers increasingly expect.
SonderCare, based in London, Ontario, Canada, has built its positioning around premium home hospital beds with therapeutic positioning capabilities, including zero gravity, Trendelenburg, comfort chair, and boost positions. Its focus on long-term care and recovery environments highlights the importance of clinical-grade functionality within residential and transitional care settings. Ergomotion, headquartered in Santa Barbara, California, operates as a global supplier of adjustable bases for smart beds, manufacturing high-volume bases with zero-gravity presets and broad mattress integration. Its continued scale and retail partnerships make it a central force in normalizing zero-gravity presets across mainstream channels. Leggett & Platt, through its adjustable beds division in the United States, stands as a major manufacturer of adjustable bed bases featuring zero-gravity presets, massage functions, wall-hugger design, and programmable positions for both consumer and medical applications, reinforcing the multi-use identity of the category.
Tempur-Pedic contributes a premium smart-sleep angle with TEMPUR-Ergo Smart Bases that combine zero-gravity positioning with automatic snore response, lumbar support, massage, and Sleeptracker-AI integration. This approach underscores how connected features and automated response systems are becoming part of the value narrative in higher-tier offerings. On the medical-equipment side, Hebei Chibang Medical Equipment Co., Ltd., based in Hengshui, Hebei Province, China, manufactures electric hospital beds for elderly and post-operative care with zero-gravity mode, adjustable back, leg, and height settings, and smart functions designed for clinical and home-care use. Zero-G Beds, operating as ZERO-G BEDS LLP and D4 Surgicals in Mumbai, Maharashtra, India, adds a regional manufacturing perspective with electric adjustable homecare and hospital beds that integrate zero-gravity positioning, remote control, and medical-grade features for elderly and home-care applications.
Recent developments reinforce the strategic weight of this cohort. In October 2025, Ergomotion marked its 20th anniversary with the opening of a new design showroom, underscoring continued investment in adjustable base technology and zero-gravity feature leadership. Moves like these matter because they signal where established suppliers are placing bets on future category expectations: refined ergonomics, smarter controls, and broader ecosystem compatibility.
Market structure also deserves attention. The category is not overwhelmingly consolidated, yet a meaningful share of revenue flows through a relatively concentrated set of influential participants. This balance creates both opportunity and risk. New entrants and regional specialists can still carve out positions through cost competitiveness, localized service, or application-specific design, while larger players leverage scale, integration, and brand trust to defend share. The report examines these dynamics in detail, giving teams a clearer view of who controls which value points and where white space may still exist.
Worldwide Smart Zero Gravity Bed Market
Market Dynamics: Policy, Reimbursement, and Use-Case Realities
Growth in this category does not happen in a vacuum. Purchasing decisions are influenced by clinical requirements, coverage pathways, procurement rules, and the practical demands of end users. For healthcare-adjacent demand, reimbursement and regulation can be as important as product performance. Medicare Part B covers hospital beds as durable medical equipment when prescribed for home use and deemed medically necessary, including adjustable models that meet positioning criteria. Coverage follows HCPCS codes such as E0265 and E0266 for total electric beds, which directly affects what buyers can access and how suppliers structure their offering language and documentation.
At the same time, hospital beds must meet medical necessity criteria for coverage, including the inability to achieve required positioning through an ordinary bed. Requirements such as head and foot elevation, height adjustment, and a face-to-face practitioner examination prior to ordering shape demand pipelines and procurement timelines. These safeguards are not obstacles to ignore; they are operational prerequisites that influence product design, sales enablement, and the way manufacturers and distributors support clinicians and patients through the approval process.
Beyond policy, the use-case logic continues to broaden. Adjustable hospital and homecare beds with zero-gravity positioning are increasingly targeted toward elderly users, post-operative patients, and long-term care needs, with the explicit aim of reducing pressure points and improving circulation. That clinical rationale strengthens the case for adoption in residential care, rehabilitation, and aging-in-place contexts, while also informing product features such as ease of remote control, adjustable height, and positioning precision. The report integrates these dynamics into the broader market narrative so that teams can evaluate demand with a realistic understanding of what enables purchase, what slows it, and where service and documentation can become competitive advantages.
Reading the Trajectory: What This Means for 2026 Decision-Makers
For executives planning around the smart zero gravity bed market, the strategic question is no longer whether the category is gaining traction, but how to position for sustained, structurally supported growth. The numbers point to a market that has moved past early experimentation and is now scaling along a defined path. That shift has several practical implications.
First, product strategy should be assessed against real demand distribution rather than assumption. The mix of sizes, applications, and feature sets matters because different buyer groups prioritize different outcomes, from consumer comfort and sleep quality to clinical positioning and caregiver support. Second, regional strategy should be informed by where intensity is highest and where incremental investment can unlock faster returns. Third, competitive positioning should account for the growing importance of integration, automation, and serviceability, since these attributes increasingly differentiate otherwise similar bases and bed systems.
Finally, companies operating in or adjacent to healthcare demand should treat reimbursement and medical necessity requirements as core components of the go-to-market design, not as back-office details. Documentation, coding alignment, and clinician-friendly product language can determine whether a solution reaches the right buyers efficiently. The full study provides the structured detail needed to turn these general principles into region-specific, segment-specific, and competitor-specific action plans.
Begin With the Complete Intelligence Package
This article offers a strategic preview of the market environment and the analytical framework behind PW Consulting's Worldwide Smart Zero Gravity Bed Market study. It is designed to show the depth, structure, and decision orientation of the research while preserving the detailed segmentation data, regional value breakdowns, application-specific revenue figures, and granular competitive metrics for the full report. Those core elements are where the most precise planning insights reside.
For teams preparing for 2026 and beyond, the complete study provides the supporting detail required to align product roadmaps, channel investments, partnership strategies, and market-entry judgments with a rigorously documented view of the category. To access the full market size progression, segmentation analysis, competitive profiles, and policy context in their complete form, visit the official PW Consulting report page and download the full Worldwide Smart Zero Gravity Bed Market research.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Zero Gravity Bed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com