

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Wood Briquettes Hit $925.4M in 2025, Projected to Surge to $1,520M by 2032

Global Wood Briquettes Market: Strategic Intelligence for 2026 Investment and Operational Planning
Executive Overview of Market Trajectory
The Worldwide Wood Briquettes Market represents a critical intersection of renewable energy policy, industrial decarbonization, and residential heating demand. As organizations navigate the complex energy transition landscape, understanding the quantitative and qualitative dimensions of this sector is paramount for strategic positioning. This market research study provides a comprehensive analysis of market size, growth trajectories, and competitive forces shaping the industry through the forecast period ending in 2032.
Having attained a valuation of approximately 925 million USD in the base year of 2025, the market has demonstrated consistent resilience. Historical data from 2020 through 2025 illustrates a steady accumulation of value, reflecting both organic growth and increased adoption rates across diverse geographical zones. Looking forward, the market is projected to reach 997.6 million USD in 2026, marking a significant step in its expansion curve. This growth is not merely linear but compounds over time, driven by entrenched policy frameworks and shifting consumer preferences toward sustainable biomass solutions. The compound annual growth rate is estimated at 7.35 percent during the forecast period, indicating a robust opportunity for stakeholders who can align their operations with emerging demand patterns.
To fully capitalize on this momentum, decision-makers require more than aggregate figures. They need granular intelligence on segment performance, regional divergences, and the specific regulatory headwinds or tailwinds that will define profitability in the coming years. This report is designed to bridge that gap, offering an evidence-based roadmap for navigating the wood briquettes value chain.
Core Segmentation and Structural Dynamics
Product Type and Material Inputs
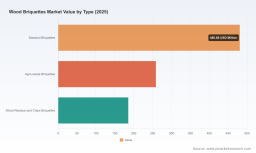
The market structure is defined by distinct product categories that cater to varying combustion requirements and feedstock availability. Analysis within this study differentiates between sawdust-based formulations, agro-waste derivatives, and wood residue or chip-based briquettes. Each type possesses unique characteristics regarding energy density, ash content, and production economics. Sawdust briquettes often dominate in terms of volume due to their prevalence in processing streams, while agro-waste variants present opportunities in regions where agricultural biomass is abundant. Wood residue and chips briquettes serve specialized industrial applications where specific burning characteristics are required.
Understanding the cost implications of raw material sourcing is critical. For instance, sawmill residues and wood chips for briquette production have shown price volatility in key markets, with averages in the EU reaching specific levels during late 2023. These input costs directly affect margin structures and pricing strategies. The report delves into how manufacturers mitigate these fluctuations through supply chain optimization and long-term contracting, ensuring that production remains viable even when feedstock prices fluctuate.
Application Segments and Demand Centers
Demand is distributed across several key application verticals, each with distinct growth drivers. Industrial boilers represent a significant portion of consumption, driven by large-scale manufacturing entities seeking cost-effective and compliant heating solutions. Residential heating remains a cornerstone of the market, fueled by consumer desire for carbon-neutral heating options and the aesthetic value of wood-burning stoves. Power generation applications are gaining traction as utilities seek to diversify energy portfolios with biomass feedstocks. Commercial and other applications round out the demand landscape, encompassing hospitality, education, and municipal heating projects.
The interaction between these application segments and regional policies creates a complex web of opportunity. In some jurisdictions, subsidies for biomass boilers significantly enhance residential adoption rates, while in others, industrial regulations mandate specific emission savings that favor high-quality briquettes over raw wood. This study dissects these application-led demand vectors to identify where volume growth is most concentrated and where margin profiles are most favorable.
Regional Market Architecture
Geographically, the market exhibits pronounced differences in maturity, demand volume, and growth speed. Europe currently holds a substantial share of the global market, supported by stringent carbon reduction targets and established biomass infrastructure. Asia Pacific follows as a significant region, characterized by rapid industrialization and increasing awareness of renewable energy alternatives. North America maintains a steady presence, driven by residential heating trends and industrial usage. Latin America and the Middle East and Africa represent emerging territories where market penetration is still developing but holds latent potential.
Regional analysis in this report goes beyond simple revenue allocation. It examines the regulatory environments, logistical constraints, and competitive intensities specific to each zone. For example, the European landscape is heavily influenced by directives such as RED III, which requires solid biomass to meet minimum greenhouse gas emission savings compared to fossil fuels. Such regulations shape not only demand but also the types of products that can be legally sold and subsidized. Similarly, the UK Boiler Upgrade Scheme provides financial incentives for biomass boiler installations, directly stimulating downstream demand in that region. Understanding these regional nuances is essential for any firm planning cross-border expansion or supply chain adjustments.
Competitive Landscape and Strategic Positioning
Key Enterprise Profiles and Operational Focus
The competitive arena is populated by a mix of established manufacturers and specialized producers, each carving out niches based on product quality, geographic reach, and operational scale. Prominent players include Lignetics International, headquartered in Louisville, Colorado, which manufactures premium wood briquettes and compressed logs for residential heating, BBQ, and commercial fireplaces. Their focus on consumer-facing quality highlights one end of the market spectrum.
In Europe, Binderholz GmbH, based in Sankt Johann in Tirol, Austria, produces high-quality wood briquettes from sawmill residues for sustainable heating solutions. Their operations are closely tied to regional milling capacity and EU demand trends. Pfeifer Group, located in Imst, Austria, offers RUF-type wood briquettes as part of its broader range of renewable wood energy products for industrial and residential use, demonstrating the integration of briquette production within larger timber and energy portfolios.
German manufacturers also play a pivotal role. Holzindustrie Torgau GmbH & Co. KG, based in Torgau, specializes in manufacturing pressed wood briquettes certified under DINplus for efficient biomass heating. Südruss Holz GmbH, situated in Unterkirnach, produces natural wood briquettes without additives for export and domestic heating markets, emphasizing purity and export capability. In North America, Bear Mountain Forest Products, located in Eagle River, Wisconsin, supplies dense hardwood briquettes designed for long-burning residential stoves and fireplaces, catering to the premium residential segment.
On the global export front, Jay Khodiyar Industries, headquartered in Rajkot, Gujarat, India, exports 100 percent wood briquettes and biomass variants to global markets for industrial boilers and heating. This company exemplifies the growing role of Asian producers in supplying international markets, leveraging cost advantages and robust manufacturing capabilities.
Strategic Developments and Market Moves
Recent developments among these key entities reveal the strategic priorities shaping the industry. In June 2024, Binderholz GmbH announced an expansion of wood briquette production capacity at its Austrian facilities to meet rising EU demand. This move underscores the confidence major players have in the growth trajectory of the European market and their willingness to invest in capacity when regulatory and demand signals are positive.
Earlier, in November 2023, Holzindustrie Torgau achieved updated DINplus certification for a new briquette product line. Certifications such as DINplus are critical in the wood briquettes market, as they signal compliance with rigorous standards regarding ash content, fines, and overall combustion performance. DIN 51731, for instance, mandates a maximum of 10 percent ash content and 0.5 percent fines for premium wood briquettes. Achieving and maintaining such certifications is a barrier to entry and a competitive differentiator, allowing firms to command premium pricing, such as the levels observed in Central Europe during the 2024 heating season where ENplus A1 wood briquettes retailed at specific price points per tonne.
The market concentration remains relatively fragmented, with top three players holding approximately 18.45 percent of revenue and the top five holding about 26.32 percent. This fragmentation suggests that while leading brands have strong positions, there is ample room for consolidation, niche specialization, or regional dominance strategies.
Regulatory, Standardization, and Economic Drivers
Policy Frameworks and Emission Requirements
Regulatory environments are among the most powerful drivers in the wood briquettes market. In the European Union, the RED III directive requires solid biomass like wood briquettes to meet greenhouse gas emission savings of at least 70 percent versus fossil fuels. This mandate forces both producers and consumers to ensure that biomass products are sourced and processed in ways that demonstrably reduce carbon footprints. It influences everything from feedstock selection to logistics and end-use verification.
Beyond emission targets, subsidy Schemes play a direct role in stimulating demand. The UK Boiler Upgrade Scheme, for instance, provides up to £7,500 grants for biomass boilers compatible with wood briquettes. Such financial mechanisms lower the capital barrier for end-users, accelerating the transition from fossil-fuel heating to biomass systems. The interplay between subsidies, certification standards, and carbon targets creates a multi-layered incentive structure that the report analyzes in detail to help stakeholders predict policy-driven demand shifts.
Quality Standards and Pricing Dynamics
Product quality is not merely a marketing claim; it is a regulatory and commercial necessity. Standards like DIN 51731 set benchmarks that protect consumers and ensure efficient combustion, reducing maintenance issues and emissions. Market data indicates that premium certified briquettes command specific price premiums in key markets. For example, during the 2024 heating season, ENplus A1 wood briquettes achieved retail prices in a defined range per tonne in Central Europe. These pricing dynamics reflect the value that consumers and industrial buyers place on reliability, consistency, and compliance.
Manufacturers must navigate the tension between production costs, which are sensitive to raw material prices and energy inputs, and the price ceilings imposed by market acceptance and competitive pressure. The report provides a framework for analyzing how shifts in input costs, such as the average European price for sawmill residues and wood chips, translate into margin impacts and pricing strategies across different product types and application segments.
Strategic Value of This Market Research Study
Comprehensive Data Coverage and Forecasting Rigor
This study is constructed to provide actionable intelligence for strategic planning. It covers historical data from 2020 through 2025, offering a robust baseline for trend analysis, and extends forecasts through 2032. The projection period allows organizations to stress-test their strategies against multiple growth scenarios and to align capital expenditure cycles with anticipated market expansion.
The report integrates quantitative forecasts with qualitative assessments of the factors driving those numbers. Rather than presenting isolated figures, the analysis contextualizes market size and growth rates within the broader ecosystem of feedstock availability, regulatory requirements, technological advancements in briquetting, and shifting consumer preferences. This holistic approach ensures that the data is interpretable and applicable to real-world decision-making.
Briquette Market
Segmentation Analysis for Targeted Strategy
One of the core strengths of this research is its detailed segmentation framework. By breaking down the market by region, type, and application, the study enables stakeholders to identify their most relevant growth pockets. A manufacturer focused on premium residential products can assess the health and growth potential of the residential heating segment across key regions. An industrial supplier can evaluate the demand outlook for industrial boilers and power generation applications. This granularity supports targeted marketing, production planning, and distribution strategies.
It is important to note that while this article highlights the breadth and depth of the analysis available, the full report contains the precise quantitative allocations and detailed forecasts for each segment and region. These specifics are essential for building financial models, setting sales targets, and evaluating investment returns with precision. Readers seeking the complete segment-level data, including exact historical and projected revenue breakdowns, are encouraged to access the full report through the source webpage.
Competitive Intelligence and Strategic Benchmarking
Understanding the competitive landscape is vital for positioning. This study profiles key companies, analyzing their strategic moves, product focus, geographic presence, and recent developments. By examining events such as capacity expansions, certification achievements, and export initiatives, the report helps firms benchmark their own strategies against industry leaders. It also sheds light on the nature of competition in a fragmented market, highlighting where consolidation is likely and where niche players can thrive.
The inclusion of recent developments, such as the capacity expansion by Binderholz and the certification update by Holzindustrie Torgau, provides timely insights into the operational priorities of major actors. These case examples, combined with broader competitive metrics, offer a practical view of how firms are responding to market opportunities and regulatory demands. For organizations evaluating partnership opportunities, acquisition targets, or competitive threats, this intelligence is invaluable.
Operational and Investment Decision Support
Ultimately, the purpose of this market research is to reduce uncertainty and improve the quality of strategic decisions. For investors, the report provides the data needed to assess market attractiveness, growth sustainability, and risk factors. For manufacturers and suppliers, it offers insights into demand trends, pricing environments, and competitive pressures that inform production planning, capacity investment, and product development. For policymakers and industry associations, it contributes to a clearer understanding of market dynamics and the impact of regulatory measures.
Worldwide Wood Briquettes Market
The study is designed to be a living reference that supports ongoing strategic dialogue. As the market evolves, with changes in feedstock markets, regulatory updates, and technological innovations, the framework provided by this research helps stakeholders adapt and respond proactively. The forecast period through 2032 offers a long enough horizon to plan for structural shifts while remaining specific enough to guide near-term actions in 2026 and beyond.
Detailed data tables, segment-specific growth rates, regional revenue projections, and comprehensive company profiles are available in the full downloadable report. Accessing these resources will enable your organization to conduct a thorough internal analysis and develop strategies that are precisely calibrated to the opportunities and challenges of the Worldwide Wood Briquettes Market.
For detailed analysis of this topic, please visit the official page: Worldwide Wood Briquettes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com