

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide MLCC Dielectric Materials Market Hits $1.86 Billion in 2025, Growing at 7.05% CAGR Through 2032

Navigating the Future of Electronic Performance: The Strategic Imperative of the Global MLCC Dielectric Materials Market
For procurement leaders, R&D directors, and corporate strategists operating in the electronics value chain, the materials that enable miniaturization and reliability are no longer a back-office concern. They are a front-line competitive differentiator. As multilayer ceramic capacitors (MLCCs) continue to anchor everything from 5G infrastructure and electric vehicles to medical implants and aerospace systems, the underlying dielectric materials that dictate capacitance density, stability, and thermal resilience have become the nucleus of supply chain resilience and product differentiation. Our newly released Worldwide MLCC Dielectric Materials Market research delivers a comprehensive, data-backed roadmap for organizations that must align material sourcing, product roadmaps, and capacity investments with the trajectory of a rapidly evolving landscape.
The global market for MLCC dielectric materials has demonstrated remarkable resilience and structural growth over the past half-decade. Valued at approximately 1,856.40 million USD in the base year of 2025, the sector has navigated cyclical demand fluctuations, raw material volatility, and shifting end-market appetites to sustain a robust compound annual growth rate of 7.05 percent through the forecast horizon extending to 2032. This trajectory underscores a fundamental reality: the demand for advanced dielectric formulations is not merely cyclical but structurally embedded in the electrification of transportation, the densification of consumer electronics, and the proliferation of high-frequency communication networks. For decision-makers, understanding where this growth concentrates, which material architectures are gaining share, and how legacy supply chains are adapting is the difference between reacting to market shifts and shaping them.
Why This Research Matters for 2026 Strategic Planning
The 2026 planning cycle arrives at a critical inflection point. Supply chain architects are recalibrating tier-two and tier-three supplier dependencies in the wake of geopolitical realignment and regional manufacturing incentives. Simultaneously, product developers are pushing capacitance targets higher while shrinking form factors to the limits of ceramic processing science. The dielectric material layer sits precisely at the intersection of these pressures.
Our forecast model maps a clear acceleration pathway for the sector, with revenue projections climbing from 1,923.77 million USD in 2026 toward 2,980.98 million USD by 2032. More importantly, the analysis isolates the inflection triggers that will separate transient demand spikes from durable structural shifts. By synthesizing historical pricing behavior, capacity commissioning timelines, and application-driven material specification trends, the report equips strategists with a decision framework that extends well beyond headline growth figures. Whether you are evaluating vertical integration opportunities, assessing supplier qualification pipelines, or modeling the cost implications of next-generation dielectric formulations, this research converts macro trends into actionable intelligence.
Market Architecture: Materials, Classes, and the Forces Shaping Demand
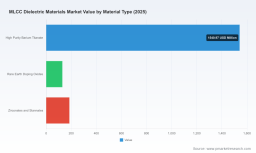
The composition of the MLCC dielectric market reflects decades of materials engineering evolution, yet its present structure is being rewritten by application requirements that demand simultaneously higher performance and lower environmental impact. Barium titanate remains the foundational dielectric compound for both Class I and Class II capacitors, enabling high capacitance density within ultra-thin ceramic layers. However, the market segmentation reveals a nuanced hierarchy of material technologies, each serving distinct performance envelopes and end-use priorities.
- High Purity Barium Titanate continues to dominate as the primary dielectric material, driven by its proven balance of permittivity, manufacturability, and compatibility with high-volume multilayer processing. Japanese suppliers in particular have advanced hydrothermal synthesis routes to deliver grades optimized for precision capacitance stability and ultra-fine grain structures.
- Zirconates and Stannates occupy a strategic niche, offering tailored electrical and mechanical properties that complement barium titanate-based systems in specialized high-reliability and high-voltage applications.
- Rare Earth Doping Oxides represent a more specialized formulation pathway, supporting capacitance tuning and temperature stability for applications where marginal gains in dielectric performance translate into meaningful system-level advantages.
Equally important is the division between dielectric classes, which directly informs material selection and supplier strategy:
- Class II formulations, encompassing X7R, X5R, and Y5V characteristics, command the largest share of material demand due to their prevalence in consumer electronics, automotive electronics, and power management circuits where high volumetric efficiency is paramount.
- Class I materials, including C0G and NP0 types, serve applications demanding exceptional temperature stability, low loss, and long-term reliability, making them indispensable for RF front-ends, precision timing circuits, medical devices, and defense-grade systems.
The market is also defined by notable concentration dynamics. With the top three players commanding 62.45 percent of market share and the top five reaching 78.9 percent, the competitive landscape reflects a mature, technology-intensive ecosystem where formulation expertise, process control, and customer qualification cycles create formidable barriers to entry. For buyers and investors alike, this concentration signals both supply assurance risks and the strategic value of locking in qualified supplier relationships before capacity tightens.
Competitive Landscape: Incumbents, Integrators, and Enabling Material Specialists
The companies profiled in this research illustrate the full spectrum of the dielectric value chain, from powder synthesis and formulated material supply to finished capacitor manufacturing and high-reliability application specialization. Understanding who competes where, and how their material capabilities differentiate their product portfolios, is essential for mapping partnership opportunities and evaluating substitution threats.
Among the leading integrated capacitor manufacturers, Murata Manufacturing Co., Ltd. continues to leverage advanced in-house dielectric material formulations, with recent emphasis on high-capacitance X7R architectures and ultra-miniature dielectric layers that support consumer electronics, automotive, and high-reliability applications. Murata’s July 2025 commencement of mass production for 0402-inch high-capacitance MLCCs at 47 µF, enabled by upgraded dielectric layering technology, exemplifies the pace at which formulation and process innovation are compressing performance boundaries.
Samsung Electro-Mechanics Co., Ltd. maintains a prominent position through proprietary dielectric materials optimized for high capacitance, automotive-grade reliability, and miniaturized components deployed across smartphones, electric vehicles, and 5G infrastructure. TDK Corporation remains a defining force in advanced fine-particle dielectric technologies, with recent moves including the expansion of its CN series to deliver low-resistance soft-termination MLCCs in the 3225 case size, offering 22 nF capacitance and C0G characteristics at 1000 V. TDK’s September 2024 automotive lineup expansion further underscored its focus on industry-leading capacitance at 100 V in 2012 and 3216 sizes, alongside new low-resistance soft termination types built on advanced dielectric formulations.
Yageo Corporation, through its broader portfolio including KEMET and AVX, supplies MLCCs anchored in barium titanate-based dielectrics with emphasis on high-voltage, automotive, and high-reliability segments. Taiyo Yuden Co., Ltd. specializes in high-performance MLCCs with customized dielectric materials spanning automotive, industrial, and consumer electronics use cases. Kyocera Corporation, including its AVX subsidiary, continues to manufacture high-reliability MLCCs using advanced ceramic dielectric formulations targeted at automotive, medical, and aerospace sectors, while Walsin Technology Corporation provides MLCCs incorporating dielectric materials tailored for both general-purpose and specialized electronic applications.
Worldwide MLCC Dielectric Materials Market
On the materials supply side, the competitive dynamics shift toward companies whose core competency lies in dielectric powder engineering and formulation technology. Knowles Precision Devices focuses on high-reliability and high-performance MLCCs with specialized dielectric formulations for medical, military, and 5G markets. Prosperity Dielectrics Co., Ltd. supplies ceramic dielectric powders and formulations across PME and BME series for NP0, X7R, and Y5V applications, directly feeding MLCC production pipelines. Vibrantz Technologies provides engineered dielectric powders and formulated materials for multilayer ceramic components, including both Class I C0G-type and Class 2 X7R-type materials. Sakai Chemical Industry Co., Ltd. has established itself as a key supplier of high-purity barium titanate dielectric powders produced via hydrothermal synthesis for premium MLCC applications, while Nippon Chemical Industrial Co., Ltd., Fuji Titanium Industry Co., Ltd., and Toho Titanium Co., Ltd. round out a robust Japanese supply base producing barium titanate and titanium-based materials critical to electronic dielectric applications.
This interplay between integrated capacitor makers and specialized dielectric material suppliers creates a layered competitive field. For strategists, the implication is clear: material sourcing decisions cannot be made in isolation from the product architecture strategies of the companies that consume them, and vice versa.
Multilayer Ceramic Capacitors (MLCCs) Market
Technology, Regulation, and Supply Chain Dynamics Reshaping the Market
The trajectory of the MLCC dielectric materials market is being shaped not only by performance demands but also by environmental compliance and raw material processing strategies. Manufacturers across the value chain continue to advance lead-free and RoHS-compliant dielectric formulations to meet global environmental standards. This regulatory momentum is not merely a compliance exercise; it is reshaping formulation roadmaps, supplier qualification timelines, and long-term cost structures. Organizations that treat regulatory adaptation as a strategic variable rather than a procedural checkbox will secure advantages in time-to-market and supply continuity.
Raw material dynamics further reinforce the need for strategic foresight. Barium titanate remains the workhorse dielectric for both Class I and Class II capacitors, and the availability of high-purity grades produced through controlled synthesis routes directly influences capacitance consistency, mechanical integrity, and yield performance. Suppliers that have invested in advanced powder processing and particle size control are positioning themselves to serve the most demanding applications, while downstream manufacturers increasingly prioritize qualification partnerships that guarantee batch-to-batch reproducibility. As electrification, connectivity, and miniaturization drive demand toward tighter tolerances, the quality of the dielectric material input becomes a direct determinant of end-product performance and warranty risk.
What the Research Delivers: An Operational Blueprint for Decision-Makers
This report is designed to move beyond descriptive market summaries and into the operational detail that strategic teams require. It integrates historical analysis from 2020 through 2025 with a forward-looking forecast spanning 2026 to 2032, enabling readers to benchmark current positioning against projected growth corridors and identify where capacity, formulation, and qualification investments will yield the greatest returns.
Within the analysis, readers will find:
- A structured assessment of material type segmentation, clarifying how barium titanate-based systems, zirconates and stannates, and rare earth doping oxides each contribute to revenue composition and where application pull is accelerating adoption.
- A detailed evaluation of dielectric class dynamics between Class II and Class I materials, including the performance-driven demand patterns that influence formulation priorities and supplier selection.
- A competitive profiling framework covering leading integrated manufacturers and specialized dielectric material suppliers, with attention to geographic footprints, technological positioning, and recent product and capacity developments.
- Contextual analysis of industry dynamics, including raw material sourcing considerations, formulation trends, and regulatory drivers that influence cost structures and supply chain design.
- Forecast scenarios and market sizing that translate top-line growth into interpretable guidance for capacity planning, sourcing strategy, and investment prioritization.
Crucially, the full report provides the granular segmentation detail, regional revenue distributions, and application-level breakdowns that executive summaries cannot accommodate. These deeper layers enable teams to model localized supply-demand balance, evaluate supplier concentration risk within specific material categories, and align product roadmap milestones with realistic material availability timelines.
Strategic Takeaways for 2026 and Beyond
The Worldwide MLCC Dielectric Materials Market research is built for leaders who need to convert complex material science trends into executable strategy. It frames the market not as a static size estimate but as a dynamic system in which formulation capability, regulatory adaptation, regional manufacturing footprints, and application-driven performance requirements continuously reshape competitive advantage.
In practical terms, the insights contained in this study support several priority actions for 2026 planning:
- Evaluate supplier qualification pipelines against material class requirements, distinguishing between high-volume Class II needs and stability-critical Class I demands.
- Assess the strategic implications of market concentration, particularly where top-tier suppliers hold disproportionate influence over qualified material supply and lead times.
- Integrate environmental compliance and lead-free formulation roadmaps into sourcing decisions, recognizing that regulatory momentum will affect cost, availability, and qualification cycles.
- Align internal R&D and procurement roadmaps with the material technologies most likely to support next-generation capacitance density, miniaturization, and high-reliability performance targets.
The full intelligence behind these recommendations, including the segment-level data, regional breakdowns, and detailed company assessments that enable precise planning, is available in the complete report. For organizations ready to move from general market awareness to targeted, evidence-based decision-making, the complete Worldwide MLCC Dielectric Materials Market research provides the depth required to act with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide MLCC Dielectric Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com