

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Die Cutting Market Hits $6.55 Billion in 2025, Forecasted to Reach $9.12 Billion by 2032

Strategic Intelligence for a Transforming Market: Introducing the Worldwide Die Cutting Service Market Research
The global die cutting service industry stands at a critical inflection point. With the market projected to reach approximately $9.12 billion by 2032 and a compound annual growth rate of 4.85 percent across the forecast horizon, the sector is no longer defined solely by mechanical precision or steady manufacturing demand. It is being reshaped by material cost volatility, sustainability mandates, accelerated technology adoption, and an increasingly fragmented competitive landscape. For executives navigating procurement strategy, capacity planning, or market entry decisions in 2026, superficial summaries are no longer sufficient. This article previews the strategic architecture of our latest Worldwide Die Cutting Service Market research and outlines why this intelligence is essential for decisive, future-ready corporate action.
A Data-Backed View of Market Momentum: 2020 Through 2032
Our analysis tracks a clear upward trajectory across the historical and forecast periods. From 2020 through 2025, the market expanded from roughly $5.12 billion to $6.55 billion, reflecting resilience despite macroeconomic pressures, supply chain realignment, and raw material price fluctuations. The forecast period from 2026 to 2032 extends that momentum, with revenue climbing through 2028 before a notable acceleration drives the market toward its 2032 endpoint. The overall trajectory underscores a structurally growing demand environment rather than a cyclical spike, but growth is not uniform. It is being pulled forward by specific process innovations, regional production shifts, and end-use industries that demand tighter tolerances, faster turnaround, and increasingly sustainable material formats.
Worldwide Die Cutting Service Market
For corporate strategists, this pattern matters because it reveals where investment and differentiation are likely to compound. The forecast period does not simply show higher aggregate revenue; it highlights a market in which operational capability, technological readiness, and regulatory compliance will increasingly separate winners from commoditized service providers. Decision-makers who understand the underlying drivers early can align capacity, vendor selection, and product-development roadmaps accordingly, rather than reacting after cost structures or customer expectations have already shifted.
Why This Research Is Designed for 2026 Decision-Makers
The Worldwide Die Cutting Service Market research is built around actionable clarity, not abstract market description. It is structured to support board-level planning, operations leadership, procurement strategy, and competitive positioning. The report integrates market sizing, segmentation, competitive profiling, and recent industry developments into a single decision-oriented framework. Readers will find a detailed mapping of process types, end-use applications, and regional demand patterns, alongside practical insights on how technology adoption and regulatory change are altering cost dynamics and service expectations.
Beyond descriptive market structure, the study examines the strategic implications of recent capital investments, equipment launches, and corporate transactions that are reshaping service capabilities. It also contextualizes raw material pricing trends and policy developments that directly affect conversion economics and compliance planning. The goal is to give executives a defensible basis for evaluating supplier partnerships, assessing technology upgrade priorities, and anticipating where service requirements will tighten over the next several years. Rather than delivering a static snapshot, the research is designed to support scenario planning in an environment where pricing, capacity, and sustainability expectations are all moving at once.
Segmentation and Demand Drivers: Where Value Is Concentrating
The market is shaped by three structural dimensions: process type, end-use industry, and regional demand. Each dimension carries distinct implications for service providers and buyers.
Process Landscape and Capability Shifts
Die cutting services are delivered through multiple conversion methods, each with different throughput characteristics, precision profiles, and capital requirements. Rotary die cutting remains a dominant pathway for high-volume production, particularly where speed, repeatability, and integrated printing or converting capabilities are essential. Flatbed die cutting continues to serve applications that demand flexibility, precision geometry, and lower setup friction for shorter runs or more complex layouts. Laser die cutting adds a further dimension by enabling intricate cuts and reducing tooling dependency in specialized use cases. Alongside these established approaches, additional process variants support niche requirements and hybrid converting workflows.
From a strategic standpoint, the relevant question is not which process is largest in isolation, but where demand is migrating as customers balance volume efficiency against customization, waste reduction, and compliance-driven material changes. The report evaluates how service providers are positioning themselves across these process categories and where equipment investment is likely to widen competitive gaps.
End-Use Industries as Demand Anchors
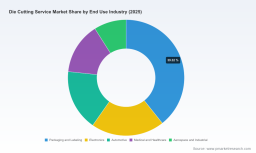
Demand for die cutting services is distributed across a diversified set of end-use industries, each with different performance requirements and procurement cycles. Packaging and labeling continues to be a central demand driver, reflecting the ongoing need for precise blanks, inserts, protective structures, and labeled components across consumer goods, e-commerce, and industrial supply chains. Electronics represents another significant demand pool, where tight tolerances, clean processing, and specialized material handling are increasingly important. Automotive applications add further volume and complexity, particularly as component specification and lightweighting requirements tighten. Medical and healthcare demand introduces strict quality, traceability, and material-compatibility expectations. Aerospace and industrial applications complete the picture with specialized performance thresholds and lower-volume but higher-value part requirements.
Importantly, these end-use segments do not grow in lockstep. Their relative influence on market expansion depends on production localization, regulatory pressure on materials, and the pace of product innovation. The research dissects how each vertical shapes service expectations and where suppliers can capture differentiation through process control, material expertise, or integrated converting capabilities.
Regional Demand and the Geography of Service Delivery
Regional demand patterns reflect broader manufacturing footprints, packaging consumption habits, and local regulatory environments. North America and Europe remain major demand centers with mature service ecosystems, while Asia Pacific stands out for its scale and ongoing production-network expansion. Latin America and the Middle East and Africa contribute additional regional demand, though from smaller bases, and are influenced by import dynamics, localized manufacturing strategies, and evolving logistics patterns.
Because regional markets differ in cost structures, supplier density, and compliance obligations, a single global strategy rarely fits all operating contexts. The report maps these regional differences in a way that helps organizations assess where to consolidate sourcing, where to diversify supply, and where regional capability gaps may create strategic risk or opportunity.
Competitive Landscape and Strategic Positioning
The competitive environment in die cutting services is characterized by a wide mix of specialized converters, packaging-focused service providers, and broader industrial material suppliers. Market concentration remains relatively modest at the top tier, with the top three firms holding a combined share in the low double digits and the top five firms still occupying a limited portion of total market revenue. This fragmentation suggests that scale alone is not the only route to advantage. Service quality, material versatility, process flexibility, and customer-specific engineering capability continue to matter deeply, especially in applications where precision, turnaround speed, and compliance are decisive.
Several U.S.-based specialists illustrate the depth of capability across the market. Colvin-Friedman Company has built a long-standing reputation for precision custom die cutting across more than twelve industries, emphasizing material versatility and decades of converting experience. Mills Industries focuses on precision die cutting for custom plastic corrugated packaging, including inserts, dividers, dunnage, bins, and protective solutions. LMI Packaging concentrates on precision die-cutting for lids and labels in packaging applications, with an emphasis on quality and strict specification requirements. Janco, Inc. delivers custom die cutting services for foam, plastic, and related materials across packaging, industrial, and medical sectors using rotary, flatbed, and steel rule methods. MCL Industries Inc. operates as a leading provider of rotary and flatbed die cutting services for plastics, foams, and related materials, offering turnkey converting for high-volume packaging production. Best Cutting Die supplies custom dies and die cutting solutions designed specifically for packaging processes, aiming to minimize downtime and support efficient production. The Strouse Corporation, American Industrial Company, and Gardico Inc each bring additional depth in custom parts, precision components, and long-standing service orientation across packaging and industrial applications.
At the same time, larger international players are shaping the broader market through scale, capital investment, and sustainability-focused innovation. DS Smith has moved aggressively into advanced rotary die-cutting capacity, including recent investment in high-precision corrugated board conversion. Mondi emphasizes die-cut carton and board solutions tied to sustainable packaging applications, while Smurfit Westrock continues to compete as a leading provider of die-cut boxes and cartons in corrugated and folding carton markets. Equipment and converting-technology suppliers also influence service capabilities indirectly by setting performance standards and enabling faster, more precise production. BOBST supports converting services and supplies advanced flatbed and rotary die-cutting equipment for folding carton and corrugated board packaging. MM Packaging specializes in die-cutting and creasing processes for cartonboard packaging to produce precise blanks for efficient forming.
The strategic takeaway is that competitive advantage in this market is increasingly multidimensional. Providers are competing not only on price, but on process reliability, material breadth, sustainability alignment, and the ability to integrate die cutting into broader converting and packaging workflows.
Recent Developments Reshaping Market Dynamics
Recent corporate and technology developments underscore how quickly the operational baseline is changing. In March 2026, DS Smith invested DKK 100 million to install an advanced rotary die-cutting line with flexographic printing at its Grenaa facility in Denmark, increasing corrugated board capacity by up to 15 million square meters annually while improving precision on complex die cuts and reducing waste. This kind of investment signals the market's direction: higher throughput, better precision, and stronger emphasis on material efficiency.
In May 2025, Winkler+Dünnebier completed the acquisition of Sysco Machinery Corporation, adding advanced rotary die-cutting, slitting, and rewinding technologies for converting and packaging applications. The transaction illustrates how equipment and converting capability are being consolidated to strengthen integrated service offerings. In March 2025, BOBST launched the MASTERCUT 106 PER flatbed die-cutter at drupa 2025, showcasing 8,000 sheets per hour speed, quick-change capabilities, and a digital performance platform for folding carton and packaging production. Product launches like this expand the practical ceiling for conversion speed and flexibility, raising expectations for service providers who rely on or partner with equipment suppliers.
These developments matter because they affect more than individual companies. They shift customer expectations around lead times, precision, waste reduction, and integrated capability. They also influence the cost and risk profile of maintaining competitive service quality, especially for organizations that must meet increasingly demanding specifications without sacrificing throughput.
Raw Material Pressure and Regulatory Disruption
Market dynamics are not driven only by equipment and competition. Cost volatility and regulatory change are reshaping the operating environment at the same time. Recent pricing data shows continued pressure in corrugated and solid fiber box manufacturing inputs. The U.S. Producer Price Index for corrugated and solid fiber box manufacturing, specifically corrugated paperboard in sheets and rolls, reached 390.002 in March 2026. At the same time, corrugated paper prices in Northeast Asia were reported at 0.41 USD per kilogram in March 2026, compared with around 0.30 USD per kilogram in North America. These differences matter for sourcing strategy, margin planning, and regional service economics, especially for organizations exposed to cross-border supply chains or multi-site procurement.
On the regulatory side, packaging and paper product responsibility is advancing rapidly in the United States. Seven states, including California, Colorado, Maryland, Maine, Minnesota, Oregon, and Washington, have enacted Extended Producer Responsibility laws for packaging and paper products, with ongoing implementation through 2026. In early 2026, Wisconsin and New Hampshire introduced EPR bills covering packaging, paper products, and beverage containers. Minnesota's packaging EPR framework requires producers to participate through a producer responsibility organization, with a needs assessment due by December 2026.
For die cutting service buyers and providers, these policies are not background noise. They influence material selection, waste-reduction priorities, reporting obligations, and the relative attractiveness of sustainable packaging formats. In practical terms, they can alter demand patterns for certain substrates, affect the cost of compliance, and reward service partners that can support material reduction, recyclability, or responsible sourcing claims with credible operational execution.
What the Full Report Delivers
The Worldwide Die Cutting Service Market research is designed to turn these forces into usable strategy. It combines market sizing and forecast context with segmentation analysis across process types, end-use industries, and regions. It profiles the competitive landscape and recent developments that are actively reshaping service capabilities. It also embeds the cost and regulatory environment into the analysis so that executives can evaluate not only where the market is heading, but what it will take to compete effectively within it.
Personal Electronic Die Cutting Market
Because this is a fast-moving market, the report is intended to support concrete decisions: how to structure supplier relationships, where to invest in process flexibility, how to anticipate compliance-driven material shifts, and how to position offerings in a fragmented but increasingly capability-sensitive market. The full dataset, segmentation detail, company profiles, and forward-looking scenario framing are available in the complete study.
Next Steps for Strategic Readers
If your organization is evaluating market entry, supplier consolidation, capacity expansion, or packaging and converting strategy for the 2026 to 2032 period, this research is built to inform those choices with rigor and commercial relevance. The executive summary and full market framework provide the level of detail required to move from general awareness to actionable intelligence. Readers seeking a complete view of segmentation splits, competitive positioning, regional dynamics, and the latest market developments are encouraged to access the full report through the source page, where the underlying data, profiles, and scenario context are presented in full.
For detailed analysis of this topic, please visit the official page: Worldwide Die Cutting Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com