

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Smart Zero Gravity Bed Market Size Hits $1.8B in 2025, projected 11.85% CAGR to $3.9B by 2032

Strategic Intelligence for the Next Frontier: Inside the Worldwide Smart Zero Gravity Bed Market
The convergence of sleep technology, wellness economics, and clinical care delivery is reshaping how households, healthcare providers, and hospitality operators approach rest and recovery. At the center of this transformation lies the smart zero gravity bed category—a segment where ergonomic positioning, connected firmware, and therapeutic functionality intersect to deliver measurable outcomes in circulation, pressure distribution, and sleep quality. Understanding this landscape requires more than product familiarization; it demands a structured view of adoption velocity, regional intensity, competitive positioning, and the regulatory and reimbursement frameworks that shape purchasing behavior.
PW Consulting's latest Worldwide Smart Zero Gravity Bed Market study has been engineered to serve precisely that need. Designed for executives, product leaders, distribution strategists, and investment teams navigating the 2026–2032 planning horizon, the report translates historical momentum and forward-looking indicators into decision-ready intelligence. Rather than presenting a static snapshot, the analysis maps how value is being created, contested, and captured across a rapidly maturing ecosystem of manufacturers, retailers, care facilities, and end users.
Why 2026 Is a Decisive Baseline for Strategic Planning
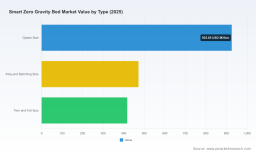
Market dynamics entering 2026 reflect a phase of consolidation and acceleration. After a period of adoption driven by pilot programs, premium consumer experimentation, and targeted healthcare procurement, the category is transitioning into a more structured growth trajectory. Reported market revenue expanded from 1,452.4 million USD in 2023 to 1,623.78 million USD in 2024, and reached 1,815.39 million USD in 2025. The trajectory continues upward, with 2026 positioned at 2,030.51 million USD and a projected climb toward 3,975.76 million USD by 2032.
Worldwide Infrared Massage Therapy Bed Market
This expansion is supported by a forecast CAGR of 11.85 percent across the 2026–2032 period, a rate that signals durable demand rather than short-cycle enthusiasm. For leadership teams, that trajectory has direct consequences. It informs capacity planning, guides channel investment, shapes partnership prioritization, and clarifies where incremental innovation can yield disproportionate returns. The report uses this macroeconomic arc as the structural backbone for deeper examinations of segment behavior, competitive intensity, and regional demand patterns, ensuring that every tactical recommendation is anchored in measurable momentum.
What the Research Delivers: Operational Depth Over Surface-Level Summaries
A market study earns its place in the executive workflow when it answers not only what is happening, but how to act on it. This publication is organized to support cross-functional decision-making, combining quantitative foundations with qualitative context that explains the forces behind the numbers. The analysis is built around several practical dimensions:
- Macro market sizing and growth mapping across the 2020–2025 historical window and the 2026–2032 forecast period, with a consistent USD million framework that supports scenario modeling and investment prioritization.
- Category and application perspectives that distinguish how demand differs across product configurations and end-use environments, helping teams align product portfolios, messaging, and channel strategy with the most relevant buying drivers.
- Regional demand intensity that reveals where adoption is most concentrated and where latent opportunity remains, enabling smarter prioritization of sales coverage, logistics footprint, and localized product adaptation.
- Competitive profiling of leading manufacturers and technology suppliers, examining positioning, product architecture, commercial reach, and recent strategic moves that signal where the market is heading.
- Regulatory and reimbursement context that clarifies how coverage policy, medical necessity criteria, and procurement rules influence accessibility, pricing tolerance, and channel behavior in healthcare-adjacent demand.
Importantly, the report does not stop at description. It is structured to help teams pressure-test assumptions: which product sizes command the strongest uptake, which applications are expanding fastest, where regional saturation is emerging, and how major players are differentiating through firmware, positioning presets, and integration features. That combination of breadth and specificity is what allows the study to support both strategic visioning and near-term execution.
Competitive Landscape: Differentiation as the New Battleground
The smart zero gravity bed market is shaped by a diverse set of participants, each bringing a distinct route to market and a different emphasis in product design. The leader group reflects a blend of specialized home-care manufacturers, adjustable-base technology suppliers, consumer sleep brands, and regional medical equipment producers. Their collective activity defines the pace of innovation and the standards buyers increasingly expect.
SonderCare, based in London, Ontario, Canada, has built its positioning around premium home hospital beds with therapeutic positioning capabilities, including zero gravity, Trendelenburg, comfort chair, and boost positions. Its focus on long-term care and recovery environments highlights the importance of clinical-grade functionality within residential and transitional care settings. Ergomotion, headquartered in Santa Barbara, California, operates as a global supplier of adjustable bases for smart beds, manufacturing high-volume bases with zero-gravity presets and broad mattress integration. Its continued scale and retail partnerships make it a central force in normalizing zero-gravity presets across mainstream channels. Leggett & Platt, through its adjustable beds division in the United States, stands as a major manufacturer of adjustable bed bases featuring zero-gravity presets, massage functions, wall-hugger design, and programmable positions for both consumer and medical applications, reinforcing the multi-use identity of the category.
Tempur-Pedic contributes a premium smart-sleep angle with TEMPUR-Ergo Smart Bases that combine zero-gravity positioning with automatic snore response, lumbar support, massage, and Sleeptracker-AI integration. This approach underscores how connected features and automated response systems are becoming part of the value narrative in higher-tier offerings. On the medical-equipment side, Hebei Chibang Medical Equipment Co., Ltd., based in Hengshui, Hebei Province, China, manufactures electric hospital beds for elderly and post-operative care with zero-gravity mode, adjustable back, leg, and height settings, and smart functions designed for clinical and home-care use. Zero-G Beds, operating as ZERO-G BEDS LLP and D4 Surgicals in Mumbai, Maharashtra, India, adds a regional manufacturing perspective with electric adjustable homecare and hospital beds that integrate zero-gravity positioning, remote control, and medical-grade features for elderly and home-care applications.
Recent developments reinforce the strategic weight of this cohort. In October 2025, Ergomotion marked its 20th anniversary with the opening of a new design showroom, underscoring continued investment in adjustable base technology and zero-gravity feature leadership. Moves like these matter because they signal where established suppliers are placing bets on future category expectations: refined ergonomics, smarter controls, and broader ecosystem compatibility.
Market structure also deserves attention. The category is not overwhelmingly consolidated, yet a meaningful share of revenue flows through a relatively concentrated set of influential participants. This balance creates both opportunity and risk. New entrants and regional specialists can still carve out positions through cost competitiveness, localized service, or application-specific design, while larger players leverage scale, integration, and brand trust to defend share. The report examines these dynamics in detail, giving teams a clearer view of who controls which value points and where white space may still exist.
Worldwide Smart Zero Gravity Bed Market
Market Dynamics: Policy, Reimbursement, and Use-Case Realities
Growth in this category does not happen in a vacuum. Purchasing decisions are influenced by clinical requirements, coverage pathways, procurement rules, and the practical demands of end users. For healthcare-adjacent demand, reimbursement and regulation can be as important as product performance. Medicare Part B covers hospital beds as durable medical equipment when prescribed for home use and deemed medically necessary, including adjustable models that meet positioning criteria. Coverage follows HCPCS codes such as E0265 and E0266 for total electric beds, which directly affects what buyers can access and how suppliers structure their offering language and documentation.
At the same time, hospital beds must meet medical necessity criteria for coverage, including the inability to achieve required positioning through an ordinary bed. Requirements such as head and foot elevation, height adjustment, and a face-to-face practitioner examination prior to ordering shape demand pipelines and procurement timelines. These safeguards are not obstacles to ignore; they are operational prerequisites that influence product design, sales enablement, and the way manufacturers and distributors support clinicians and patients through the approval process.
Beyond policy, the use-case logic continues to broaden. Adjustable hospital and homecare beds with zero-gravity positioning are increasingly targeted toward elderly users, post-operative patients, and long-term care needs, with the explicit aim of reducing pressure points and improving circulation. That clinical rationale strengthens the case for adoption in residential care, rehabilitation, and aging-in-place contexts, while also informing product features such as ease of remote control, adjustable height, and positioning precision. The report integrates these dynamics into the broader market narrative so that teams can evaluate demand with a realistic understanding of what enables purchase, what slows it, and where service and documentation can become competitive advantages.
Reading the Trajectory: What This Means for 2026 Decision-Makers
For executives planning around the smart zero gravity bed market, the strategic question is no longer whether the category is gaining traction, but how to position for sustained, structurally supported growth. The numbers point to a market that has moved past early experimentation and is now scaling along a defined path. That shift has several practical implications.
First, product strategy should be assessed against real demand distribution rather than assumption. The mix of sizes, applications, and feature sets matters because different buyer groups prioritize different outcomes, from consumer comfort and sleep quality to clinical positioning and caregiver support. Second, regional strategy should be informed by where intensity is highest and where incremental investment can unlock faster returns. Third, competitive positioning should account for the growing importance of integration, automation, and serviceability, since these attributes increasingly differentiate otherwise similar bases and bed systems.
Finally, companies operating in or adjacent to healthcare demand should treat reimbursement and medical necessity requirements as core components of the go-to-market design, not as back-office details. Documentation, coding alignment, and clinician-friendly product language can determine whether a solution reaches the right buyers efficiently. The full study provides the structured detail needed to turn these general principles into region-specific, segment-specific, and competitor-specific action plans.
Begin With the Complete Intelligence Package
This article offers a strategic preview of the market environment and the analytical framework behind PW Consulting's Worldwide Smart Zero Gravity Bed Market study. It is designed to show the depth, structure, and decision orientation of the research while preserving the detailed segmentation data, regional value breakdowns, application-specific revenue figures, and granular competitive metrics for the full report. Those core elements are where the most precise planning insights reside.
For teams preparing for 2026 and beyond, the complete study provides the supporting detail required to align product roadmaps, channel investments, partnership strategies, and market-entry judgments with a rigorously documented view of the category. To access the full market size progression, segmentation analysis, competitive profiles, and policy context in their complete form, visit the official PW Consulting report page and download the full Worldwide Smart Zero Gravity Bed Market research.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Zero Gravity Bed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com