

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Heavy Truck Battery Swap Market Hits $1.25B in 2025, Projects 21% CAGR to 2032

The 2026 Inflection Point: Strategic Intelligence for the Worldwide Heavy Truck Battery Swap Stations Market
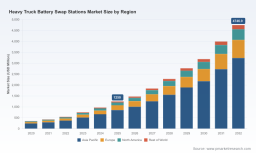
The commercial transportation sector stands at a definitive crossroads. As decarbonization mandates harden and total cost of ownership models shift, battery-electric heavy trucks are transitioning from pilot programs to scaled deployment. Yet the charging bottleneck remains the single greatest barrier to fleet electrification at scale. Battery swap technology has emerged as the structural solution to this challenge, and 2026 marks the year the industry moves from proof-of-concept to commercial reality. Our newly released Worldwide Heavy Truck Battery Swap Stations Market research delivers the granular intelligence executives need to allocate capital, design infrastructure strategies, and secure competitive positioning in a market projected to surge from USD 1,250.0 million in 2025 to USD 4,746.9 million by 2032, reflecting a compound annual growth rate of 21.0 percent across the 2026–2032 forecast window.
This research is engineered not as a passive data repository but as a decision architecture tool. Every section is calibrated to answer the strategic questions that will define boardroom conversations in 2026: Where does capital flow most efficiently? Which operational models will dominate early-adopter corridors? How do regulatory interventions reshape unit economics? And which players are building defensible moats versus those riding temporary policy tailwinds? The following analysis outlines the strategic architecture of this intelligence, demonstrating how it translates market complexity into actionable executive roadmap components.
A Market Trajectory Defined by Acceleration and Structural Rebalancing
The growth curve tells a story of accelerating commercial validation. Revenue expanded from USD 350.0 million in 2020 to USD 427.88 million in 2021, then accelerated through USD 543.2 million in 2022 and USD 750.94 million in 2023 as infrastructure rollouts moved beyond demonstration phases. The trajectory crossed the one-billion threshold at USD 968.97 million in 2024, reached USD 1,250.0 million in 2025, and is projected to climb to USD 1,474.17 million in 2026 before scaling to USD 1,839.2 million in 2027, USD 2,279.85 million in 2028, USD 2,768.68 million in 2029, USD 3,189.24 million in 2030, USD 3,995.27 million in 2031, and ultimately USD 4,746.9 million in 2032. This expansion is not linear; it reflects compounding effects of standardized hardware deployment, fleet-scale procurement cycles, and localized incentive architectures aligning with route-specific utilization patterns.
For executives, the critical insight lies in recognizing that 2026–2028 represents a positioning window where early infrastructure commitments secure operational corridors, while delayed entry forces negotiation from a disadvantaged position as asset utilization rates climb and site availability contracts. The research maps these inflection dynamics across multiple commercial variables, enabling scenario modeling that accounts for deployment pacing, regulatory timeline shifts, and capital expenditure phasing.
Decoding the Commercial Architecture: Segmentation Logic and Deployment Realities
The market does not grow uniformly across geographies or operational configurations. Regional deployment patterns reveal distinct maturity curves, with Asia Pacific commanding the largest revenue share at USD 852.66 million, followed by Europe at USD 218.48 million, North America at USD 128.21 million, and Rest of World at USD 50.65 million. These distributions reflect differences in freight corridor density, policy sequencing, grid integration timelines, and the progression of truck manufacturing ecosystems. The research dissects the underlying drivers behind each regional trajectory, examining how corridor-specific freight volumes, municipal permitting structures, and cross-border trade routes influence station siting economics and utilization forecasts.
Station architecture introduces another strategic dimension. Automated swap stations, representing USD 954.28 million of the segmentation landscape, deliver throughput advantages critical for high-utilization fleet corridors, while semi-automated configurations at USD 295.72 million offer capital flexibility for phased rollouts and lower-density routes. Operation models further diversify strategic considerations: fleet-dedicated stations at USD 699.11 million align with captive logistics networks seeking predictable turnaround cycles, whereas public access stations at USD 550.89 million address multi-operator utilization and emerging commercial ecosystems. Each segment carries distinct capex profiles, utilization thresholds, and margin trajectories, all of which are mapped in detail within the full report to support deployment sequencing decisions.
The competitive structure adds another layer of strategic complexity. Market concentration metrics show a CR3 of 65.2 percent and a CR5 of 78.4 percent, indicating that early-mover positioning and standardized ecosystem control are consolidating rapidly. This concentration underscores the urgency of strategic timing: as leading operators scale standardized networks and secure preferential site access, late entrants face increasing structural friction in building comparable throughput economics.
Operational Economics, Grid Integration, and the Policy Multiplier
Infrastructure deployment cannot be evaluated in isolation from the operational and regulatory environment that shapes unit economics. Station construction requires substantial upfront investment, with costs typically ranging from RMB 15 million to RMB 25 million per site when accounting for civil works, battery procurement, and grid upgrades. Grid integration demands are equally consequential, as stations require minimum 2MVA connection capacity to support simultaneous swap operations involving multiple heavy battery packs. These technical thresholds directly influence site selection logic, permitting timelines, and the economic viability of high-throughput configurations.
Battery economics form the core variable in total cost calculations. Heavy truck swap batteries in the 500–700kWh LFP range trade in bulk at approximately RMB 800 to RMB 1,200 per kWh, making procurement scale, cycle-life management, and second-life utilization pathways critical margin determinants. The research models these cost structures alongside utilization scenarios to identify the throughput thresholds at which station economics transition from marginal to accretive, providing executives with clear deployment pacing benchmarks.
Policy architecture functions as a strategic accelerator. Chinese local governments have structured subsidy frameworks offering up to RMB 10 million per heavy truck battery swap station under new infrastructure initiatives, materially improving early-stage payback profiles. Simultaneously, standardization efforts have gained formal traction. The MIIT group standard T/CAMPEV 115-2023, released in October 2023, specifies battery voltage compatibility up to 1000V and mandates swap completion times under six minutes for heavy trucks. This standard establishes the technical baseline for interoperability and reduces the fragmentation risk that historically plagued early swap ecosystems. The report maps how these regulatory instruments interact with corporate capital deployment cycles, enabling executives to anticipate subsidy utilization windows, compliance timelines, and interoperability requirements across different jurisdictions.
Competitor Positioning: Who Is Building Scale and Who Is Building Standards
The competitive landscape is defined by a concentrated group of infrastructure and vehicle ecosystem players advancing parallel but increasingly intersecting strategies. CATL, headquartered in Ningde, China, operates the Tianfu Battery Swap Network, deploying standardized heavy-duty truck battery swap stations engineered for 5-minute swap cycles on 500kWh+ battery packs. Its November 2023 commissioning of the world's first standardized heavy-duty truck battery swap station in Yibin, Sichuan, supporting Sinotruk vehicles, signals a shift from component supply to integrated infrastructure ownership, positioning the company at the intersection of battery standardization and station-level throughput optimization.
Worldwide Heavy Truck Battery Swap Stations Market
Farizon Auto, based in Hangzhou, China, has advanced its V5 SuperSwap station network to support Geely's electric logistics vehicles through modular battery swapping architectures. The September 2023 launch of its first heavy truck swap station in Hangzhou marked an early operational footprint for a vehicle manufacturer building parallel infrastructure capability, a model that ties station economics directly to captive fleet deployment and reduces interoperability uncertainty in early corridor rollouts.
TGOOD, headquartered in Shenzhen, China, delivers integrated battery swap solutions spanning heavy-duty trucks and logistics applications, with commercial stations already operational across multiple Chinese provinces. Its multi-provincial footprint illustrates the importance of geographic diversification and operational learning curves in refining station throughput, maintenance cycles, and localized grid coordination strategies.
Aulton New Energy, based in Wuxi, China, extends its bus swap technology heritage into heavy truck applications, offering turnkey swap stations featuring automated battery handling systems. Its cross-segment technology transfer highlights a strategic pathway where standardized mechanical handling, control software, and safety protocols developed in higher-volume transit applications are adapted to the heavier payload and higher voltage requirements of commercial truck corridors.
The recent development timeline confirms that 2023 represented an acceleration point. Between September and November 2023, the ecosystem advanced on multiple fronts: a flagship station commissioning, a formal interchangeability standard from the Ministry of Industry and Information Technology, and the launch of a manufacturer-led network node. These milestones collectively illustrate how standardization, hardware deployment, and vehicle ecosystem alignment are converging to reduce the fragmentation risk that previously constrained commercial scalability.
What the 2026–2032 Forecasting Framework Delivers
Executive decision-making under capital allocation pressure requires more than directional market sizing. The research is structured to support scenario-driven planning across multiple decision dimensions. It combines historical performance tracking from 2020 through 2025 with forward-looking forecasting across the 2026–2032 window, enabling readers to test deployment pacing assumptions against revenue trajectories, utilization thresholds, and capitalization timing.
The report examines station type economics in operational context, contrasting the throughput advantages and capex intensity of fully automated configurations against the flexibility and phased deployment logic of semi-automated sites. It evaluates operation model divergence between fleet-dedicated deployments, which prioritize turnaround predictability and captive utilization, and public access models, which pursue multi-operator aggregation and broader corridor coverage. Regional deployment logic is analyzed through the lens of corridor density, policy sequencing, and infrastructure readiness, rather than through static market share tables, ensuring that executives understand the underlying conditions that shape where and when station networks achieve economic viability.
Competitive intelligence goes beyond corporate profiling to map strategic posture, technology positioning, and deployment sequencing. The analysis identifies which players are prioritizing standardized interchangeability, which are aligning station rollout with captive vehicle procurement, and how recent standardization milestones alter the barrier profile for new entrants. This competitive mapping is integrated with market concentration dynamics to clarify the window during which partnership, site acquisition, and standardization adoption decisions carry the highest strategic leverage.
From Intelligence to Execution: Why 2026 Demands Precision Planning
The growth trajectory, regulatory architecture, and competitive consolidation visible in the current market phase create a narrow planning horizon. Capital deployment decisions made in 2026 will determine whether organizations secure high-utilization corridors or enter as followers competing for constrained site availability and secondary freight routes. The research equips executives to navigate this window by translating market scale projections into deployment sequencing logic, regulatory timing into capital phasing strategies, and competitor movement into partnership and positioning options.
For fleet operators, the intelligence clarifies the throughput and utilization thresholds at which swap station access transitions from operational experiment to structural advantage. For infrastructure developers and equipment suppliers, it identifies the site economics, grid integration requirements, and standardization trajectories that shape bankability and scale potential. For investors and strategic advisors, the concentration dynamics and regional deployment sequencing provide a framework for evaluating where value capture is most likely to accrue as the market matures from early infrastructure buildout toward broader corridor integration.
The full report expands every dimension outlined here into a comprehensive strategic architecture. It integrates detailed segmentation analysis, operational cost modeling, regulatory impact mapping, competitive positioning frameworks, and forward-looking scenario structures designed specifically for 2026 capital allocation and infrastructure planning cycles. The macro trajectory, the standardization milestones, the site economics, and the competitor deployment patterns documented within provide the evidence base required to move from market awareness to execution readiness.
Worldwide Substation Battery Market
Access the complete Worldwide Heavy Truck Battery Swap Stations Market research to secure the full segmentation breakdowns, competitor strategy maps, regional deployment logic, and scenario-planning frameworks that transform market intelligence into boardroom-ready strategy. In a market advancing at a 21.0 percent compound growth rate toward a 2032 revenue milestone above USD 4.7 billion, the organizations that move with precision in 2026 will define the infrastructure corridors and standardization standards that shape the next decade of heavy truck electrification.
For detailed analysis of this topic, please visit the official page: Worldwide Heavy Truck Battery Swap Stations Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com