

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Hydrochar Market Hits $285.5M in 2025, Projected 8.5% CAGR to 2032

Strategic Horizons in the Global Hydrochar Market: Navigating the 2032 Outlook
The global transition toward circular carbon economies is no longer a theoretical ambition. It is a measurable industrial shift, and nowhere is this more evident than in the rapidly maturing hydrochar sector. Hydrothermal carbonization has evolved from a niche laboratory process into a commercially viable pathway for converting wet organic residues into stable, energy-dense carbon materials. For executives, investors, and policy strategists operating in 2026, the question is no longer whether hydrochar will scale, but how market participants will position themselves within a rapidly fragmenting and capital-intensive landscape. This analysis draws from PW Consulting's latest worldwide hydrochar market research, offering a strategic preview of the macroeconomic trajectory, competitive architecture, and operational levers that will define the next seven years.
Market Trajectory: From Acceleration to Structural Scaling
The hydrochar market is entering a phase of compounding structural growth rather than cyclical fluctuation. Historical revenue data from 2020 through 2025 demonstrates a consistent upward arc, reflecting the gradual commercialization of hydrothermal carbonization (HTC) and related conversion technologies across municipal waste management, industrial biomass processing, and agricultural valorization networks. From an analytical perspective, the transition into the 2026–2032 forecast window marks a critical inflection point, as scaling effects, regulatory alignment, and feedstock logistics begin to converge.
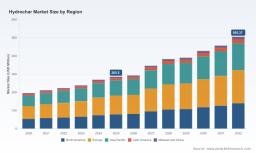
The market size trajectory underscores this momentum. Starting at approximately 195.4 million USD in 2020, revenue climbed steadily to 285.5 million USD by the base year of 2025. This historical run-rate establishes a firm foundation for the forecast period, with projected revenue expanding to 292.49 million USD in 2026 and accelerating toward 345.9 million USD by 2027. The trajectory continues upward through the decade, culminating in a projected market valuation of 505.37 million USD by 2032. When annualized, this pathway translates to a compound annual growth rate of 8.5 percent, a figure that places hydrochar among the more resilient subsegments within the broader bioenergy and carbon management ecosystem. For corporate strategists, an 8.5 percent CAGR is not merely a growth indicator; it is a signal that supply chain investments, technology partnerships, and capacity planning must be calibrated against a compounding demand environment rather than a static market structure.
Regulatory Catalysts and Feedstock Dynamics
Market expansion in the hydrochar space is being reinforced by a convergence of regulatory mandates and structural feedstock advantages. In Europe, the revised Waste Framework Directive (2008/98/EC) has established binding timelines for the separate collection of biowaste, fundamentally altering municipal waste management economics. This policy shift is expected to accelerate the deployment of HTC-based pathways, as municipalities and industrial processors seek compliant, high-value utilization routes for wet organic streams that would otherwise incur high transportation and disposal costs.
The raw material landscape further amplifies this trajectory. IEA Bioenergy Task 40 has identified roughly 200 million metric tons per year of available wet biomass residues across Europe alone, a volume that provides substantial feedstock headroom for hydrothermal conversion. This availability is critical because hydrochar production inherently favors wet biomass, circumventing the energy-intensive drying requirements that constrain conventional pyrolysis operations. From a technical standpoint, hydrothermal processing achieves a carbon yield in the range of 70 to 80 percent from initial biomass, while simultaneously densifying the energy content to approximately 25 MJ/kg, positioning the output as both a soil amendment and a drop-in solid fuel.
Carbon pricing mechanisms are adding commercial momentum. Under current European Union Emissions Trading System guidelines, the co-firing of hydrochar in industrial and power generation settings can qualify for carbon credit recognition, given that the process can reduce CO2 emissions by up to 90 percent relative to conventional coal combustion. This reimbursement dynamic transforms hydrochar from a waste-management solution into a monetizable decarbonization asset, enabling power generators and heavy industry operators to integrate hydrochar into existing combustion infrastructure with measurable compliance benefits. In parallel, macroeconomic planning in Asia is creating import and scaling pathways. China's 14th Five-Year Plan explicitly targets a 20 percent share for biomass energy, establishing a policy environment that supports both domestic development and cross-border procurement of hydrochar products and technology partnerships.
Segmentation and Application Architecture
The revenue architecture of the hydrochar market reflects a diversified application base, with material valorization and energy recovery operating as parallel growth engines. Rather than relying on a single end-use vertical, the market distributes demand across soil and fertilizer applications, solid fuel and energy generation, and activated carbon or adsorbent production. This tripartite composition provides structural resilience, as fluctuations in one application segment can be partially offset by demand in another. Soil amendment and fertilizer utilization remains a foundational demand channel, particularly as agricultural sectors seek organic carbon-based soil conditioners that improve water retention, nutrient availability, and long-term carbon sequestration.
Simultaneously, the solid fuel and energy generation pathway has emerged as the largest demand driver in the current market structure. Hydrochar's compatibility with existing combustion systems, combined with its elevated energy density and low moisture content after processing, enables industrial boilers, co-firing facilities, and dedicated bioenergy plants to substitute a portion of their fossil fuel inputs with a renewable carbon carrier. The activated carbon and adsorbents segment represents a higher-value, performance-driven market, where hydrochar serves as a precursor for filtration media, contaminant capture, and industrial purification applications. This segment's growth is tightly coupled with tightening environmental standards across water treatment, air quality management, and industrial process control.
Feedstock type segmentation further illustrates the market's adaptability. Sewage sludge, agricultural waste, and food waste each contribute meaningful volumes, with the relative attractiveness of each stream varying by regional waste management infrastructure, local regulatory frameworks, and downstream end-use requirements. Sewage sludge conversion benefits from established municipal collection systems and high moisture content that aligns well with hydrothermal processing. Agricultural residues provide a geographically distributed feedstock base with strong seasonal availability, while food waste streams offer concentrated organic content suitable for localized conversion facilities. The optimal feedstock mix is rarely static; it is shaped by logistics costs, subsidy structures, and the proximity of conversion capacity to both waste generation points and end-use markets.
Competitive Landscape: Technology Positioning and Corporate Strategy
The competitive structure of the hydrochar market remains moderately fragmented, with the top three participants collectively capturing approximately 28.5 percent of market revenue and the top five firms extending that share to roughly 35.2 percent. This concentration pattern indicates that while scale advantages are materializing, the market has not yet consolidated around a small number of dominant incumbents. The current competitive environment is instead defined by differentiated technology pathways, geographic specialization, and application-specific product positioning.
Ingelia, headquartered in Barcelona, Spain, has established itself as a reference point for commercial HTC deployment, particularly in the conversion of sewage sludge and biowaste into fertilizer and fuel-grade hydrochar. The company's operational footprint advanced significantly in November 2022, when it initiated operations at a 7,000 ton-per-year hydrochar plant in Italy, demonstrating the feasibility of medium-scale, continuous conversion infrastructure processing municipal sewage streams. This milestone highlights the commercial viability of integrating HTC into existing wastewater and waste-to-resource networks.
TerraNova Energy GmbH, based in Münster, Germany, has pursued an industrial-scale strategy through its HTCycle technology, targeting wet biomass residues for both energy and soil applications. The company reinforced its market trajectory in June 2023 by securing a contract for a HTCycle plant in Germany designed to produce approximately 20,000 tons per year of hydrochar from biowaste. This contract reflects a strategic emphasis on large-capacity facilities that leverage European biowaste collection mandates and industrial decarbonization requirements.
BlackCarbon GmbH, operating from St. Pölten, Austria, has carved out a premium positioning by manufacturing hydrochar from wood waste and agricultural residues, specifically designed as a drop-in coal replacement for industrial boilers. In March 2023, the company expanded its facility to a 10,000 ton-per-year capacity, signaling commitment to scaling a product line that prioritizes combustion compatibility and energy substitution in industrial heat applications.
Arbaflame A/S, headquartered in Aarhus, Denmark, has pursued a standardized pellet product strategy with its Arbacore hydrochar pellets, targeting co-firing applications in power plants as a sustainable coal alternative. This approach aligns with the broader energy transition demand for standardized, transportable biomass-derived fuels that can be integrated into existing power generation logistics without extensive boiler modifications.
Haffner Energy, based in Vitry-le-François, France, focuses on its ERC technology for generating SynChar hydrochar from wet organic waste, targeting energy production and carbon storage applications. The company achieved an important validation milestone in September 2022 with the certification of its ERC pilot plant for 1 ton-per-day SynChar production from agricultural waste, a step that supports its pathway toward commercial scaling and process refinement.
Worldwide Hydrochar Market
Hydrocracker Market
Antaco, operating from Santiago, Chile, illustrates the geographic diversification of the market by producing hydrochar from forestry residues and sewage sludge for soil amendment and biofuel markets across South America. The company's business model reflects the applicability of hydrochar technologies beyond European and North American regulatory contexts, demonstrating that feedstock availability, agricultural soil needs, and bioenergy demand can jointly support commercial deployment in emerging regional markets.
Strategic Decision Points for 2026 Leadership
For corporate leaders and investment decision-makers, the hydrochar market presents a set of interlocking strategic choices. The first is feedstock positioning. Given the diversity of viable input streams and the strong dependence on local logistics, companies must assess whether to align with municipal waste management contracts, agricultural residue supply networks, or industrial organic waste partnerships. Feedstock security is not merely an operational concern; it is a determinant of capacity utilization, revenue predictability, and margin stability.
The second decision point is application-market alignment. Facilities and technologies optimized for solid fuel substitution may require different product specifications, quality controls, and commercial partnerships than those targeting soil amendment or activated carbon production. The market does not reward generic product strategies. Instead, it increasingly favors architectures in which conversion capacity, downstream offtake agreements, and quality certification are integrated around a clearly defined end-use pathway.
The third strategic dimension is geographic and regulatory exposure. European biowaste mandates, carbon credit eligibility under emissions trading frameworks, and Asia's biomass energy targets create differentiated opportunity sets across regions. Market participants need to evaluate where regulatory tailwinds will most rapidly convert into contracted demand, and where infrastructure gaps, feedstock competition, or certification requirements may slow commercialization. The presence of a market concentration level in the high twenties to mid-thirties percent range further suggests that early positioning in underserved regional demand centers or specialized application niches can yield meaningful competitive insulation before later-stage consolidation pressures intensify.
Finally, capital allocation and partnership strategy will play a decisive role. The recent expansion and contracting activity observed among leading firms demonstrates that capacity scaling is being undertaken in phases, often anchored by specific feedstock contracts or downstream offtake arrangements. Market entrants and existing players alike are likely to benefit from structured collaborations that distribute technology risk, align feedstock sourcing with conversion capacity, and secure revenue visibility through multi-year offtake or joint operating models.
Conclusion: Why Comprehensive Market Intelligence Matters in 2026
The worldwide hydrochar market is entering a decade in which growth will be defined less by macroeconomic cyclicity than by regulatory momentum, feedstock logistics, and application-specific commercialization. The macro trajectory points toward sustained expansion, with the market advancing from approximately 285.5 million USD in 2025 to a projected 505.37 million USD by 2032 at a compound annual growth rate of 8.5 percent. Yet macroeconomic direction alone is insufficient for rigorous corporate planning. Effective strategy demands segmentation clarity, regional demand mapping, feedstock cost modeling, technology benchmarking, and competitive intelligence that links corporate developments to broader market shifts.
PW Consulting's Worldwide Hydrochar Market research is designed to provide that operational depth. The study integrates baseline and forecast revenue structures, segmentation analysis across regions, feedstock types, and application channels, and a detailed competitive assessment of the companies actively shaping the commercial landscape. It examines the regulatory, raw material, carbon pricing, and macroeconomic developments that are altering demand formation, while offering practical context for capacity planning, partnership evaluation, and market-entry decisions.
Full segmentation figures, regional revenue distributions, detailed company positioning, and forecast scenarios are available within the complete study. Readers seeking to translate the market's directional momentum into actionable 2026 strategy are encouraged to access the full report for comprehensive data, granular segmentation breakdowns, and the competitive intelligence required to benchmark opportunities against current industry dynamics.
For detailed analysis of this topic, please visit the official page: Worldwide Hydrochar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com