

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Global DC Power Supplies Market to Hit $5.9B by 2032, 6.42% CAGR Through 2032

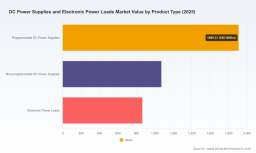
Global DC Power Supply and Electronic Load Markets: Strategic Intelligence for 2026 Corporate Decision-Making
The worldwide DC power supply and electronic power load industry stands at a critical inflection point. Between 2020 and 2032, global market revenue is projected to expand from approximately USD 2,780 million to nearly USD 5,945 million, representing a compound annual growth rate of 6.42 percent across the forecast horizon. This structural upward trajectory is not merely a function of incremental demand recovery; it reflects a fundamental realignment in how enterprises design, validate, and manufacture power electronics across automotive, semiconductor, industrial automation, aerospace, and renewable energy verticals. The Worldwide DC Power Supplies and Electronic Power Loads Market research publication arrives precisely when executive leadership teams require defensible, scenario-ready intelligence to navigate supply chain reconfiguration, component cost volatility, and accelerating technology substitution cycles.
For corporate strategists, procurement directors, product planners, and venture investors, this report functions as a decision architecture rather than a static sizing exercise. It maps historical revenue behavior from 2020 through 2025, establishes a rigorous baseline for 2025, and projects forward through 2032 with transparent methodological scaffolding. By deliberately separating macro trajectory from segment-level granularity, the study equips leadership teams to calibrate capital allocation, capacity expansion, vendor partnerships, and technology roadmaps without prematurely exposing sensitive forecasting assumptions.
Macro Trajectory and the Mechanics of Growth Through 2032
The revenue arc captured in this study demonstrates a pattern of recovery, consolidation, and renewed acceleration. After modest contraction in 2023, the market rebounded decisively, with 2024 and 2025 reflecting strong demand pull across multiple end-user ecosystems. The forecast window extending to 2032 positions cumulative growth above historical baselines, driven by electrification mandates, data infrastructure expansion, advanced manufacturing test requirements, and sustained defense modernization programs. The reported CAGR of 6.42 percent consolidates these dynamics into a disciplined growth framework that balances demand-side momentum with practical constraints on component availability, pricing pressure, and regional manufacturing shifts.
Importantly, the study does not treat growth as a uniform linear progression. Revenue expansion is shaped by divergent adoption curves across programmable versus non-programmable architectures, the expanding role of electronic power loads in automated test and validation environments, and the intensifying interplay between semiconductor content, thermal management requirements, and system-level power density targets. Corporate readers will find value in understanding how these structural forces interact to influence market velocity without relying on superficial headline figures that obscure execution risk.
Report Architecture and Actionable Intelligence for Planning Teams
The publication is structured to support multi-function decision-making. Executive summaries convert complex modeling outputs into strategic narratives suitable for board-level review and capital committee discussions. Detailed market sizing sections establish historical baselines, validate demand drivers, and explain the forward-looking assumptions that underpin the forecast period. Rather than presenting aggregate numbers in isolation, the analysis contextualizes revenue evolution within product architecture shifts, application-specific testing requirements, and end-user procurement behavior across industrial, commercial, and government domains.
Beyond sizing, the report delivers operational intelligence that directly informs product strategy and supply chain planning. Coverage includes technology transition pathways, regional manufacturing dynamics, competitive positioning logic, and the practical implications of component cost escalation on product economics. Procurement and engineering leaders will gain clarity on where sourcing vulnerabilities are likely to concentrate, how test equipment requirements are reshaping load and supply specifications, and which application segments are generating the strongest pull for high-reliability, high-density power solutions. Product managers can use these insights to prioritize feature investments, platform consolidation, and portfolio alignment with emerging validation standards.
The study also addresses ecosystem interdependencies that typical market summaries overlook. Coverage of supplier behavior, testing workflow evolution, and application-specific power quality requirements helps organizations translate market momentum into concrete planning assumptions. For enterprises navigating multi-year development cycles or long-term vendor agreements, this level of contextual depth reduces the probability of strategic misalignment and supports more resilient operating models.
Worldwide DC Power Supplies and Electronic Power Loads Market
Competitive Landscape: Positioning, Specialization, and Strategic Implications
The competitive environment is characterized by a mix of broad-platform manufacturers, technology specialists, and application-focused innovators. Market concentration metrics indicate that leading incumbents hold meaningful share, but the landscape remains sufficiently fragmented and dynamic to reward differentiated positioning. The report evaluates core participants across multiple strategic dimensions, including product breadth, precision and programmability capabilities, thermal and power density engineering, and vertical-specific validation expertise.
DC Electronic Load Market
Firms such as TDK-Lambda, Keysight Technologies, Chroma ATE Inc., XP Power, Mean Well Enterprises, EA Elektro-Automatik, Advanced Energy Industries, Magna-Power Electronics, B&K Precision Corporation, Vicor Corporation, Delta Electronics, Murata Manufacturing, and Acopian Power Supplies each occupy distinct strategic coordinates within the market. Several organizations emphasize high-efficiency, compact architectures leveraging advanced semiconductor materials and topologies. Others differentiate through precision programmable platforms designed for R&D validation, production test, battery simulation, and power supply characterization. A further cohort competes on reliability, rapid fulfillment, broad voltage and current ranges, and cost-effective industrial deployment.
Recent vendor activity underscores how aggressively companies are reshaping their portfolios to capture emerging demand. In early 2026, Magna-Power Electronics introduced new high-voltage 1U DC power supply models reaching up to 3000 Vdc, signaling continued investment in high-voltage test and industrial applications. North Atlantic Industries released a 600W DC/DC supply for SOSA-aligned VPX systems, directly targeting aerospace and defense modernization requirements. P-DUKE launched a 150W high-efficiency industrial AC/DC unit for demanding environments, while Jetronl Instruments introduced next-generation programmable solutions aimed at high-end electronics manufacturing across automotive, new energy, and communications testing. ActionPower expanded its automated test equipment portfolio with PCL-series DC electronic loads, reinforcing the growing integration of load instrumentation into validation workflows.
These developments illustrate a broader pattern: competitors are not merely expanding product counts, they are repositioning around application specificity, test integration, power density, and reliability assurance. For enterprise buyers and investors, the strategic question is no longer which supplier is largest, but which portfolio logic best matches an organization's validation needs, procurement constraints, and long-term technology roadmap.
Supply Chain Pressures, Material Constraints, and Component Cost Dynamics
Market growth does not unfold in a vacuum. External shocks and structural material constraints are reshaping cost assumptions, lead-time expectations, and sourcing strategies across the power electronics value chain. In 2025, export controls on rare earth elements and related magnet technologies expanded, with downstream implications for components used in DC power supplies and electronic loads. Around the same period, U.S. actions under Section 232 highlighted national security concerns tied to processed critical minerals and derivative products, reinforcing the strategic importance of supply diversification and regional sourcing resilience.
Component-level pricing pressures have compounded these sourcing complexities. In the first quarter of 2026, tantalum capacitors and MLCCs experienced price increases in the range of 15 to 30 percent, influenced in part by demand associated with AI server power regulation. Power MOSFET and IGBT producers also raised prices by 10 to 20 percent in early 2026 as copper and silicon input costs escalated, while high-voltage MOSFET lead times lengthened meaningfully. These dynamics create a dual challenge for product planners: managing unit cost inflation while maintaining performance and reliability targets in increasingly density-sensitive applications.
At the same time, technology substitution trends are accelerating. Industry analysis points to sustained momentum behind higher efficiency and higher power density designs in electric vehicles and data center infrastructure, with advanced wide-bandgap devices expected to play a growing role in traction inverters and DC-DC converters. This technological trajectory reinforces demand for power supplies and electronic loads that can validate, simulate, and stress next-generation architectures under realistic operating conditions. For organizations operating in this environment, resilience depends on anticipating cost transmission mechanisms, qualifying alternative component sources, and aligning product specifications with the longer-term direction of semiconductor and magnet supply chains.
Strategic Value for 2026 Decision-Making
The 2026 market environment rewards organizations that combine forward-looking demand intelligence with disciplined supply chain and technology planning. This study is designed to support exactly that posture. For strategic planning teams, it provides a structured basis for evaluating revenue opportunity, prioritizing market entry or expansion, and aligning product roadmaps with verifiable demand signals. For procurement and supply chain leaders, it highlights where material constraints, pricing momentum, and regulatory actions are most likely to affect sourcing strategy and total cost of ownership. For technology and engineering leadership, it clarifies how test, validation, and simulation requirements are evolving as power architectures grow more complex and performance expectations intensify.
The analysis also helps organizations separate cyclical noise from durable structural shifts. Not every price increase or product launch signals long-term opportunity; some reflect temporary supply tightness, regional policy reactions, or short-term customer urgency. By grounding interpretation in macro trajectory, segmentation logic, and competitive behavior patterns, the report enables decision-makers to allocate attention and capital more efficiently, avoiding overreaction to isolated events while remaining responsive to genuine demand transformation.
Why Executive Teams Should Access the Full Study
While this preview outlines the strategic contours of the market and the reasoning behind the forecast, the full Worldwide DC Power Supplies and Electronic Power Loads Market research delivers the deeper intelligence required for precise execution. Complete segmentation coverage, detailed regional and application-level breakdowns, competitive positioning maps, and scenario-ready forecast structures are essential for organizations making investment commitments, vendor selections, capacity decisions, or product launch plans. Aggregate market direction establishes confidence; segment-level evidence enables precision.
For leadership teams preparing for 2026 and beyond, the study offers more than market size and growth rates. It provides a coherent framework for interpreting material constraints, competitive responses, and application-driven demand evolution in a market where performance, reliability, and supply resilience increasingly determine competitive outcomes. Readers seeking the full analytical backbone behind these conclusions are encouraged to access the complete report through the source page, where detailed segmentation, company profiles, and forward forecasts are available for immediate strategic application.
For detailed analysis of this topic, please visit the official page: Worldwide DC Power Supplies and Electronic Power Loads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com